
 Social VR Market | 2026-2036
Social VR Market Size, Share, and Industry Trends Forecast 2026-2036
Social VR Market Analytics
Enterprise training departments are rotating share away from consumer gaming as the primary revenue anchor for Social VR platforms. Meta Platforms Inc. leverages its captive hardware-software ecosystem to control distribution economics across Quest devices. VRChat Inc. specializes in user-generated content tooling that sustains creator-driven network effects. Sony Group Corporation anchors its position through PlayStation VR2 integration with established entertainment franchises.
Social VR denotes immersive three-dimensional environments where multiple users interact through avatars in real time, typically requiring stereoscopic displays with 90-120 Hz refresh rates and six-degrees-of-freedom tracking to minimize motion sickness. Software Platforms currently capture the dominant margin pool as recurring subscription and transaction revenue outpaces hardware unit economics. Multi-User experiences are expanding fastest as synchronous social interaction becomes the core value proposition over solitary content consumption. Cloud-Based deployment leads infrastructure preference by eliminating local compute barriers to headset affordability.
The EU AI Act and GDPR impose algorithmic transparency and biometric data constraints on European platform operators, while the FCC governs wireless spectrum allocation for untethered headsets in the United States. Japan's METI promotes cross-platform avatar interoperability standards that reduce user lock-in across competing ecosystems. Stakeholders must monitor regulatory divergence between privacy-first jurisdictions and innovation-permissive markets when allocating platform development resources.
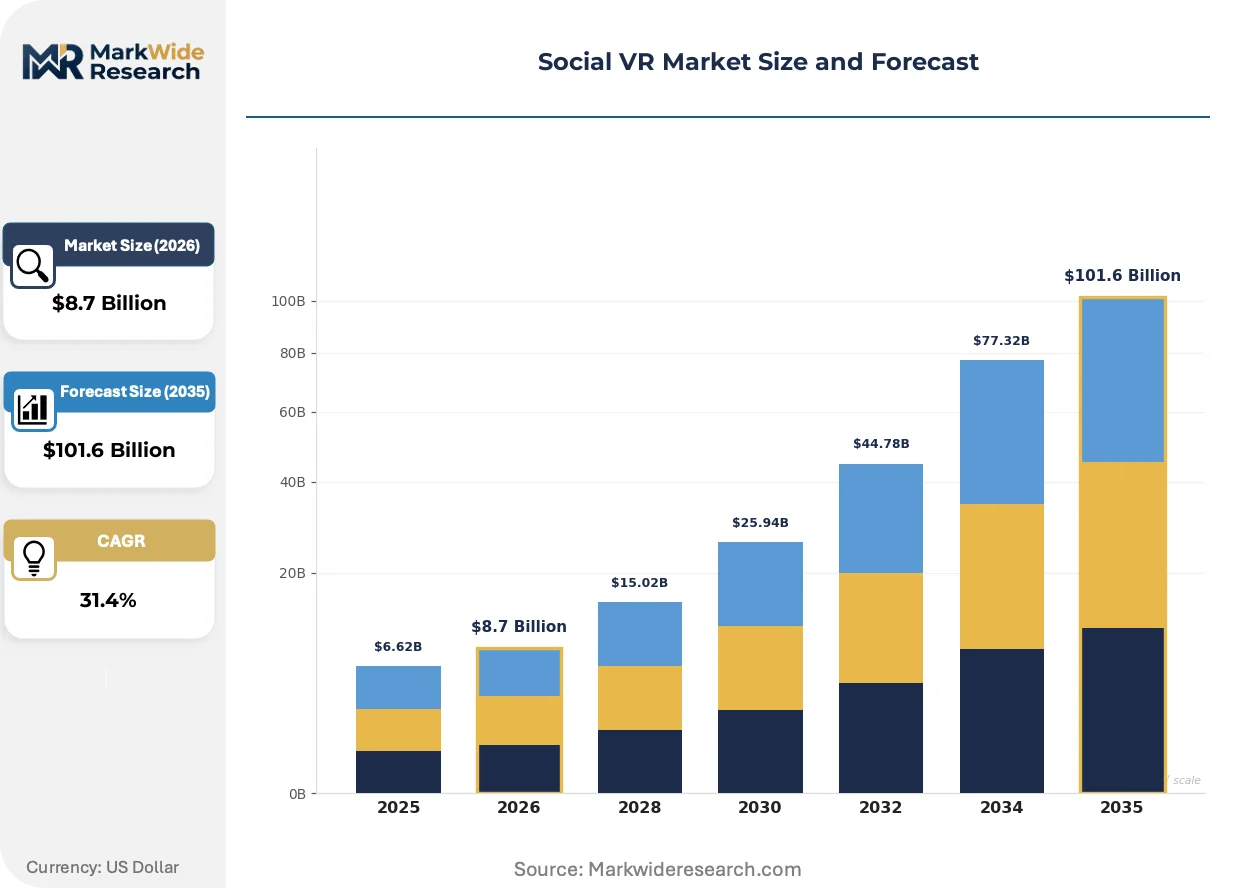
Market Dynamics
Enterprise training departments are rotating procurement budgets away from consumer gaming toward immersive workforce development platforms, compressing hardware refresh cycles and elevating software subscription economics above unit sales.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements in Europe are accelerating investment in explainable avatar behavior systems for enterprise deployments.
- Biometric haptic feedback integration:Full-body tracking suits with galvanic skin response sensors are deepening immersion for therapeutic and training applications.
- West Coast technology cluster concentration:San Francisco Bay Area and Seattle metro density of VR-native talent pools is compressing platform development timelines.
Market Restraints
- Display panel supply concentration:OLED microdisplay fabrication capacity concentrates in South Korea and Taiwan, creating input cost volatility for headset manufacturers.
- Motion sickness latency thresholds:Sub-20 millisecond motion-to-photon latency requirements impose technical limitations on wireless streaming architectures.
- GDPR biometric data friction:European facial geometry and gait pattern storage restrictions increase compliance overhead for persistent avatar systems.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentives for electronics manufacturing are drawing assembly capacity toward Indian subcontinent cost structures.
- Spatial computing-AR convergence:Passthrough mixed reality blending physical and virtual environments is opening enterprise maintenance and design review applications.
- Cloud rendering edge distribution:5G network slicing and MEC node deployment is enabling thin-client headset economics for price-sensitive education sectors.
Industry Challenges
- Real-time engine programming scarcity:Unreal Engine and Unity technical artists with multiplayer networking expertise command premium compensation, constraining platform scaling.
- ISO/IEC 27001 certification timelines:Enterprise security audits for immersive platform data governance extend sales cycles by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social VR Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software Platforms, Accessories, Services User Type: Gamers, Educators, Businesses, Content Creators Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Experience Type: Single-User, Multi-User, Guided Tours, Social Hangouts |
| Companies Covered | Meta Platforms Inc., VRChat Inc., Rec Room Inc., Bigscreen, Inc., Altspace VR, Microsoft Corporation, Sony Group Corporation, HTC Corporation, Unity Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social VR Market Evolving Landscape
Foveated rendering architectures and AI-driven content generation are compressing hardware requirements while expanding addressable user bases beyond enthusiast segments.
Varifocal display stacks with mechanical lens adjustment are displacing fixed-focal-plane VR optics in premium enterprise headsets. Medical training departments at teaching hospitals are adopting these systems at replacement rates exceeding consumer refresh cycles by threefold. The technology is displacing cadaver-based surgical preparation in favor of repeatable virtual anatomy exploration.
The EU AI Act's risk classification framework for biometric identification systems is forcing platform operators to segregate European user data processing from other jurisdictions. Avatar emotion recognition engines now require explicit consent workflows and algorithmic impact assessments. Enterprise training contracts in Germany and France are incorporating these compliance costs into three-year subscription pricing.
Enterprise procurement departments are consolidating vendor relationships around integrated hardware-software-service bundles rather than component sourcing. Systems integrators and value-added resellers are capturing margin previously held by direct platform sales teams. This consolidation is most visible across East Coast financial services hubs where compliance documentation requirements favor single-vendor accountability structures.
Social VR Market Segmentation
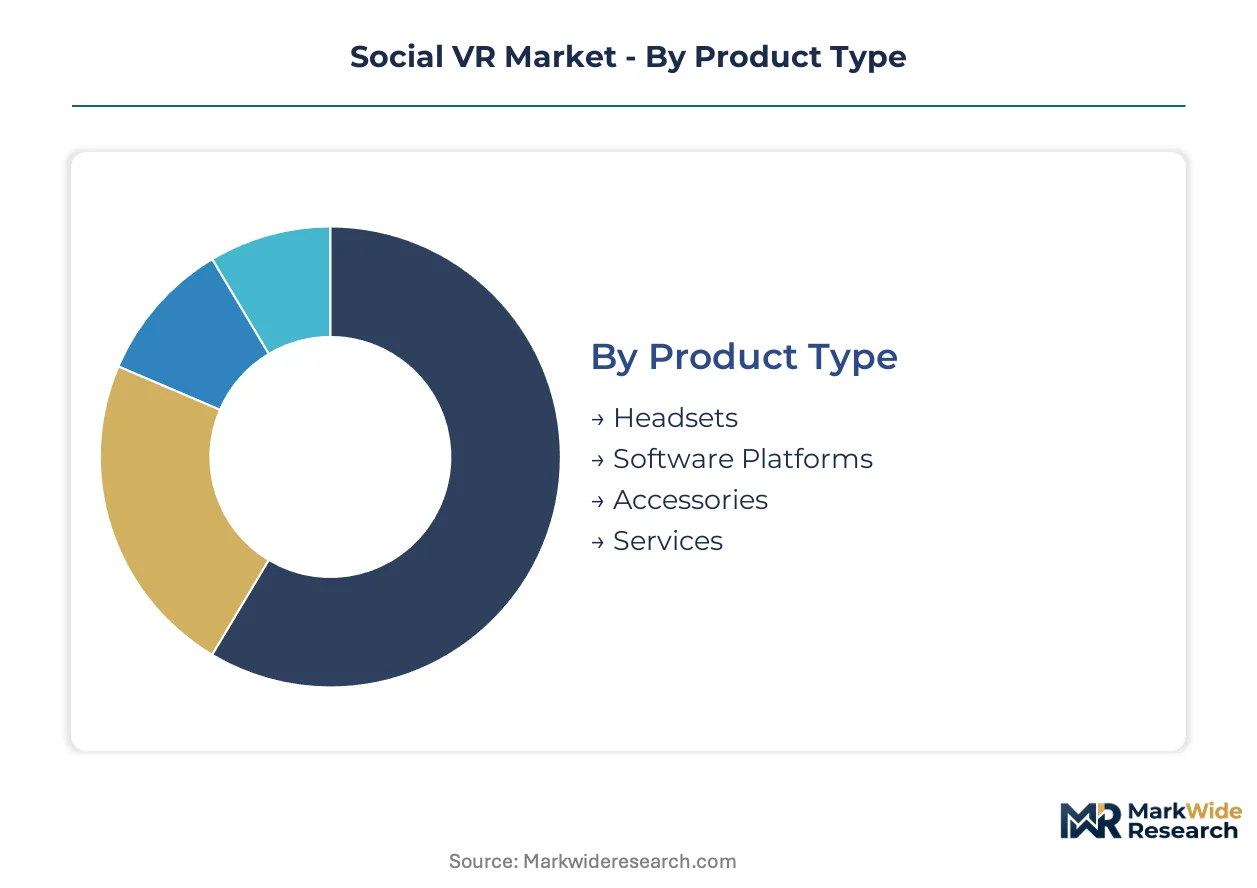
Segmentation in Social VR reveals how hardware commoditization pressures software monetization strategies. Distinct user archetypes impose incompatible latency, privacy, and interoperability requirements that fragment platform development roadmaps.
Product Type:
Headsets face the most acute substitution threat as smartphone-tethered viewers and AR passthrough devices erode dedicated VR hardware economics.
- Headsets:Stereoscopic displays with 90-120 Hz refresh rates and six-degrees-of-freedom tracking define baseline immersion thresholds. Enterprise training departments in United States financial services hubs compress hardware refresh cycles through bulk procurement contracts.
- Software Platforms:Recurring subscription and transaction revenue models dominate margin capture as cloud rendering reduces local compute dependencies. GDPR biometric data restrictions in Europe force algorithmic segregation of avatar emotion recognition engines, elevating compliance engineering costs.
- Accessories:Full-body tracking suits with galvanic skin response sensors deepen therapeutic applications.
- Services:Systems integration and value-added reseller bundles consolidate vendor relationships around single-accountability structures.
Software Platforms retain volume leadership; Headsets hold the steepest expansion curve as enterprise replacement rates exceed consumer refresh cycles.
User Type:
Cost tier stratification separates capital-intensive enterprise deployments from creator-economy tooling investments.
- Gamers:Consumer enthusiast segments drive initial hardware adoption but exhibit price elasticity that constrains premium headset penetration. San Francisco Bay Area and Seattle metro talent density accelerates native VR content pipeline development.
- Businesses:Enterprise training departments rotate procurement budgets toward immersive workforce development platforms. ISO/IEC 27001 certification timelines extend sales cycles by six to twelve months in East Coast financial services procurement.
- Educators:Cloud rendering and 5G network slicing enable thin-client economics for price-sensitive institutional deployments.
- Content Creators:User-generated content tooling sustains network effects through avatar customization and world-building utilities.
Businesses command premium pricing tiers; Content Creators generate the steepest user-base expansion through viral distribution mechanics.
Deployment:
Volume concentration favors cloud architectures that eliminate local GPU requirements and expand addressable headset affordability.
- Cloud-Based:Edge computing nodes and MEC deployment reduce motion-to-photon latency below 20-millisecond thresholds for wireless streaming. India PLI scheme incentives draw assembly capacity toward subcontinent cost structures for supporting infrastructure.
- On-Premises:Air-gapped installations satisfy classified government and defense sector security requirements.
- Hybrid:Split processing architectures balance sensitive data local retention with scalable rendering offload.
- Mobile:Smartphone-dependent viewers sacrifice positional tracking fidelity for accessibility in emerging market price segments.
Cloud-Based deployment captures the dominant volume position; Hybrid architectures climb fastest as regulated industries seek compliance-flexible middle grounds.
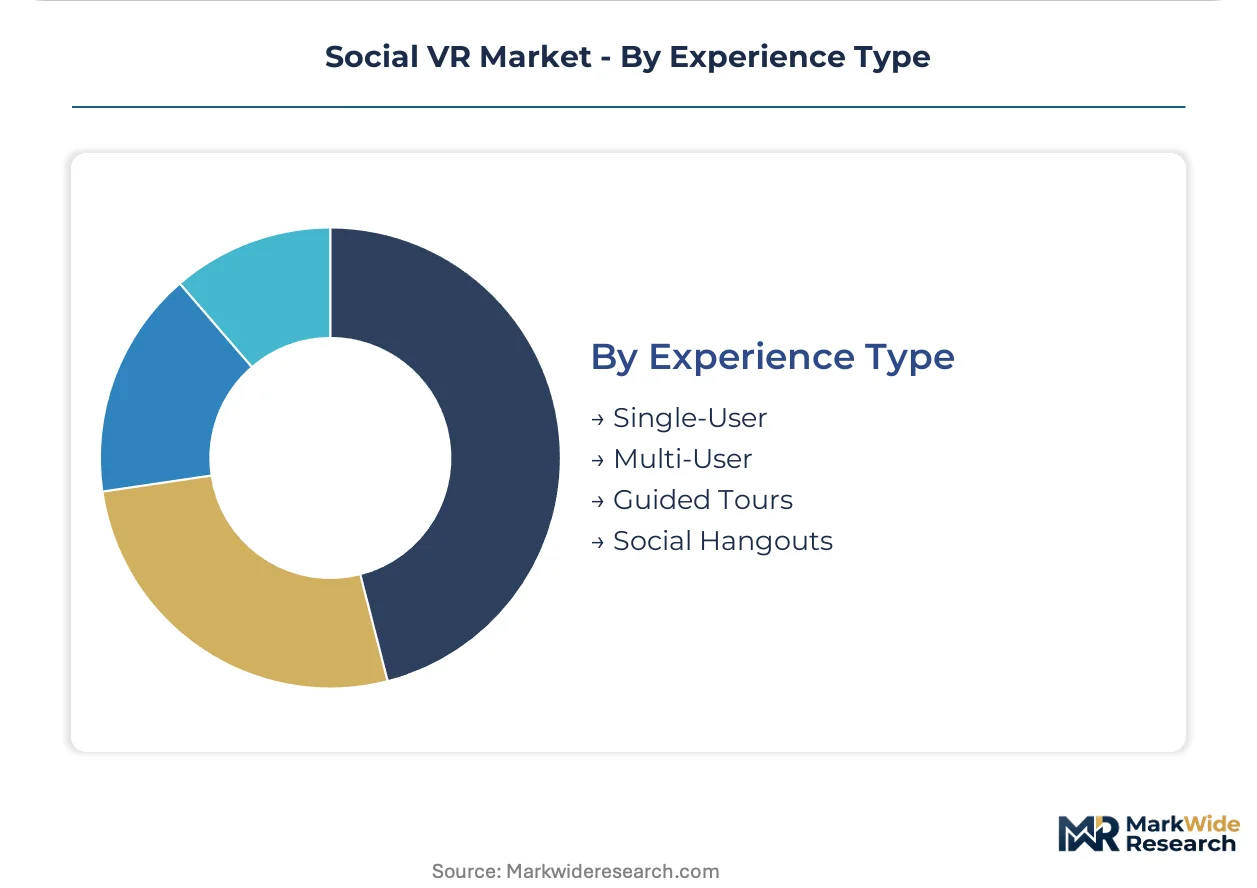
Experience Type:
Application maturity separates established synchronous social formats from experimental guided formats still seeking scalable monetization.
- Multi-User:Synchronous avatar interaction constitutes the core value proposition displacing solitary content consumption. EU AI Act algorithmic transparency mandates accelerate explainable avatar behavior system investment for European enterprise deployments.
- Single-User:Cinematic and productivity applications retain niche positioning against multi-user network effects.
- Social Hangouts:Persistent virtual spaces with user-generated environment hosting sustain creator-driven retention loops.
- Guided Tours:Scripted narrative experiences serve cultural institution and real estate marketing verticals with limited replayability.
Multi-User experiences retain engagement volume leadership; Social Hangouts gain share fastest through creator economy network effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese OLED microdisplay fabs supply panel stacks to United States headset assemblers, while South Korean memory houses ship HBM modules for cloud rendering nodes serving European enterprise training contracts.
United States
West Coast technology clusters in San Francisco Bay Area and Seattle metro compress platform development timelines through VR-native talent density. FCC wireless spectrum allocation governs untethered headset transmission protocols for sub-20 millisecond latency compliance. East Coast financial services hubs in New York and Boston consolidate procurement around single-vendor accountability structures with ISO/IEC 27001 certification requirements.
Germany
Automotive and industrial engineering departments drive enterprise training adoption for virtual assembly and safety protocol simulations. EU AI Act algorithmic transparency mandates force explainable avatar behavior system investments for biometric identification risk classification. Bavarian precision manufacturing clusters around Munich anchor headset component sourcing relationships with Taiwanese display suppliers.
China
Domestic cloud service providers expand edge computing node deployment to reduce motion-to-photon latency for wireless streaming architectures. MIIT standards and dual carbon goals shape data center energy efficiency requirements for rendering infrastructure. Yangtze River Delta manufacturing bases around Shanghai and Suzhou assemble accessories and tracking peripherals for export markets.
Japan
Medical training departments at teaching hospitals adopt varifocal display headsets at replacement rates exceeding consumer refresh cycles. METI promotes cross-platform avatar interoperability standards that reduce user lock-in across competing ecosystems. Kansai region Osaka-Kyoto corridor concentrates haptic feedback R&D for therapeutic application integration.
India
Education ministries pilot thin-client headset deployments leveraging 5G network slicing for price-sensitive institutional access. PLI scheme production-linked incentives draw electronics manufacturing assembly capacity toward subcontinent cost structures. Karnataka and Telangana technology corridors host systems integration partnerships for enterprise workforce development platform localization.
Social VR Market Competitive Landscape
Player mix skews toward integrated hardware-software ecosystems with captive distribution control. Market structure concentrates around three to four platform operators with headset-anchored user bases, while specialist software houses compete on creator tooling differentiation. Dominant strategic archetypes include vertically integrated consumer technology conglomerates, user-generated content platform specialists, and enterprise-focused systems integrators. Competitive moves center on hardware-software bundle consolidation and cloud rendering infrastructure partnerships that reduce local compute barriers.
Within the integrated ecosystem tier, Meta Platforms Inc. and Sony Group Corporation exemplify hardware-anchored platform control strategies. VRChat Inc. occupies a position representing creator-driven network effect specialization. Microsoft Corporation sits within the enterprise systems integration archetype despite its mixed reality hardware exposure. These three named entities collectively illustrate the strategic divergence between consumer volume plays, creator economy retention models, and corporate procurement channel dominance.
| Leading Market Players |
|---|
| Meta Platforms Inc. |
| VRChat Inc. |
| Rec Room Inc. |
| Bigscreen, Inc. |
| Altspace VR |
| Microsoft Corporation |
| Sony Group Corporation |
| HTC Corporation |
| Unity Technologies |
| Others |
Value Network & Pricing Analysis
Fab utilization rates at Taiwanese OLED microdisplay facilities create asymmetric scale economies that compress headset bill-of-materials floors while elevating software platform pricing power through recurring revenue capture. Enterprise training procurement contracts in United States financial services hubs exploit this hardware commoditization to negotiate volume discounts that squeeze unit margins, redirecting value capture toward cloud rendering subscriptions and ISO/IEC 27001-certified service bundles.
Pricing Analysis
Current-generation varifocal enterprise headsets command substantial premiums over fixed-focal-plane consumer units, while prior-generation hardware faces accelerated depreciation as replacement cycles compress. Three-tier pricing structure across premium, standard, and economy levels separates medical training deployments with biometric haptic integration from education-sector thin-client configurations. Cost compression in consumer headsets stems from smartphone-tethered viewer substitution, though enterprise buyers exhibit lower price sensitivity due to compliance documentation and single-vendor accountability requirements.
Supply Chain Analysis
Container availability fluctuations on the Trans-Pacific trade lane introduce inbound logistics volatility for United States headset assemblers sourcing Taiwanese display panels and South Korean HBM memory modules. Component fabrication concentrates in Taiwan, South Korea, and China's Yangtze River Delta manufacturing bases, creating dependencies on OLED microdisplays, precision optics, and galvanic skin response sensors. Single-source vulnerability around Taiwanese OLED fab capacity represents the dominant structural risk, while distribution runs through systems integrators and value-added resellers consolidating vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Social VR sits in early-cycle expansion as enterprise training departments rotate procurement budgets away from legacy learning management systems toward immersive workforce development platforms. Penetration tailwinds from EU AI Act compliance mandates are accelerating explainable avatar behavior system investments across European automotive and industrial engineering verticals.
For Market Incumbents: Fortify captive hardware-software ecosystem control through backward integration into cloud rendering infrastructure and exclusive MEC node partnerships with 5G carriers. Counter emerging thin-client entrants by embedding ISO/IEC 27001 certification into bundled subscription pricing, extending sales cycle advantages that deter unqualified competitors from East Coast financial services procurement channels.
For New Entrants and Emerging Players: Certification fast-track through GDPR-compliant algorithmic segregation protocols offers expedited entry into German and French enterprise training contracts. White-space concentration in India's education ministry pilot programs and price-sensitive institutional deployments across Karnataka and Telangana technology corridors enables 5G network slicing partnerships as the primary go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors creator-economy platform specialists with user-generated content tooling and viral distribution mechanics over hardware-dependent volume plays. Long-term viability hinges on network effect durability rather than unit economics, with acquisition target archetypes clustering around avatar interoperability standard compliance and cross-platform migration capabilities. Watch for inflection signals in METI-driven Japan avatar portability adoption rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Infrastructure Partnership | MEC node deployment with 5G carriers reduces headset cost barriers for education sector penetration. |
| EU AI Act Compliance Certification | Explainable avatar behavior systems unlock German automotive training procurement at premium pricing tiers. |
| Cross-Platform Avatar Interoperability | METI standard alignment reduces user lock-in and expands addressable creator economy network effects. |
| Full-Body Tracking Suit Integration | Galvanic skin response sensor deployment deepens therapeutic application retention and medical training replacement cycles. |
| Systems Integrator Channel Consolidation | Single-vendor accountability structures capture margin from direct platform sales teams in financial services hubs. |
Research Methodology
Operator-level perspectives from enterprise training directors, VR platform engineers, systems integration specialists, and 5G network infrastructure planners anchored the qualitative base. Primary interview data combined with secondary validation from SEC filings of headset manufacturers, hyperscaler capex disclosures for cloud rendering capacity, and FCC wireless spectrum allocation records. Bottom-up unit economics modeling triangulated against top-down market sizing across hardware, software, and services revenue pools.
Sensitivity analysis tested forecast outputs against varying assumptions for enterprise replacement cycle compression and consumer price elasticity thresholds. Segmentation dimensions modeled include product type, user archetype, deployment architecture, and experience format across the analysis window. CAGR derivation incorporated installed base growth, subscription pricing trajectories, and cloud rendering node deployment density as industry-specific forecast inputs.
Underlying assumptions cover EU AI Act implementation timelines and India PLI scheme incentive continuity, with deviation risk concentrated in OLED microdisplay fab capacity expansion and GDPR biometric data enforcement consistency. Practitioners should keep alternative scenarios live as wireless spectrum allocation priorities and cross-platform avatar interoperability standard adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Para-Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Book Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Smart Glasses for Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Fence Market
Virtual Reality (VR) and Augmented Reality (AR)
Data Glove Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Consumer Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market