
 VR Collaboration Platform Market | 2026-2036
VR Collaboration Platform Market Size, Share, and Industry Trends Forecast 2026-2036
VR Collaboration Platform Market Insights
Market Context with Strategic Players
North American cloud infrastructure capacity is decoupling from European data-sovereignty requirements, creating divergent platform architectures. Meta leverages its headset manufacturing scale to control hardware-software integration for enterprise clients. Microsoft sustains channel dominance through Azure-hosted Teams integrations that reduce IT friction. ArborXR competes by specializing in device management for distributed VR fleets across healthcare networks.
Technical Definition and Structural Segments
A VR collaboration platform is a software environment that renders shared three-dimensional workspaces accessible through head-mounted displays, motion tracking sensors, and spatial audio engines, enabling geographically dispersed users to manipulate digital objects in real time for design review, training, or remote supervision. By application, training simulations command the deepest deployment budgets because aerospace and energy firms require certifiable proficiency records. By end user, corporate enterprises anchor current revenue while educational institutions represent the fastest-growing adoption curve as campus VR labs replace physical maker spaces. By deployment model, cloud-based delivery dominates new implementations though hybrid configurations persist in defense and financial services where on-premises rendering handles classified assets.
Regulatory Frame and Forward-Looking Close
The EU AI Act classifies biometric inference in immersive environments as high-risk, forcing platform vendors to document algorithmic decision pathways. The FDA regulates VR-based surgical training modules as medical education devices, requiring validation studies for credentialing acceptance. OSHA guidelines for extended headset use in industrial settings are tightening exposure limits. Stakeholders must monitor whether data-localization mandates fragment platform development into incompatible regional codebases.
Market Dynamics
The EU AI Act's biometric data classification is forcing platform vendors toward edge-computing architectures that process facial tracking and gaze inference locally, fragmenting previously centralized cloud architectures and raising deployment complexity for multinational rollouts.
Growth Catalysts
- GDPR Article 9 Restrictions:Germany's automotive OEMs are accelerating industrial VR lab deployments to replace physical clay modeling facilities, creating certifiable digital audit trails for design reviews.
- Foveated Rendering:Eye-tracking hardware advances are reducing GPU load requirements by 40-60% in training simulations, enabling wireless headset deployment in aerospace maintenance facilities.
- OSHA Industrial Guidelines:Tightening exposure limits for extended headset use are driving demand for ergonomic hardware-software bundles that monitor session duration and force break protocols.
Market Restraints
- GPU Supply Concentration:Taiwan-based foundry capacity constraints create 6-9 month lead times for enterprise-grade rendering hardware, delaying platform scaling for energy sector clients.
- Biometric Data Localization:The EU AI Act's high-risk classification forces redundant infrastructure deployment across member states, inflating total cost of ownership for cross-border collaboration tools.
- 2D Video Conferencing:Microsoft Teams and Zoom maintain entrenched procurement contracts with 90-day cancellation windows, creating switching friction for VR pilot programs.
Strategic Opportunities
- India's PLI Scheme:Electronics manufacturing incentives are attracting headset assembly operations, creating localized supply chains for educational institution deployments.
- FDA Medical Device Pathway:Surgical training modules validated as Class II medical education devices command premium pricing and 5-year exclusive procurement contracts from hospital networks.
- Haptic Glove Convergence:Integration with force-feedback peripherals is opening industrial maintenance applications where precise torque simulation replaces physical equipment access.
Industry Challenges
- Spatial Computing Talent Gap:Shortage of Unity and Unreal Engine developers with networked multiplayer experience extends platform customization timelines from 8 weeks to 6 months.
- CE Marking Complexity:MDR compliance for VR-based physical therapy tools requires clinical evidence dossiers that delay European market entry by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VR Collaboration Platform Market |
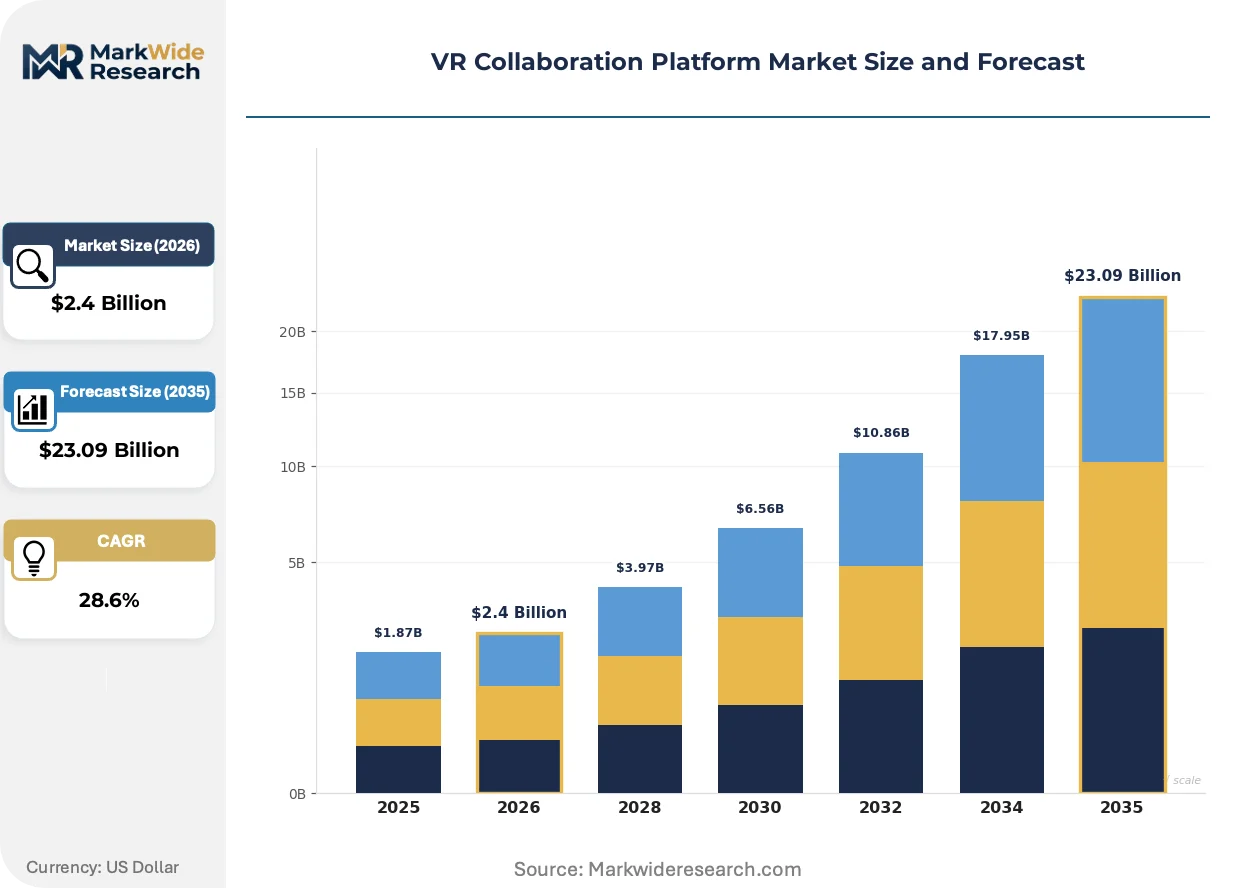
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Remote Work, Virtual Meetings, Training Simulations, Project Collaboration End User: Corporate Enterprises, Educational Institutions, Healthcare Providers, Creative Agencies Deployment Model: On-Premises, Cloud-Based, Hybrid, Virtual Private Network Technology: Head-Mounted Displays, Motion Tracking, 3D Audio, Interactive Interfaces |
| Companies Covered | Qbit, glue, ArborXR, STAGE, The Wild, hubs, MeetinVR, Meta, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VR Collaboration Platform Market Trends and Innovations
Immersive workspace technology is pivoting from novelty demonstration to operational infrastructure, with rendering architectures and data sovereignty frameworks racing to match enterprise security requirements.
Cloud-based rendering is overtaking on-premises GPU clusters as the dominant deployment model for corporate training programs. Siemens and BMW are migrating simulation workloads to distributed edge nodes that process biometric data within national borders. This architecture is compressing hardware capital requirements while complicating vendor pricing structures.
The EU AI Act's high-risk classification for biometric inference is mandating algorithmic documentation that most platforms lacked six months ago. Vendors must now maintain decision-pathway records for eye-tracking analytics used in performance assessment. German automotive labs are responding by demanding on-premise inference engines that exclude third-party cloud processing entirely.
Corporate procurement departments are consolidating VR platform selection under central IT governance rather than allowing departmental experimentation. Healthcare networks in the US are replacing pilot programs with 3-year enterprise agreements that bundle hardware, software, and support. This concentration is visible most acutely in university hospital systems where procurement committees now require FDA validation as a threshold qualification.
VR Collaboration Platform Market Segmentation
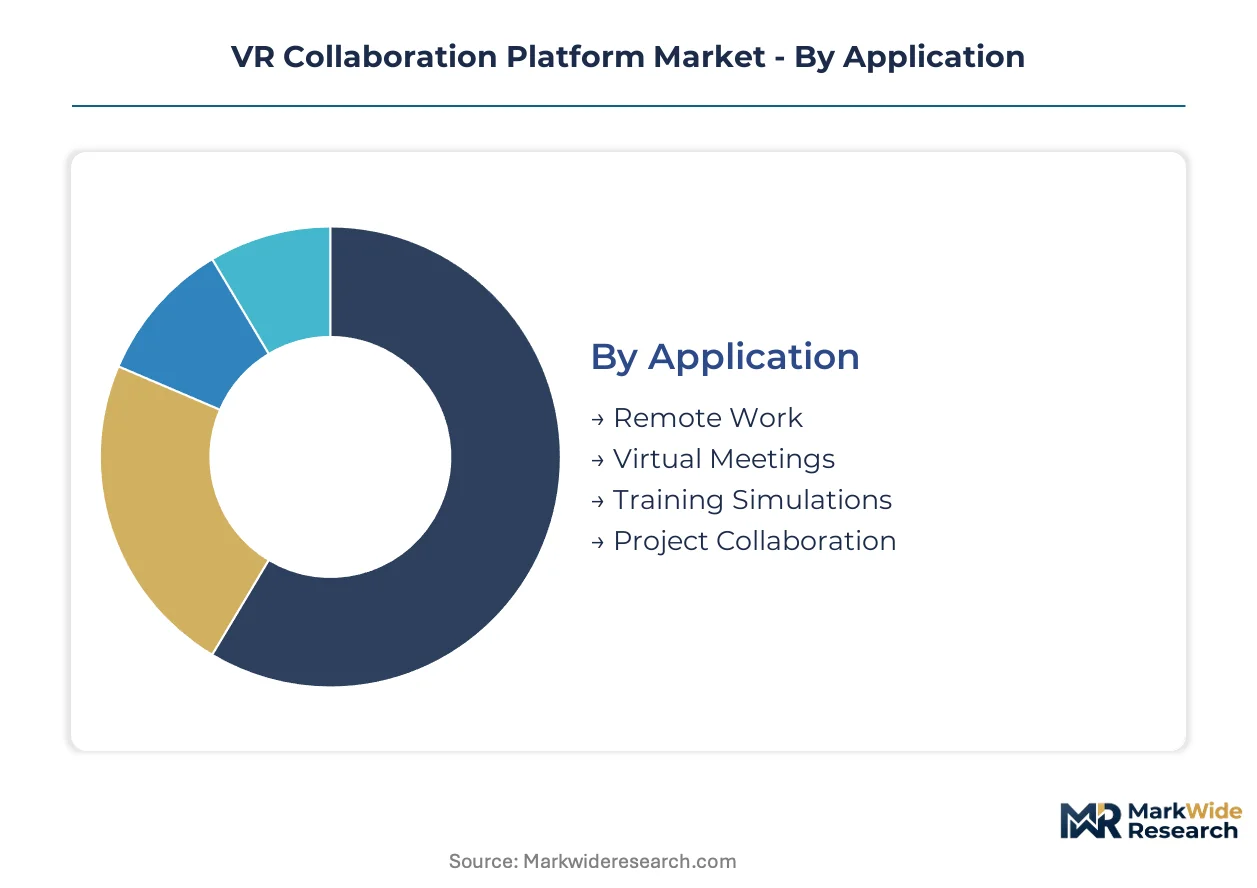
VR collaboration platforms fragment across four structural dimensions that determine procurement priorities and vendor positioning. Each category reflects distinct technical requirements, compliance burdens, and customer concentration patterns that shape competitive strategy.
Application:
Standardized workflows dominate remote work deployments while training simulations demand heavy customization for certifiable outcomes.
- Training Simulations:Certifiable proficiency environments with integrated assessment engines and audit trails. Aerospace and energy firms in Germany anchor demand as they replace physical simulation facilities with persistent virtual environments subject to OSHA exposure protocols.
- Project Collaboration:Shared 3D workspaces enabling real-time design manipulation and spatial annotation. Automotive OEMs concentrate procurement here, driven by GDPR Article 9 requirements for biometric data localization in cross-border engineering reviews.
- Remote Work:Persistent virtual offices with spatial audio and avatar-based presence. Demand clusters in corporate headquarters seeking IT governance consolidation.
- Virtual Meetings:Scheduled immersive sessions replacing 2D video conferencing. Procurement friction from entrenched Teams and Zoom contracts limits near-term scaling.
Leading the category by volume: Project Collaboration. Expanding most quickly: Training Simulations.
End User:
Enterprise procurement committees prioritize vendor consolidation while educational buyers fragment across institutional pilot programs.
- Corporate Enterprises:Centralized IT governance with 3-year bundled agreements covering hardware, software, and support. Healthcare networks in the US demand FDA validation as threshold qualification for surgical training modules.
- Educational Institutions:Campus VR labs replacing physical maker spaces with networked multiplayer environments. India's PLI scheme for electronics manufacturing is attracting localized headset assembly for this segment.
- Healthcare Providers:Surgical training and physical therapy applications requiring Class II medical device validation. CE Marking under MDR extends European market entry timelines significantly.
- Creative Agencies:Design review and client presentation workflows with emphasis on visual fidelity and rapid deployment.
Dominant by procurement value: Corporate Enterprises. Steepest adoption curve: Educational Institutions.
Deployment Model:
Cloud architectures reduce capital intensity while hybrid configurations persist where data sovereignty mandates on-premise inference.
- Cloud-Based:Distributed rendering with subscription pricing and automatic updates. Siemens and BMW are migrating simulation workloads here, though EU AI Act biometric classifications complicate cross-border data flows.
- Hybrid:Edge nodes processing sensitive biometric data locally with cloud orchestration for non-sensitive workloads. German automotive labs demand this architecture to exclude third-party cloud processing entirely.
- On-Premises:Captive GPU clusters for classified assets in defense and financial services. Taiwan foundry capacity constraints create 6-9 month hardware lead times.
- Virtual Private Network:Encrypted tunnels for distributed teams requiring jurisdictional data containment without full edge infrastructure.
Primary deployment path: Cloud-Based. Fastest architectural shift: Hybrid.
Technology:
Hardware-software integration intensity varies from commoditized displays to specialized tracking systems with algorithmic documentation requirements.
- Head-Mounted Displays:Wireless headsets with foveated rendering reducing GPU load 40-60%. Eye-tracking hardware advances enable aerospace maintenance deployment without tethered workstations.
- Motion Tracking:Full-body and hand tracking for industrial maintenance with haptic glove convergence. Force-feedback peripherals open precise torque simulation applications.
- 3D Audio:Spatial sound engines enabling directional communication and environmental immersion. Standard component across all platform tiers.
- Interactive Interfaces:Gesture, gaze, and voice control modalities. EU AI Act mandates algorithmic decision-pathway documentation for eye-tracking analytics used in performance assessment.
Highest integration complexity: Motion Tracking. Fastest capability expansion: Head-Mounted Displays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GPU foundry capacity in Taiwan feeds headset assembly lines across Germany, the United States, and India, concentrating hardware procurement decisions in three distinct regulatory environments.
Germany
Automotive OEMs in Stuttgart and Munich operate the densest cluster of industrial VR collaboration labs, replacing physical clay modeling facilities with persistent virtual environments. The EU AI Act's high-risk classification for biometric inference forces edge-computing architectures that process gaze tracking locally. Bavaria's automotive engineering centers now demand on-premise inference engines excluding third-party cloud processing entirely.
United States
Healthcare networks in university hospital systems anchor surgical training module procurement, requiring FDA validation as threshold qualification for credentialing acceptance. OSHA guidelines for extended headset use in industrial settings tighten exposure limits, driving demand for ergonomic hardware-software bundles. The Pacific Northwest hosts cloud infrastructure capacity decoupling from European data-sovereignty requirements.
India
Educational institutions represent the fastest-growing adoption curve as campus VR labs replace physical maker spaces. The PLI scheme for electronics manufacturing attracts localized headset assembly operations, creating supply chains for institutional deployments. Karnataka and Telangana concentrate demand from engineering colleges expanding networked multiplayer environments.
China
MIIT standards for networked virtual environments shape platform architecture requirements for domestic deployment. Yangtze River Delta manufacturing clusters supply motion tracking sensors and display components to global headset vendors. Shenzhen-based hardware integrators dominate wireless headset assembly for enterprise training applications.
United Kingdom
Creative agencies in London concentrate design review and client presentation workflows with emphasis on visual fidelity. The Information Commissioner's Office enforces GDPR Article 9 restrictions on biometric data collection in immersive workspaces. Southeast England hosts defense contractors maintaining on-premises GPU clusters for classified collaboration assets.
VR Collaboration Platform Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized device management and healthcare network penetration. The vendor base spans three structural tiers: cloud infrastructure operators controlling enterprise channel access, headset manufacturers leveraging hardware-software integration, and vertical specialists targeting regulated industries with compliance-heavy deployment models. Dominant competitive moves include strategic partnerships with automotive OEMs for industrial lab standardization and geographic expansion through localized headset assembly partnerships.
Within the cloud infrastructure tier, Microsoft exemplifies channel dominance through Azure-hosted integrations reducing IT procurement friction. Meta occupies a position anchoring hardware-software integration for enterprise clients through captive headset manufacturing scale. ArborXR represents the vertical specialist archetype, sitting within the healthcare network segment with device management capabilities for distributed VR fleets.
| Leading Market Players |
|---|
| Qbit |
| glue |
| ArborXR |
| STAGE |
| The Wild |
| hubs |
| MeetinVR |
| Meta |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialists in enterprise VR software have compressed pricing discipline through aggressive bundling of hardware procurement with multi-year SaaS commitments, while their captive financing arms extract working capital efficiency from Taiwanese foundry payment terms that cascade through headset assembly operations in China and India.
Pricing Analysis
Warranty and service bundling separates premium-tier deployments from unbundled economy offerings, with German automotive OEMs demanding inclusive on-premise edge infrastructure support while educational buyers in India accept stripped hardware-only configurations. Three-tier pricing structure across premium, standard, and economy levels reflects FDA certification status for surgical training modules and GDPR Article 9 compliance depth for biometric data handling. Cost compression in the standard tier is intensifying because cloud rendering vendors are absorbing GPU supply risk into fixed subscription rates. Healthcare networks show least price sensitivity due to credentialing requirements, whereas campus IT departments in emerging markets operate under severe capital constraints.
Supply Chain Analysis
Reverse-logistics flows for enterprise VR headsets remain underdeveloped, with most vendors lacking systematic refurbishment programs for returned motion tracking sensors and degraded battery packs. Taiwan, China, and Vietnam concentrate supply for GPU foundry output, display panel fabrication, and final assembly respectively. The chain draws from rare earth elements for magnet arrays in haptic gloves, gallium nitride substrates for power electronics, and specialized optical polymers for pancake lenses. Single-source vulnerability in Taiwan-based foundry capacity creates systemic exposure for rendering hardware procurement. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with limited channel partner penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EU AI Act compliance costs force subscale vendors to exit or sell, with biometric data localization mandates requiring infrastructure investments that fragment below $50 million annual recurring revenue.
For Market Incumbents: Lock in automotive OEM relationships through exclusive edge-computing infrastructure partnerships that exclude third-party cloud processing, while acquiring haptic glove specialists to control force-feedback peripheral supply for industrial maintenance applications. The threat of Microsoft's Teams-integrated VR bundles demands defensive certification investments in FDA-validated surgical training modules.
For New Entrants and Emerging Players: Enter via India's educational institution segment where PLI-subsidized localized headset assembly creates cost advantages against import-dependent incumbents, targeting engineering colleges in Karnataka and Telangana with networked multiplayer lab configurations. White-space exists in physical therapy applications requiring MDR CE Marking, where clinical evidence dossier requirements delay established vendors.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertical specialists with healthcare network device management capabilities in the United States, where FDA validation as threshold qualification creates durable competitive moats. Long-term viability hinges on 5-10 year enterprise agreement renewal rates rather than pilot program conversion. Monitor OSHA guideline tightening for industrial exposure limits as inflection indicator for ergonomic hardware-software bundle demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Partnership | Automotive OEMs in Bavaria demand on-premise inference engines excluding third-party cloud processing entirely. |
| FDA Class II Medical Device Validation | Hospital networks require this threshold qualification for surgical training module credentialing acceptance. |
| Haptic Glove Technology Integration | Force-feedback peripherals open precise torque simulation for aerospace maintenance without physical equipment. |
| Localized Headset Assembly Operations | India's PLI scheme attracts supply chain relocation for educational institution deployment cost competitiveness. |
| Biometric Data Localization Compliance | EU AI Act mandates edge nodes processing gaze tracking within national borders for cross-border collaboration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with VR platform engineering leads, healthcare procurement committee members, automotive simulation facility directors, and educational IT administrators. FDA 510(k) submissions, EU AI Act implementation guidance, German KBA automotive standards, and India's PLI scheme disbursement records provided validation anchors. Bottom-up deployment counts across enterprise, healthcare, and education segments were triangulated against top-down cloud infrastructure capacity and headset shipment data.
Data-stream reconciliation across multiple inputs enabled segmentation modeling by application, end user, deployment model, and technology type throughout the forecast period. CAGRs were derived from installed base growth rates adjusted for replacement cycles and expansion revenue per account. Foveated rendering adoption curves, biometric data localization compliance timelines, and OSHA guideline evolution served as industry-specific forecast inputs.
Revisions become necessary when GPU foundry capacity constraints extend beyond current procurement timelines, when EU AI Act enforcement intensity shifts, or when FDA validation pathways for surgical training modules accelerate. Practitioners should monitor Taiwan semiconductor equipment import data and German automotive OEM edge-computing RFP volumes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Middle East and Africa Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Commercial Augmented Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Production Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Education Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented and Virtual Reality (AR VR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market