
 AR and VR Solutions Market | 2026-2036
AR and VR Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
AR and VR Solutions Market Insights
Subscription-based software layers for spatial computing is recalibrating how AR and VR value gets captured and renewed. Meta leverages its social platform integration to anchor consumer headset ecosystems. Microsoft Corporation sustains enterprise credibility through its industrial mixed-reality stack. Sony Group Corporation dominates premium entertainment VR through proprietary content pipelines.
AR and VR solutions encompass wearable displays, spatial software engines, motion controllers, and environmental sensors that render digital content into physical space or immerse users in synthetic environments. These systems rely on sub-20ms motion-to-photon latency, inside-out tracking cameras, and foveated rendering to prevent simulator sickness while delivering photorealistic scenes. Headsets command the hardware margin pool while software subscriptions capture recurring value. Healthcare applications are expanding fastest as surgical planning and remote rehabilitation protocols validate clinical outcomes. Gaming remains the volume leader but faces margin compression from platform store fees.
The EU AI Act classifies biometric inference from AR headsets as high-risk, forcing compliance audits for European deployments. The FDA reviews VR therapeutic devices as digital health tools, creating a dual-track pathway for wellness versus prescription indications. China's MIIT mandates GB standards for near-eye display safety and electromagnetic compatibility. Stakeholders must monitor how national data-localization rules fragment cloud-rendering architectures and force regional infrastructure buildouts.
Market Dynamics
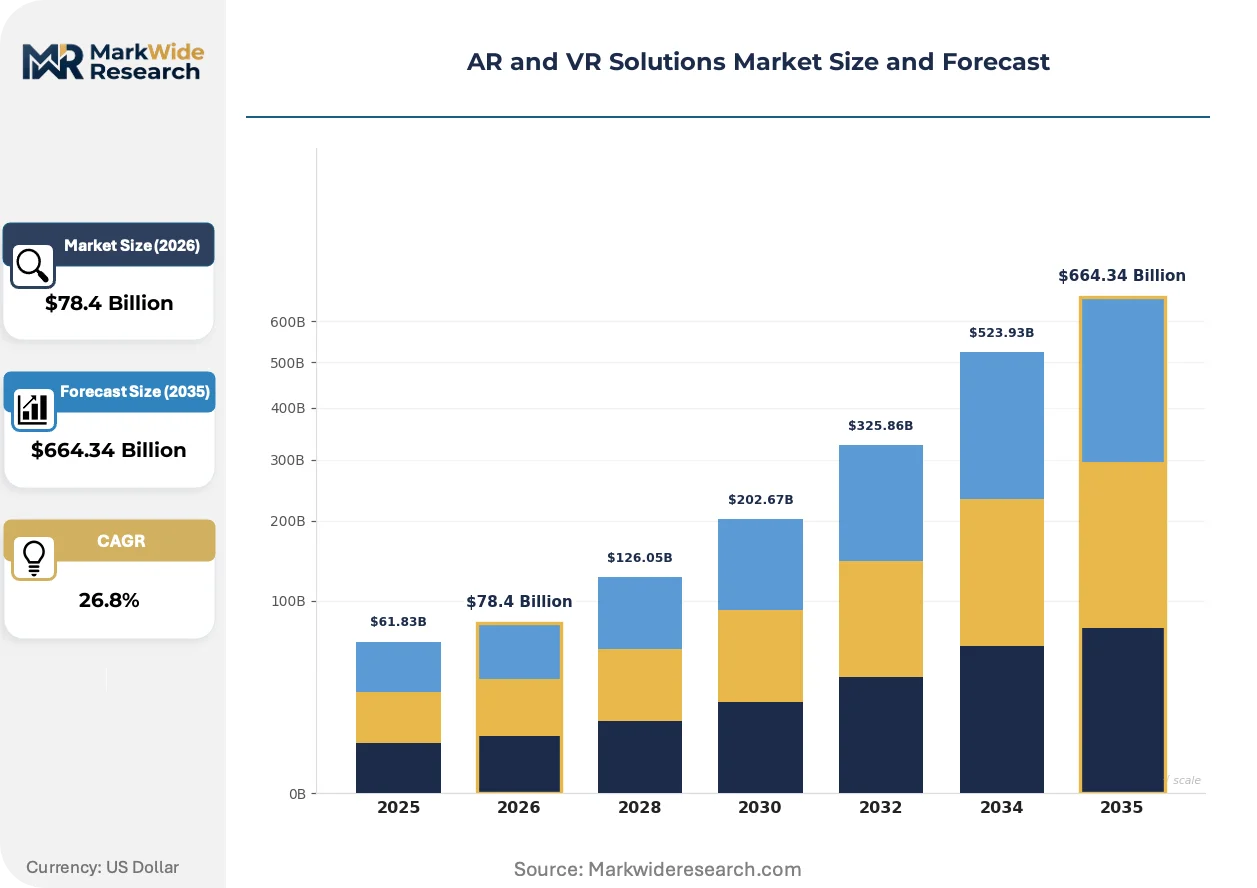
Subscription software layers are recalibrating value capture in spatial computing, shifting margin pools from one-time hardware sales toward recurring SaaS revenue streams anchored by enterprise training and remote collaboration protocols.
Growth Catalysts
- Enterprise Training Mandates:Manufacturing and logistics operators in Germany are expanding headset deployments for assembly-line simulation and hazardous-environment rehearsal, validating time-to-competency metrics.
- EU AI Act Compliance Services:Biometric inference classification as high-risk is forcing European deployments to adopt audit-ready data architectures, creating consultative revenue streams for compliant platform vendors.
- Foveated Rendering Maturation:Eye-tracking hardware integration is reducing GPU load requirements by 40-60%, enabling untethered standalone headsets to approach PC-VR fidelity thresholds.
Market Restraints
- Display Panel Concentration:Micro-OLED and pancake lens supply chains cluster in South Korea and Japan, creating single-source vulnerability for premium headset manufacturers.
- Motion-to-Photon Latency Floors:Sub-20ms synchronization requirements demand specialized ASICs and optical tracking subsystems that resist cost-down engineering.
- GDPR Biometric Friction:Continuous eye-tracking and spatial mapping generate persistent personal data streams that trigger data-localization mandates and cross-border transfer restrictions.
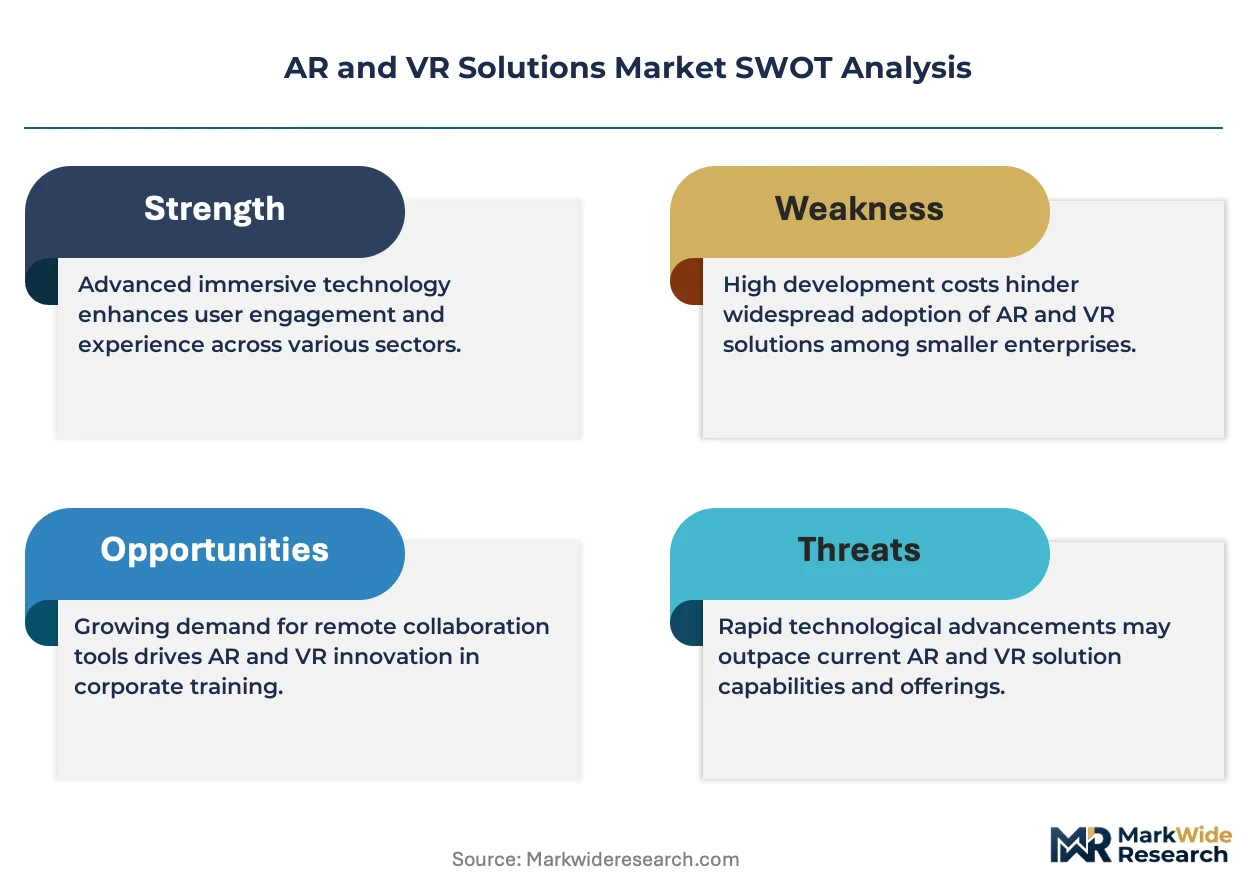
Strategic Opportunities
- Surgical Planning Protocols:Pre-operative visualization in cardiac and orthopedic specialties is absorbing VR planning tools into hospital credentialing requirements, particularly in United States academic medical centers.
- China GB Standards Alignment:MIIT-mandated near-eye display safety certifications create a regulated procurement channel for domestic and foreign hardware vendors meeting electromagnetic compatibility thresholds.
- Cloud-Rendering Architectures:Edge computing partnerships with telecommunications operators are enabling low-latency streaming to lightweight headsets, decoupling display quality from local processing power.
Industry Challenges
- Spatial Computing Talent Scarcity:Developers proficient in Unity and Unreal Engine spatial toolkits command premium compensation, constraining software pipeline velocity for mid-tier vendors.
- FDA Dual-Track Navigation:VR therapeutic devices face divergent evidentiary requirements between wellness and prescription indications, extending certification timelines and clinical trial expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR and VR Solutions Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $664.34 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Software, Controllers, Accessories Application: Gaming, Training, Education, Healthcare Technology: Augmented Reality, Virtual Reality, Mixed Reality, 360-Degree Video End User: Entertainment, Retail, Automotive, Real Estate |
| Companies Covered | Meta, Sony Group Corporation, Apple Inc., Microsoft Corporation, Google LLC, HTC Corporation, Samsung Electronics Co., Ltd., Unity Software Inc., Valve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR and VR Solutions Market Trends and Innovations
Three forces are compressing the innovation cycle in immersive technologies: rendering architecture decentralization, biometric regulation hardening, and procurement model unbundling. Each is redistributing margin pools and vendor influence.
Pass-through mixed reality is absorbing computational workloads previously reserved for fully occluded VR, enabling industrial technicians in United States automotive plants to overlay schematics onto physical assembly stations without removing headsets. Manufacturers are adopting this modality faster than entertainment developers anticipated, compressing the addressable market for single-purpose VR hardware.
The EU AI Act's high-risk classification for biometric inference is forcing European healthcare and enterprise deployments to implement explainable AI documentation and human-in-the-loop override systems. Surgical planning platforms and workforce training tools are most affected, with vendors restructuring cloud architectures to keep inference processing within regional boundaries.
Hardware-as-a-service leasing is displacing capital expenditure models in German and Chinese industrial training programs, with facility operators preferring per-seat monthly fees that bundle headsets, software licenses, and technical support. This shift concentrates procurement authority with operational technology managers rather than traditional IT departments, altering vendor sales motion requirements.
AR and VR Solutions Market Segmentation
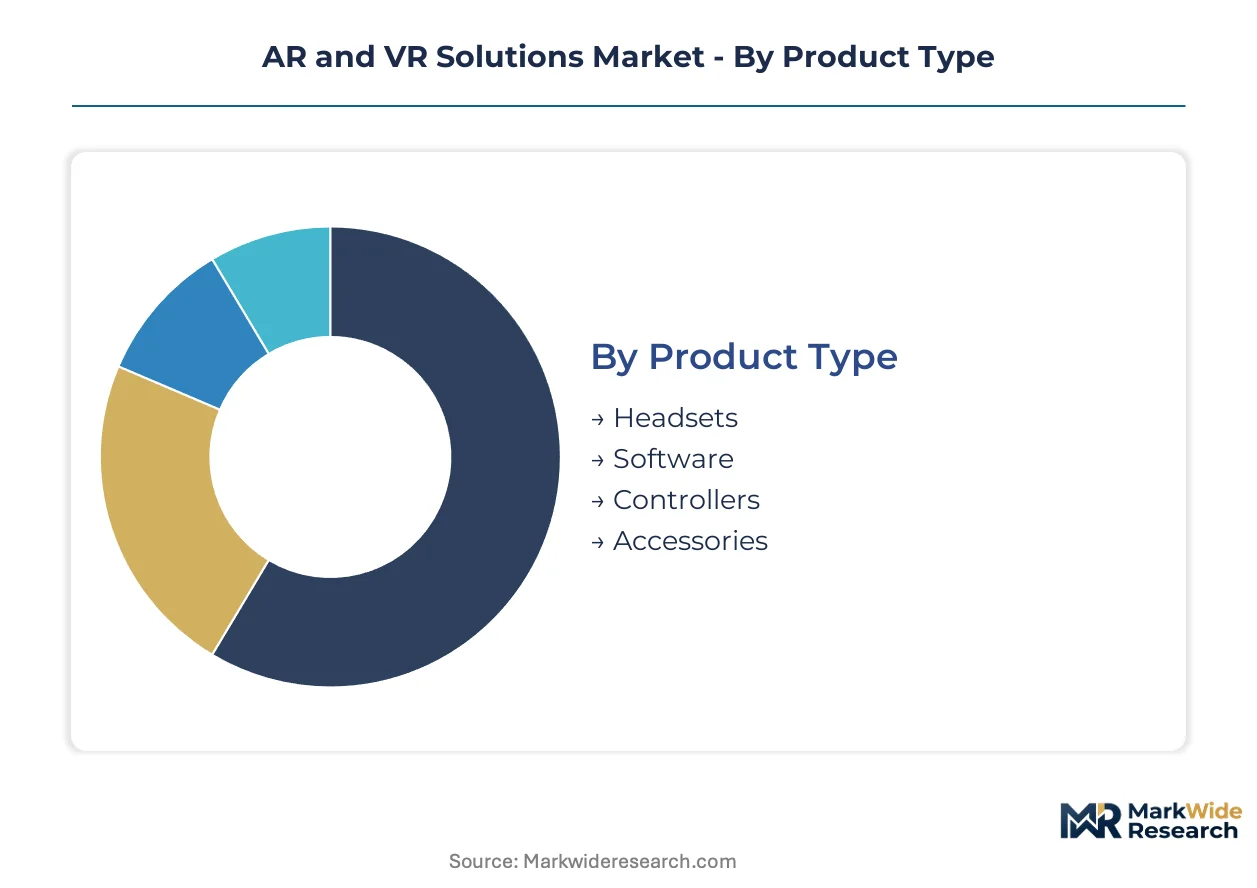
Segmentation in AR and VR Solutions reveals how procurement authority shifts between IT departments and operational technology managers based on deployment scale and use case complexity. Understanding these divides clarifies where margin pools concentrate and which technical specifications dominate buying criteria.
Product Type:
Hardware specifications and software licensing models determine total cost of ownership across enterprise and consumer deployments.
- Headsets:Wearable displays integrate micro-OLED panels, pancake optics, and inside-out tracking cameras to achieve sub-20ms motion-to-photon latency. Manufacturing and logistics operators in Germany prioritize pass-through mixed-reality capabilities for assembly-line overlay applications.
- Software:Spatial computing engines and enterprise training platforms operate on subscription tiers that bundle content libraries, analytics dashboards, and compliance documentation. Demand concentrates in United States healthcare systems seeking FDA-aligned therapeutic modules.
- Controllers:Hand-tracking peripherals and haptic gloves enable precision manipulation in surgical planning and industrial simulation environments.
- Accessories:Charging docks, protective cases, and prescription lens inserts extend headset utility for prescription-wearing professionals in automotive design studios.
Volume sits with Headsets; growth tilts toward Software.
Application:
Regulatory scrutiny and reimbursement pathways segment commercial viability across therapeutic, educational, and entertainment contexts.
- Gaming:Consumer entertainment platforms drive unit shipments but face margin compression from platform store fees and content licensing costs. Volume leadership persists in China and United States markets despite profitability pressures.
- Training:Workforce simulation protocols in hazardous environments and complex assembly procedures absorb enterprise hardware budgets. German automotive manufacturers credential technicians using VR rehearsal modules that reduce time-to-competency metrics.
- Education:Immersive history, science, and vocational curricula deploy in United States academic medical centers and Chinese technical institutes under procurement frameworks that prioritize content durability.
- Healthcare:Surgical planning and remote rehabilitation tools climb fastest as United States hospitals integrate pre-operative visualization into cardiac and orthopedic credentialing requirements.
Revenue concentrates in Training; steepest expansion trajectory belongs to Healthcare.
Technology:
Rendering architecture choices determine hardware processing requirements and cloud-dependency profiles for different immersion depths.
- Augmented Reality:Optical see-through and video see-through systems overlay digital content onto physical environments using spatial mapping and SLAM algorithms. Retail applications in China leverage AR for virtual try-on and showroom visualization.
- Virtual Reality:Fully occluded headsets generate synthetic environments demanding high-fidelity graphics and low-latency tracking. Gaming and entertainment deployments in United States drive volume despite tethering constraints.
- Mixed Reality:Pass-through cameras enable simultaneous physical and digital interaction, absorbing workloads from pure VR in German industrial settings where technicians overlay schematics onto assembly stations.
- 360-Degree Video:Spherical capture and playback systems serve tourism, real estate, and remote site inspection use cases with lower interactivity requirements.
Deployment scale favors Virtual Reality; capability expansion centers on Mixed Reality.
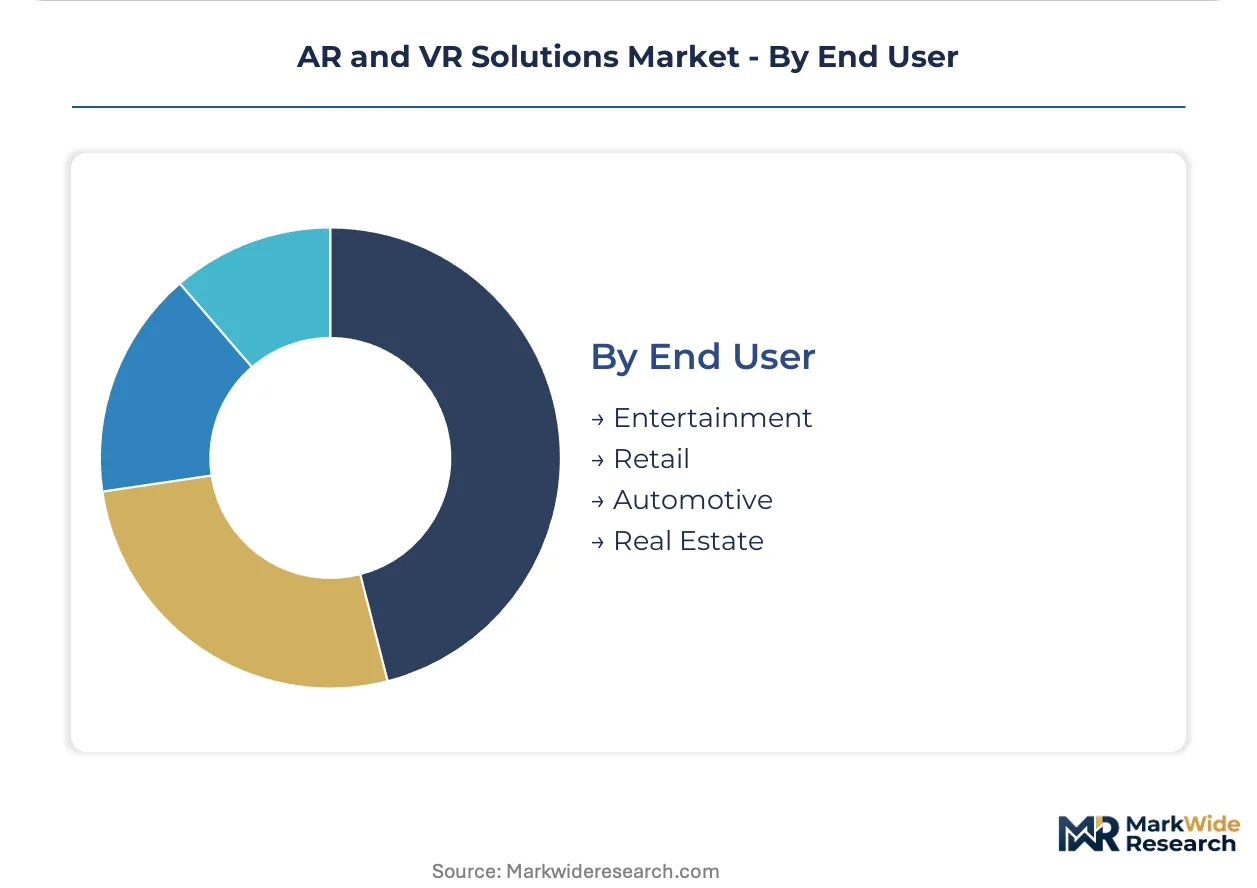
End User:
Industry-specific compliance mandates and procurement authority structures reshape vendor sales motions and pricing flexibility.
- Entertainment:Content studios and streaming platforms prioritize proprietary exclusives and social feature integration over hardware specifications.
- Retail:Virtual showrooms and AR product visualization tools reduce return rates for furniture and apparel merchants in China and United States markets.
- Automotive:Design review, manufacturing training, and dealership configuration tools absorb mixed-reality budgets as German and United States OEMs digitize product development pipelines.
- Real Estate:Virtual property tours and architectural visualization services accelerate transaction velocity for commercial and residential brokers.
Investment intensity peaks in Automotive; penetration gaps remain widest in Real Estate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware production concentrates in East Asian component clusters while enterprise software consumption tilts toward North American and European industrial budgets. This geographic split shapes procurement patterns and regulatory compliance architectures across deployment regions.
United States
Healthcare systems and automotive manufacturers drive enterprise headset procurement for surgical planning and design review workflows. FDA digital health oversight creates dual-track certification pathways for VR therapeutic devices. Academic medical centers in Boston and the San Francisco Bay Area credential residents using immersive pre-operative visualization modules.
China
Domestic OEMs absorb volume production of micro-OLED panels and pancake optics while retail AR applications expand in virtual try-on and showroom visualization. MIIT mandates GB standards for near-eye display safety and electromagnetic compatibility. Manufacturing clusters in Shenzhen and Shanghai integrate mixed-reality training into automotive assembly-line protocols.
Germany
Automotive OEMs and logistics operators deploy pass-through mixed reality for technician credentialing and hazardous-environment rehearsal. EU AI Act compliance requirements force audit-ready data architectures for biometric inference from eye-tracking systems. Industrial training facilities in Bavaria and Baden-Württemberg absorb hardware-as-a-service leasing models.
Japan
Precision manufacturing and entertainment content studios sustain demand for high-fidelity VR systems and motion-capture infrastructure. METI industrial digitization incentives accelerate workforce simulation deployments. Tokyo and Osaka house concentrated development talent for spatial computing engines and haptic peripheral integration.
South Korea
Display panel foundries in Gyeonggi Province supply micro-OLED substrates to global headset manufacturers, creating upstream leverage in hardware value chains. MFDS medical device frameworks shape therapeutic VR certification timelines. Seoul-based electronics conglomerates anchor consumer entertainment ecosystems while expanding enterprise software partnerships.
AR and VR Solutions Market Competitive Landscape
Capital-heavy hardware producers compete with asset-light software designers for margin capture in spatial computing. The vendor base stratifies across three tiers: integrated platform operators controlling headset-to-cloud stacks, specialized component suppliers dominating optical and sensor subsystems, and vertical software houses serving regulated healthcare and industrial training segments. Dominant competitive moves include strategic partnerships with telecommunications operators for edge-rendering infrastructure and portfolio diversification into subscription-based enterprise training platforms.
Within the integrated platform tier, Meta and Microsoft Corporation exemplify divergent ecosystem strategies. Meta leverages social platform integration to anchor consumer headset deployments and recurring content revenue. Microsoft Corporation sustains enterprise credibility through industrial mixed-reality stacks serving automotive and healthcare procurement channels. Sony Group Corporation occupies a premium entertainment position, anchoring proprietary content pipelines that differentiate hardware offerings in high-margin gaming segments.
| Leading Market Players |
|---|
| Meta |
| Sony Group Corporation |
| Apple Inc. |
| Microsoft Corporation |
| Google LLC |
| HTC Corporation |
| Samsung Electronics Co., Ltd. |
| Unity Software Inc. |
| Valve Corporation |
| Others |
Pricing and Supply Chain Analysis
Micro-OLED substrate pricing indices cascade through headset manufacturing tiers, compressing margins for premium standalone devices while subscription software layers capture recurring value insulated from component volatility. Panel cost fluctuations reshape procurement negotiations between South Korean foundries and hardware assemblers in China and Vietnam.
Pricing Analysis
Margin tightening in enterprise hardware reflects foveated rendering maturation reducing GPU load requirements and enabling cost-down engineering in mid-tier headsets. Three-tier pricing structure across premium, standard, and economy levels separates surgical-grade FDA-aligned devices from industrial training modules and consumer entertainment units. Pricing pressure stems from platform store fees compressing gaming software margins. Healthcare systems exhibit lowest price sensitivity due to reimbursement pathways; logistics operators in Germany demonstrate highest sensitivity, driving hardware-as-a-service leasing adoption.
Supply Chain Analysis
China's MIIT-mandated GB standards for near-eye display safety and electromagnetic compatibility reshape sourcing patterns, forcing foreign vendors toward domestic component partnerships or costly certification duplication. Display panel production concentrates in South Korea and Japan; optical assembly feeds from Shenzhen and Shanghai manufacturing clusters. Single-source vulnerability persists for pancake lens substrates. Distribution runs through telecommunications operators for edge-rendering partnerships and direct enterprise sales for industrial training deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panel substrate capacity constraints prop pricing power for integrated platform operators controlling headset-to-cloud stacks, while software subscription layers capture margin insulated from hardware supply cycles.
For Market Incumbents: Extend enterprise credibility through industrial mixed-reality stack deepening, particularly in automotive design review and surgical planning protocols where FDA dual-track navigation creates certification moats. Counter emerging cloud-rendering entrants by anchoring edge infrastructure partnerships with telecommunications operators in United States and German markets. Prioritize backward integration into eye-tracking ASIC design to reduce motion-to-photon latency subsystem costs. For New Entrants and Emerging Players: Enter via cloud-rendering software layers decoupled from hardware supply constraints, targeting real estate visualization and remote rehabilitation applications where incumbent platform integration remains shallow. White-space concentrates in 360-degree video capture for tourism and construction site inspection, segments demanding lower interactivity specifications. Pursue hardware-as-a-service leasing models to bypass capital expenditure procurement friction in Chinese technical institutes. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized component suppliers dominating optical and sensor subsystems in South Korea and Japan, where display panel foundry consolidation creates upstream leverage. Long-term viability hinges on regulatory compliance service layers addressing EU AI Act biometric inference mandates. Monitor FDA prescription-indication approvals for VR therapeutic devices as inflection signal for healthcare segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Meta's social platform anchoring binds consumer headset ecosystems to recurring content revenue streams. |
| Strategic Partnership | Telecommunications edge-rendering alliances enable low-latency streaming to lightweight headsets in United States markets. |
| Acquisition of Specialist Firm | Eye-tracking ASIC designers reduce motion-to-photon latency floors resisting cost-down engineering pressures. |
| Geographic Expansion | GB standards alignment unlocks regulated procurement channels for domestic and foreign hardware vendors in China. |
| Product Launch | FDA-aligned surgical planning modules integrate into United States academic medical center credentialing requirements. |
Research Methodology
Multi-period observation of headset shipment volumes, subscription renewal rates, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with spatial computing developers, enterprise training procurement officers, healthcare biomedical engineers, and telecommunications edge infrastructure planners. Secondary validation drew from FDA 510(k) submissions, EMA medical device registrations, MIIT GB standard publications, and hyperscaler capex disclosures. Bottom-up unit economics triangulated against top-down industrial digitization budget surveys.
Segment-weighting across product type, application, technology, and end-user dimensions calibrated value distribution throughout the projection horizon. Deployment scale differentials between gaming volume and healthcare expansion trajectories informed CAGR derivation. Industry-specific inputs included foveated rendering adoption curves, EU AI Act compliance audit costs, and hardware-as-a-service penetration rates in German automotive training facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under display panel supply disruptions, GDPR biometric data localization mandate expansion, and FDA prescription-indication pathway acceleration. Forecasts reflect assumptions documented in segmentation granularity and regional regulatory cluster definitions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Neuro-Gaming Technology Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
Wireless AR Glass Market
Virtual Reality (VR) and Augmented Reality (AR)
Germany Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Virtual Reality Market