
 AR in Healthcare Market | 2026-2036
AR in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
AR in Healthcare Market Analysis
North American surgical training infrastructure is reconfiguring how hospitals adopt immersive visualization platforms. Microsoft Corporation leverages its HoloLens hardware ecosystem to anchor enterprise-grade medical deployments across teaching hospitals. Siemens Healthineers sustains deep R&D intensity in image-guided therapy systems that integrate AR overlays with live imaging modalities. Philips competes through specialized interventional suites that combine augmented visualization with catheter navigation.
Augmented reality in healthcare overlays digital anatomical models, real-time imaging data, and procedural guidance onto the clinician's field of view through head-mounted displays or projection systems, requiring sub-20-millisecond motion-to-photon latency to prevent simulator sickness during lengthy procedures. The technology serves primarily to reduce surgical error rates, compress training curves for complex interventions, and enable remote expert assistance during live operations. Markerless tracking technology leads in commercial deployment because it eliminates fiducial preparation time in sterile environments, while surgical visualization applications capture the deepest margin pools due to reimbursement alignment with existing procedural codes. Smart glasses dominate device type discussions for their hands-free operation, though headsets retain traction in controlled simulation settings where field-of-view breadth outweighs mobility constraints.
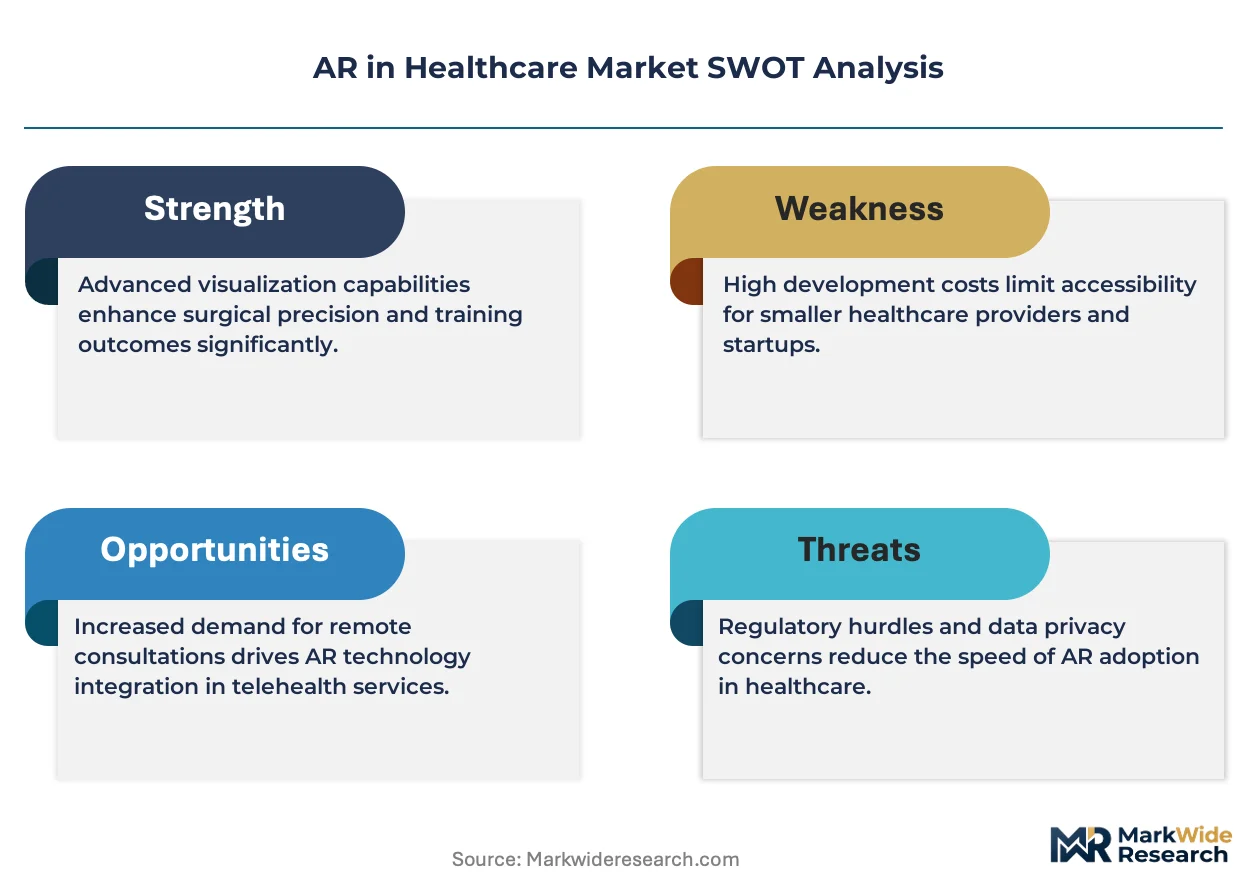
FDA premarket notification pathways for AR surgical navigation systems impose substantial clinical validation requirements that filter out undercapitalized entrants. EMA's Medical Device Regulation extends conformity assessment obligations to software-driven visualization tools, creating parallel compliance burdens for multi-territory launches. Health Canada and Japan's PMDA maintain distinct but converging standards for optical see-through displays in clinical settings. Stakeholders must monitor how reimbursement authorities classify AR-assisted procedures relative to conventional surgical codes, as this determination will govern hospital capital allocation and physician adoption velocity.
Market Dynamics
Markerless tracking systems are compressing surgical preparation timelines and forcing incumbent navigation platforms to eliminate fiducial dependencies or lose hospital procurement cycles.
Growth Catalysts
- FDA 510(k) pathway maturation:Streamlined premarket notification frameworks for optical see-through surgical devices accelerate hospital system pilot-to-deployment transitions in the United States.
- Interventional radiology digitization:Catheter labs in Germany and Japan are retrofitting suites with AR overlay capabilities to merge live fluoroscopy with 3D anatomical models during complex vascular procedures.
- Remote surgical assistance protocols:5G-enabled telementoring networks allow expert surgeons in tertiary centers to annotate operative fields for rural hospitals, extending specialist reach without physical relocation.
Market Restraints
- EMA MDR conformity costs:Extended assessment obligations for software-driven visualization tools impose parallel compliance burdens that delay multi-territory launches by 18-24 months.
- Optical component supply concentration:Waveguide and microdisplay manufacturing clusters in East Asia create vulnerability to single-source dependencies for head-mounted display producers.
- Motion-to-photon latency thresholds:Sub-20-millisecond synchronization requirements demand specialized GPU architectures that inflate hardware bill-of-materials by 40-60% relative to consumer AR devices.
Strategic Opportunities
- Prehospital emergency medicine:Ambulance services in the United States are piloting AR-guided intravenous access and airway management for paramedic skill augmentation in transit.
- Physical therapy rehabilitation:Gamified movement tracking applications represent an underpenetrated outpatient segment where reimbursement codes are stabilizing faster than surgical categories.
- Japan PMDA fast-track designations:Breakthrough device pathways for intraoperative navigation systems compress review timelines and create first-mover advantages for compliant entrants.
Industry Challenges
- Surgical informatics talent scarcity:Health systems struggle to recruit clinical engineers capable of integrating AR platforms with existing PACS and EMR architectures.
- Capital equipment refresh cycles:Hospital CFOs demand 7-10 year depreciation schedules for AR suites, compressing vendor pricing power and forcing hardware-as-a-service pivots.
- Interoperability certification delays:DICOM-RT and HL7 FHIR conformance testing for mixed-reality viewers extends implementation timelines by 6-9 months per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AR in Healthcare Market |
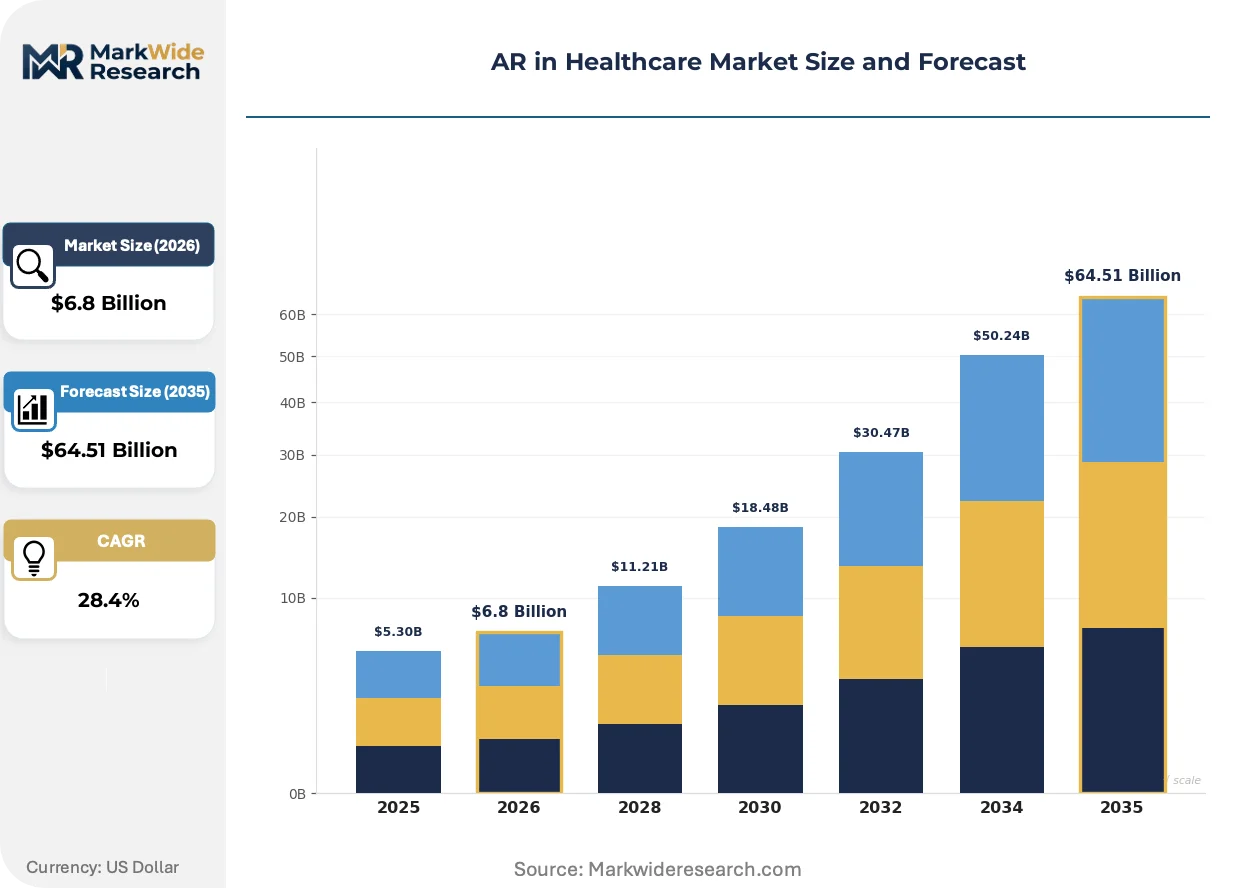
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $64.51 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Marker-Based, Markerless, Projection-Based, Superimposition End User: Hospitals, Clinics, Medical Training Institutions, Research Organizations Application: Medical Imaging, Surgical Visualization, Patient Education, Rehabilitation Device Type: Smart Glasses, Mobile Devices, Headsets, Wearable Displays |
| Companies Covered | Microsoft Corporation, Siemens Healthineers, Koninklijke Philips, Google LLC, Magic Leap, CAE Healthcare, EchoPixel, AccuVein, XRHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AR in Healthcare Market Emerging Trajectories
Computational photonics and edge AI deployment are collapsing the latency barriers that previously confined AR surgical systems to research environments.
Spatial computing chipsets with dedicated neural processing units are collapsing the hardware footprint required for real-time anatomical segmentation. Academic medical centers in the United States are deploying these systems in hybrid operating rooms at twice the pace of community hospitals. The technology is collapsing the distinction between preoperative planning and live navigation by enabling on-the-fly model updates from intraoperative imaging.
EU Medical Device Regulation Article 10 software classification rules are forcing AR visualization vendors to maintain technical documentation libraries that satisfy notified body scrutiny of algorithm training datasets. Manufacturers serving European markets must now demonstrate clinical validation across diverse patient populations. Surgical navigation platforms with machine learning components face the steepest compliance burden, driving consolidation among undercapitalized software-only entrants.
Hospital procurement committees are consolidating vendor relationships around enterprise AR platforms rather than best-of-breed point solutions. Integrated delivery networks in Germany and Japan are awarding 5-7 year exclusive contracts to single-platform providers, displacing fragmented purchasing of standalone simulation and navigation tools. This concentration is most visible in university hospital systems where standardization across subspecialty departments reduces training and support overhead.
AR in Healthcare Market Segmentation
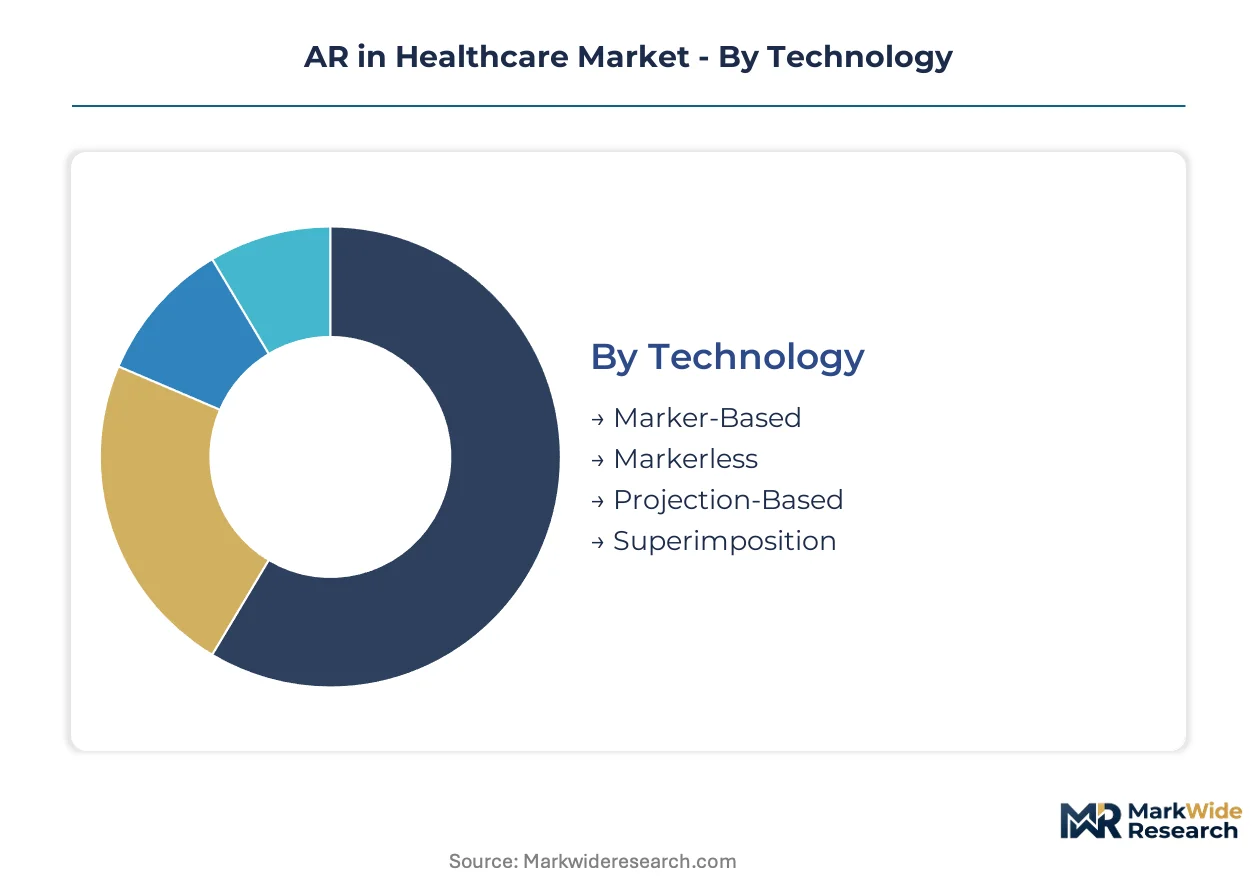
AR healthcare segmentation reveals how hardware specifications, clinical workflows, and reimbursement pathways fragment purchasing authority across hospital departments. Procurement committees weight device latency against integration costs differently depending on whether the use case involves live surgery, resident training, or outpatient rehabilitation.
Technology:
After-sales service intensity varies sharply across tracking modalities, with markerless systems demanding continuous calibration support while projection-based installations require on-site optical alignment expertise.
- Markerless:Computer vision algorithms track anatomical features without fiducial preparation, eliminating sterile field contamination risks. Demand concentrates in United States tertiary surgical centers where FDA-cleared navigation systems command premium procurement budgets. Service contracts typically span 5-7 years with quarterly calibration visits.
- Marker-Based:Fiducial markers attached to surgical instruments enable sub-millimeter tracking precision through infrared cameras. German university hospitals favor this approach for orthopedic navigation where bone-implant alignment tolerances are tightest. Hardware replacement cycles accelerate due to marker sterilization wear.
- Projection-Based:Direct surface projection overlays anatomical data onto patient skin without wearable hardware.
- Superimposition:Real-time image fusion combines CT/MRI datasets with live video feeds through semi-transparent displays.
By volume, Markerless leads. By growth pace, Superimposition is ahead.
End User:
Capital allocation authority differs fundamentally between integrated delivery networks and standalone facilities, with research organizations operating on grant cycles rather than depreciation schedules.
- Hospitals:Hybrid operating rooms in Japan and Germany anchor enterprise AR deployments where surgical visualization integrates with existing imaging archives. Procurement committees demand DICOM conformance and 7-year hardware lifecycles. These installations generate the deepest service revenue streams for vendors.
- Medical Training Institutions:Simulation centers purchase headsets in volume for procedural training without live patient risk. United States academic medical centers refresh equipment every 3-4 years as graphics fidelity improves. Grant funding volatility creates lumpy demand patterns.
- Clinics:Outpatient settings prioritize mobile AR for patient education and preoperative planning.
- Research Organizations:Experimental protocols drive early-stage hardware adoption before commercial clearance.
By revenue concentration, Hospitals dominate. By expansion trajectory, Medical Training Institutions are climbing fastest.
Application:
Reimbursement code alignment determines which applications capture sustainable margin pools versus pilot program funding.
- Surgical Visualization:Real-time anatomical overlay during live procedures reduces revision rates in complex spinal and cranial interventions. United States hospital systems prioritize this category due to existing CPT code alignment that preserves physician billing workflows. Latency requirements below 20 milliseconds exclude consumer-grade hardware.
- Rehabilitation:Gamified movement tracking for stroke and orthopedic recovery operates in outpatient settings with emerging reimbursement stability. German physiotherapy networks are expanding fastest as statutory health insurance pilots mature into permanent coverage categories.
- Medical Imaging:3D reconstruction overlay enhances radiologist interpretation of complex anatomy.
- Patient Education:Preoperative anatomical visualization improves informed consent documentation.
By current deployment scale, Surgical Visualization leads. By reimbursement momentum, Rehabilitation is gaining share fastest.
Device Type:
Form factor tradeoffs between field-of-view breadth and mobility constraints segment procurement across surgical subspecialties.
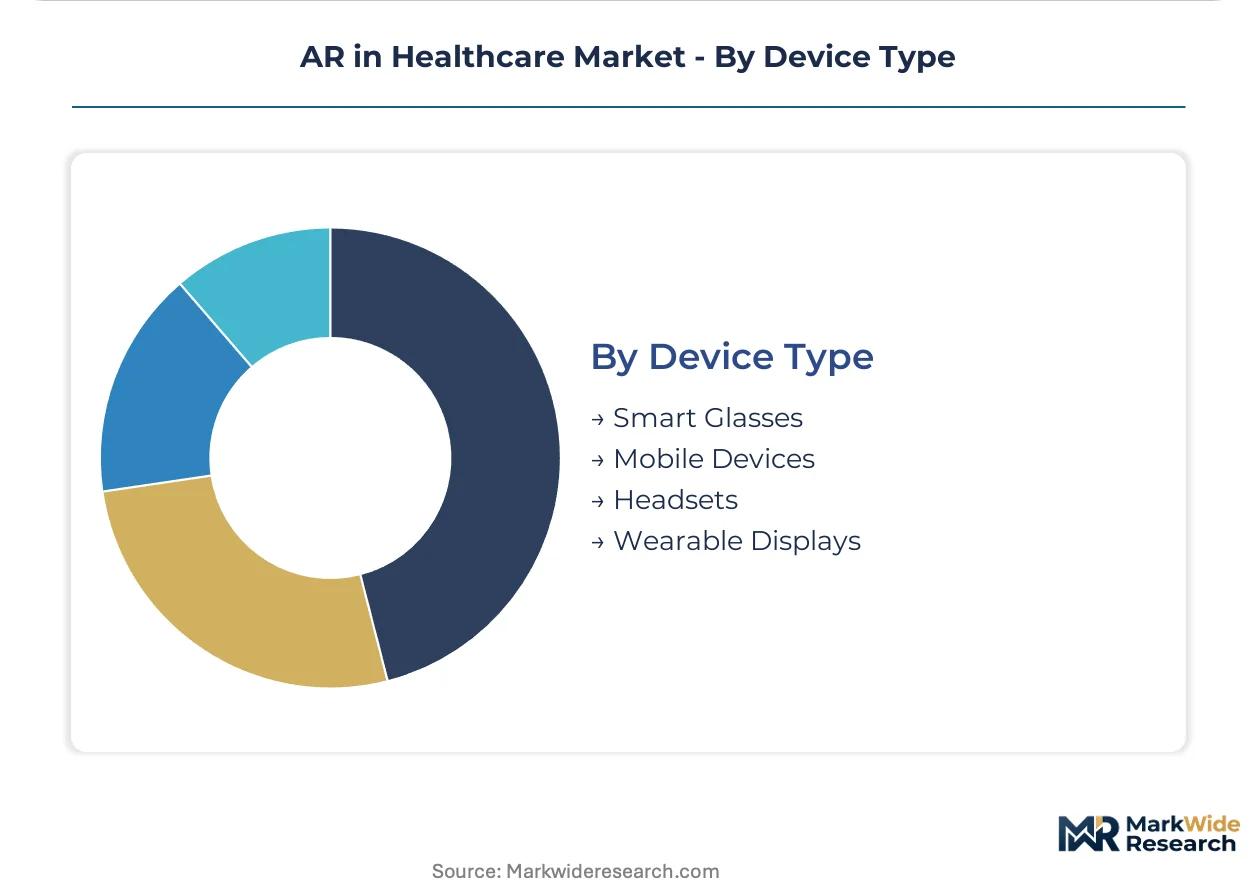
- Smart Glasses:Optical see-through displays enable hands-free operation during lengthy procedures. Japanese catheter labs favor lightweight designs for interventional radiology where lead apron compatibility matters. Battery life limitations restrict continuous use to 4-6 hours without hot-swapping.
- Headsets:Immersive displays with wide field-of-view dominate simulation environments where spatial presence outweighs mobility. United States medical schools deploy these for anatomy education where student cohorts rotate through scheduled sessions. Tethered configurations require dedicated facility infrastructure.
- Mobile Devices:Smartphone and tablet AR leverage existing hardware for cost-sensitive deployments.
- Wearable Displays:Chest-mounted or arm-mounted screens serve sterile field contexts where head-worn devices are impractical.
By installed base, Smart Glasses lead. By volume growth, Mobile Devices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket notification frameworks anchor the United States as the dominant geography, while EMA Medical Device Regulation and Japan PMDA pathways shape multi-territory commercialization timelines for AR surgical systems.
United States
Hospital systems in the United States prioritize surgical visualization platforms that align with existing CPT reimbursement codes. FDA 510(k) pathway maturation accelerates pilot-to-deployment transitions for optical see-through devices. Academic medical centers in Boston and the San Francisco Bay Area deploy hybrid operating rooms with AR integration at twice the pace of community hospitals.
Germany
German university hospitals favor marker-based tracking systems for orthopedic navigation where bone-implant alignment tolerances are tightest. EMA MDR conformity assessment obligations extend to software-driven visualization tools, creating compliance burdens that delay product launches. The catheter labs of Heidelberg and Munich retrofit suites with AR overlay capabilities for complex vascular procedures.
Japan
Japanese health systems digitize surgical workflows through PMDA fast-track designations for intraoperative navigation systems. METI funding programs support 5G-enabled telementoring networks that extend specialist reach to rural hospitals. Tokyo and Osaka medical centers anchor enterprise AR deployments where surgical visualization integrates with existing imaging archives.
United Kingdom
United Kingdom teaching hospitals reconfigure surgical training infrastructure around immersive visualization platforms. MHRA regulatory alignment with EMA MDR creates parallel compliance requirements for multi-territory vendors. London and Cambridge medical schools refresh simulation equipment every 3-4 years as graphics fidelity improves.
South Korea
South Korean health systems adopt smart glasses for interventional radiology where lead apron compatibility matters. MFDS medical device review pathways maintain distinct but converging standards for optical see-through displays. Seoul Capital Area hospitals consolidate vendor relationships around enterprise AR platforms rather than fragmented point solutions.
AR in Healthcare Market Vendor Landscape
Capability concentration sits with specialized medical imaging vendors; scale advantage sits with diversified technology conglomerates. The market structure divides between hardware-anchored ecosystems and software-centric navigation platforms. Three archetypes dominate: enterprise technology providers with existing hospital relationships, dedicated healthcare AR specialists with regulatory expertise, and medical device incumbents extending into visualization overlays. Competitive moves center on strategic partnerships for interoperability certification and portfolio diversification into adjacent rehabilitation applications.
Among diversified technology providers, Microsoft Corporation exemplifies the hardware-ecosystem archetype through its enterprise-grade medical deployments. Siemens Healthineers occupies a position representing the medical device incumbent vector with deep R&D intensity in image-guided therapy systems. Koninklijke Philips anchors the specialized interventional suite tier, combining augmented visualization with catheter navigation capabilities.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Siemens Healthineers |
| Koninklijke Philips |
| Google LLC |
| Magic Leap |
| CAE Healthcare |
| EchoPixel |
| AccuVein |
| XRHealth |
| Others |
Supply Flow & Price Mechanics
East Asian waveguide and microdisplay manufacturing clusters concentrate upstream optical component supply, anchoring margin capture in head-mounted display assembly tiers while downstream hospital procurement committees extract value through extended service contracts and calibration bundling.
Pricing Analysis
Japanese and German hospital systems pay 15-25% premiums for FDA-cleared and CE-marked navigation platforms relative to United States community hospital pricing. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service intensity. Cost compression in standard-tier hardware is intensifying because GPU architecture commoditization erodes specialized medical device premiums. Medical training institutions exhibit highest price sensitivity due to grant funding volatility, while integrated delivery networks in Japan demonstrate lowest sensitivity through 5-7 year exclusive contracting authority.
Supply Chain Analysis
Foxconn, Pegatron, and Jabil hold dominant contract manufacturing capacity for AR headset assembly across medical and consumer verticals. Taiwan, South Korea, and Japan concentrate waveguide lithography and microdisplay fabrication. Raw material dependencies center on gallium nitride substrates, rare-earth phosphors, and specialized optical polymers. Single-source vulnerability in diffractive waveguide etching equipment creates procurement risk for second-tier device vendors. Distribution runs through direct enterprise sales teams for hospital systems and specialized medical device distributors for simulation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on DICOM-RT and HL7 FHIR interoperability certification, which collapses vendor fragmentation into enterprise-scale ecosystem winners as integrated delivery networks consolidate purchasing authority.
For Market Incumbents: Build regulatory clearance moats through simultaneous FDA 510(k) and EMA MDR submission pipelines to compress multi-territory launch timelines. Deepen backward integration into optical waveguide manufacturing to reduce East Asian single-source exposure. Defend against software-only entrants by bundling hardware refresh cycles with EMR integration services that hospital biomedical engineers cannot replicate internally.
For New Entrants and Emerging Players: Prehospital emergency medicine in United States ambulance services represents the most penetrable entry point given minimal incumbent footprint and emerging reimbursement pilot structures. Physical therapy rehabilitation in German statutory health insurance networks offers parallel white-space access through faster reimbursement code stabilization than surgical categories. Go-to-market through GPO contracts managers at mid-tier integrated delivery networks bypasses entrenched relationships at academic medical centers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical navigation specialists facing EMA MDR compliance cost overruns and delayed revenue recognition. Long-term viability over the analysis window favors platforms with installed base conversion capability rather than point-solution hardware vendors. Monitor Japan PMDA fast-track designation velocity as inflection indicator for regulatory pathway efficiency arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates hospital pilot-to-deployment transitions for optical see-through surgical devices in United States tertiary centers. |
| CE Marking Pathway | Unlocks German and United Kingdom procurement cycles under EMA MDR conformity assessment obligations for software-driven tools. |
| Hospital System Partnership | Secures 5-7 year exclusive contracts with integrated delivery networks seeking standardization across subspecialty departments. |
| Software Companion Development | Enables DICOM-RT and HL7 FHIR conformance that extends implementation timelines but locks in EMR integration revenue streams. |
| Reimbursement Strategy | Aligns AR-assisted procedures with existing CPT codes to preserve physician billing workflows and accelerate capital allocation. |
Methodological Framework
The analysis maps surgical visualization, medical training, rehabilitation, and patient education sub-sectors, each validated through hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up demand modeling and top-down market sizing triangulate volume and value outputs.
Assumptions held fixed include regulatory pathway timelines for FDA, EMA, and PMDA clearance; varied assumptions encompass 5G infrastructure deployment pace and health system capital equipment refresh cycles. Segmentation dimensions modeled span technology type, end user category, application workflow, and device form factor across the analysis window. CAGRs derive from procedure volume growth, hardware replacement cycles, and service contract expansion rates. Forecast inputs incorporate surgical error rate reduction evidence and training curve compression metrics from academic medical center deployments.
Practitioners should monitor reimbursement authority classification decisions and optical component supply chain disruptions for early signals of forecast revision. Quarterly review of FDA 510(k) clearance velocity and Japan PMDA fast-track designation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Mobile Infrastructure Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Construction Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Virtual Reality Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Virtual Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Fitting Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
AR/VR Chip Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive AR and VR Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Learning Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Automotive Augmented Reality (AR) HUD System Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market