
 Virtual Reality Content Creation Market | 2026-2036
Virtual Reality Content Creation Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Reality Content Creation Market Intelligence
Photorealistic rendering fidelity is unwinding across the Virtual Reality Content Creation landscape as studios race to meet enterprise expectations. Meta leverages its hardware-software integration to anchor development pipelines for immersive experiences. Schell Games specializes in interactive narrative systems that differentiate its portfolio within training simulations. Arcturus Studios controls volumetric video capture workflows that extend its reach into live-event VR production.
Virtual Reality Content Creation encompasses the design, development, and optimization of immersive digital environments rendered at 90 frames per second or higher to eliminate motion sickness, serving industries that require spatial presence for training, entertainment, or therapeutic intervention. Video games occupy the largest revenue pool among content types, though training simulations capture margin concentration as defense and aviation buyers prioritize certification-grade fidelity. Game engines sustain the fastest expansion within technology segments, while motion capture systems retain premium pricing due to hardware complexity and calibration expertise.
FCC guidelines on broadcast spectrum allocation shape wireless VR streaming capabilities in the United States, while GDPR and the EU AI Act constrain biometric data collection and synthetic media disclosure across European deployments. ISO standards for ergonomic headset design influence hardware compatibility requirements that content creators must address. Stakeholders must weigh regulatory fragmentation against the technical cost of building multi-jurisdiction compliance into asset pipelines.
Market Dynamics
Enterprise buyers now mandate 90 frames-per-second rendering thresholds to eliminate simulator sickness, forcing studios to rebuild asset pipelines around real-time ray tracing rather than pre-baked lighting. This technical floor is compressing margins for mid-tier developers while concentrating contract awards among firms with captive motion-capture stages.
Growth Catalysts
- EU AI Act disclosure mandates:Synthetic media labeling requirements in Europe are generating demand for provenance-tracking tools that authenticate VR training footage origin.
- Defense aviation certification:FAA and EASA simulator qualification standards are pulling photorealistic cockpit environments into mandatory procurement cycles for pilot retraining.
- Neuromodulation therapy:Pain management clinics in Germany and Japan are reimbursing VR exposure protocols for chronic condition treatment.
Market Restraints
- GPU allocation scarcity:Foundry capacity constraints for high-end graphics processors are extending lead times for render farm expansion.
- Optical component concentration:Pancake lens manufacturing clusters in Taiwan create single-source vulnerability for headset display stacks.
- Biometric data friction:GDPR pupil-tracking restrictions limit gaze-contingent rendering deployment across European healthcare installations.
Strategic Opportunities
- India PLI scheme:Domestic electronics manufacturing incentives are attracting VR hardware assembly that seeds localized content studios.
- Neural haptic convergence:Integration of EMG wristbands with force-feedback gloves is opening rehabilitation application contracts.
- Saudi giga-project entertainment:Qiddiya and Red Sea tourism developments are tendering immersive historical reconstruction experiences.
Industry Challenges
- Unreal Engine specialization shortage:Blueprint visual scripting expertise commands premium wages that inflate project labor costs.
- ISO 9241-307 ergonomic certification:Headset comfort testing protocols add months to hardware-software integration timelines.
- Cross-platform asset fragmentation:Meta's proprietary shader formats conflict with OpenXR standards, forcing redundant development tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Reality Content Creation Market |
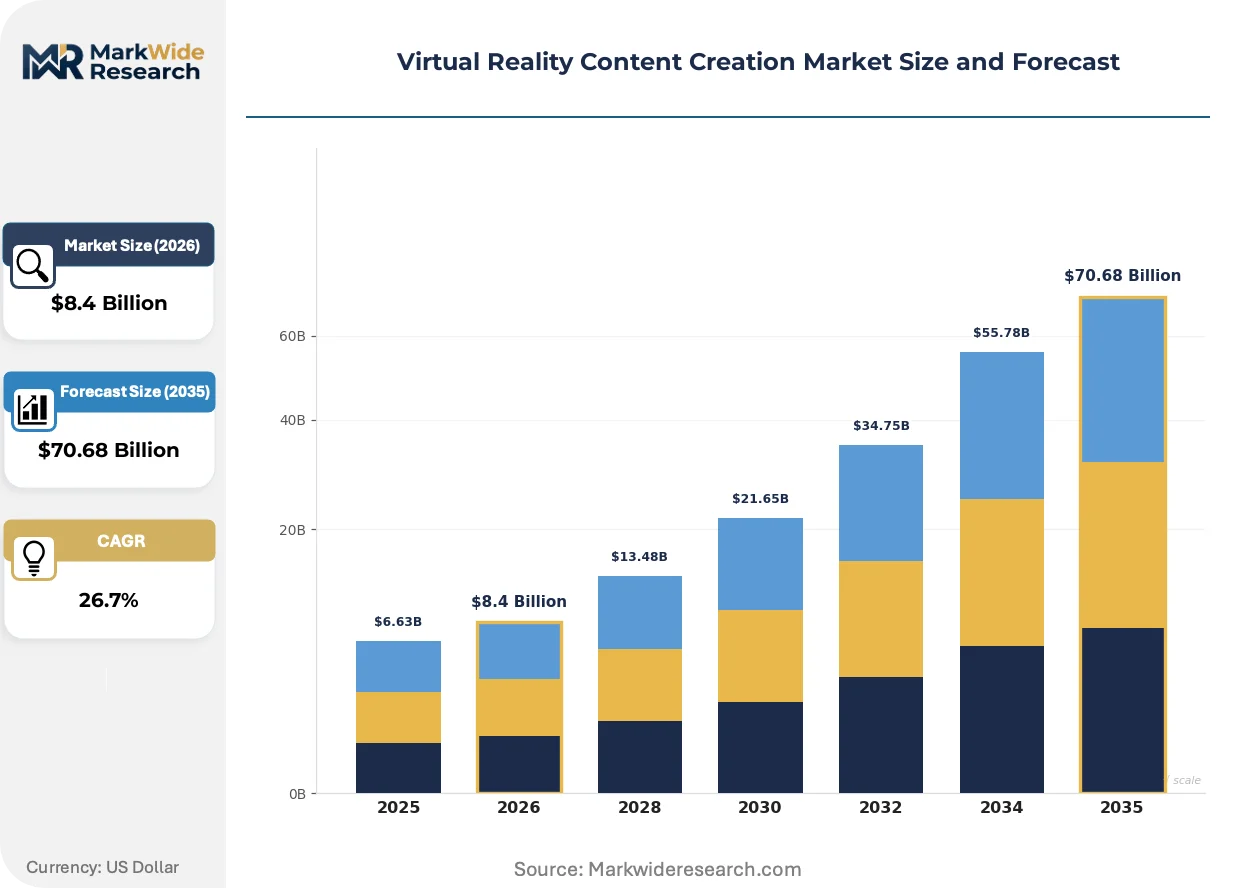
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $70.68 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Video Games, Training Simulations, Educational Content, Marketing Experiences End User: Enterprises, Educational Institutions, Entertainment Industry, Healthcare Professionals Technology: 3D Modeling Software, Game Engines, Motion Capture Systems, VR Headsets Distribution Channel: Direct Sales, Online Platforms, Licensing, Partnerships |
| Companies Covered | Treeview, Arcturus Studios, Meta, ForeVR Games, Penrose, Felix & Paul Studios, Takeaway Reality, Talespin Reality Labs, Schell Games, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Reality Content Creation Market Strategic Shifts & Innovations
Neural rendering pipelines are compressing production cycles from months to weeks, altering how studios staff technical art departments and bid on fixed-price contracts. This acceleration is redistributing competitive advantage toward firms with in-house AI research capacity.
Gaussian splatting is supplanting traditional polygon mesh workflows for static environment reconstruction. Archaeological visualization teams at British museums are adopting radiance field techniques to digitize heritage sites without photogrammetry crews. The method is compressing location shoot budgets while enabling six-degrees-of-freedom exploration of spaces previously limited to 360-degree video.
The EU AI Act's synthetic media disclosure requirements are mandating embedded metadata standards for AI-generated textures and voice synthesis. German automotive training providers must now watermark procedurally generated instructor avatars. This compliance layer is favoring studios with established digital asset management infrastructure over garage operators.
Hospital procurement departments are unbundling VR content licensing from hardware lease agreements, forcing developers to price software subscriptions independently of Meta or Pico headset bundles. This shift is visible most acutely in United States health systems where IT governance committees now separate capital equipment from operating expenditure budgets for therapeutic applications.
Virtual Reality Content Creation Market Segmentation
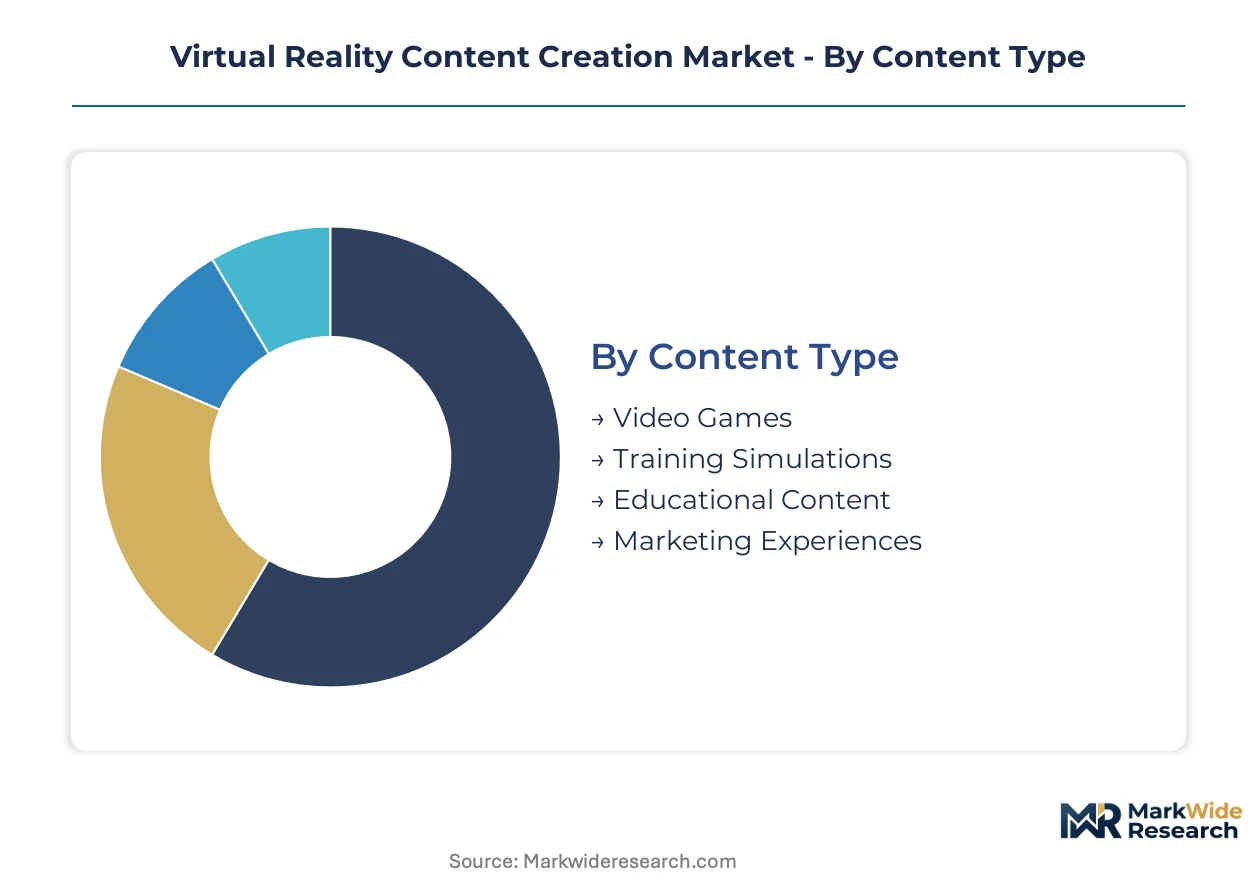
Segmentation in VR content creation reveals how technical requirements diverge across use cases. Defense contractors demand certification-grade fidelity that consumer entertainment cannot substitute. Healthcare procurement separates software licensing from hardware leases, reshaping vendor economics.
Content Type:
Training simulations face acute substitution pressure from lower-fidelity screen-based modules, while immersive entertainment maintains irreplaceable spatial presence advantages.
- Video Games:Real-time engines render interactive worlds at 90 frames per second minimum. Demand concentrates in the United States where Meta Quest storefronts dominate consumer distribution. This segment retains volume leadership.
- Training Simulations:FAA and EASA certification standards mandate photorealistic cockpit environments with haptic feedback integration. Defense and aviation buyers in Germany and Japan prioritize retraining module procurement. This segment holds the steepest expansion curve.
- Educational Content:Museums and universities deploy radiance field techniques for heritage site digitization.
- Marketing Experiences:Brand activations leverage volumetric capture for transient event deployments.
Video games retain volume leadership; training simulations hold the steepest expansion curve.
End User:
Enterprise buyers now separate capital equipment from operating expenditure budgets, compressing margins for bundled hardware-software offerings.
- Enterprises:Procurement committees mandate ISO 9241-307 ergonomic compliance before headset deployment. Manufacturing and logistics operators in the United States drive demand for warehouse safety training modules.
- Healthcare Professionals:Pain management clinics in Germany and Japan reimburse VR exposure protocols for chronic condition treatment. GDPR pupil-tracking restrictions constrain gaze-contingent rendering deployment across European installations.
- Educational Institutions:British museums adopt Gaussian splatting for six-degrees-of-freedom heritage exploration.
- Entertainment Industry:Live-event producers in Saudi Arabia tender immersive historical reconstruction contracts for giga-project developments.
Enterprises dominate current procurement volume; healthcare professionals are climbing the fastest as reimbursement frameworks mature.
Technology:
Game engines displace standalone 3D modeling workflows as real-time rendering becomes the default production pipeline.
- Game Engines:Unreal Engine Blueprint visual scripting commands premium wages that inflate project labor costs. Real-time ray tracing pipelines now replace pre-baked lighting across enterprise contract bids.
- Motion Capture Systems:Hardware complexity and calibration expertise retain premium pricing. Captive motion-capture stages concentrate contract awards among integrated studios.
- 3D Modeling Software:Traditional polygon mesh workflows face displacement by neural rendering pipelines.
- VR Headsets:Pancake lens manufacturing clusters in Taiwan create single-source vulnerability for display stack supply.
Game engines command the broadest adoption base; motion capture systems maintain the highest margin structure.
Distribution Channel:
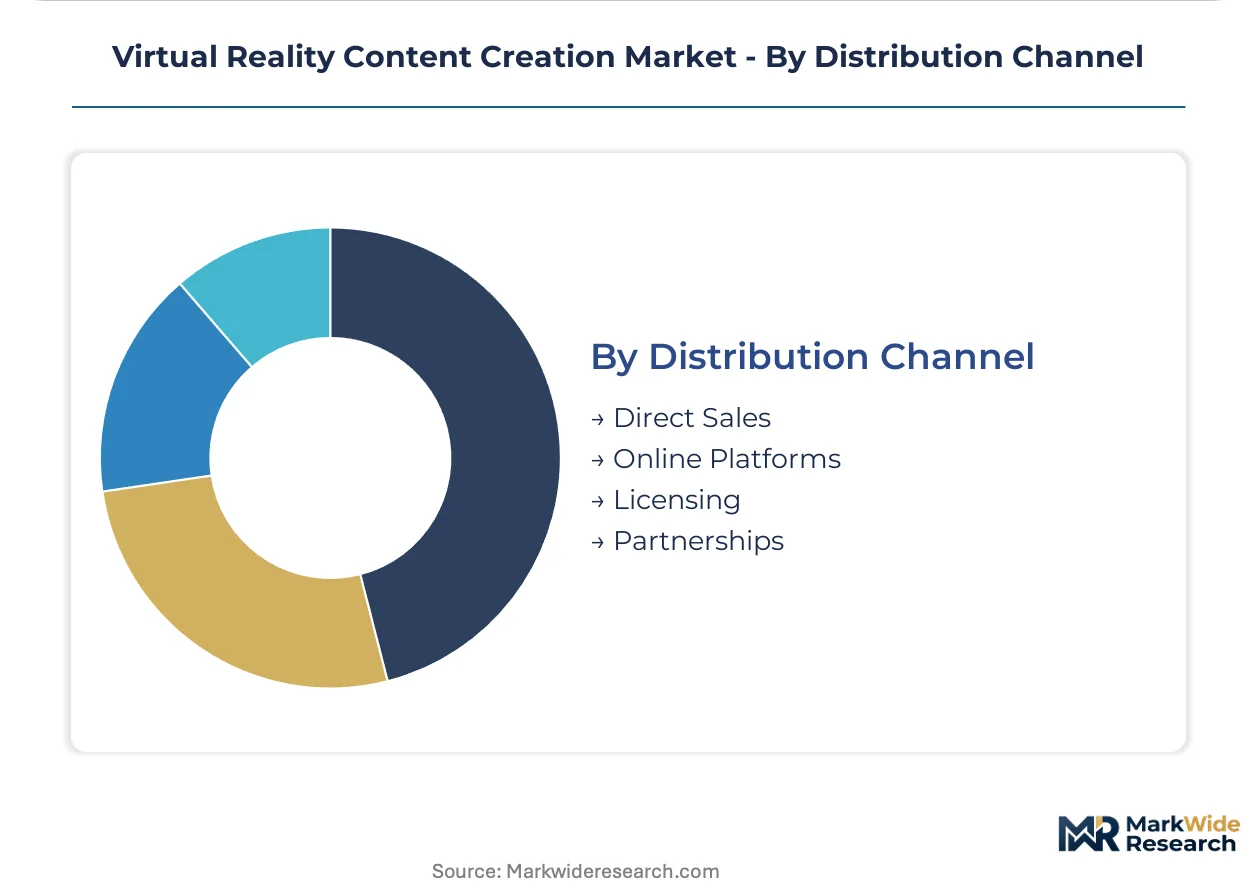
Direct sales relationships dominate high-value enterprise contracts while online platforms fragment consumer revenue capture.
- Direct Sales:Defense and aviation certification requirements necessitate bespoke development relationships. FAA simulator qualification standards pull studios into multi-year procurement cycles.
- Licensing:Hospital IT governance committees now separate software subscriptions from hardware lease agreements. Independent pricing forces developers to build recurring revenue models.
- Online Platforms:Meta Quest storefronts concentrate consumer game distribution.
- Partnerships:Saudi giga-project tenders require joint venture structures for immersive experience delivery.
Direct sales retain the highest contract value concentration; licensing is gaining share fastest as healthcare procurement unbundles hardware and software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in VR content creation tilt toward services outflow from the United States and Germany toward Saudi Arabia and Japan, where localized production capacity remains underdeveloped. Software licensing revenue flows predominantly from North American and European studios toward Asian healthcare and defense buyers.
United States
Enterprise procurement committees at Boeing and Lockheed Martin drive demand for FAA-certified cockpit simulations. FCC spectrum allocation rules for 6 GHz bands enable untethered VR streaming in warehouse training deployments. Seattle and Los Angeles host the densest concentrations of Unreal Engine technical art talent, where Schell Games and Meta maintain captive development pipelines.
Germany
Pain management clinics in Munich and Hamburg now reimburse VR exposure therapy under statutory health insurance frameworks. The EU AI Act mandates synthetic media watermarking for all procedurally generated training avatars, forcing studios to rebuild asset management systems. Stuttgart automotive clusters source photorealistic assembly simulations from domestic content houses to avoid cross-border data transfer complications.
Japan
METI subsidies for digital therapeutics accelerate hospital procurement of neuromodulation VR protocols for chronic pain and stroke rehabilitation. JIS ergonomic standards for headset weight distribution constrain hardware-software integration timelines for foreign vendors. Tokyo and Osaka development studios specialize in anime-styled immersive entertainment for export to Southeast Asian markets.
Saudi Arabia
Qiddiya and Red Sea giga-project tenders require immersive historical reconstructions that exceed domestic production capacity, pulling European and American studios into joint venture structures. SFDA medical device classification rules for therapeutic VR systems create compliance bottlenecks for imported software. Riyadh-based localization teams adapt foreign content for Arabic-language deployment in entertainment and training verticals.
India
PLI scheme incentives for electronics manufacturing attract VR hardware assembly operations that seed adjacent content studios in Bengaluru and Hyderabad. BIS certification requirements for imported headsets delay software bundling agreements with international developers. Domestic IT services firms in Pune and Chennai are building captive VR training modules for internal deployment and eventual export to Gulf markets.
Virtual Reality Content Creation Market Key Industry Players
Concentration sits with hardware-integrated platforms and specialized training studios rather than pure-play content houses. The vendor base spans three tiers: captive studios owned by headset manufacturers, independent developers with motion-capture infrastructure, and boutique shops serving single verticals. Strategic moves center on M&A for volumetric capture capabilities and exclusive licensing deals for defense aviation certification.
Within the hardware-integrated tier, Meta anchors development through its Quest ecosystem control. Among independent specialists, Schell Games exemplifies the training simulation archetype with its interactive narrative systems, while Arcturus Studios occupies a position in volumetric video workflows for live-event production. These three entities represent the dominant competitive anchors around which mid-tier studios must differentiate.
| Leading Market Players |
|---|
| Treeview |
| Arcturus Studios |
| Meta |
| ForeVR Games |
| Penrose |
| Felix & Paul Studios |
| Takeaway Reality |
| Talespin Reality Labs |
| Schell Games |
| Others |
Cost & Logistics Intelligence
Project-based capacity reservation contracts dominate enterprise VR content procurement, locking United States defense contractors into multi-year development cycles with fixed-price milestones that guarantee motion-capture stage access while capping exposure to GPU render farm cost volatility.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing across healthcare and aviation training verticals, where FAA certification-grade fidelity commands premium positioning against standard entertainment modules. Price differentiation separates ISO 9241-307 ergonomic compliance tiers from uncertified consumer deployments, while cost compression in mid-tier development intensifies as Unreal Engine Blueprint specialists capture wage premiums. Hospital procurement committees exhibit acute price sensitivity when unbundling software licenses from Meta headset leases, whereas defense aviation buyers demonstrate inelastic demand for cockpit simulator fidelity.
Supply Chain Analysis
Strategic stockpile preferences for pancake lens modules and high-bandwidth memory components dominate headset manufacturing, with Taiwan, South Korea, and Japan anchoring optical component supply. Raw material dependencies center on gallium nitride substrates, rare-earth magnet arrays, and specialized polymer films for pancake lens stacks. Single-source vulnerability in Taiwan's display component clusters creates tariff exposure chokepoints for United States hardware assemblers. Distribution runs through direct sales relationships for enterprise certification contracts, while online platform storefronts fragment consumer game revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Virtual Reality Content Creation sits within early-cycle expansion as enterprise procurement committees at Boeing and Lockheed Martin institutionalize FAA-certified training modules, with reimbursement frameworks in German and Japanese pain management clinics accelerating healthcare vertical penetration.
For Market Incumbents: Secure captive motion-capture infrastructure through backward integration into volumetric video stages, insulating contract awards from mid-tier studio competition while building proprietary shader libraries that reduce OpenXR standardization friction. Certification investment in EU AI Act-compliant provenance-tracking tools defends position against emerging synthetic media disclosure mandates.
For New Entrants and Emerging Players: Lead with radiance field technique specialization for archaeological and heritage visualization contracts, where British museum procurement lacks incumbent saturation and Gaussian splatting expertise remains scarce. Target Saudi giga-project joint venture structures as the most penetrable geography, leveraging European studio partnerships for Qiddiya historical reconstruction tenders.
For Investors and Strategic Acquirers: Studios with integrated AI research capacity and established digital asset management infrastructure represent priority acquisition targets, positioned to capture neural rendering pipeline acceleration and EU synthetic media compliance layering. Long-term viability hinges on 5-10 year enterprise subscription retention as healthcare unbundling matures. The signal to watch is hospital IT governance committee separation of capital equipment from operating expenditure budgets reaching critical mass in United States health systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Neural Rendering Pipeline Investment | Compression of production cycles from months to weeks redistributes competitive advantage toward AI-capable studios. |
| EU AI Act Compliance Infrastructure | Embedded metadata standards for synthetic media watermarking favor studios with established digital asset management systems. |
| Motion-Capture Stage Acquisition | Captive volumetric video infrastructure concentrates contract awards among integrated studios serving defense aviation certification. |
| Healthcare Licensing Unbundling | Independent software subscription pricing builds recurring revenue models as hospital procurement separates capital from operating expenditure. |
| Saudi Joint Venture Formation | Qiddiya and Red Sea giga-project tenders pull European and American studios into localized partnership structures for Arabic-language deployment. |
Research Approach
A spread of perspectives from VR studio technical directors, healthcare procurement managers at German pain clinics, defense aviation training officers, and FCC regulatory affairs leads converged on the working assumptions that shape this analysis. Primary fieldwork combined with secondary validation from SEC filings of hardware-integrated platforms, EASA simulator qualification documentation, EU AI Act implementation guidance, and hospital GPO contract databases. Bottom-up project pipeline assessment and top-down market sizing triangulated volume estimates across the analysis window.
Segmentation dimensions modeled include content type, end-user vertical, underlying technology stack, and distribution channel structure, with additional granularity on certification tier and reimbursement status for healthcare applications. CAGRs were derived from fitted growth curves calibrated to disclosed contract values and procurement cycle visibility. Industry-specific forecast inputs incorporated FAA and EASA simulator qualification pipeline data, METI digital therapeutics subsidy disbursement rates, and Saudi giga-project tender publication timelines.
The analysis sits within stated boundaries; outcomes outside sustained enterprise VR deployment acceleration, stable foundry capacity for high-end GPU allocation, or continued reimbursement framework expansion in German and Japanese healthcare would require recalibration. Forecasts reflect documented assumptions regarding certification standard harmonization and hardware-software unbundling velocity. Revision becomes warranted when EU AI Act enforcement intensity or Taiwan optical component supply disruption crosses materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR Collaboration Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Canada Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
VR All-In-One Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
5G and Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Prototype Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Mirror Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Training Market
Virtual Reality (VR) and Augmented Reality (AR)
India Desktop Virtualization Market
Virtual Reality (VR) and Augmented Reality (AR)
Italy Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Solutions Market
Virtual Reality (VR) and Augmented Reality (AR)
Middle East Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR and VR in Training Market
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
UK Metaverse Market