
 Genomic Biomarkers Market | 2026-2036
Genomic Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Genomic Biomarkers Market Analysis
Companion diagnostic licensing revenue is reconfiguring margin pools away from standalone test sales toward integrated therapy-test partnerships. QIAGEN leverages its sample-to-insight platform to control pre-analytical workflows across clinical and research channels. Thermo Fisher Scientific anchors its position through end-to-end NGS instrument and consumable ecosystems that lock in recurring revenue streams. Illumina dominates sequencing hardware installed base, though its recent strategy shifts reflect competitive pressure from emerging platform vendors.
Genomic biomarkers are DNA, RNA, protein, or epigenetic signatures detectable through molecular assays that indicate normal biological processes, pathogenic states, or pharmacologic responses to therapeutic intervention; these markers typically require nucleic acid extraction, amplification, and detection platforms operating at analytical sensitivities reaching single-digit variant allele frequencies. DNA markers and NGS technology command the largest current revenue share due to established reimbursement for solid tumor profiling, while epigenetic biomarkers represent the fastest-expanding segment as methylation-based liquid biopsy applications gain clinical traction in early cancer detection. Oncology applications absorb the majority of commercial investment, though cardiovascular genomic testing is emerging as a secondary growth corridor driven by polygenic risk score integration into preventive care protocols.
FDA biomarker qualification programs and EMA's parallel scientific advice pathways shape clinical trial design and companion diagnostic co-development requirements, directly determining which genomic tests achieve regulatory acceptance and payer coverage. The EU AI Act and GDPR impose additional algorithmic transparency and data governance obligations on machine learning-based biomarker interpretation tools deployed in European clinical settings. Stakeholders must monitor evolving payer evidence requirements, as health technology assessment bodies tighten criteria for demonstrating clinical utility beyond analytical validity.
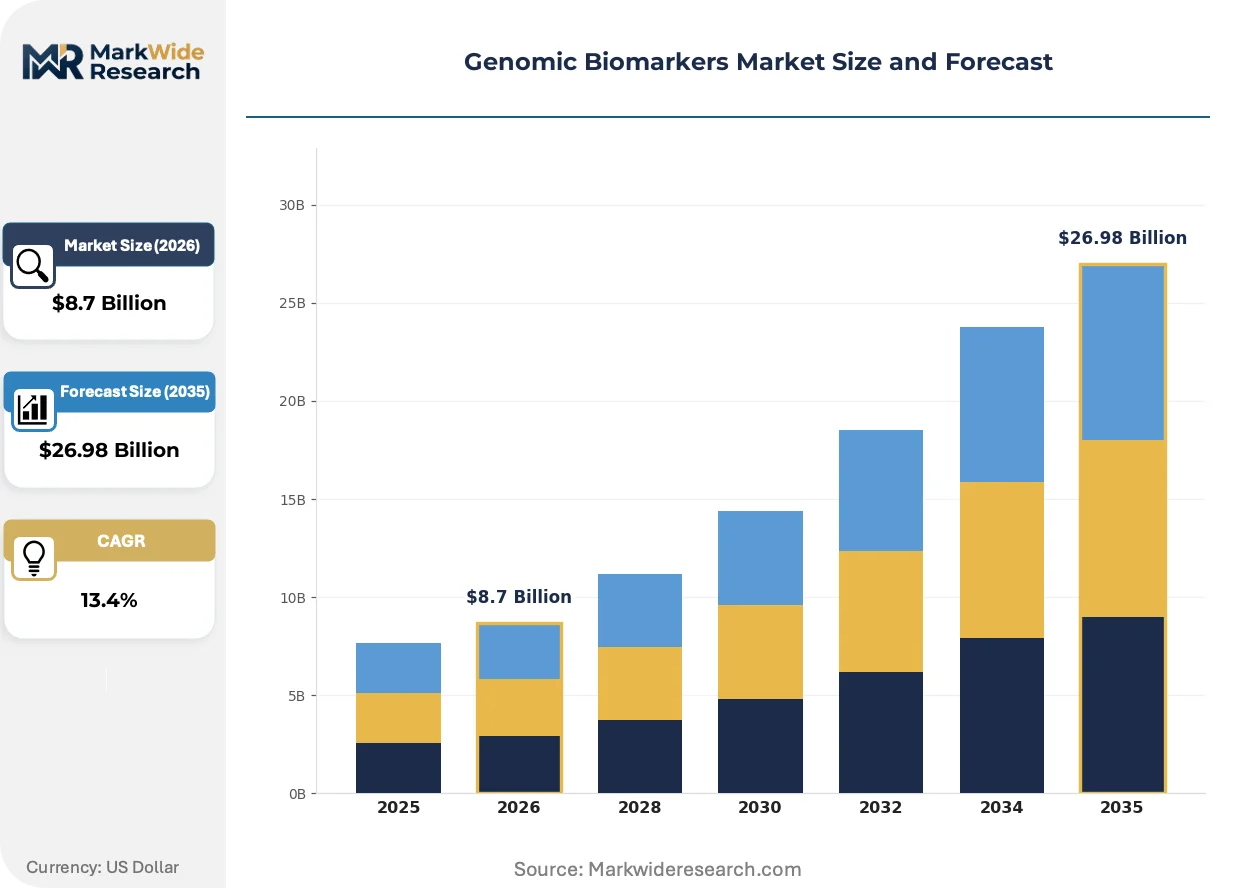
Market Dynamics
Companion diagnostic co-development requirements are compressing traditional R&D timelines, forcing pharmaceutical sponsors to integrate biomarker strategies into Phase I trial designs rather than retrofitting them post-hoc.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for liquid biopsy assays accelerate clinical validation timelines and de-risk capital deployment for test developers targeting oncology indications.
- Medicare Coverage Determinations:National coverage decisions for molecular diagnostic tests establish immediate addressable patient populations and reduce commercial uncertainty for assay manufacturers.
- NGS Platform Miniaturization:Benchtop sequencing systems reduce capital barriers for community hospital laboratories, expanding test access beyond academic medical center networks.
Market Restraints
- Reagent Supply Concentration:Polymerase and nucleotide raw material production clusters in Germany and the United States, creating vulnerability to single-source disruptions.
- Analytical Validity-Efficacy Gap:Payer bodies require prospective clinical utility data that exceeds FDA clearance standards, extending reimbursement timelines by 18-36 months.
- Variant Interpretation Bottleneck:Shortage of board-certified molecular pathologists constrains report generation capacity for high-complexity somatic profiling tests.
Strategic Opportunities
- Pharmacogenomic Expansion:Psychiatric medication response prediction represents an underpenetrated application segment with limited current test competition.
- EU AI Act Compliance Services:Algorithmic transparency requirements for machine-learning variant classification tools create advisory revenue streams for quality system consultants.
- Direct-to-Consumer Channel:Wellness-oriented polygenic risk score products bypass traditional clinical distribution through subscription genetic testing platforms.
Industry Challenges
- Bioinformatics Talent Scarcity:Pipeline variant scientists with dual training in molecular biology and computational statistics command premium compensation, inflating operational costs.
- LIMS Integration Complexity:Legacy laboratory information management systems require custom API development to accommodate NGS data volumes, delaying test launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genomic Biomarkers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Markers, RNA Markers, Protein Markers, Epigenetic Biomarkers Technology: NGS, PCR, Microarray, Mass Spectrometry Application: Oncology, Cardiovascular, Infectious Diseases, Neurology End User: Pharmaceuticals, Research Institutions, Diagnostic Laboratories, Biotech Companies |
| Companies Covered | QIAGEN, Eurofins Scientific, Thermo Fisher Scientific, Exact Sciences, Guardant Health, Roche, Myriad Genetics, Invitae, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genomic Biomarkers Market Emerging Trajectories
Cloud-based variant interpretation is collapsing the traditional hardware-software boundary in molecular diagnostics, enabling distributed analysis workflows that decouple sequencing from clinical decision support.
Multiplexed methylation detection platforms are virtualizing tissue-of-origin identification for cancers of unknown primary, replacing sequential immunohistochemistry staining panels with single-tube molecular assays. Community pathology laboratories in the United States are adopting these systems to retain oncology specimen referrals that previously transferred to academic centers. The technology is virtualizing diagnostic service line economics by compressing turnaround times from fourteen days to seventy-two hours.
EMA's parallel scientific advice mechanism now coordinates biomarker qualification with FDA pre-submission pathways, harmonizing evidentiary requirements for transatlantic companion diagnostic submissions. Pharmaceutical sponsors receive synchronized feedback on analytical validation plans, reducing protocol amendment rates. Oncology therapeutic areas with concurrent FDA-EMA filings report streamlined development timelines compared to sequential regulatory strategies.
Payers are unbundling technical component reimbursement from professional interpretation fees, forcing laboratories to justify molecular pathology charges through discrete documentation of physician consultation time. United States commercial insurers lead this decomposition, with Medicare Advantage plans adopting similar claims editing protocols. Independent clinical laboratories face margin compression as professional component rates reset downward toward pathology consultation benchmarks.
Genomic Biomarkers Market Segmentation
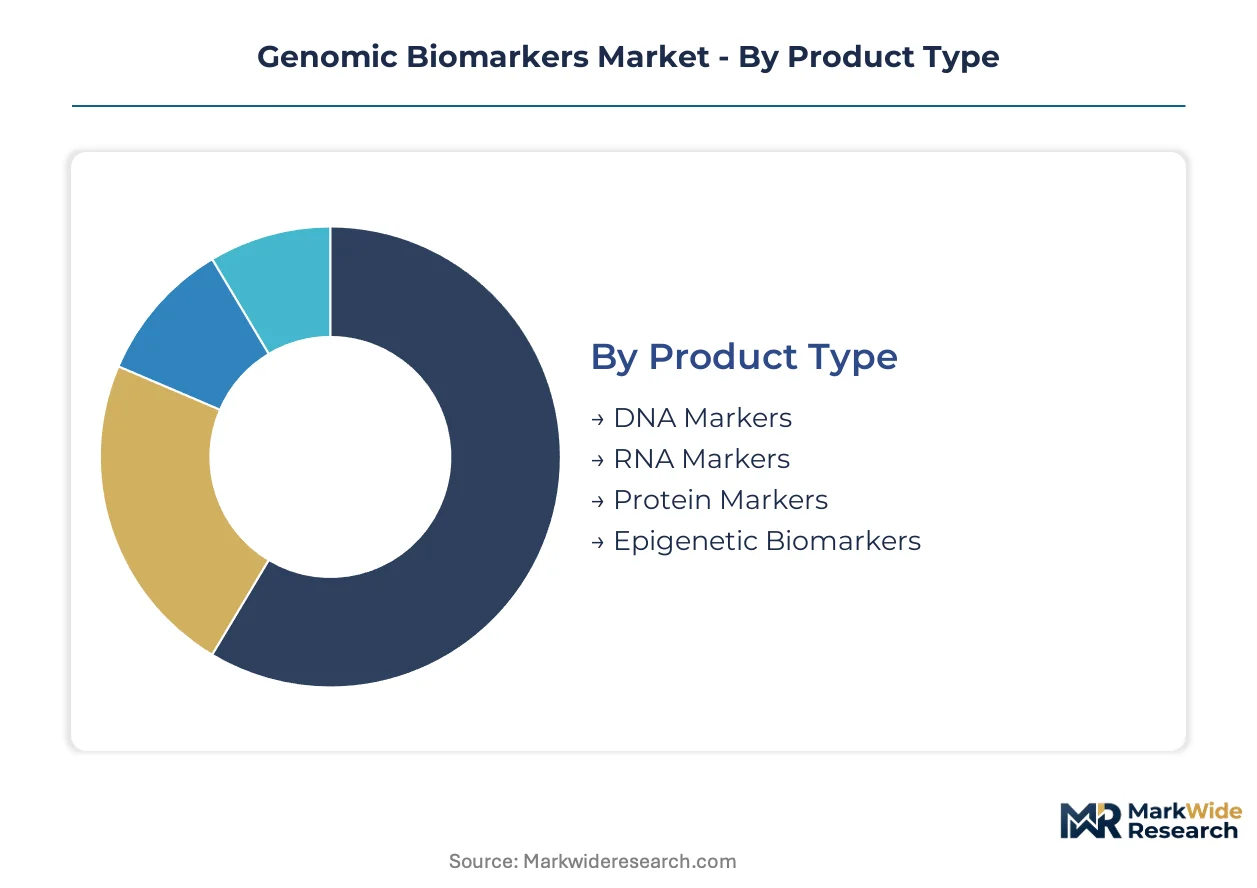
Genomic biomarker segmentation reveals divergent margin structures across molecular assay categories. Technology-platform pairings determine reimbursement pathways and capital intensity requirements for test developers.
Product Type:
Cost tier stratification separates high-complexity sequencing-based markers from lower-cost immunoassay alternatives, with reimbursement codes clustering around technical difficulty.
- DNA Markers:Somatic mutation panels and germline variant tests detect single nucleotide changes, copy number alterations, and structural rearrangements through hybridization capture or amplicon sequencing. Solid tumor profiling in United States academic medical centers absorbs the majority of commercial DNA marker volume, driven by Medicare coverage for comprehensive genomic profiling in advanced cancers.
- Epigenetic Biomarkers:DNA methylation signatures and histone modification patterns enable tissue-of-origin identification and minimal residual disease monitoring without tumor tissue. Liquid biopsy applications in early cancer detection are expanding fastest as methylation-specific PCR and bisulfite sequencing costs decline below tissue biopsy alternatives.
- RNA Markers:Gene expression signatures and fusion transcript detection classify tumor subtypes and predict therapeutic response through quantitative PCR or transcriptome sequencing.
- Protein Markers:Post-translational modification states and protein quantification provide functional readouts that complement nucleic acid measurements in multiplexed assay panels.
DNA markers hold installed capacity. Epigenetic biomarkers are rotating up the share rankings.
Technology:
Application specificity determines platform selection, with throughput requirements and variant detection sensitivity driving capital deployment decisions.
- NGS:Next-generation sequencing platforms deliver parallel analysis of thousands of loci with analytical sensitivity to variant allele frequencies below one percent. Oncology companion diagnostic development in United States and European Union therapeutic areas concentrates NGS instrument purchases, as FDA and EMA co-development pathways require prospective clinical validation of sequencing-based assays.
- PCR:Quantitative and digital PCR systems provide rapid turnaround for targeted variant detection at lower per-sample costs than comprehensive profiling. Community hospital laboratories in United States regional markets deploy PCR-based pharmacogenomic panels for psychiatric and cardiovascular medication guidance, where reimbursement favors lower-complexity testing.
- Microarray:Hybridization-based genotyping enables high-throughput screening of known variants across large sample collections for genome-wide association studies.
- Mass Spectrometry:Matrix-assisted laser desorption and electrospray ionization methods quantify proteins and metabolites with high specificity for proteomic biomarker applications.
NGS dominates the installed base. PCR is rotating up the share rankings.
Application:
Volume concentration varies sharply across therapeutic areas, with oncology absorbing the majority of biomarker development investment and cardiovascular emerging as a secondary corridor.
- Oncology:Solid tumor profiling, hematologic malignancy classification, and minimal residual disease monitoring represent the primary revenue pool for genomic biomarker manufacturers. Companion diagnostic co-development with pharmaceutical sponsors in United States and European Union markets locks in long-term consumable revenue through therapy-test partnerships.
- Cardiovascular:Polygenic risk scores for coronary artery disease and pharmacogenomic guidance for antiplatelet therapy are gaining clinical traction in preventive care protocols. United States health systems with value-based contracting arrangements are piloting genomic risk stratification for statin therapy selection.
- Infectious Diseases:Pathogen genomic surveillance and antimicrobial resistance profiling enable targeted therapy selection in hospital-acquired infection management.
- Neurology:Cerebrospinal fluid biomarkers and blood-based assays for neurodegenerative disease classification remain in early clinical validation stages.
Oncology holds installed capacity. Cardiovascular is rotating up the share rankings.
End User:
Customer type determines procurement patterns, with pharmaceutical sponsors funding companion diagnostic development and diagnostic laboratories absorbing routine clinical testing volume.
- Pharmaceuticals:Drug developers commission biomarker discovery and companion diagnostic co-development to enable patient stratification in registrational trials. FDA breakthrough therapy designations increasingly require prospective biomarker strategies, embedding molecular diagnostic partners into oncology and immunology pipeline decisions.
- Diagnostic Laboratories:Independent and hospital-affiliated labs purchase assay kits and interpretation services for routine clinical testing. United States Medicare coverage determinations for molecular diagnostic tests directly shape laboratory purchasing decisions, as national fee schedules establish addressable patient populations.
- Research Institutions:Academic medical centers and government research programs fund biomarker discovery studies with less immediate commercial pressure than pharmaceutical applications.
- Biotech Companies:Emerging therapeutic developers leverage contract research organizations for biomarker strategy without building internal diagnostic capabilities.
Pharmaceuticals hold installed capacity. Diagnostic laboratories are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for genomic biomarkers diverge sharply across major markets. The United States concentrates investment in companion diagnostic co-development, while Germany and Japan emphasize analytical validation standards, and China scales manufacturing capacity for sequencing consumables.
United States
Medicare national coverage determinations for comprehensive genomic profiling in advanced cancers drive laboratory purchasing decisions. FDA breakthrough device designation pathways accelerate liquid biopsy assay validation timelines. The Boston-Cambridge corridor anchors pharmaceutical-sponsored biomarker discovery, with academic medical centers in New York and California absorbing the highest test volumes.
Germany
EMA parallel scientific advice mechanisms coordinate biomarker qualification with FDA pathways for transatlantic submissions. The EU AI Act imposes algorithmic transparency requirements on machine-learning variant classification tools deployed in clinical settings. The Rhine-Main biotech cluster around Frankfurt concentrates contract research organizations supporting companion diagnostic development.
China
NMPA innovation review pathways compress registration timelines for domestically developed NGS-based assays. National reimbursement catalog expansion for molecular diagnostic tests determines hospital procurement priorities. The Yangtze River Delta biopharmaceutical manufacturing base around Shanghai and Suzhou scales reagent production for regional sequencing instrument ecosystems.
Japan
PMDA sakigake designation system accelerates approval for genomic biomarker-guided therapies in oncology. METI funding programs support domestic development of methylation-based liquid biopsy platforms. The Kanto region around Tokyo concentrates hospital-based molecular pathology laboratories adopting NGS systems for solid tumor profiling.
United Kingdom
NICE technology appraisal processes determine National Health Service commissioning for genomic tests beyond analytical validity requirements. Genomics England 100,000 Genomes Project infrastructure supports population-scale biomarker discovery. The Cambridge-London life sciences corridor hosts emerging diagnostic developers targeting FDA-EMA concurrent submission strategies.
Genomic Biomarkers Market Vendor Landscape
Capability concentration sits with platform technology developers; scale advantage sits with integrated life sciences conglomerates. The market structures around three tiers: sequencing hardware specialists controlling instrument installed bases, sample-to-insight platform providers capturing pre-analytical workflows, and assay developers locking in pharmaceutical co-development partnerships. Dominant competitive moves include therapy-test partnership structures that embed diagnostic consumables into drug commercialization strategies, and vertical integration into cloud-based variant interpretation services that reduce customer switching costs.
Within the platform technology tier, Illumina and Thermo Fisher Scientific occupy positions as hardware ecosystem anchors, while QIAGEN exemplifies the sample-to-insight integration archetype. These three companies represent distinct strategic postures: instrument lock-in through consumable recurring revenue, end-to-end workflow control, and pre-analytical workflow standardization across clinical and research channels.
| Leading Market Players |
|---|
| QIAGEN |
| Eurofins Scientific |
| Thermo Fisher Scientific |
| Exact Sciences |
| Guardant Health |
| Roche |
| Myriad Genetics |
| Invitae |
| Illumina |
| Others |
Supply Flow & Price Mechanics
German polymerase and nucleotide manufacturers anchor upstream reagent supply, concentrating pricing power with sequencing consumable producers who then negotiate therapy-test partnership terms with pharmaceutical sponsors. Margin pools shift toward integrated diagnostic-therapeutic bundles as standalone assay pricing faces compression from Medicare national coverage determinations.
Pricing Analysis
Long-term companion diagnostic offtake agreements dominate pharmaceutical co-development, locking in consumable volumes across multi-year therapy commercialization cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA-breakthrough-designated liquid biopsy panels from community hospital PCR pharmacogenomic tests and research-grade screening assays. Cost compression in the standard tier intensifies because United States commercial insurers unbundle technical and professional component reimbursement. Diagnostic laboratories exhibit highest price sensitivity due to Medicare fee schedule exposure, while pharmaceutical sponsors prioritize analytical validity over unit cost.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates reagent supply risk as polymerase production clusters in Baden-Württemberg and nucleotide synthesis concentrates in Bavaria. Raw material dependencies include modified nucleotides, thermostable polymerases, and magnetic bead chemistries. Single-source vulnerability persists for methylation-specific PCR enzymes used in epigenetic liquid biopsy platforms. Distribution runs through regional sequencing instrument distributors who bundle consumable contracts with hardware maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among United States health systems with value-based contracting arrangements, consolidating laboratory purchasing decisions under centralized procurement functions. This consolidation fragments addressable markets for standalone assay vendors.
For Market Incumbents: Build regulatory moats through FDA breakthrough device designation accumulation and EMA parallel scientific advice pathway mastery. Pharmaceutical sponsors now require prospective biomarker strategies in Phase I trials, embedding diagnostic partners early. Incumbents should anchor consumable recurring revenue through therapy-test partnership structures that extend beyond patent expiry. Capacity addition in cloud-based variant interpretation services reduces customer switching costs against emerging platform vendors. For New Entrants and Emerging Players: Build out psychiatric pharmacogenomic testing infrastructure where current competition remains limited and reimbursement pathways are stabilizing. Cardiovascular polygenic risk score integration into preventive care protocols represents the most penetrable application segment. Direct-to-consumer wellness subscription platforms offer a go-to-market angle that bypasses traditional clinical laboratory distribution channels and their consolidated purchasing power. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed clinical laboratory rollups that acquired community hospital molecular pathology operations. Long-term viability hinges on Medicare coverage expansion for minimal residual disease monitoring and early cancer detection methylation assays. Acquisition target archetypes include cloud-native variant interpretation software developers with EU AI Act compliance infrastructure. The signal to watch is NMPA innovation review pathway acceleration for domestically developed NGS assays in China.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Locks in multi-year consumable revenue through therapy-test bundling with pharmaceutical sponsors. |
| Cloud-Based Variant Interpretation Platform Launch | Decouples sequencing hardware from clinical decision support, reducing customer switching costs. |
| EU AI Act Compliance Service Expansion | Captures advisory revenue from algorithmic transparency requirements for machine-learning biomarker tools. |
| Direct-to-Consumer Genetic Testing Channel Entry | Bypasses consolidated health system procurement through wellness-oriented polygenic risk score subscriptions. |
| Methylation-Based Liquid Biopsy FDA Submission | Accelerates clinical validation timelines through breakthrough device designation for early cancer detection. |
Methodological Framework
The analysis maps DNA marker panels, epigenetic methylation assays, RNA expression signatures, and protein quantification platforms, each validated through molecular pathologists, diagnostic laboratory operations directors, pharmaceutical biomarker strategy leads, and payer coverage policy specialists. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, EMA scientific advice letters, CMS national coverage determinations, and ClinicalTrials.gov biomarker endpoints. Bottom-up assay volume modeling and top-down pharmaceutical R&D spend allocation were triangulated to derive market estimates.
Assumptions held fixed include Medicare coverage expansion trajectories for comprehensive genomic profiling, EMA-FDA regulatory harmonization continuity, and NGS platform miniaturization adoption curves across community hospital laboratories. Segmentation dimensions modeled encompass biomarker type, technology platform, therapeutic application, end-user category, and regional regulatory cluster. CAGRs were derived from installed base growth projections and consumable pull-through rates. Industry-specific forecast inputs include companion diagnostic co-development pipeline counts and liquid biopsy clinical validation study enrollment rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by emerging sequencing platform vendors or cloud-native interpretation software developers would shift outcomes. Regulatory pathway disruptions, reagent supply interruptions, or payer evidence requirement tightening represent specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Digital Genome Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Global NGS Sample Preparation Market
Genomics
Human Genetics Market
Genomics
DNA Sequencing Services Market
Genomics
Antisense Oligonucleotides Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
NGS-Based RNA-Sequencing Market
Genomics
Pharmacogenomics Technology Market
Genomics
Genetic Testing Market
Genomics
United States DNA Sequencing Products Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Global Long Read Sequencing Market
Genomics
Europe Epigenetics Market
Genomics
Europe Hereditary Cancer Testing Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market