
 Preclinical MRI Equipment Market | 2026-2036
Preclinical MRI Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Preclinical MRI Equipment Market Analytics
Multi-source procurement for superconducting magnet assemblies is shifting toward vertically integrated supply arrangements among top-tier vendors. Bruker Corporation sustains dominance through captive magnet manufacturing and cryogenics expertise. Siemens Healthineers leverages its healthcare imaging heritage to cross-sell preclinical platforms into academic consortia. Agilent Technologies anchors its position through specialized RF coil architectures and spectroscopy integration.
Preclinical MRI equipment encompasses high-field magnetic resonance imaging systems engineered for rodent and small-animal imaging, typically operating at field strengths from 4.7 Tesla to 21 Tesla with bore diameters under 40 centimeters, generating spatial resolution below 100 microns for tissue morphology and functional parameter mapping in drug development and disease modeling. Closed MRI systems occupy the largest installed base due to superior field homogeneity and signal-to-noise ratios required for neuroscience protocols, while hybrid MRI segments expand fastest as multimodal PET-MRI and SPECT-MRI configurations gain traction in oncology and cardiology translational research where co-registered functional and anatomical data streamline compound efficacy assessment.
FDA oversight of preclinical imaging data quality under GLP guidelines, EPA requirements for cryogen handling and disposal, and ISO 13485 quality management standards collectively elevate compliance costs and favor established vendors with documented regulatory dossiers. The EU AI Act and MDR framework increasingly influence software-enabled reconstruction algorithms and diagnostic claim boundaries in European procurement. Stakeholders must monitor evolving qualification thresholds for artificial intelligence-assisted image analysis tools as regulatory bodies distinguish between research-grade and clinically translatable preclinical outputs.
Market Dynamics
Contract research organizations are consolidating imaging service capacity around multi-modal platforms, forcing equipment vendors to bundle hardware with validated assay protocols and GLP-compliant data packages to secure multi-year service agreements.
Growth Catalysts
- GLP Validation Requirements:FDA 21 CFR Part 11 mandates for electronic records in preclinical studies compel pharmaceutical sponsors to upgrade legacy systems, creating replacement demand for compliant platforms with audit trails.
- Oncology Translational Pipelines:Immuno-oncology compound portfolios require longitudinal tumor microenvironment imaging, driving installation of high-field systems with cryogenic coil arrays in Boston and San Diego R&D clusters.
- Helium Conservation Technologies:Closed-loop cryogen recovery systems reduce operating costs and supply vulnerability, accelerating adoption in facilities facing helium price volatility and delivery constraints.
Market Restraints
- Superconducting Wire Concentration:Niobium-titanium filament supply concentrates among Japanese and European specialty metal processors, exposing OEMs to input cost spikes and allocation rationing during demand surges.
- Site Preparation Burden:Fringe field shielding, cryogen venting infrastructure, and vibration isolation requirements add construction costs that disqualify older academic buildings from system installation.
- PhD-Level Service Technician Scarcity:Maintenance and field service roles require combined expertise in superconducting magnet physics, RF engineering, and veterinary anesthesia protocols, constraining vendor expansion capacity.
Strategic Opportunities
- China Biotech Corridor Expansion:Suzhou and Zhangjiang science parks are constructing dedicated preclinical imaging facilities, creating first-mover advantage for vendors establishing local application support centers.
- AI-Assisted Image Reconstruction:Deep learning algorithms for motion correction and super-resolution reconstruction reduce scan times, enabling higher throughput in contract research settings where per-study pricing dominates.
- Point-of-Care Translation Pathways:Clinical MRI vendors are backward-integrating into preclinical platforms to capture longitudinal biomarker validation workflows, opening channel partnerships with university hospitals.
Industry Challenges
- Cross-Disciplinary Training Gaps:Facility managers must coordinate radiologists, veterinary surgeons, and computational biologists, yet formal certification programs for small-animal imaging operations remain institution-specific.
- Legacy Data Migration Complexity:Decades of proprietary file formats from discontinued platforms impede meta-analysis across studies, forcing sponsors to fund expensive re-scanning or manual curation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preclinical MRI Equipment Market |
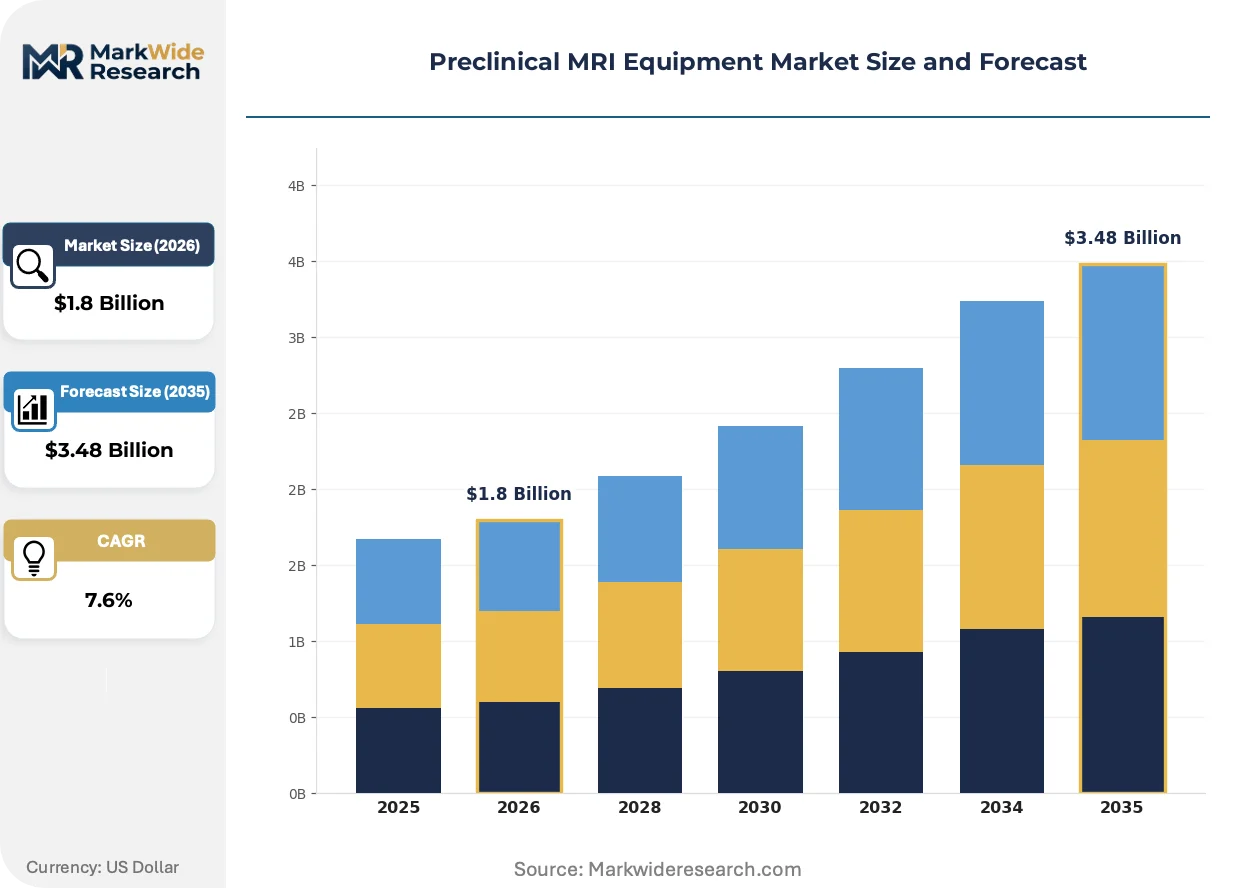
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Hybrid MRI End User: Academic Institutes, Pharmaceutical Companies, Research Organizations, Diagnostics Centers Technology: Gradient Echo, Spin Echo, Functional MRI, Diffusion Tensor Imaging Application: Neurology, Oncology, Cardiology, Musculoskeletal Disorders |
| Companies Covered | Bruker Corporation, Agilent Technologies, Siemens Healthineers, Aspect Imaging, FUJIFILM Holdings Corporation, MR Solutions, Revvity, Mediso Medical Imaging Systems, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preclinical MRI Equipment Market Evolving Landscape
Preclinical MRI is converging with molecular imaging and computational pathology, compressing the timeline between in vivo observation and histological validation while raising software complexity demands.
Cryogen-free superconducting magnets are electrifying the installed base expansion strategy for mid-tier academic centers. These systems eliminate helium dependency and reduce facility infrastructure requirements. Veterinary schools and smaller contract research operations in Germany and the Netherlands are adopting them at twice the pace of traditional wet-magnet platforms. The technology is electrifying vendor go-to-market models by enabling remote-site demonstrations and faster installation cycles.
The EU AI Act's risk classification framework is reshaping software procurement criteria for European imaging facilities. Algorithms generating quantitative biomarker outputs now face conformity assessment requirements previously reserved for diagnostic devices. Preclinical platforms with integrated AI reconstruction modules in France and Switzerland are undergoing voluntary CE marking to preempt future mandatory certification, creating a two-tier market between validated and research-grade software bundles.
Academic consortia are unbundling service contracts from hardware purchases, negotiating separate agreements for preventive maintenance, application training, and remote technical support. This fragmentation is compressing vendor margin structures while opening specialist service provider opportunities. The pattern is most visible in National Institutes of Health-funded centers in Maryland and North Carolina, where multi-institutional purchasing cooperatives now dominate tender processes.
Preclinical MRI Equipment Market Segmentation
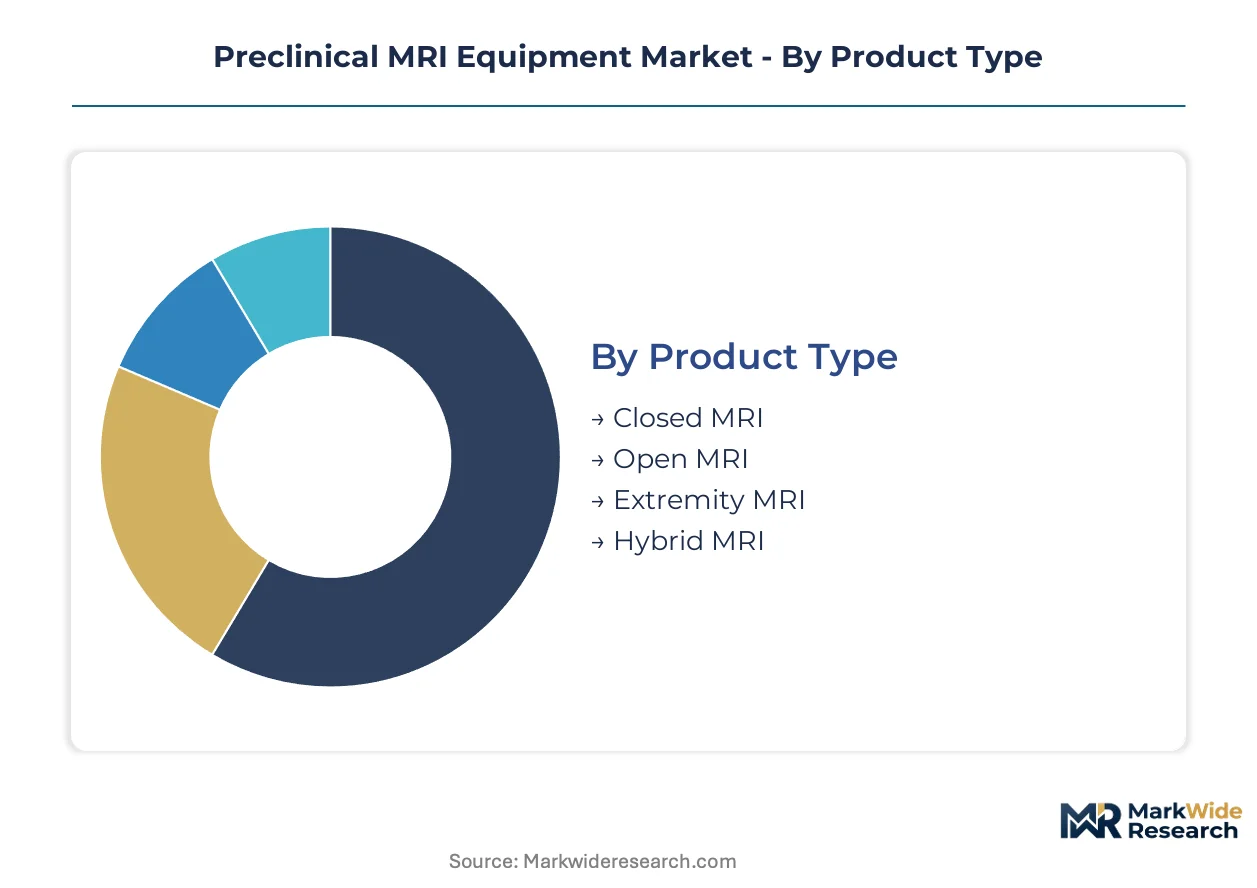
Preclinical MRI equipment segmentation reveals how procurement priorities diverge across facility types and research objectives. Technical specifications, compliance requirements, and throughput demands create distinct buyer profiles that vendors must address through differentiated platform configurations.
Product Type:
Cost tier determines infrastructure requirements and operational complexity for buyers in this category.
- Closed MRI:High-field cylindrical bore systems deliver superior field homogeneity and signal-to-noise ratios essential for neuroscience protocols. Pharmaceutical R&D clusters in Boston and San Diego prioritize these platforms for longitudinal tumor microenvironment studies requiring sub-100-micron resolution.
- Hybrid MRI:Multimodal PET-MRI and SPECT-MRI configurations enable co-registered functional and anatomical data capture. Contract research organizations consolidating imaging service capacity around these platforms to streamline compound efficacy assessment in oncology and cardiology translational pipelines.
- Open MRI:Permanent magnet or resistive designs accommodate larger subjects and interventional procedures with reduced fringe field constraints. Veterinary schools in Germany and the Netherlands favor cryogen-free variants for mid-tier academic budgets.
- Extremity MRI:Compact dedicated systems target limb and joint imaging with lower siting costs. Smaller contract research operations deploy these for musculoskeletal disorder modeling where full-body capability is unnecessary.
Closed MRI leads volumes today; Hybrid MRI is gaining share fastest.
End User:
Application maturity and funding stability separate buyers by operational risk tolerance.
- Pharmaceutical Companies:GLP-compliant data packages and validated assay protocols drive procurement. FDA 21 CFR Part 11 mandates for electronic records compel sponsors to upgrade legacy systems, creating replacement demand with audit trail requirements.
- Academic Institutes:National Institutes of Health-funded centers in Maryland and North Carolina dominate tender processes through multi-institutional purchasing cooperatives. These buyers unbundle service contracts from hardware purchases, negotiating separate agreements for preventive maintenance and application training.
- Research Organizations:Contract research organizations expanding preclinical imaging services require high-throughput platforms with AI-assisted reconstruction for per-study pricing models.
- Diagnostics Centers:Emerging demand from veterinary diagnostic chains seeking point-of-care translation pathways for companion animal imaging.
Academic Institutes anchor installed base expansion; Pharmaceutical Companies drive premium platform upgrades.
Technology:
Imaging speed and contrast mechanism sophistication define competitive positioning.
- Functional MRI:Blood-oxygen-level-dependent signal detection enables real-time neural activity mapping. Neuroscience consortia prioritize these capabilities for drug development pipelines targeting central nervous system disorders.
- Diffusion Tensor Imaging:White matter tractography through water diffusion anisotropy supports traumatic brain injury and neurodegenerative disease modeling. Academic medical centers with established computational pathology workflows demand integrated DTI reconstruction modules.
- Spin Echo:Robust T1 and T2 contrast weighting remains standard for anatomical morphology assessment across all end-user segments.
- Gradient Echo:Rapid acquisition sequences suit high-throughput screening applications where motion sensitivity is manageable.
Spin Echo retains broadest deployment; Functional MRI climbs the fastest as neuroimaging protocols proliferate.
Application:
Therapeutic area funding intensity and biomarker validation maturity shape segment dynamics.
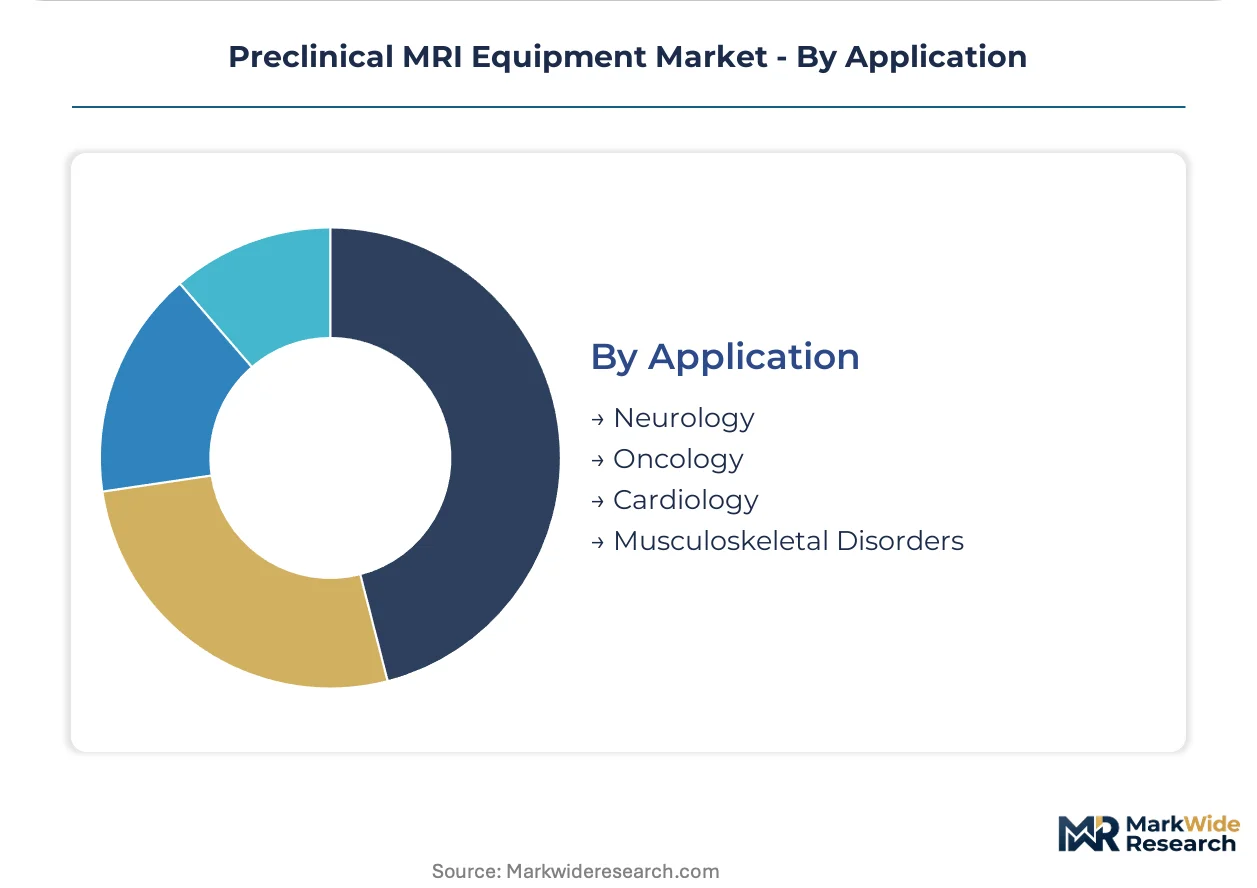
- Oncology:Immuno-oncology compound portfolios require longitudinal tumor microenvironment imaging. High-field systems with cryogenic coil arrays dominate procurement in pharmaceutical R&D clusters.
- Neurology:Disease modeling for Alzheimer's and Parkinson's therapies drives demand for ultra-high-field platforms above 9.4 Tesla. EU AI Act conformity assessment requirements now influence software procurement for quantitative biomarker outputs in France and Switzerland.
- Cardiology:Translational research for myocardial infarction and heart failure models expands hybrid MRI adoption for functional assessment.
- Musculoskeletal Disorders:Osteoarthritis and rheumatoid arthritis modeling supports steady demand for mid-field extremity systems.
Oncology commands premium pricing; Neurology shows steepest expansion trajectory as biomarker programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego pharmaceutical R&D clusters generate concentrated procurement for high-field preclinical MRI systems with GLP-compliant audit trails.
United States
National Institutes of Health-funded centers in Maryland and North Carolina coordinate multi-institutional purchasing cooperatives that unbundle service contracts from hardware acquisitions. FDA 21 CFR Part 11 mandates for electronic records in preclinical studies compel pharmaceutical sponsors to upgrade legacy platforms. The Boston biotechnology corridor drives premium installations for longitudinal tumor microenvironment imaging in immuno-oncology pipelines.
Germany
Veterinary schools and mid-tier academic centers adopt cryogen-free superconducting magnets at twice the pace of traditional wet-magnet platforms. The EU AI Act and MDR framework reshape software procurement criteria for quantitative biomarker outputs. The Baden-Württemberg and Bavaria regions host concentrated preclinical imaging facilities serving contract research organizations expanding multimodal service capacity.
China
Suzhou and Zhangjiang science parks construct dedicated preclinical imaging facilities targeting biotech corridor expansion. NMPA alignment with international GLP standards elevates compliance requirements for imported platforms. Local application support centers emerge as competitive differentiators for vendors establishing first-mover positions in the Yangtze River Delta cluster.
Switzerland
Preclinical platforms with integrated AI reconstruction modules undergo voluntary CE marking to preempt mandatory certification under evolving EU AI Act risk classifications. Swissmedic oversight of software-enabled diagnostic claims influences procurement specifications for quantitative imaging outputs. The Basel pharmaceutical research hub sustains demand for ultra-high-field systems above 9.4 Tesla in neurology biomarker programs.
Japan
PMDA recognition of preclinical imaging data in regulatory submissions drives platform standardization among pharmaceutical sponsors. METI funding for advanced medical device development supports domestic vendor capacity in superconducting magnet components. The Kanto region maintains installed base concentration for neuroscience consortia targeting central nervous system disorder modeling.
Preclinical MRI Equipment Market Competitive Landscape
Global majors compete with regional champions across magnet manufacturing and cryogenics expertise, producing a tiered structure where captive supply chains separate premium-tier vendors from assembly-dependent competitors. Three archetypes dominate: vertically integrated superconducting magnet producers, healthcare imaging heritage firms cross-selling preclinical platforms, and specialized RF coil architects with spectroscopy integration. Consolidation pressure intensifies through strategic partnerships bundling hardware with validated assay protocols, while geographic expansion into Chinese biotech corridors emerges as a critical competitive move.
Among the vertically integrated tier, Bruker Corporation anchors positions through captive magnet manufacturing and cryogenics capabilities. Siemens Healthineers occupies a scale-driven position leveraging healthcare imaging heritage for academic consortia penetration. Agilent Technologies exemplifies the specialized RF architecture segment through spectroscopy-integrated platform positioning. These three represent distinct competitive vectors—upstream magnet control, clinical-to-preclinical channel leverage, and application-specific coil engineering—shaping procurement negotiations across pharmaceutical and academic end-user segments.
| Leading Market Players |
|---|
| Bruker Corporation |
| Agilent Technologies |
| Siemens Healthineers |
| Aspect Imaging |
| FUJIFILM Holdings Corporation |
| MR Solutions |
| Revvity |
| Mediso Medical Imaging Systems |
| Koninklijke Philips |
| Others |
Value Network & Pricing Analysis
Cryogen-free superconducting magnet manufacturing is simultaneously compressing facility infrastructure costs and concentrating procurement leverage among Japanese and European specialty metal processors. This dual effect reshapes how vendors structure platform pricing and how buyers negotiate long-term service agreements across pharmaceutical and academic segments.
Pricing Analysis
Input-cost pass-through from niobium-titanium filament supply rationing drives pricing stratification across premium, standard, and economy tiers. ISO 13485 certification grade and GLP-compliant audit trail capabilities separate premium platforms from research-grade alternatives. Cost compression in mid-field systems is intensifying because helium price volatility forces buyers toward cryogen-free alternatives. Contract research organizations exhibit highest price sensitivity due to per-study pricing models, while pharmaceutical sponsors prioritize compliance over cost.
Supply Chain Analysis
Domestic-content mandates in China's NMPA framework are reshaping sourcing patterns for imported platforms in Suzhou and Zhangjiang science parks. Superconducting wire supply draws from Japan, Germany, and the United States, with niobium-titanium filaments, cryogenic cooling systems, and RF coil assemblies anchoring component dependencies. Single-source vulnerability in Japanese specialty metal processors exposes OEMs to allocation rationing during demand surges. Distribution runs through direct vendor sales teams for pharmaceutical accounts and academic purchasing cooperatives for institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preclinical MRI equipment functions as a stable compounder anchored by GLP validation mandates that perpetuate replacement cycles across pharmaceutical R&D infrastructure. Regulatory compliance requirements create durable demand floors regardless of macroeconomic volatility.
For Market Incumbents: Hedge helium supply vulnerability through captive cryogen recovery system development or strategic partnerships with Japanese wire processors. Consolidate application support centers in China's Yangtze River Delta before local vendors achieve NMPA alignment with international standards. Vertical integration into RF coil architectures preserves margin against specialized competitors.
For New Entrants and Emerging Players: AI-assisted image reconstruction algorithms offer a technology-first wedge into contract research organization service contracts where throughput pricing dominates. Target mid-tier academic centers in Germany and the Netherlands adopting cryogen-free platforms at twice traditional wet-magnet pace. Lead with remote technical support capabilities to unbundle service contracts from hardware purchases.
For Investors and Strategic Acquirers: Valuations sit cheapest among RF coil architecture specialists with spectroscopy integration capabilities and established academic channel relationships. Long-term viability rests on software-enabled diagnostic claim boundaries hardening under EU AI Act risk classifications. Watch for voluntary CE marking acceleration among preclinical platforms with integrated AI reconstruction modules as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| GLP-Compliant Platform Upgrade | FDA 21 CFR Part 11 mandates compel pharmaceutical sponsors to replace legacy systems with audit-trail-enabled configurations. |
| AI Reconstruction Module Integration | Deep learning algorithms for motion correction reduce scan times and enable higher throughput in CRO per-study pricing models. |
| Cryogen-Free Magnet Deployment | Elimination of helium dependency reduces facility infrastructure requirements and accelerates installation cycles in mid-tier academic centers. |
| China Application Support Center Establishment | Local technical presence creates first-mover advantage in Suzhou and Zhangjiang science parks constructing dedicated preclinical imaging facilities. |
| Multi-Institutional Purchasing Cooperative Partnership | NIH-funded centers in Maryland and North Carolina dominate tender processes through unbundled hardware and service contract negotiations. |
Research Methodology
Multiple input streams — primary interviews with biomedical engineers, pharmaceutical R&D executives, and GPO contracts managers; secondary validation through FDA 510(k) filings, NMPA registration databases, and hospital procurement records; and trade data from customs authorities — were reconciled through bottom-up and top-down triangulation. Field perspectives from superconducting magnet physicists and veterinary anesthesia protocol specialists informed technical specification assumptions.
Historical shipment data was cross-referenced against expert panel inputs to establish baseline penetration rates across the projection horizon. Segmentation dimensions modeled include field strength tier, magnet cooling technology, end-user facility type, and regional regulatory cluster. CAGRs were derived from weighted scenario analysis incorporating GLP validation timeline acceleration and helium supply constraint probabilities.
The model holds under stable regulatory enforcement of FDA and NMPA data quality standards; deviation in EU AI Act risk classification thresholds or sudden niobium-titanium supply disruption would shift replacement demand timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Canada Nuclear Medicine Market
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
North America Fluoroscopy Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Spinal Imaging Market