
 Body Worn Temperature Sensors Market | 2026-2036
Body Worn Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Body Worn Temperature Sensors Market Analysis
Medical-grade accuracy is collapsing the gap between consumer wellness wearables and clinical diagnostic tools. Texas Instruments Inc. leverages its precision analog semiconductor portfolio to sustain leadership in signal conditioning for temperature acquisition. STMicroelectronics NV anchors its position through MEMS fabrication scale and integrated sensor modules that reduce device footprint for patch form factors.
Body worn temperature sensors are electronic transducers mounted on or integrated into garments, skin-contact patches, or accessories that measure core or surface body temperature with specified clinical tolerances, typically transmitting data via Bluetooth or RFID to centralized monitoring platforms for continuous physiological surveillance. Patch sensors occupy the highest-margin tier due to their disposable revenue model and hospital procurement volume, while smart clothing competes on comfort adherence in sports team deployments where athlete compliance determines data continuity. Thermocouple technology dominates clinical trials requiring rapid thermal response, though infrared non-contact variants are gaining share in elder care facilities where skin integrity concerns limit adhesive-based contact methods.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and testing burdens for manufacturers seeking dual-market access. HIPAA privacy standards and GDPR data governance frameworks constrain how temperature data flows from wearable devices to electronic health record systems, creating compliance costs that favor established players with dedicated regulatory affairs functions. Stakeholders must monitor evolving reimbursement codes for remote therapeutic monitoring as payer decisions will determine whether body worn temperature sensors remain hospital-procured capital or shift toward patient-owned durable medical equipment.
Market Dynamics
The convergence of FDA 510(k) clearance streamlining and Medicare reimbursement expansion for remote therapeutic monitoring is compressing commercialization timelines while elevating clinical validation requirements above consumer-grade wellness benchmarks.
Growth Catalysts
- RTM Reimbursement Codes:CMS-established billing categories for remote therapeutic monitoring reimburse body-worn temperature data when captured under physician supervision, accelerating hospital procurement cycles.
- Aging Demographics:Japan's super-aged population and Germany's 65-plus cohort expansion generate institutional demand for continuous temperature surveillance in elder care facilities and post-acute settings.
- Bluetooth Low Energy:The wireless protocol's 1.5-year battery life for patch sensors eliminates charging friction that previously compromised patient adherence in longitudinal studies.
Market Restraints
- MEMS Foundry Concentration:Taiwan Semiconductor Manufacturing and specialty MEMS fabricators in Hsinchu Science Park control 70-plus percent of sensor die supply, exposing manufacturers to geopolitical disruption.
- Silver Price Volatility:Thermocouple junctions and conductive traces in disposable patches face input cost swings from precious metal commodity markets.
- GDPR Data Localization:EU Medical Device Regulation companion requirements mandate European-based health data processing infrastructure, raising capital deployment thresholds for non-EU vendors.
Strategic Opportunities
- Pediatric Fever Monitoring:Underpenetrated home-care segment for continuous infant temperature tracking during post-vaccination surveillance and nocturnal fever management.
- Fertility Tracking Integration:Basal body temperature sensors converging with ovulation prediction algorithms create subscription revenue models outside traditional healthcare procurement.
- Occupational Heat Stress:OSHA-influenced workplace safety mandates for agricultural and construction workers in Australia and the US Gulf states drive enterprise fleet deployments.
Industry Challenges
- Clinical Validation Talent:Scarcity of biostatisticians experienced in wearable sensor equivalence trials slows 510(k) submission preparation for mid-tier manufacturers.
- EHR Integration Complexity:HL7 FHIR interoperability requirements demand engineering resources that stretch development budgets for point-solution vendors.
- Adhesive Dermatitis Risk:Extended-wear patch sensors trigger skin reactions in 8-12 percent of users, necessitating biocompatibility testing iterations that extend certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Worn Temperature Sensors Market |
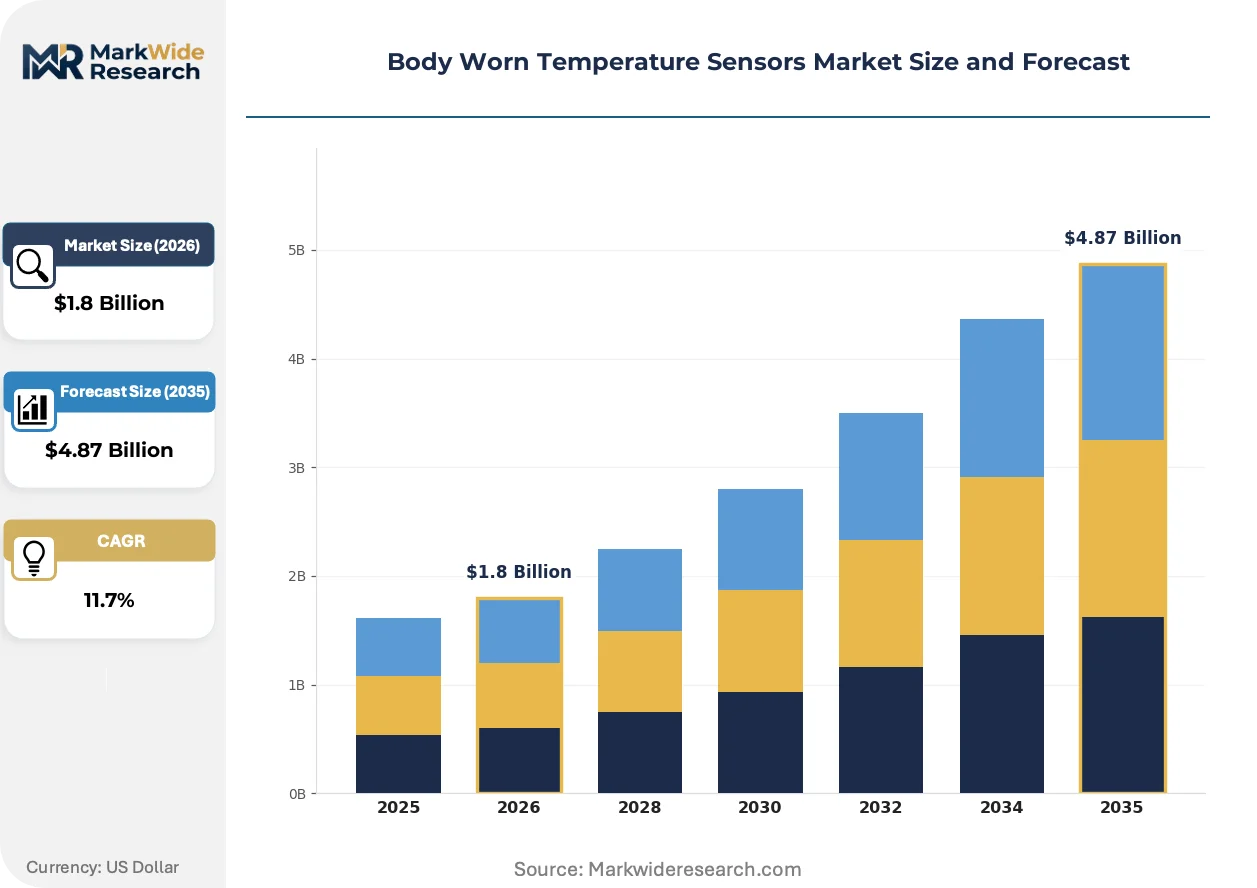
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.87 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch Sensors, Smart Clothing, Wearable Devices, Thermoregulation Units Technology: Infrared, Thermocouples, RFID, Bluetooth Connectivity End User: Hospitals, Sports Teams, Individual Consumers, Elder Care Facilities Application: Health Monitoring, Fitness Tracking, Clinical Trials, Patient Care |
| Companies Covered | Silicon Laboratories Inc., Maxim Integrated Products Inc., STMicroelectronics NV, Texas Instruments Inc., Analog Devices Inc., Medtronic plc, Garmin Ltd., Philips, Omron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Worn Temperature Sensors Market Emerging Trajectories
Material science breakthroughs and regulatory pathway refinements are collapsing the validation burden for clinical-grade wearables while expanding addressable use cases beyond hospital walls into ambulatory and consumer-adjacent segments.
Flexible printed circuit technology is miniaturizing temperature acquisition modules to sub-2mm thicknesses compatible with textile integration. Sports medicine programs at NCAA Division I universities are adopting smart compression garments for real-time heat illness prevention during summer training camps. The form-factor reduction is enabling 72-hour continuous wear without skin irritation, compressing the performance gap between disposable patches and reusable apparel.
The EU Medical Device Regulation's 2021 recast tightened clinical evidence requirements for Class IIa temperature monitoring devices, forcing manufacturers to generate prospective validation data rather than predicate-device equivalency. German notified bodies have accumulated 18-month review backlogs, diverting commercialization energy toward US FDA pathways. Swissmedic's parallel review program offers accelerated access for devices holding FDA clearance, redirecting European market entry strategies through Switzerland.
Hospital procurement departments are consolidating vendor relationships under single-source remote patient monitoring contracts that bundle temperature sensors with pulse oximetry and blood pressure modules. Health systems in Texas and Florida are disintermediating traditional medical device distributors through direct manufacturer partnerships that include clinical training and data analytics subscriptions. The purchasing concentration favors integrated platform vendors over standalone temperature sensor specialists, compressing available shelf space for point solutions in IDN supply chains.
Body Worn Temperature Sensors Market Segmentation
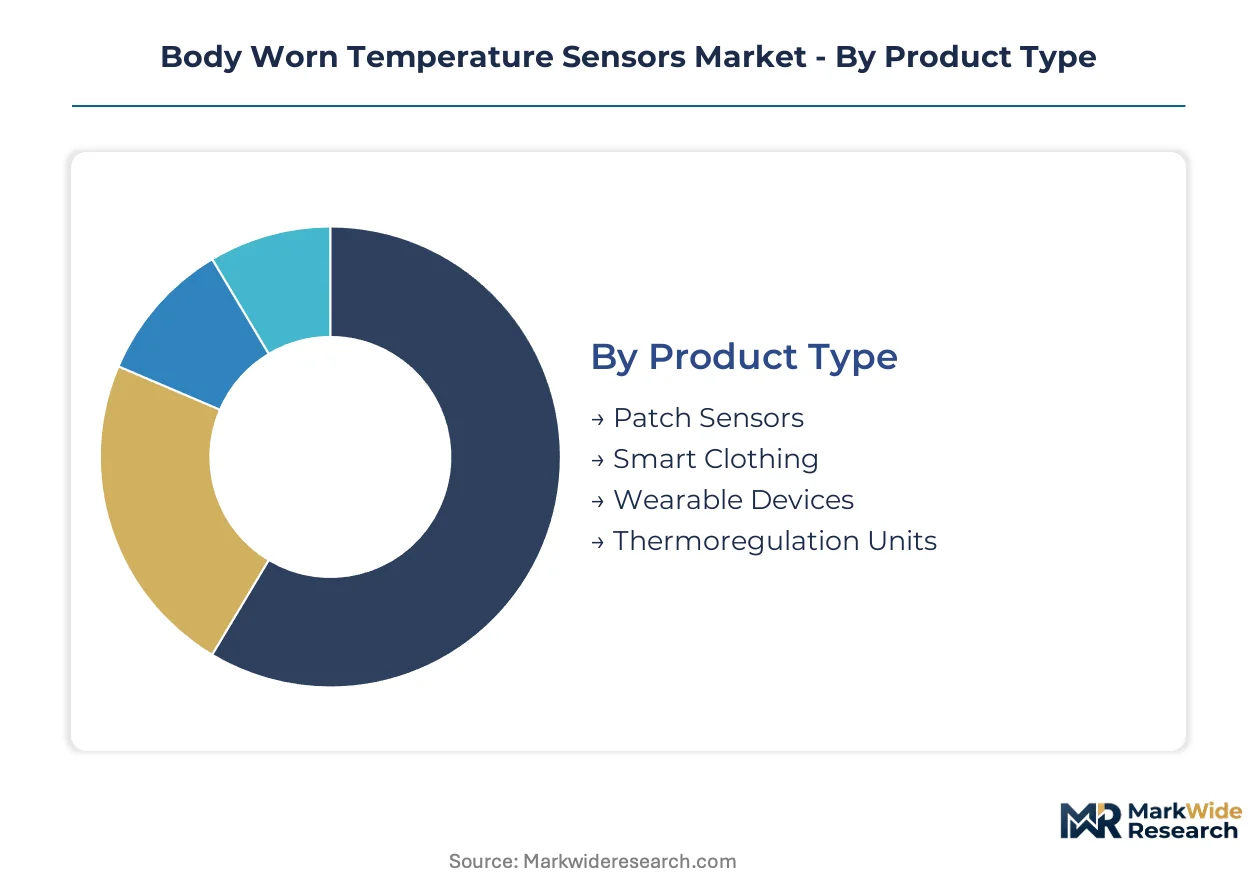
Body worn temperature sensors fragment across four distinct category axes, each carrying different margin profiles and regulatory burdens. Product type determines reimbursement eligibility under CMS remote therapeutic monitoring codes, while technology selection shapes battery life and data fidelity trade-offs that constrain viable use cases.
Product Type:
FDA 510(k) clearance pathways distinguish reimbursable clinical tools from consumer wellness devices, creating tiered market access conditions that segment manufacturers by regulatory capability rather than sensor performance alone.
- Patch Sensors:Disposable adhesive-mounted transducers with integrated Bluetooth Low Energy transmission modules. Hospital procurement departments in Germany and Japan concentrate volume here for post-acute temperature surveillance, drawn by the per-unit reimbursement model and 72-hour continuous wear certification.
- Smart Clothing:Textile-integrated conductive fiber networks measuring skin surface temperature through fabric contact. NCAA Division I athletic programs and Australian mining operations drive demand for this segment, prioritizing athlete and worker compliance over absolute clinical precision.
- Wearable Devices:Wrist-worn or finger-mounted temperature acquisition modules, typically paired with pulse oximetry and accelerometry functions.
- Thermoregulation Units:Active heating-cooling garments with embedded feedback loops for core temperature management.
Patch sensors handle the majority of throughput; smart clothing is expanding most quickly on share as occupational safety mandates proliferate.
Technology:
Signal acquisition methods split the market by response speed, power budget, and compatibility with continuous wear constraints.
- Infrared:Non-contact thermal radiation detection preserving skin integrity in fragile elderly populations. Elder care facilities in Japan's super-aged prefectures favor this approach where adhesive contact risks dermal injury.
- Thermocouples:Bimetallic junctions delivering millisecond thermal response for clinical trial protocols requiring precise fever onset detection. Pharmaceutical sponsors running infectious disease studies in the United States specify this technology for protocol compliance.
- RFID:Passive wireless temperature logging without onboard power, suitable for short-range hospital inventory and patient identification workflows.
- Bluetooth Connectivity:Active wireless protocol enabling real-time data streaming to centralized monitoring platforms.
Thermocouples dominate clinical trial procurement; Bluetooth modules are climbing the fastest as battery chemistry improvements extend patch sensor longevity.
End User:
Customer type determines pricing power, with institutional procurement commanding volume discounts and individual consumers accepting premium markups for fertility tracking and pediatric applications.
- Hospitals:Integrated delivery networks bundling temperature sensors with pulse oximetry and blood pressure modules under single-source remote patient monitoring contracts. Texas and Florida health systems are disintermediating distributors through direct manufacturer partnerships.
- Sports Teams:Professional and collegiate athletic programs purchasing fleet deployments for heat illness prevention. Australian Rules Football and US collegiate football programs generate seasonal demand spikes aligned with summer training camp calendars.
- Individual Consumers:Direct-to-purchase users seeking fertility tracking or infant fever monitoring solutions.
- Elder Care Facilities:Institutional operators managing post-acute and long-term care populations.
Hospitals anchor procurement volume; individual consumers represent the steepest expansion trajectory as subscription-based fertility tracking applications commercialize.
Application:
Use case segmentation maps directly to reimbursement code availability and clinical evidence requirements under FDA and EU MDR frameworks.
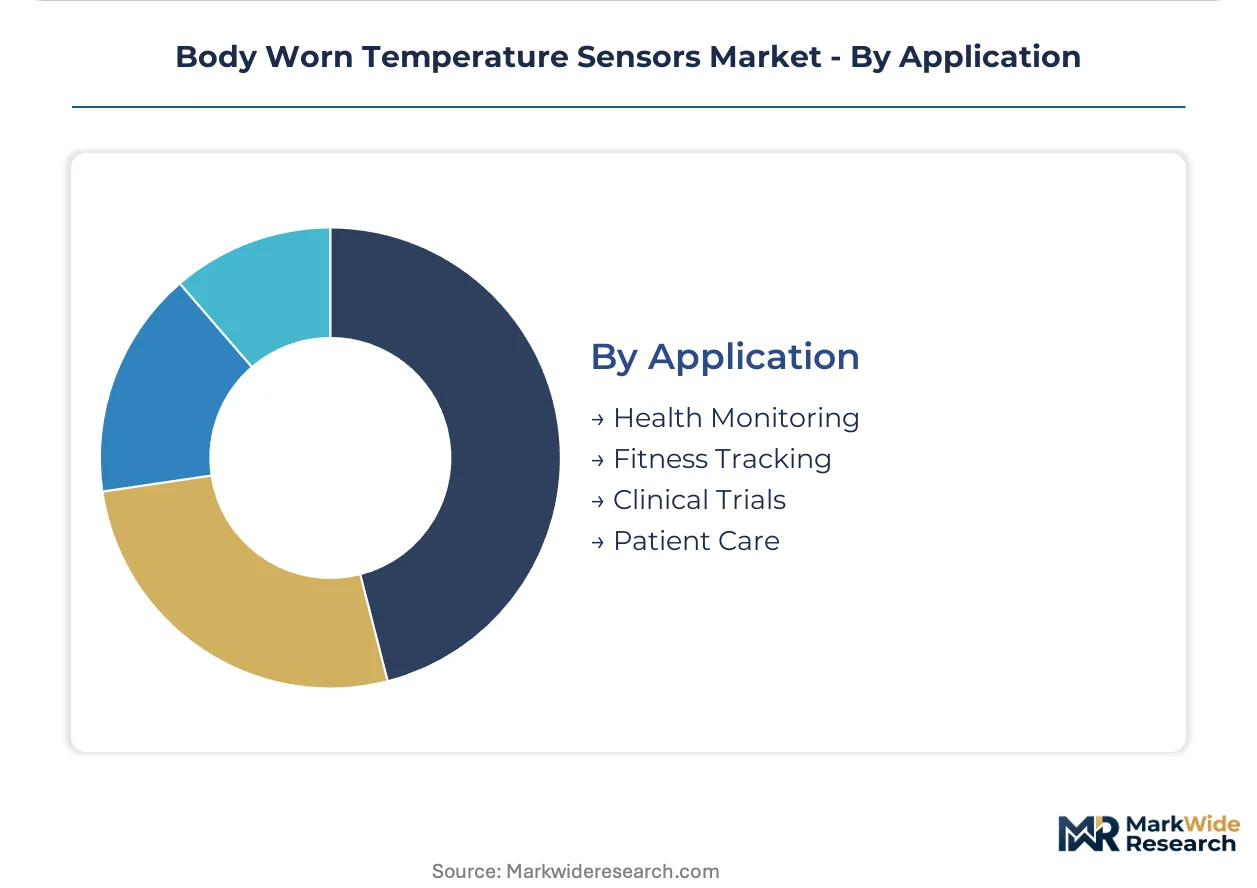
- Health Monitoring:Continuous physiological surveillance for chronic condition management, qualifying for CMS remote therapeutic monitoring reimbursement when physician-supervised. German statutory health insurance funds have established parallel reimbursement categories accelerating adoption in Bavaria and North Rhine-Westphalia.
- Fitness Tracking:Athletic performance optimization and heat stress prevention in occupational and recreational settings. Australian agricultural employers and US Gulf Coast construction firms deploy fleet-scale programs driven by OSHA-influenced safety mandates.
- Clinical Trials:Protocol-grade temperature acquisition for pharmaceutical research.
- Patient Care:Post-discharge surveillance and hospital-at-home temperature monitoring.
Health monitoring commands the largest installed base; fitness tracking is gaining share fastest as workplace safety regulations tighten in high-temperature occupations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for body worn temperature sensors tilt toward net imports in clinical-grade segments while semiconductor components flow from established Asian fabrication centers to device assemblers in North America and Europe.
United States
FDA 510(k) clearance streamlining and Medicare reimbursement expansion for remote therapeutic monitoring accelerate hospital procurement cycles. CMS-established billing categories reimburse body-worn temperature data under physician supervision. Texas and Florida health systems drive demand through direct manufacturer partnerships that bypass traditional distributors.
Germany
An aging population and statutory health insurance reimbursement frameworks for digital health tools concentrate institutional demand. EU Medical Device Regulation compliance requirements shape product development timelines for manufacturers seeking market access. Bavaria and North Rhine-Westphalia host the densest deployment of post-acute temperature surveillance programs.
Japan
Super-aged demographics in prefectures like Aichi and Osaka generate sustained demand for continuous temperature surveillance in elder care facilities. METI industrial standards guide wearable device interoperability specifications. Tokyo-based healthcare networks integrate infrared non-contact variants where skin integrity concerns limit adhesive-based methods.
China
Domestic MEMS fabrication scale and integrated sensor module production reduce device costs for patch form factors. NMPA medical device registration pathways determine commercialization timelines for clinical-grade wearables. Hsinchu Science Park suppliers anchor sensor die supply chains serving downstream device manufacturers.
Australia
OSHA-influenced workplace safety mandates for agricultural and construction workers drive enterprise fleet deployments for heat stress prevention. TGA regulatory frameworks govern clinical-grade wearable market entry. Queensland and Western Australian mining operations generate seasonal demand spikes for smart clothing thermoregulation solutions.
Body Worn Temperature Sensors Market Vendor Landscape
Listed leaders compete with private specialists across regulatory capability and MEMS fabrication scale, creating tiered competitive dynamics. Precision analog semiconductor portfolios and signal conditioning expertise separate clinical-grade suppliers from consumer wellness entrants. Three archetypes dominate: integrated platform vendors bundling multi-parameter monitoring, standalone sensor specialists focusing on temperature acquisition fidelity, and textile-technology hybrids converging apparel with physiological tracking. M&A activity concentrates among platform vendors acquiring point-solution temperature specialists, while capacity expansion targets European data localization infrastructure under GDPR requirements.
Within the semiconductor-centric tier, Texas Instruments Inc. and STMicroelectronics NV exemplify precision analog and MEMS fabrication leadership respectively. Analog Devices Inc. occupies a position bridging signal conditioning expertise with healthcare application focus. These three anchors represent distinct competitive vectors: analog semiconductor heritage, fabrication scale integration, and mixed-signal healthcare specialization.
| Leading Market Players |
|---|
| Silicon Laboratories Inc. |
| Maxim Integrated Products Inc. |
| STMicroelectronics NV |
| Texas Instruments Inc. |
| Analog Devices Inc. |
| Medtronic plc |
| Garmin Ltd. |
| Philips |
| Omron |
| Others |
Supply Flow & Price Mechanics
FDA 510(k) clearance requirements and EU MDR certification tiers simultaneously gate supplier qualification and stratify price levels across clinical-grade and consumer-adjacent segments. Hospital procurement departments in Germany and Japan command volume discounts for disposable patch sensors, while individual consumers absorb premium markups for fertility-tracking subscriptions that bundle hardware with algorithmic services.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that compress margins for high-volume patch sensor manufacturers. Price differentiation separates FDA-cleared clinical devices from wellness-grade alternatives, with certification level and after-sales service bundling driving tier separation. Cost compression in the disposable patch tier is intensifying because silver price volatility in thermocouple junctions feeds directly into input costs. Hospital IDNs exhibit lowest price sensitivity due to bundled RPM contracts, whereas individual consumers show highest elasticity when comparing standalone hardware against subscription-integrated alternatives.
Supply Chain Analysis
Just-in-time inventory strategies dominate among device assemblers serving hospital procurement cycles, though strategic silver stockpiling persists among thermocouple-dependent manufacturers exposed to precious metal commodity swings. Sensor die fabrication concentrates in Taiwan, South Korea, and China, with MEMS foundries in Hsinchu Science Park feeding downstream assembly operations. Raw material dependencies span silver for conductive traces, lithium for Bluetooth module batteries, and medical-grade adhesives for skin-contact layers. Single-source vulnerability around Taiwan Semiconductor Manufacturing exposes the supply chain to geopolitical disruption. Distribution runs through integrated delivery network procurement departments that disintermediate traditional medical device distributors in Texas and Florida health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biostatisticians experienced in wearable sensor equivalence trials represent the scarcest capability layer, slowing 510(k) submissions for mid-tier manufacturers and compressing commercialization timelines for entrants lacking dedicated regulatory affairs functions.
For Market Incumbents: Fortify MEMS fabrication partnerships through capacity reservation agreements with Taiwan-based foundries to defend against geopolitical supply interruption. Deepen backward integration into precision analog semiconductor design to reduce dependency on Texas Instruments and Analog Devices for signal conditioning components. Hospital procurement consolidation under single-source RPM contracts threatens standalone temperature sensor specialists; platform bundling with pulse oximetry and blood pressure modules preserves shelf space in IDN supply chains. For New Entrants and Emerging Players: Data analytics service layers surrounding continuous temperature streams remain under-developed by hardware-centric incumbents, creating white-space for software-native entrants. Pediatric fever monitoring and fertility tracking applications present the most penetrable consumer segments outside institutional procurement channels. A direct-to-patient subscription model bypassing hospital purchasing committees offers the cleanest go-to-market angle for algorithm-integrated basal body temperature sensors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across European data localization infrastructure as GDPR mandates drive health data processing facility deployment. The five-to-ten year viability window favors acquisition targets with established FDA 510(k) clearance portfolios and existing CMS reimbursement code alignment. Signal to monitor: Medicare remote therapeutic monitoring reimbursement expansion rates, as payer decisions determine whether body worn temperature sensors remain hospital-procured capital or shift toward patient-owned durable medical equipment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates hospital procurement cycles under CMS reimbursement categories. |
| CE Marking Pathway | Unlocks German statutory health insurance reimbursement for digital health tools. |
| Hospital System Partnership | Enables direct manufacturer relationships that bypass traditional distributors in Texas and Florida. |
| Software Companion Development | Supports subscription revenue models for fertility tracking and pediatric fever monitoring applications. |
| Reimbursement Strategy | Determines transition from hospital-procured capital to patient-owned durable medical equipment. |
Methodological Framework
Operator-level perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, EU MDR notified body records, and hospital procurement contract disclosures. Bottom-up segment sizing across product type, technology, end user, and application dimensions triangulated with top-down market envelope checks.
Sensitivity analysis tested forecast outputs against alternative assumptions for MEMS foundry capacity expansion, silver price trajectory bands, and CMS reimbursement code adoption curves across the projection horizon. Segmentation dimensions modeled include product form factor, signal acquisition technology, institutional versus consumer procurement channel, and geographic regulatory cluster. CAGRs derived from fitted growth curves incorporating historical adoption patterns, demographic projections, and policy implementation timelines. Industry-specific inputs encompassed Bluetooth Low Energy battery chemistry improvement curves and EU MDR notified body review backlog durations.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and CMS remote therapeutic monitoring reimbursement frameworks; material policy shifts would require re-modeling. Specific risk factors that could revise projections include Taiwan Strait supply disruption, precious metal commodity spikes, and GDPR enforcement escalation mandating additional data localization infrastructure. Revision becomes warranted when MEMS foundry utilization rates or Medicare reimbursement code utilization cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
On-Board Magnetic Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Air Flow Monitoring System Market