
 Smart Level Probe Market | 2026-2036
Smart Level Probe Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Level Probe Market Insights
Wireless sensor networking is fragmenting traditional wired level measurement architectures across process industries. Emerson Electric Co. leverages its Plantweb digital ecosystem to anchor premium positioning in integrated wireless deployments. ABB Ltd. competes through its Ability Smart Sensor platform, which extends predictive maintenance capabilities to level probe fleets. Siemens AG dominates European utility applications with Sitrans portfolio depth and channel control across DACH region integrators.
A smart level probe is an instrumented sensing device that measures liquid or solid material height within vessels, tanks, or silos using electromagnetic, acoustic, or optical principles, typically achieving measurement accuracies within millimeters across temperature ranges from minus forty to two hundred degrees Celsius. Its primary industrial purpose is enabling automated inventory management, overflow prevention, and batch process control in continuous or batch manufacturing environments. Radar probes command the highest value per unit due to extreme-condition tolerance in high-pressure chemical reactors, while ultrasonic variants sustain volume leadership in water treatment basins where foam and vapor interference remain minimal. Wireless technology integration represents the fastest-expanding configuration, though guided wave technology retains margin concentration in safety-critical oil and gas separator applications.
The US EPA enforces Clean Water Act discharge monitoring standards that mandate certified level instrumentation at municipal treatment outfalls, while the EU F-Gas Regulation restricts refrigerant-based purge systems used with certain probe types in cold-climate installations. FDA 21 CFR Part 11 compliance requirements for electronic records shape food and beverage probe selection, particularly for dairy and brewery tank applications. Stakeholders must weigh interoperability certification against vertical lock-in risks as fieldbus standards proliferate and edge computing architectures redefine where measurement intelligence resides.
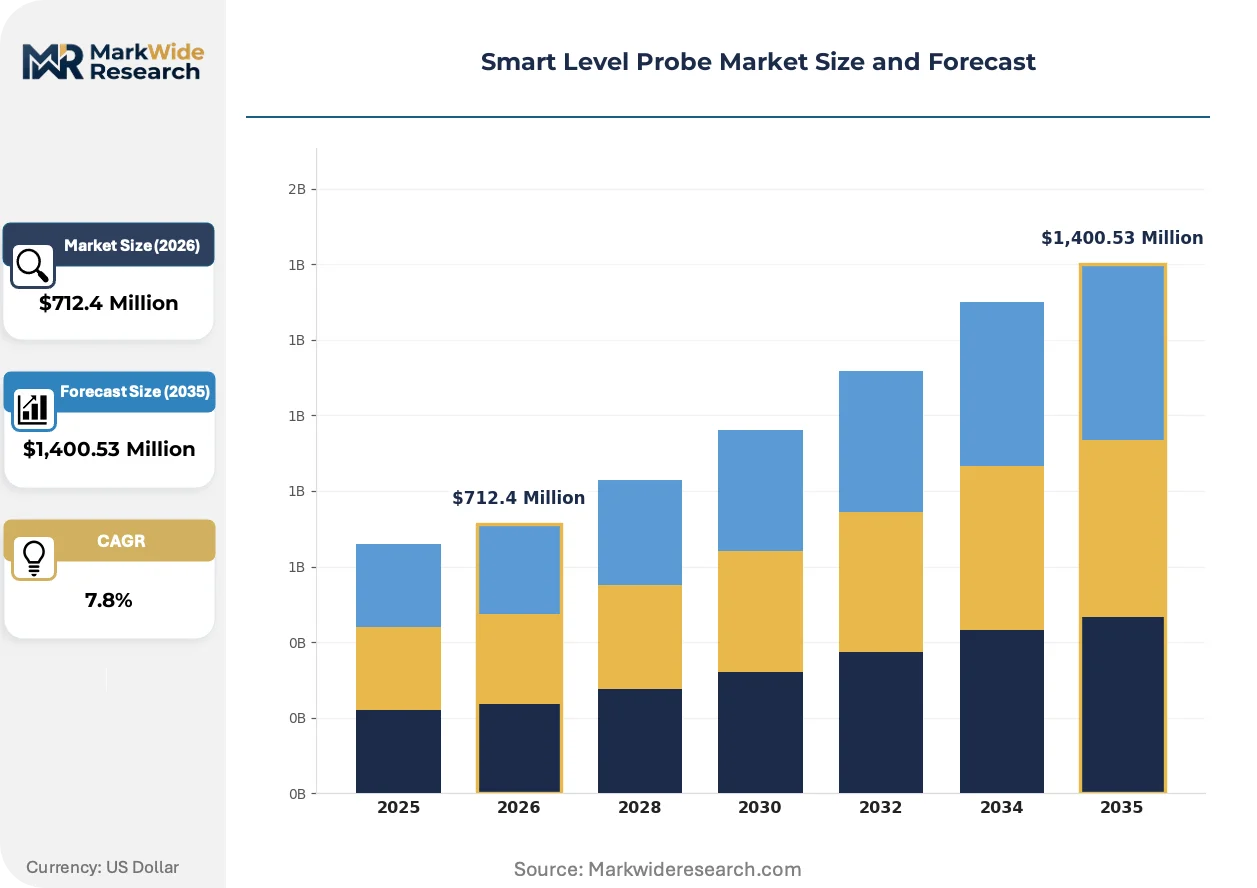
Market Dynamics
Industrial IoT integration with cloud-based asset management platforms is fragmenting legacy wired architectures across process industries, forcing incumbent vendors to reconfigure hardware portfolios around edge-native intelligence and subscription software revenue models.
Growth Catalysts
- EU Drinking Water Directive Revisions:Water treatment facilities in Germany and the Netherlands are expanding probe deployments under tightened monitoring mandates for continuous level surveillance at municipal intake and discharge points.
- SIL-Certified Automation Upgrades:Tank farm operators along the US Gulf Coast petrochemical corridor require safety-integrity-certified measurement devices for overflow prevention systems in high-hazard storage facilities.
- Wireless Sensor Networking:Battery-powered mesh protocols are eliminating trenching and conduit costs at remote wellpad separators and agricultural silo installations where wired infrastructure proves uneconomical.
Market Restraints
- Semiconductor Component Concentration:Custom ASICs and RF front-end modules for radar signal processing concentrate sourcing among East Asian foundries, exposing lead time volatility to geopolitical friction.
- F-Gas Regulatory Friction:The EU F-Gas Regulation restricts refrigerant-based purge systems used with certain ultrasonic probe types in cold-climate installations, forcing design pivots in Nordic markets.
- Guided Wave Radar Cost Structure:Coaxial probe assemblies require precision-machined waveguide elements and high-temperature ceramic seals that sustain 40-60% raw material cost premiums versus non-contact alternatives.
Strategic Opportunities
- India Water Infrastructure Modernization:Central government smart city initiatives and AMRUT 2.0 funding are creating first-time demand for networked level monitoring at urban sewage treatment plants and distribution reservoirs.
- Edge-AI Convergence:On-device machine learning inference for foam pattern recognition and false-echo suppression is collapsing the need for separate signal conditioning hardware in chemical reactor applications.
- Digital Twin Integration:Asset performance management platforms are opening recurring software revenue streams through predictive calibration drift alerts and automated maintenance scheduling.
Industry Challenges
- Fieldbus Standard Proliferation:Interoperability certification against HART, PROFIBUS PA, Foundation Fieldbus, and emerging OPC UA FX specifications fragments engineering validation resources and extends product development cycles.
- Cybersecurity Compliance Burden:IEC 62443 certification for industrial automation components demands dedicated secure development lifecycle processes and third-party penetration testing that smaller vendors struggle to fund.
- Legacy System Integration Complexity:Brownfield installations in established chemical and oil terminals require protocol gateways and physical layer adapters that increase commissioning cost and failure point exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Level Probe Market |
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,400.53 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive Probes, Ultrasonic Probes, Magnetic Probes, Radar Probes Technology: Wireless Technology, Guided Wave Technology, Optical Technology, Acoustic Technology End User: Oil & Gas Industry, Water Treatment Facilities, Food & Beverage Industry, Chemical Processing Plants Installation: Indoor Installation, Outdoor Installation, Tank Installation, Pipeline Installation |
| Companies Covered | Emerson Electric Co., ABB Ltd., Siemens AG, AMETEK Inc., Honeywell International Inc., Endress+Hauser Group Services AG, Magnetrol International Inc., Garner Industries LLC, OMEGA Engineering Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Level Probe Market Trends and Innovations
Measurement intelligence is migrating from centralized control systems toward distributed edge nodes, compressing response latency for safety-critical level alarms while enabling new predictive maintenance service architectures.
80 GHz FMCW radar technology is collapsing the performance gap between non-contact and guided wave configurations in solids level applications. Cement and grain elevator operators are adopting these units for dusty silo environments where mechanical plumb bob systems previously dominated. The shift is collapsing aftermarket service revenue tied to cable replacement and mechanical wear components.
The US EPA enforces Clean Water Act discharge monitoring standards that mandate certified level instrumentation at municipal treatment outfalls. Facilities must install redundant measurement points with data logging capabilities to demonstrate continuous compliance during inspection events. California and Texas utilities are accelerating procurement timelines to meet consent decree deadlines.
Buyers are unbundling hardware procurement from calibration and verification services, contracting third-party metrology firms for annual SIL proof-testing rather than relying on OEM service agreements. This disintermediation is most pronounced in European pharmaceutical manufacturing where FDA 21 CFR Part 11 compliance documentation requirements favor independent audit trails over vendor-managed records.
Smart Level Probe Market Segmentation
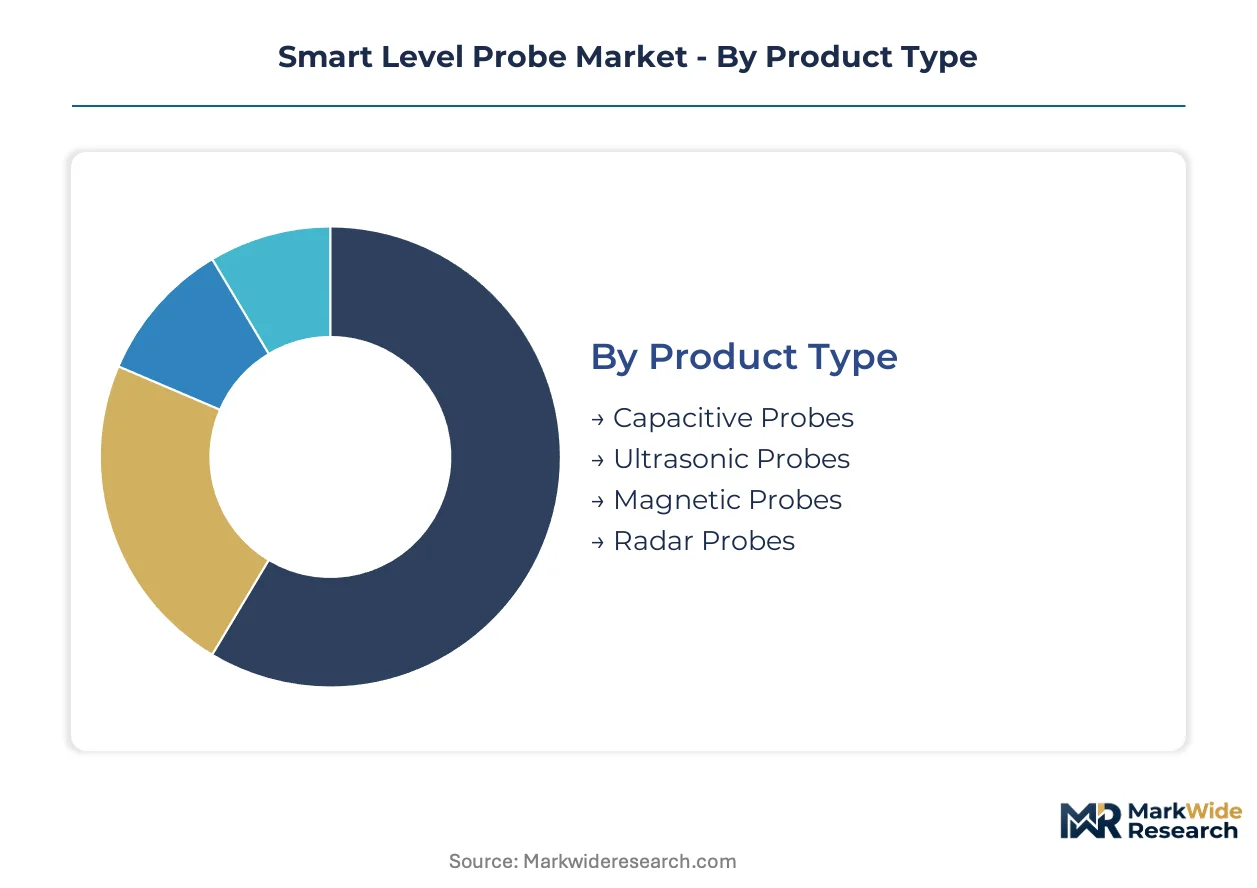
Smart level probe segmentation reflects divergent technical requirements across process environments. Technology choices determine total cost of ownership, while installation context dictates enclosure ratings and cabling architecture.
Product Type:
Mature electromagnetic and acoustic technologies coexist with emerging solid-state configurations across industrial verticals.
- Radar Probes:Frequency-modulated continuous wave transmitters operate through vapor, dust, and foam layers that blind optical alternatives. Petrochemical tank farms along the US Gulf Coast specify 80 GHz units for high-pressure reactor vessels where SIL certification is mandatory.
- Ultrasonic Probes:Piezoelectric transducers emit acoustic pulses for non-contact measurement in ambient-temperature water basins. German and Dutch municipal treatment facilities deploy these for EU Drinking Water Directive compliance at intake monitoring points.
- Capacitive Probes:Dielectric sensing elements suit conductive liquid detection in small vessel applications.
- Magnetic Probes:Float-actuated reed switch arrays provide electromechanical backup in legacy tank gauging systems.
Radar configurations command premium positioning in safety-critical applications; ultrasonic variants sustain volume leadership across water infrastructure.
Technology:
Signal transmission architecture separates capital-intensive wired installations from rapidly scaling battery-powered deployments.
- Wireless Technology:Mesh networking protocols eliminate trenching costs at remote wellpad separators and agricultural silo sites. Emerson Electric and ABB compete through integrated digital ecosystems that bundle hardware with cloud-based asset management subscriptions.
- Guided Wave Technology:Coaxial waveguide probes deliver precision measurement in turbulent liquid surfaces and low-dielectric solids. Oil and gas separator applications in the Permian Basin favor these units for safety-integrity compliance despite 40-60% raw material cost premiums.
- Optical Technology:Laser time-of-flight sensors serve specialized pharmaceutical tank applications requiring CIP/SIP compatibility.
- Acoustic Technology:Air-coupled ultrasonic systems monitor open-channel flow in irrigation and flood control infrastructure.
Wireless configurations are climbing the fastest as industrial IoT integration fragments legacy wired architectures; guided wave retains margin concentration in hazardous area certifications.
End User:
Regulatory intensity and automation maturity create distinct procurement patterns across process industries.
- Oil & Gas Industry:Upstream separators, midstream tank terminals, and downstream refining units demand explosion-proof enclosures and SIL-rated measurement chains. EPA Clean Water Act enforcement drives redundant level instrumentation at produced water treatment outfalls.
- Water Treatment Facilities:Municipal intake, process, and discharge monitoring positions require continuous level surveillance with data logging for regulatory demonstration. India AMRUT 2.0 funding is creating first-time networked monitoring demand at urban sewage plants.
- Food & Beverage Industry:FDA 21 CFR Part 11 documentation requirements shape probe selection for dairy and brewery tank applications.
- Chemical Processing Plants:Aggressive media compatibility and high-temperature tolerance specifications dominate reactor vessel specifications.
Water treatment facilities represent the broadest addressable base; oil and gas commands the highest per-unit specification intensity.
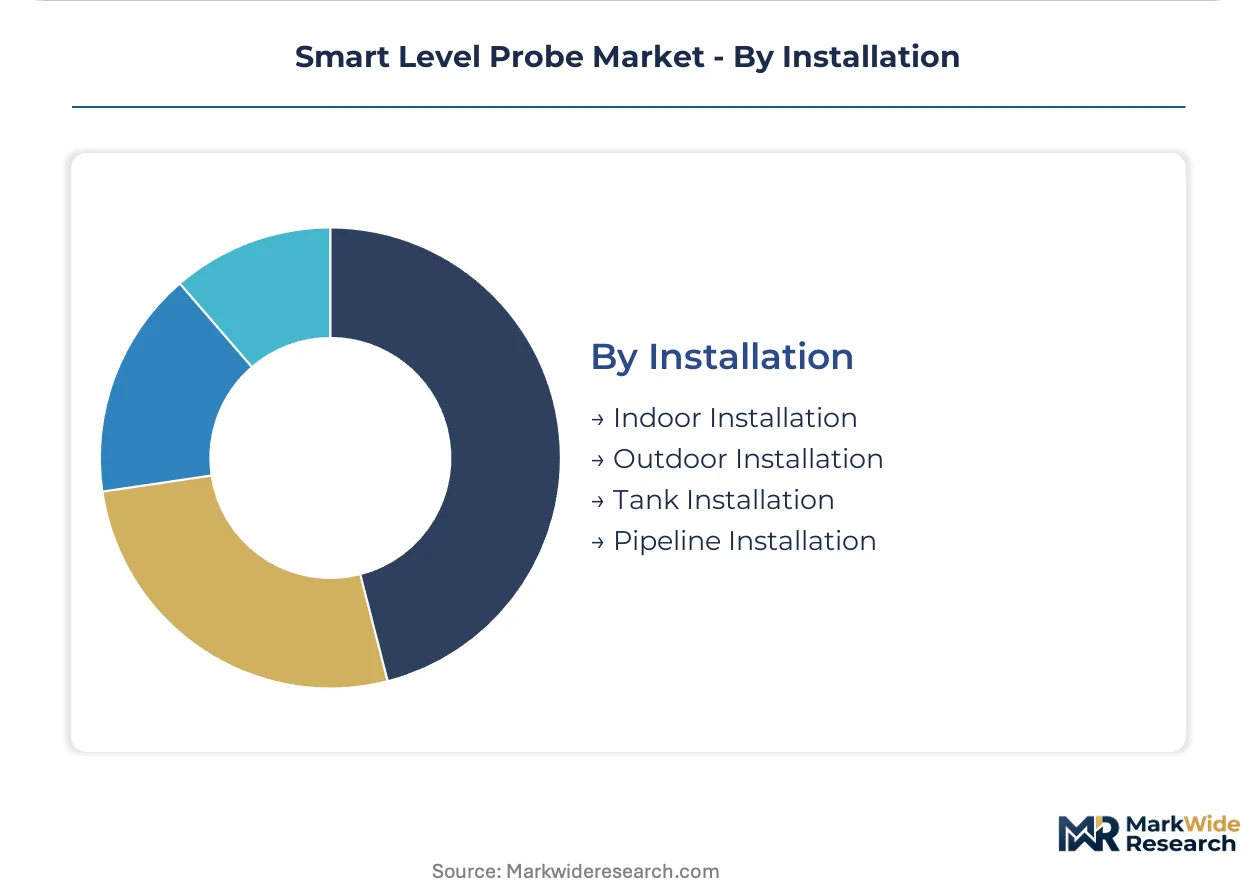
Installation:
Environmental exposure and vessel geometry dictate mechanical packaging and access requirements.
- Outdoor Installation:NEMA 4X and IP67 enclosures protect electronics against precipitation, temperature cycling, and UV degradation. Cold-climate Nordic deployments face EU F-Gas Regulation constraints on refrigerant-based purge systems.
- Tank Installation:Top-mounted, side-mounted, and stilling well configurations accommodate vessel geometry from small process tanks to bulk liquid storage. Cement and grain elevator operators are adopting 80 GHz radar for dusty silo environments.
- Indoor Installation:Controlled environment specifications reduce enclosure costs in packaged equipment skids.
- Pipeline Installation:Insertion probes and clamp-on alternatives monitor surge tanks and pig launcher receivers.
Tank installations anchor replacement demand across established process infrastructure; outdoor specifications are gaining share fastest with wireless networking expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for precision-machined waveguide assemblies and RF front-end modules concentrates supply risk in East Asian foundries, while demand expansion clusters around regulatory enforcement zones in North America and Western Europe.
United States
EPA Clean Water Act discharge monitoring mandates drive redundant level instrumentation procurement at municipal treatment outfalls in California and Texas. Gulf Coast petrochemical tank farms require SIL-certified measurement devices for overflow prevention systems. Houston and Corpus Christi anchor the highest specification intensity for explosion-proof radar probes in high-hazard storage facilities.
Germany
EU Drinking Water Directive revisions compel municipal utilities to expand continuous level surveillance at intake and discharge points. The F-Gas Regulation restricts refrigerant-based purge systems for ultrasonic installations in cold-climate regions. Bavaria and North Rhine-Westphalia concentrate water treatment facility modernization, with Düsseldorf and Munich integrators controlling channel access for Siemens AG deployments.
Netherlands
Stringent surface water quality standards accelerate probe deployment at Rhine-Meuse-Scheldt delta monitoring stations. Rotterdam's port authority mandates certified level instrumentation for chemical storage terminals under Seveso III implementation. Randstad region utilities lead European adoption of cloud-integrated asset management platforms for probe fleet optimization.
India
AMRUT 2.0 central government funding creates first-time demand for networked level monitoring at urban sewage treatment plants. The Central Electricity Authority mandates continuous surveillance instrumentation for thermal power plant cooling water systems. Maharashtra and Gujarat concentrate smart city initiative deployments, with Mumbai and Ahmedabad utilities procuring initial wireless sensor networks for distribution reservoir monitoring.
China
Dual carbon goals and wastewater treatment capacity expansion drive municipal probe procurement in Yangtze River Delta municipalities. The Ministry of Ecology and Environment enforces discharge monitoring standards that mirror EU directive structures. Shanghai and Jiangsu province chemical parks specify high-temperature radar probes for reactor vessel applications in polyethylene and polyester production clusters.
Smart Level Probe Market Competitive Landscape
On the supply side, the industry is consolidating around integrated digital ecosystems that bundle hardware with recurring software revenue streams. Tiered competitive positioning separates full-stack automation conglomerates from specialized sensor fabricators and regional component suppliers. Dominant competitive moves include strategic partnerships with cloud platform providers and vertical integration into edge computing silicon for on-device signal processing.
Within the integrated automation tier, Emerson Electric Co., ABB Ltd., and Siemens AG exemplify divergent geographic anchoring strategies. Emerson leverages its Plantweb digital ecosystem to capture premium positioning in North American wireless deployments. ABB competes through predictive maintenance service architectures extending to level probe fleets. Siemens dominates European utility applications through channel control across German-speaking integrator networks.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Siemens AG |
| AMETEK Inc. |
| Honeywell International Inc. |
| Endress+Hauser Group Services AG |
| Magnetrol International Inc. |
| Garner Industries LLC |
| OMEGA Engineering Inc. |
| Others |
Pricing and Supply Chain Analysis
Semiconductor component concentration in East Asian foundries determines both pricing tier spreads and supply chain shape, as custom ASICs and RF front-end modules for radar signal processing expose lead time volatility to geopolitical friction while forcing buyers into premium pricing for safety-certified alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with SIL-certified guided wave radar commanding 40-60% raw material cost premiums over non-contact ultrasonic alternatives due to precision-machined waveguide elements and high-temperature ceramic seals. Price differentiation separates explosion-proof enclosures for Gulf Coast petrochemical tank farms from basic IP67 configurations for municipal water basins, while subscription software bundling with cloud-based asset management platforms is displacing pure hardware transactional models. Pricing pressure stems from semiconductor sourcing bottlenecks as buyers absorb extended lead times or pay expedite premiums. Municipal utilities exhibit highest price sensitivity due to public procurement constraints, whereas oil and gas operators prioritize certification compliance over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced RF semiconductor technology limit flows from Taiwan, South Korea, and China, constraining domestic radar probe manufacturers' access to cutting-edge signal processing components. Precision-machined waveguide assemblies draw from German and Japanese metalworking specialists, while ceramic seal compounds rest on limited US and European specialty chemical suppliers. Single-source vulnerability concentrates in custom ASIC fabrication, where foundry capacity allocation favors consumer electronics over industrial automation runs. Distribution runs through authorized integrator networks in the DACH region and direct OEM relationships with Gulf Coast petrochemical operators, with cloud platform partnerships emerging as an alternative channel for wireless sensor networking deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from solid-state optical sensors and edge-AI enabled camera systems in non-hazardous tank applications, requiring defensive repositioning around certification moats and integrated software ecosystems.
For Market Incumbents: Build switching-cost moats through predictive maintenance service architectures that embed level probe fleets within cloud-based asset management platforms, creating data gravity that resists unbundling. Deepen backward integration into edge computing silicon for on-device foam pattern recognition, collapsing separate signal conditioning hardware and capturing margin from AI-enabled chemical reactor applications. Defend against ultrasonic probe commoditization in water treatment by anchoring premium positioning through EPA Clean Water Act compliance documentation and SIL-certified measurement chains that emerging optical substitutes cannot yet match.
For New Entrants and Emerging Players: Establish a beachhead in India's AMRUT 2.0-funded urban sewage treatment plants, where first-time networked monitoring demand creates greenfield procurement absent incumbent lock-in. Target wireless sensor networking deployments at remote agricultural silo installations and Permian Basin wellpad separators, where trenching economics favor battery-powered mesh protocols over wired infrastructure. Pursue white-label partnerships with cloud platform providers to bypass direct channel competition with Siemens AG's DACH integrator control and Emerson Electric's Plantweb ecosystem dominance.
For Investors and Strategic Acquirers: EPA consent decree deadlines for California and Texas municipal utilities reshape the acquisition landscape toward probe manufacturers with redundant measurement point expertise and data logging capabilities. Long-term viability favors vendors with recurring software revenue streams from predictive calibration drift alerts over pure hardware fabricators exposed to 80 GHz radar commoditization. Monitor EU F-Gas Regulation enforcement in Nordic markets as an inflection signal; design pivots away from refrigerant-based purge systems will separate adaptive suppliers from stranded asset holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Silicon Development | On-device inference for foam recognition collapses separate signal conditioning hardware in chemical reactors. |
| Cloud Platform Integration | Asset performance management subscriptions open recurring revenue through predictive calibration drift alerts. |
| Wireless Mesh Certification | Battery-powered protocols eliminate trenching costs at remote wellpad separators and agricultural silos. |
| SIL Certification Investment | Safety-integrity compliance anchors premium positioning in Gulf Coast petrochemical tank farm upgrades. |
| India Channel Development | AMRUT 2.0 funding creates first-time demand for networked monitoring at urban sewage treatment plants. |
Research Methodology
A spread of perspectives from plant engineers at petrochemical tank farms, municipal water utility procurement managers, OEM technical directors, and aftermarket service heads converged on the working assumptions, validated against customs records for precision-machined waveguide imports, SEC filings from automation conglomerates, EPA enforcement action databases, and EU Drinking Water Directive implementation reports. Bottom-up unit economics for radar and ultrasonic probe configurations triangulated against top-down addressable market sizing by end-use vertical.
Demand-supply balance modeling across the projection horizon segmented by technology type, installation architecture, end-use industry, and regional regulatory cluster, with CAGRs derived from historical replacement cycle analysis and greenfield infrastructure investment trajectories. Forecast inputs incorporated EU F-Gas Regulation compliance timelines, India smart city initiative funding disbursements, and 80 GHz FMCW radar adoption curves in cement and grain elevator solids measurement applications.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at Gulf Coast petrochemical operators or central government infrastructure funding continuity in India would shift the trajectory. Material shifts in export-control restrictions on RF semiconductor technology or EPA enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Reservoir Monitoring System Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market