
 Digital Radiography Sensor Market | 2026-2036
Digital Radiography Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Radiography Sensor Market Analysis
Subscription-based software-defined image processing is recalibrating what equipment vendors monetize beyond hardware shipments. Siemens Healthineers leverages integrated AI-enhanced reconstruction modules to sustain recurring revenue per installed detector. Carestream Health Inc. anchors its competitiveness in North American outpatient imaging chains through remote calibration services. Fujifilm Holdings Corporation differentiates via proprietary phosphor plate chemistry that extends sensor lifecycle in high-throughput hospital environments.
Digital radiography sensors are solid-state photon-counting or energy-integrating devices that convert X-ray attenuation into electrical signals for diagnostic image formation, typically employing amorphous selenium or cesium iodide scintillator layers on thin-film transistor backplanes. Their primary purpose is to replace analog film and computed radiography plates with immediate digital readout, reducing patient dose and eliminating chemical processing infrastructure. Flat panel detectors occupy the dominant revenue position due to universal compatibility with existing radiography suites and superior spatial resolution for thoracic and orthopedic protocols. Wireless sensors represent the fastest-expanding category as battery efficiency and data transmission protocols enable portable bedside imaging in emergency and intensive care settings. Digital cassette systems retain niche utility in veterinary and budget-constrained outpatient facilities where full room replacement is capital-prohibitive.
FDA 510(k) premarket notification requirements govern sensor safety and electromagnetic compatibility for US market entry, while the EU Medical Device Regulation imposes clinical evidence thresholds for Class IIa imaging devices sold in European Economic Area member states. The EPA's radiation protection standards indirectly shape sensor design through dose optimization mandates that manufacturers must document in premarket submissions. Stakeholders should monitor evolving cybersecurity guidance from FDA and notified bodies, as networked detector architectures introduce patient data exposure vectors that regulators are actively addressing through postmarket surveillance expansion.
Market Dynamics
Hospital procurement consortiums in Germany are consolidating purchasing power around flat-panel detector architectures, compressing vendor margins and accelerating standardization across radiology departments previously fragmented by equipment generation.
Growth Catalysts
- EPA radiation protection standards:Dose optimization mandates documented in FDA 510(k) premarket submissions compel healthcare facilities to replace film-based systems with digital sensors that reduce patient exposure.
- Emergency and intensive care settings:Battery efficiency gains in wireless sensors enable portable bedside imaging, expanding addressable use cases beyond fixed radiography suites.
- Amorphous selenium conversion layers:Direct-conversion photon-counting architectures deliver superior spatial resolution for thoracic protocols, pulling demand from orthopedic and mammography applications.
Market Restraints
- Cesium iodide scintillator supply concentration:Thin-film transistor backplane manufacturing concentrates in East Asian foundries, exposing detector OEMs to single-source substrate risks.
- EU Medical Device Regulation clinical evidence thresholds:Class IIa imaging devices face extended notified body review timelines that delay European Economic Area market entry by quarters.
- Computed radiography plate residual utility:Budget-constrained veterinary clinics and rural outpatient facilities retain phosphor plate systems where full room replacement capital is unavailable.
Strategic Opportunities
- Subscription-based software-defined image processing:Integrated AI-enhanced reconstruction modules enable recurring revenue streams per installed detector beyond hardware shipment margins.
- Remote calibration services:North American outpatient imaging chains adopt predictive maintenance contracts that lock in vendor relationships through software-tethered service tiers.
- India diagnostic infrastructure expansion:Central government health scheme procurement creates first-time digital radiography demand in tier-two and tier-three cities previously served by analog film.
Industry Challenges
- Interoperability with legacy PACS architectures:DICOM conformance testing for networked detector integration consumes engineering resources and extends deployment timelines.
- Postmarket cybersecurity surveillance expansion:FDA guidance on networked detector patient data exposure vectors requires continuous vulnerability monitoring and patch management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Radiography Sensor Market |
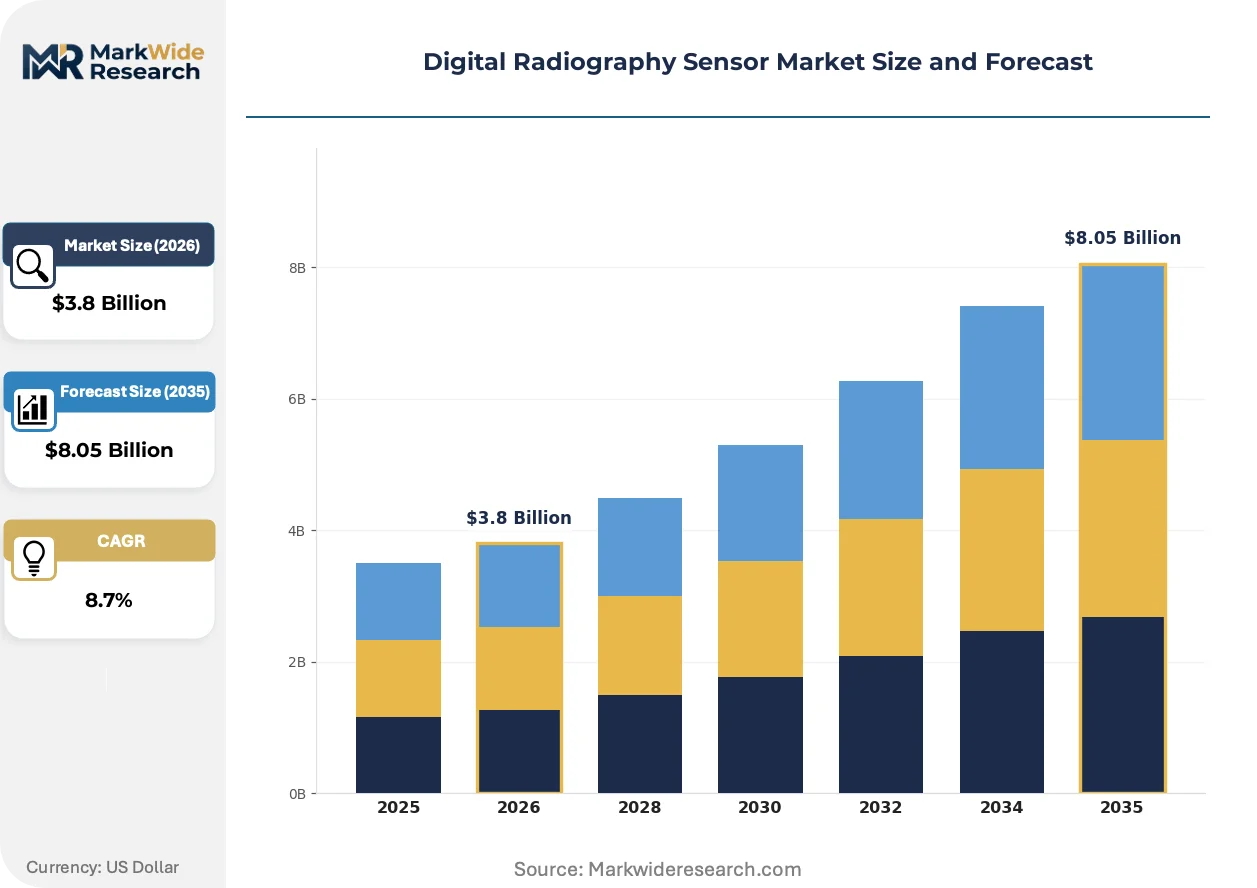
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Detectors, Computed Radiography Sensors, Wireless Sensors, Digital Cassette Systems End User: Hospitals, Diagnostic Imaging Centers, Research Institutions, Outpatient Facilities Technology: Ceramics, Photostimulable Phosphor, LED, Charge-Coupled Device Application: Dental Imaging, Thoracic Imaging, Orthopedic Imaging, Veterinary Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Inc., Fujifilm Holdings Corporation, Carestream Health Inc., Hologic Inc., Shimadzu Corporation, Agfa-Gevaert Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Radiography Sensor Market Emerging Trajectories
Detector architectures are fragmenting into specialized form factors optimized by care setting, while regulatory pressure on dose accountability and data security reshapes how vendors monetize hardware through software attachments.
Photon-counting detector technology is modularizing across dual-layer configurations that separate high and low energy spectra for material decomposition imaging. Academic medical centers in Switzerland and the Netherlands are piloting these systems for quantitative tissue characterization. The structural consequence is compressing the upgrade cycle from decade-long equipment replacement to component-level sensor swaps that preserve room infrastructure.
EU AI Act risk classification rules are redefining which image reconstruction algorithms require conformity assessment before clinical deployment. Manufacturers must now document training data provenance and performance drift monitoring for machine learning modules embedded in detector firmware. European radiology departments are responding by demanding vendor transparency on algorithm update protocols and version control.
After-sales service unbundling is fragmenting traditional equipment lease bundles into discrete software, hardware, and calibration subscriptions. Outpatient imaging chains in the United States are negotiating à la carte maintenance contracts that separate detector warranty from image processing license fees. This shift is most visible in Texas and Florida markets where private equity-backed radiology platforms aggregate purchasing across dozens of sites.
Digital Radiography Sensor Market Segmentation
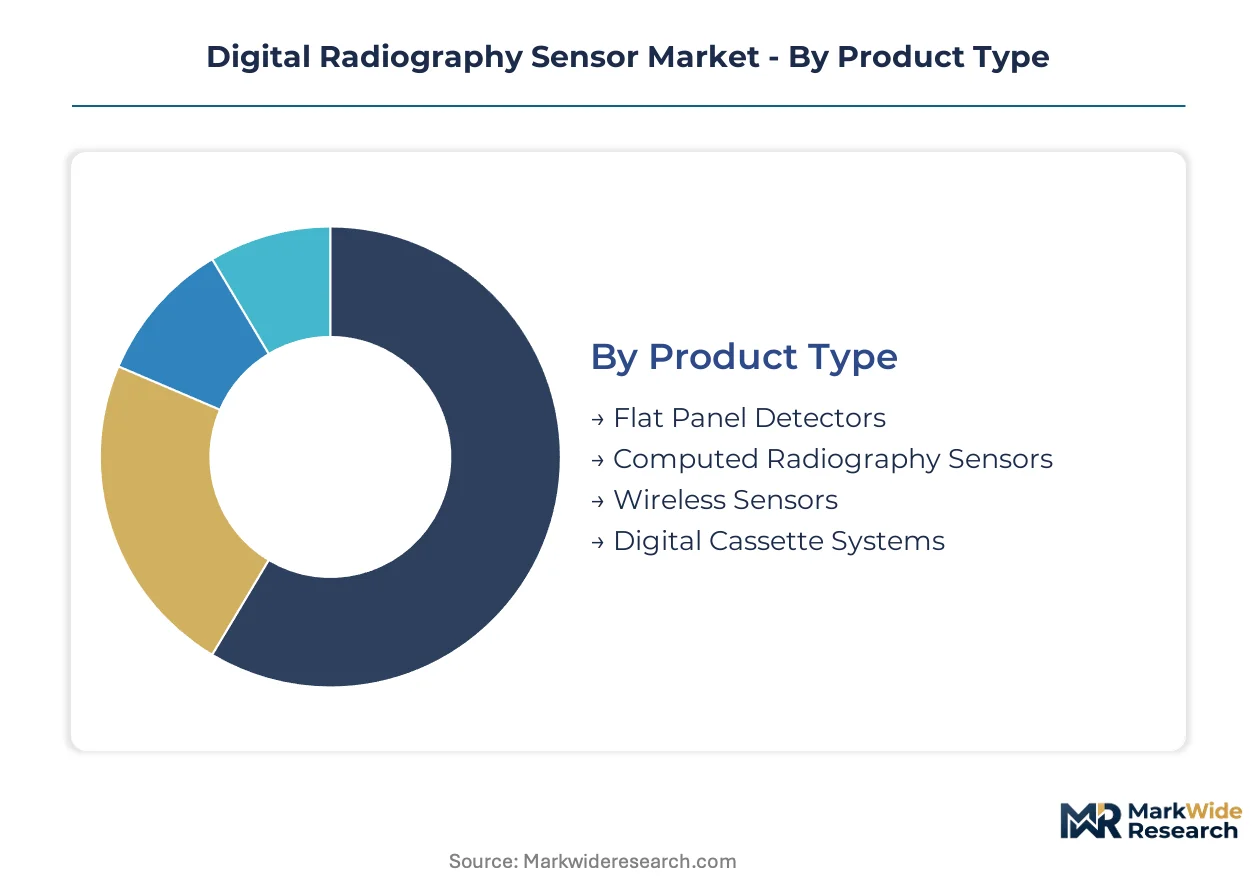
Digital radiography sensor procurement splits sharply between high-throughput hospital installations demanding premium specifications and cost-sensitive outpatient settings prioritizing capital efficiency. Technology choices cascade through detector architecture, software integration requirements, and service contract structures that lock in vendor relationships for decade-long replacement cycles.
Product Type:
Volume shipments concentrate in flat-panel architectures while premium pricing migrates toward wireless form factors that command service-attachment multiples.
- Flat Panel Detectors:Amorphous selenium direct-conversion layers on thin-film transistor backplanes deliver the spatial resolution thresholds required for thoracic and orthopedic protocols. Hospital procurement consortiums in Germany standardize procurement around this architecture, compressing vendor margins through consolidated purchasing power.
- Wireless Sensors:Battery-efficient photon-counting arrays with optimized data transmission protocols enable portable bedside imaging in emergency and intensive care settings. North American dental clinics are expanding wireless fleets to replace aging film-based systems, pulling demand from fixed-suite alternatives.
- Computed Radiography Sensors:Photostimulable phosphor plates retain residual utility in budget-constrained veterinary clinics where full room replacement capital remains unavailable.
- Digital Cassette Systems:Drop-in retrofit form factors serve rural outpatient facilities transitioning from analog film without infrastructure overhaul.
Today's leader: Flat Panel Detectors. Tomorrow's challenger: Wireless Sensors.
End User:
Customer concentration shifts from inpatient radiology departments toward distributed outpatient networks that prioritize equipment mobility and rapid patient throughput.
- Hospitals:Radiology departments in academic medical centers demand detector architectures compatible with legacy PACS infrastructure and AI-enhanced reconstruction modules. Swiss and Dutch academic centers pilot dual-layer photon-counting configurations for quantitative tissue characterization.
- Diagnostic Imaging Centers:Private equity-backed radiology platforms in Texas and Florida aggregate purchasing across dozens of sites, negotiating à la carte maintenance contracts that separate detector warranty from image processing license fees.
- Research Institutions:Pilot installations of modular sensor configurations support component-level upgrade cycles that preserve room infrastructure.
- Outpatient Facilities:Tier-two and tier-three cities in India generate first-time digital radiography demand through central government health scheme procurement.
Procurement gravity centers on Diagnostic Imaging Centers. Steepest expansion trajectory: Outpatient Facilities.
Technology:
Material science differentiation separates premium direct-conversion architectures from scintillator-based alternatives competing on manufacturing scale.
- Ceramics:Cesium iodide scintillator layers deposited on ceramic substrates dominate manufacturing throughput, though thin-film transistor backplane concentration in East Asian foundries exposes OEMs to single-source substrate risks.
- Photostimulable Phosphor:Europium-doped barium fluorohalide crystals enable computed radiography plate reusability, extending sensor lifecycle in high-throughput hospital environments through proprietary chemistry optimization.
- LED:Solid-state illumination arrays support intraoral sensor miniaturization for dental applications requiring confined-space maneuverability.
- Charge-Coupled Device:Legacy silicon-based architectures retain niche deployment in veterinary imaging where resolution requirements trail human diagnostic thresholds.
Scale leader: Ceramics. Technology pivot point: Photostimulable Phosphor.
Application:
Clinical use case fragmentation drives detector specialization, with dose accountability mandates reshaping technology selection by anatomical target.
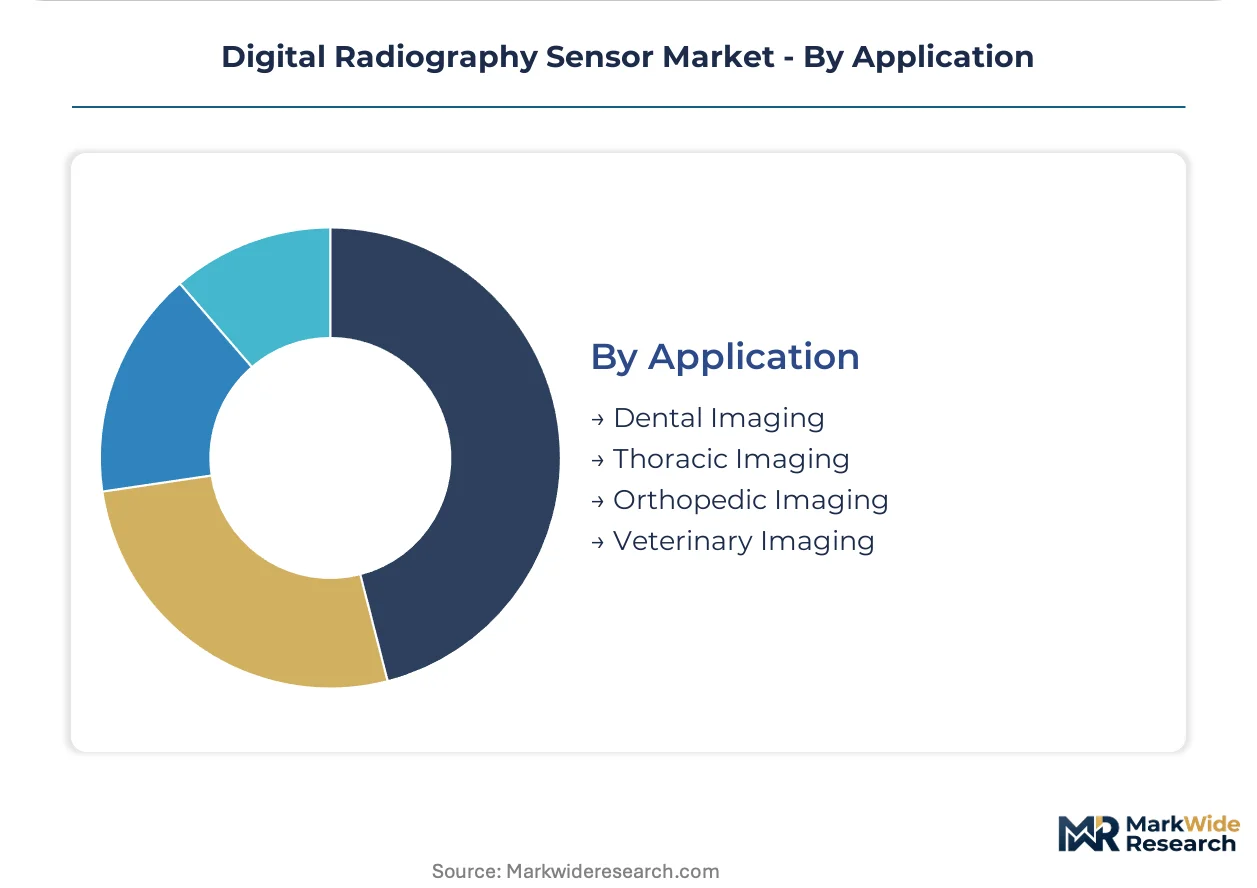
- Dental Imaging:Intraoral sensor miniaturization demands CMOS-based architectures with fiber-optic tethers or wireless transmission protocols. FDA clearance pathways for wireless detector submissions are compressing review timelines, accelerating fleet replacement cycles.
- Thoracic Imaging:Direct-conversion amorphous selenium delivers the quantum efficiency and spatial resolution required for lung parenchyma visualization, pulling demand from orthopedic and mammography applications.
- Orthopedic Imaging:Weight-bearing extremity protocols favor large-field flat-panel configurations with rapid image acquisition to minimize patient motion artifacts.
- Veterinary Imaging:Species-adapted cassette sizes and reduced dose protocols serve companion animal practices and equine referral hospitals.
Revenue concentration: Thoracic Imaging. Segment gaining share fastest: Dental Imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany compresses vendor margins through hospital procurement consortiums, while the United States accelerates wireless sensor adoption through compressed FDA review timelines.
Germany
Hospital procurement consortiums concentrate purchasing power around flat-panel detector architectures, standardizing radiology departments previously fragmented by equipment generation. The EU Medical Device Regulation imposes clinical evidence thresholds for Class IIa imaging devices, extending notified body review timelines. Bavarian medical technology clusters anchor detector manufacturing and service operations for Central European distribution.
United States
Dental clinics expand digital imaging fleets to replace aging film-based systems, pulling demand toward wireless sensor configurations. FDA 510(k) premarket notification requirements govern sensor safety and electromagnetic compatibility, with review timelines compressing for wireless detector submissions. Texas and Florida outpatient imaging chains negotiate à la carte maintenance contracts that separate detector warranty from software license fees.
India
Central government health scheme procurement generates first-time digital radiography demand in tier-two and tier-three cities previously served by analog film. The country's national medical device regulator establishes quality standards for imported imaging equipment under CDSCO jurisdiction. Maharashtra and Gujarat diagnostic infrastructure clusters absorb the bulk of public procurement allocations for radiology equipment.
Switzerland
Academic medical centers pilot dual-layer photon-counting configurations for quantitative tissue characterization, compressing upgrade cycles from decade-long replacement to component-level sensor swaps. Swissmedic oversees clinical evidence requirements for novel detector modalities entering the national market. Basel and Zurich research hospital networks coordinate cross-border pilot programs with Dutch academic centers.
Japan
Domestic manufacturers leverage proprietary phosphor plate chemistry to extend sensor lifecycle in high-throughput hospital environments. PMDA review pathways for digital radiography equipment align with international harmonization initiatives for medical device approvals. Osaka and Nagoya industrial corridors concentrate thin-film transistor backplane manufacturing for regional detector OEM supply.
Digital Radiography Sensor Market Vendor Landscape
Top-tier vendors anchor premium-tier positioning through integrated software-hardware bundles, while mid-scale specialists compete on service-attachment multiples and regional customization. The market structure concentrates around conglomerate healthcare divisions with captive distribution networks and dedicated imaging software units. Three archetypes dominate: diversified medical technology conglomerates with full-modality portfolios, pure-play detector manufacturers with component-level specialization, and regional system integrators with service-heavy business models. Competitive moves center on M&A for AI reconstruction capabilities and strategic partnerships for phosphor plate chemistry access.
Within the conglomerate tier, Siemens Healthineers and GE Healthcare exemplify integrated healthcare technology positioning, while Fujifilm Holdings Corporation occupies a distinct niche through materials science heritage in imaging substrates. These three entities represent the dominant competitive anchors against which specialized detector manufacturers and regional service providers calibrate their market entry strategies.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Inc. |
| Fujifilm Holdings Corporation |
| Carestream Health Inc. |
| Hologic Inc. |
| Shimadzu Corporation |
| Agfa-Gevaert Group |
| Others |
Supply Flow & Price Mechanics
Thin-film transistor backplane engineering talent concentration in Osaka and Nagoya industrial corridors feeds labor-cost differentials that widen pricing-tier spreads between premium photon-counting architectures and standard scintillator-based alternatives. Detector OEMs leverage this geographic specialization to stratify procurement offerings across hospital consortiums, outpatient chains, and budget-constrained rural facilities.
Pricing Analysis
Capacity additions in East Asian foundries are reshaping price floors for cesium iodide scintillator substrates, compressing margins on mid-tier flat-panel configurations. Pricing stratifies across premium, standard, and economy tiers based on spatial resolution certification and after-sales service bundling. Cost compression in the standard tier is intensifying because German hospital procurement consortiums consolidate purchasing power. Outpatient imaging chains in Texas and Florida exhibit the highest price sensitivity, while Swiss academic medical centers demonstrate the least.
Supply Chain Analysis
Dual-sourcing qualification requirements from major hospital systems are forcing detector OEMs to qualify secondary thin-film transistor backplane suppliers beyond their primary East Asian foundry relationships. Manufacturing concentrates in Japan, South Korea, and Taiwan for TFT backplanes, with cesium iodide scintillator crystal growth anchored in Japanese and Chinese chemical processing facilities. Supply chain risk centers on single-source vulnerability for amorphous selenium deposition equipment. Distribution runs through regional medical device distributors with specialized radiology equipment service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through the regulatory cost differential between FDA 510(k) review timelines in the United States and extended EU Medical Device Regulation notified body assessments in Europe.
For Market Incumbents: Deploy software-tethered service tiers to lock in hospital procurement relationships against pure-play detector manufacturers offering unbundled hardware pricing. Siemens Healthineers and GE Healthcare should deepen backward integration into phosphor plate chemistry to defend margin position against Fujifilm's materials science heritage. Prioritize AI-enhanced reconstruction module certification under EU AI Act risk classification rules to preempt regulatory displacement. For New Entrants and Emerging Players: Capture tier-two and tier-three city demand in India through central government health scheme procurement channels, where first-time digital radiography installations outpace replacement cycles in saturated Western markets. Target veterinary imaging as the most penetrable segment, where resolution requirements trail human diagnostics and incumbent service infrastructure remains underdeveloped. Pursue channel partnerships with regional medical device distributors rather than direct hospital sales. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with full-modality portfolios are the most active acquirer in this space, seeking AI reconstruction capabilities through component-level specialist acquisitions. Long-term viability hinges on software-defined monetization transition completion within the next decade. Watch FDA cybersecurity guidance expansion as the inflection signal for postmarket surveillance cost escalation that favors scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Wireless Detector | Compressed review timelines accelerate fleet replacement cycles in North American dental clinics. |
| CE Marking Pathway for AI Module | EU AI Act conformity requirements reshape algorithm deployment protocols for European radiology departments. |
| Hospital System Partnership | German procurement consortiums standardize flat-panel architectures through consolidated purchasing power. |
| Software Companion Development | Subscription-based image processing enables recurring revenue streams beyond hardware shipment margins. |
| Reimbursement Strategy | EPA dose optimization mandates drive replacement demand from film-based systems in outpatient settings. |
Methodological Framework
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and radiology department heads grounded qualitative findings in procurement decision dynamics. Secondary validation drew from FDA 510(k) premarket notification databases, EU Medical Device Regulation notified body guidance documents, hospital procurement consortium contract filings, and CMS Medicare reimbursement schedules. Bottom-up sensor shipment estimates triangulated against top-down healthcare capital expenditure projections.
Top-down macroeconomic indicators anchored the analytical lens while bottom-up vendor shipment data refined segment-level allocations across the projection horizon. Segmentation dimensions modeled include detector architecture, end-user facility type, technology material, and clinical application protocol. CAGRs derived from regression analysis of historical replacement cycles and procurement pipeline visibility. Forecast inputs incorporated FDA review timeline compression rates and EU AI Act implementation phase-in schedules.
Regulatory timeline delays, supply chain disruption in thin-film transistor substrate manufacturing, and cybersecurity incident frequency are the dominant revision risks to the outlook. Deviation in FDA wireless detector clearance velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Acoustic Wave Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Meteorological Devices Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Global Single Loop Controller Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Sensor Hub Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Battery Monitor Market