
 Latin America Wireless Sensors Market | 2026-2036
Latin America Wireless Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Wireless Sensors Market Foresight
Market Context
Aftermarket service revenue from sensor calibration and predictive maintenance platforms is reshaping margin distribution across the Latin America wireless sensors value chain. Honeywell International Inc. leverages its industrial automation heritage to anchor premium service contracts with oil and gas operators in Brazil and Mexico. Emerson Electric Co. competes through specialized vibration and acoustic monitoring solutions tailored to Latin American mining and petrochemical installations. Siemens AG controls a significant share of smart building retrofit projects, extending its digital infrastructure footprint across urban commercial centers in the region.
Technical Definition and Segment Structure
Latin America wireless sensors encompass self-contained transducer devices that convert physical phenomena into radio-frequency signals for remote data acquisition, typically operating on sub-gigahertz ISM bands or 2.4 GHz protocols with power budgets under 100 milliwatts for battery-constrained deployments. These instruments serve industrial process optimization, environmental compliance, and asset visibility across geographically dispersed operations where wired infrastructure proves uneconomical. Temperature sensors dominate volume shipments due to their ubiquity in cold chain logistics and agricultural climate control, while LoRaWAN technology captures the fastest expansion trajectory driven by long-range, low-power requirements in Brazilian agribusiness and Mexican pipeline networks. Pressure sensors sustain premium pricing in oil and gas applications where hazardous area certification and precision specifications create substantial barriers to commoditization.
Regulatory Framework and Outlook
Brazil's ANATEL spectrum allocations for unlicensed IoT bands, Mexico's federal energy regulatory standards for pipeline monitoring, and Argentina's INTI quality certification requirements collectively shape product compliance pathways and market access conditions for wireless sensor vendors. ANATEL's evolving framework for massive IoT deployments directly determines which transmission technologies achieve commercial scale in Brazilian territory. Stakeholders must monitor regulatory harmonization progress across Mercosur member states, as divergent certification timelines and technical standards fragment procurement decisions and complicate regional platform rollouts.
Market Dynamics
LoRaWAN protocol standardization across Brazilian agribusiness and Mexican energy infrastructure is compressing deployment timelines and forcing hardware vendors to consolidate firmware stacks around sub-gigahertz spectrum efficiency.
Growth Catalysts
- ANATEL spectrum allocations:Brazil's unlicensed IoT band frameworks enable massive sensor deployments without spectrum licensing costs, accelerating precision agriculture adoption in Mato Grosso soybean corridors.
- Pipeline surveillance mandates:Mexico's federal energy regulatory standards require real-time pressure and leak detection across Pemex distribution networks, creating guaranteed demand for hazardous-area-certified wireless nodes.
- Bluetooth proximity sensing:Automotive assembly automation in Argentina's Córdoba manufacturing belt drives concentrated procurement of short-range positioning sensors for robotic coordination systems.
Market Restraints
- Lithium battery supply concentration:Primary cell dependency on Chilean and Argentine lithium carbonate processing creates input cost volatility for battery-constrained sensor designs.
- Certification fragmentation:Divergent INTI quality timelines across Mercosur member states extend product approval cycles and inflate compliance overhead for multi-country vendors.
- Wired infrastructure persistence:Existing 4-20mA loop installations in Brazilian petrochemical plants resist wireless retrofit where explosion-proof cabling already satisfies insurance underwriters.
Strategic Opportunities
- Colombian mining corridors:Untapped Andean copper and gold extraction operations present first-mover potential for vibration and acoustic monitoring networks in tailings dam surveillance.
- Edge-AI convergence:On-device inference chips combined with mmWave sensing enable predictive maintenance without cloud dependency, appealing to remote Chilean mining camps with intermittent connectivity.
- Smart building retrofits:Mexico City's commercial real estate efficiency mandates create procurement channels for HVAC-integrated temperature and occupancy sensor arrays in Class A office stock.
Industry Challenges
- RF engineering talent scarcity:Sub-gigahertz antenna design and mesh network optimization skills concentrate in São Paulo and Mexico City, inflating compensation for field deployment teams.
- Legacy SCADA integration:Modbus and Profibus protocol translation layers introduce latency and failure points when bridging decades-old control systems with IP-native wireless gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Wireless Sensors Market |
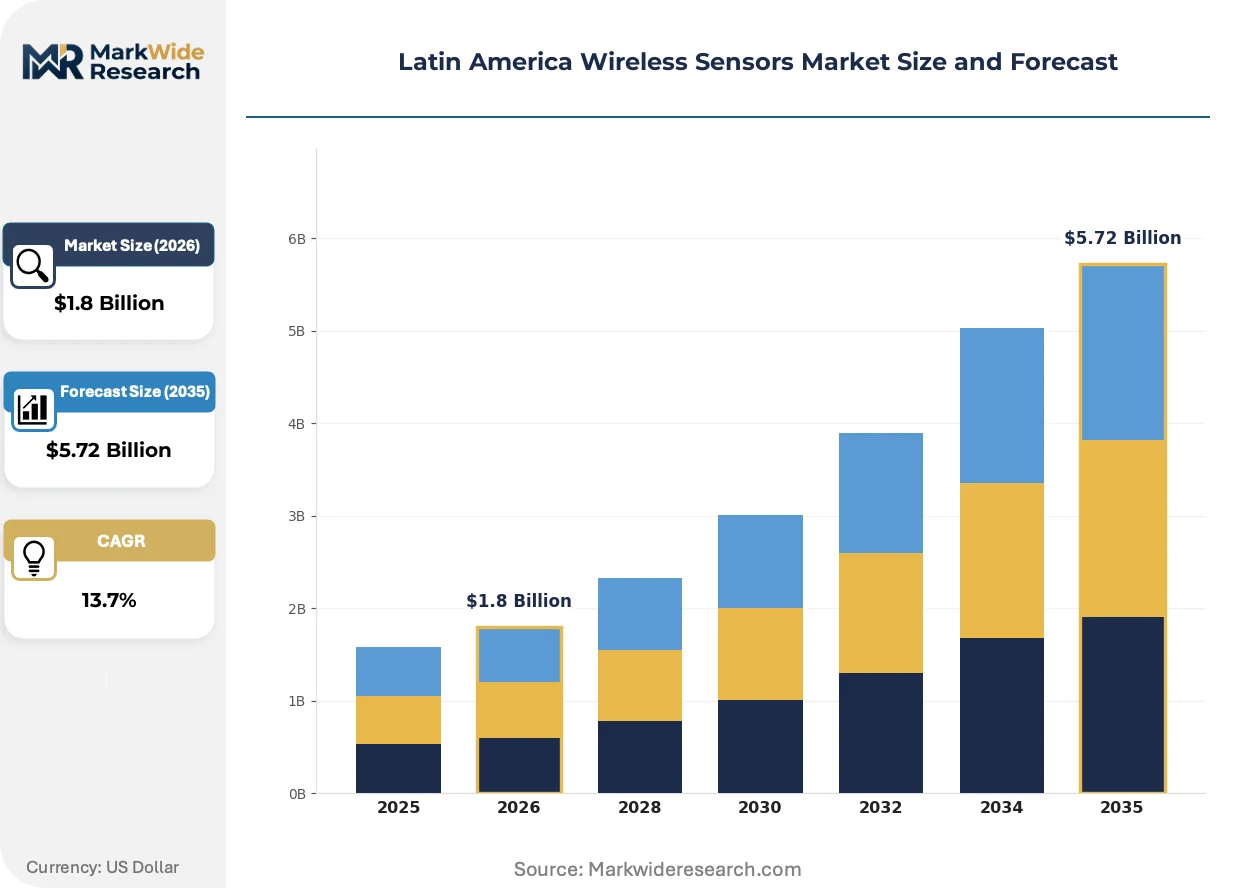
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Humidity Sensors, Proximity Sensors Technology: Bluetooth, Zigbee, LoRaWAN, NFC End User: Agriculture, Oil & Gas, Automotive, Healthcare Application: Asset Tracking, Environmental Monitoring, Home Automation, Industrial Automation |
| Companies Covered | Honeywell International Inc., Emerson Electric Co., ABB Ltd., Texas Instruments Incorporated, Pasco Scientific, Monnit Corporation, Schneider Electric, Siemens AG, Infineon Technologies AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Wireless Sensors Market Shifts & Advancements
Energy harvesting and ambient power scavenging are eliminating battery replacement cycles in remote agricultural and pipeline monitoring applications across the region.
Photovoltaic-thermal hybrid harvesters is migrating from laboratory prototypes to commercial soil moisture nodes in Brazilian citrus groves, where six-month dry seasons previously dictated lithium primary cell swaps. Large agribusiness cooperatives in São Paulo state are piloting dye-sensitized solar cells integrated with supercapacitor buffers, eliminating truck rolls for battery maintenance in thousand-hectare monitoring grids. This migration from electrochemical to ambient power is compressing total cost of ownership calculations and extending competitive bids to ten-year service horizons.
Brazil's ANATEL Resolution 680 is mandating interoperability testing for massive IoT devices operating in 902-928 MHz and 433 MHz bands, forcing chipset vendors to submit unified certification packages rather than country-specific variants. The industrial consequence is a consolidation of firmware development resources around reference designs that satisfy multiple Latin American regulators simultaneously. Oil and gas sensor suppliers targeting Brazilian pre-salt platforms are responding by pre-certifying LoRaWAN modules against both ANATEL and Mexico's IFT requirements, accelerating cross-border procurement.
Aftermarket calibration services are unbundling from original hardware sales as Brazilian cold chain operators and Mexican pipeline maintenance contractors seek specialized metrology providers. Third-party service bureaus in Guadalajara and Campinas are displacing manufacturer-direct support contracts through accredited laboratories offering faster turnaround on pressure sensor recertification. This pattern is most visible in pharmaceutical distribution networks where ANVISA temperature mapping requirements demand quarterly probe validation that hardware OEMs cannot economically provision.
Latin America Wireless Sensors Market Segmentation
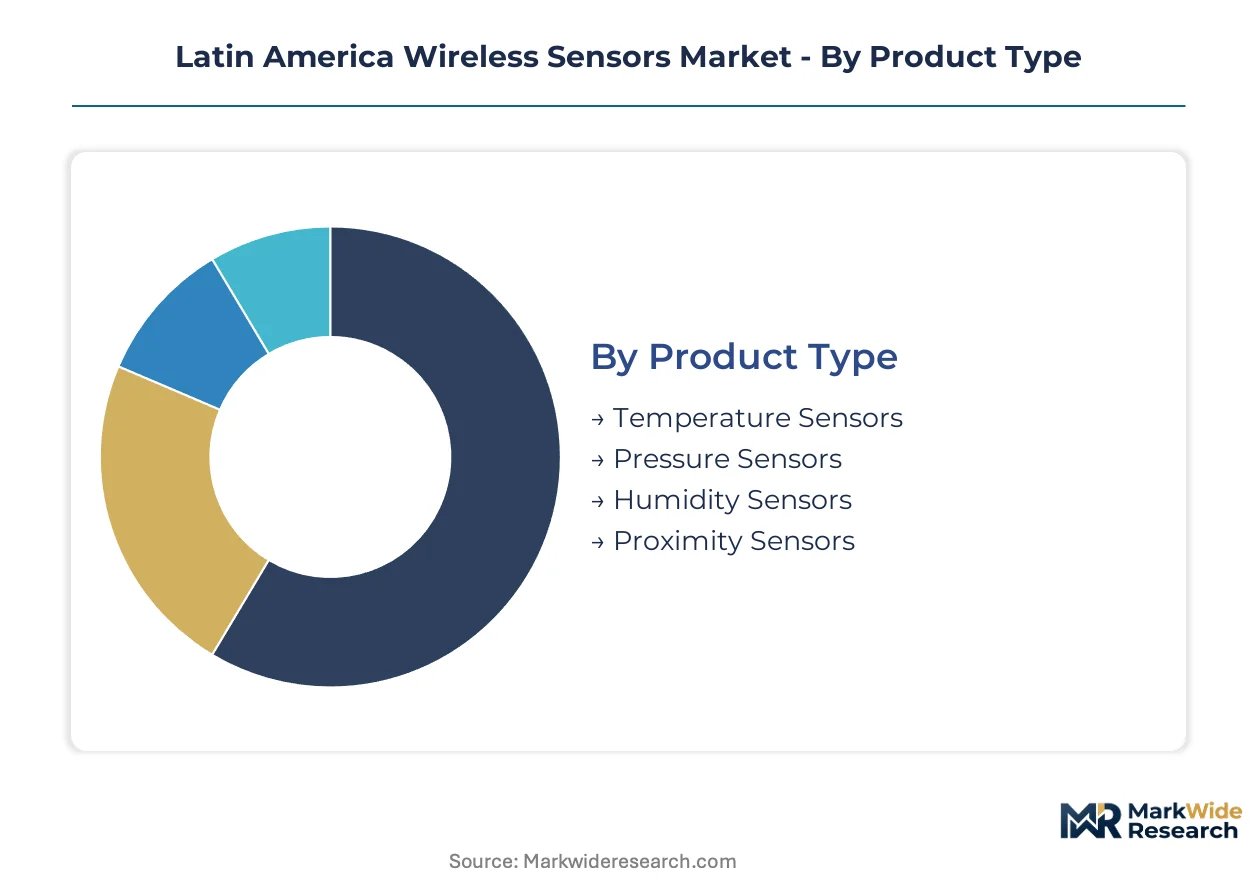
Segmentation of the Latin America wireless sensors market reveals how protocol selection, physical measurement type, and vertical deployment requirements create distinct procurement channels across Brazilian agribusiness, Mexican energy infrastructure, and Argentine manufacturing corridors.
Product Type:
Temperature and pressure sensors anchor fundamentally different commercial models—commodity volume versus certified premium—across regional cold chain logistics and hazardous-area industrial monitoring.
- Temperature Sensors:Thermistor and RTD-based nodes with ±0.5°C accuracy dominate pharmaceutical cold chain validation across Brazil's ANVISA-regulated distribution networks. São Paulo state cold storage operators deploy thousands of battery-powered probes for continuous vaccine and biologic monitoring, where calibration drift triggers mandatory replacement cycles.
- Pressure Sensors:Piezoresistive transducers certified for IECEx Zone 0/1 deployment capture premium pricing in Pemex pipeline networks and Brazilian pre-salt platform monitoring. Mexican federal energy mandates require real-time pressure telemetry across 12,000 kilometers of hydrocarbon distribution infrastructure.
- Humidity Sensors:Capacitive polymer sensing elements protect grain storage assets in Mato Grosso soybean cooperatives.
- Proximity Sensors:Inductive and capacitive variants coordinate robotic assembly sequences in Córdoba automotive manufacturing clusters.
The dominant share belongs to temperature sensors, while pressure sensors are closing the gap fastest on hazardous-area certification premiums.
Technology:
Protocol selection hinges on range-power tradeoffs, with sub-gigahertz long-range networks displacing mesh topologies in geographically dispersed agricultural and pipeline surveillance applications.
- LoRaWAN:Sub-gigahertz chirp spread spectrum modulation enables 15-kilometer range at sub-50mW power budgets, making it the default choice for Brazilian citrus grove soil monitoring and Mexican pipeline leak detection. ANATEL's 902-928 MHz band allocation and Mexico's IFT harmonization allow single firmware stacks to serve both markets.
- Bluetooth:2.4 GHz Low Energy stacks with sub-10 meter range concentrate in Argentine automotive assembly lines and Mexican hospital asset tracking, where high-density node deployment favors mesh self-healing over long-range penetration.
- Zigbee:IEEE 802.15.4-based mesh networks persist in legacy smart building retrofits across Mexico City commercial real estate.
- NFC:13.56 MHz passive coupling serves localized sensor configuration and maintenance authentication in Brazilian pharmaceutical cold chain probe commissioning.
LoRaWAN holds the installed base advantage, though Bluetooth is expanding most quickly through automotive and healthcare proximity applications.
End User:
Vertical demand patterns split between outdoor environmental monitoring requiring weatherproofing and explosion-proof industrial certification versus indoor controlled environments prioritizing compact form factors.
- Agriculture:Precision farming operations in Brazil's Mato Grosso and São Paulo states drive soil moisture, climate, and irrigation monitoring node procurement. Large cooperatives operate thousand-hectare sensor grids where battery maintenance costs dominate total ownership calculations.
- Oil & Gas:Mexican pipeline surveillance mandates and Brazilian pre-salt platform monitoring create guaranteed demand for hazardous-area-certified pressure, vibration, and acoustic sensors with SIL-rated reliability specifications.
- Automotive:Córdoba manufacturing belt assembly plants deploy Bluetooth-enabled proximity sensors for robotic coordination and quality control automation.
- Healthcare:Brazilian hospital networks and pharmaceutical distributors require continuous temperature and humidity validation for regulatory compliance with ANVISA cold chain standards.
Agriculture commands the largest volume deployment, while oil and gas generates the highest per-node revenue through certification premiums.
Application:
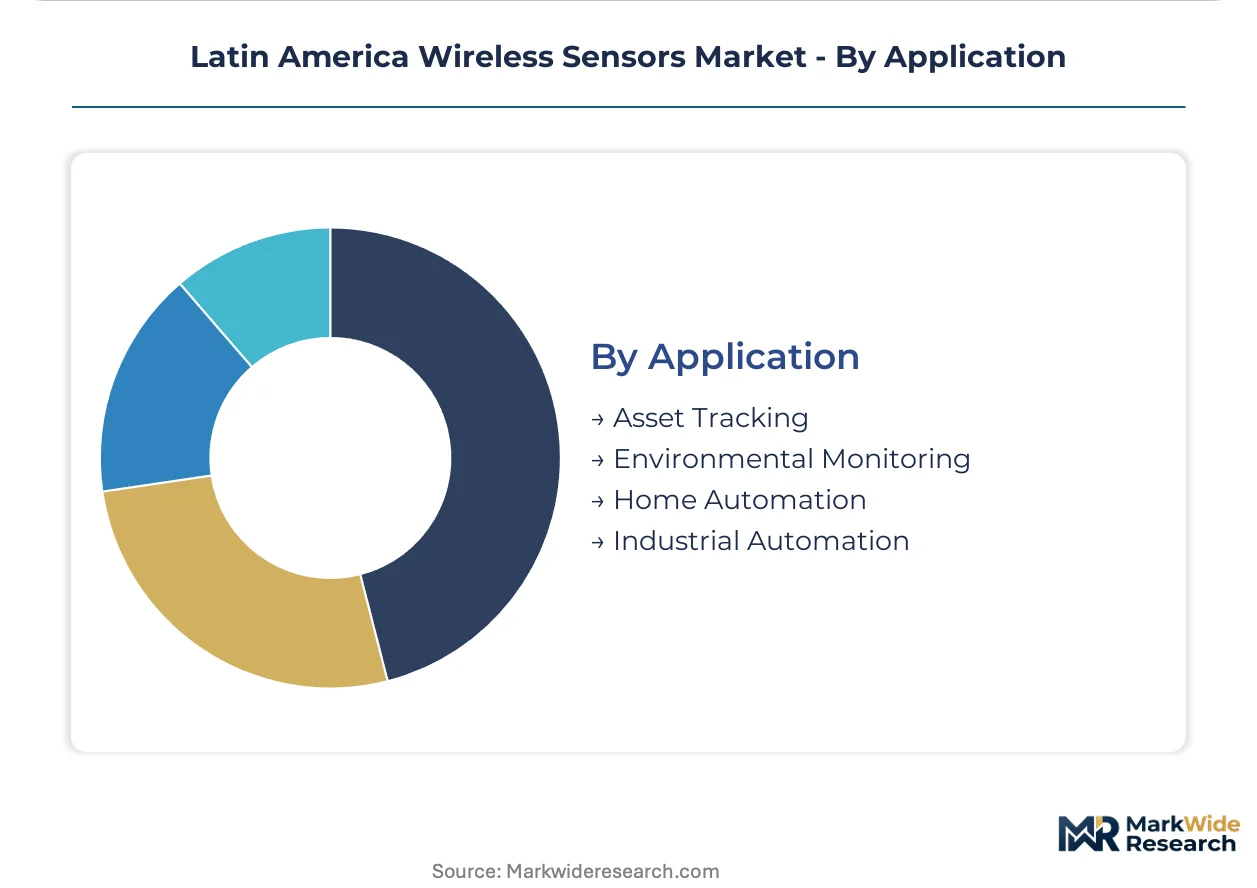
Application segmentation tracks the shift from reactive monitoring toward predictive intervention, with environmental and asset visibility use cases leading platform investment.
- Environmental Monitoring:Distributed sensing networks track soil conditions, air quality, and water table levels across Brazilian agricultural zones and Colombian mining tailings dams. These deployments prioritize decade-long service horizons with minimal maintenance access.
- Asset Tracking:Real-time location systems in Mexican healthcare and Brazilian logistics verticals monitor high-value equipment and temperature-sensitive cargo through combined GPS, Bluetooth beacon, and LoRaWAN backhaul architectures.
- Industrial Automation:Wireless sensor networks retrofit decades-old Brazilian petrochemical and Argentine manufacturing control systems, bridging Modbus and Profibus legacy protocols with IP-native gateways.
- Home Automation:Smart building retrofits in Mexico City Class A office stock integrate HVAC, occupancy, and lighting control through wireless sensor arrays driven by federal energy efficiency mandates.
Environmental monitoring leads deployment scale, though asset tracking is gaining share fastest through cold chain regulatory enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Latin America, with Brazilian agribusiness operators driving hard bargains on volume sensor contracts while Mexican pipeline operators absorb premium pricing for hazardous-area certification without price resistance.
Brazil
Mato Grosso soybean cooperatives deploy thousand-hectare soil moisture grids where battery maintenance costs dominate procurement decisions. ANATEL's 902-928 MHz spectrum allocation enables massive LoRaWAN deployments without licensing fees. São Paulo state cold storage operators anchor pharmaceutical cold chain sensor volumes under ANVISA regulatory pressure.
Mexico
Pemex pipeline surveillance mandates create guaranteed demand for IECEx-certified pressure and acoustic sensors across 12,000 kilometers of hydrocarbon infrastructure. Federal energy regulatory standards require real-time leak detection telemetry with SIL-rated reliability specifications. Guadalajara hosts third-party calibration laboratories displacing manufacturer-direct service contracts.
Argentina
INTI quality certification requirements extend product approval timelines and inflate compliance overhead for multi-country vendors. Córdoba automotive manufacturing clusters concentrate Bluetooth-enabled proximity sensor procurement for robotic assembly coordination. Buenos Aires pharmaceutical distributors drive temperature validation node demand under ANMAT cold chain enforcement.
Chile
Remote mining camps with intermittent connectivity attract edge-AI sensor architectures that enable predictive maintenance without cloud dependency. The country's lithium carbonate processing dominance creates input cost volatility for battery-constrained designs. Antofagasta copper extraction operations present first-mover opportunities for vibration monitoring networks in tailings dam surveillance.
Colombia
Andean copper and gold extraction corridors remain underpenetrated for wireless sensor networks despite tailings dam safety pressures. Bogotá-based system integrators bridge Modbus legacy protocols with IP-native gateways for industrial retrofit projects. Coffee region agricultural cooperatives pilot soil monitoring nodes with photovoltaic-thermal hybrid harvesters eliminating battery replacement cycles.
Latin America Wireless Sensors Market Competitive Landscape
Capability concentration sits with industrial automation heritage players; scale advantage sits with semiconductor and component suppliers with broad distribution footprints. The market structures around three tiers: diversified multinationals with service contract anchoring, specialized sensor manufacturers with hazardous-area certification depth, and modular hardware vendors with firmware interoperability focus. Consolidation pressures favor M&A between calibration service providers and hardware OEMs, while technology licensing agreements accelerate ANATEL pre-certification for cross-border market entry.
Within the diversified industrial tier, Honeywell International Inc. and Emerson Electric Co. occupy positions shaped by premium service contract anchoring with oil and gas operators. Siemens AG exemplifies the smart building retrofit specialist vector with digital infrastructure penetration across Mexican urban commercial centers. Texas Instruments Incorporated represents the semiconductor supplier archetype with chipset-level presence enabling downstream vendor ecosystems. These three anchors illustrate how competitive positioning splits between solution integration depth and component-scale supply relationships.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Emerson Electric Co. |
| ABB Ltd. |
| Texas Instruments Incorporated |
| Pasco Scientific |
| Monnit Corporation |
| Schneider Electric |
| Siemens AG |
| Infineon Technologies AG |
| Others |
Supply & Pricing Matrix
Undercapacity in Chilean lithium carbonate processing is compressing margins for battery-dependent sensor vendors while amplifying pricing power for cell manufacturers serving Brazilian agribusiness and Mexican pipeline operators. This supply bottleneck forces hardware OEMs to absorb input volatility or pass through costs to price-sensitive agricultural cooperatives, reshaping contract structures toward longer-term offtake agreements with embedded escalation clauses.
Pricing Analysis
Aftermarket calibration and predictive maintenance service tiers now drive lifetime value across the Latin America wireless sensors value chain. Pricing stratifies across IECEx-certified premium nodes for Pemex hazardous-area deployments, standard LoRaWAN modules for Brazilian precision agriculture, and economy-tier temperature probes for pharmaceutical cold chain validation. Cost compression in the standard tier is intensifying because semiconductor vendors are consolidating firmware stacks around ANATEL-IFT harmonized reference designs. Agricultural cooperatives in Mato Grosso exhibit highest price sensitivity, while Mexican oil and gas operators absorb premium certification costs without resistance due to federal mandate compliance requirements.
Supply Chain Analysis
Export control restrictions on sub-gigahertz RF chipsets and edge-AI inference accelerators are constraining flows from US and Taiwanese foundries to Latin American system integrators. Component sourcing draws from Chinese PCB assembly houses, Mexican contract manufacturers serving regional logistics, and German precision sensor element suppliers. Single-source vulnerability concentrates in Chilean lithium carbonate for primary cells and Taiwanese LoRaWAN module production. Distribution runs through São Paulo-based industrial distributors for Brazilian agribusiness, Guadalajara calibration service bureaus for Mexican energy maintenance contractors, and direct OEM relationships for Argentine automotive tier-one suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America wireless sensors market functions as a defensive-moat arena where regulatory certification entrenchment creates substantial switching costs for end-users. ANATEL, IFT, and INTI approval timelines embed incumbents deeply into buyer procurement workflows.
For Market Incumbents: Harden certification moats by pre-approving unified firmware stacks against multiple Mercosur regulatory frameworks simultaneously, compressing competitor entry timelines. Deepen backward integration into Chilean lithium cell supply through joint venture structures with carbonate processors, insulating margin positions from input volatility. Priority defensive investment centers on edge-AI inference chip integration for remote mining applications where intermittent connectivity disadvantages cloud-dependent challengers. For New Entrants and Emerging Players: Pursue Colombian Andean mining corridors for vibration and acoustic monitoring networks where tailings dam surveillance pressure meets underpenetrated vendor presence. Target coffee region agricultural cooperatives with photovoltaic-thermal hybrid harvester nodes that eliminate battery maintenance costs dominating Brazilian soybean operator total ownership calculations. Go-to-market angle should emphasize ten-year service horizon competitive bids against incumbent lithium primary cell replacement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across calibration service provision as Guadalajara and Campinas laboratories achieve scale economies displacing manufacturer-direct support contracts. Long-term viability favors acquisition targets combining accredited metrology capabilities with established ANATEL certification relationships rather than pure hardware OEMs lacking service revenue anchoring. Signal to watch is consolidation between third-party calibration bureaus and hardware vendors seeking recurring revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Approval Investment | Unified ANATEL-IFT firmware stacks accelerate cross-border procurement for Brazilian-Mexican agribusiness and energy deployments. |
| Energy Harvesting Technology Migration | Photovoltaic-thermal hybrid nodes eliminate truck rolls for battery maintenance in thousand-hectare Brazilian citrus monitoring grids. |
| Calibration Service Bureau Acquisition | Guadalajara and Campinas laboratories displace manufacturer-direct contracts through faster ANVISA-mandated probe recertification turnaround. |
| Edge-AI Inference Chip Integration | On-device predictive maintenance enables Chilean mining camp deployments without cloud connectivity dependency. |
| LoRaWAN Module Standardization | Sub-gigahertz chirp spread spectrum consolidation around 902-928 MHz band efficiency compresses deployment timelines. |
Research Methodology
Initial hypotheses were tested against primary input from precision agriculture operations managers, Pemex maintenance engineering leads, ANATEL certification specialists, and pharmaceutical cold chain compliance officers and refined through secondary validation. Secondary sources included ANATEL regulatory filings, Mexican IFT spectrum allocation documents, Brazilian customs import data for sensor components, and SEC 10-K disclosures from industrial automation vendors. Bottom-up sensor shipment estimates from Brazilian cooperatives and Mexican pipeline operators were triangulated against top-down market size calculations derived from agricultural acreage under monitoring and hydrocarbon infrastructure telemetry mandate coverage.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning measurement type, protocol technology, vertical end-use, and geographic regulatory cluster. CAGRs were derived from installed base growth rates adjusted for replacement cycles and technology migration patterns. Industry-specific forecast inputs incorporated ANATEL Resolution 680 interoperability testing timelines and Pemex pipeline surveillance mandate compliance deadlines.
Sensitivities concentrate around lithium carbonate price volatility, Mercosur regulatory harmonization progress, and edge-AI chipset export control expansion. Forecasts reflect documented assumptions regarding battery technology cost curves and LoRaWAN network deployment velocities. Material shifts in Chilean lithium processing capacity or US-Taiwan semiconductor trade restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Microsensor Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Global Multi-Turn Potentiometer Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Blue-Green Algae Sensors Market