
 Global Light Sensors Market | 2026-2036
Global Light Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Light Sensors Market Foresight
Automotive supplier demand is hardening as ambient light and proximity detection migrate from premium vehicles to mass-market platforms. STMicroelectronics N.V. leverages its MEMS and imaging portfolio to anchor European automotive design wins. ams-OSRAM AG sustains dominance in optical sensing through backward integration into epitaxial wafer production. Broadcom Inc. competes in consumer electronics with compact module designs that reduce board space for smartphone manufacturers.
Light sensors are semiconductor devices that convert photonic energy into electrical signals, typically operating across ultraviolet to infrared wavelengths with responsivity measured in amperes per watt. These components enable automatic brightness adjustment, optical switching, and spectral analysis in industrial and consumer systems. CMOS sensors now lead volume shipments due to on-chip integration with signal processing circuitry, while photodiodes retain margin strength in aerospace and defense applications requiring radiation hardness. Digital light sensors are displacing analog architectures in smart lighting networks where I2C and SPI interfaces simplify microcontroller pairing.
The EU F-Gas Regulation and REACH compliance frameworks in Europe, alongside NHTSA lighting safety standards in the United States and GB standards administered by SAMR in China, collectively elevate barrier-to-entry for uncertified suppliers. Ecodesign requirements under the EU Green Deal mandate minimum efficacy thresholds for sensor-driven luminaires, redirecting procurement toward validated component vendors. Stakeholders must monitor how automotive OEM qualification cycles and building-code electrification mandates in multiple jurisdictions reshape specification roadmaps and supplier qualification timelines.
Market Dynamics
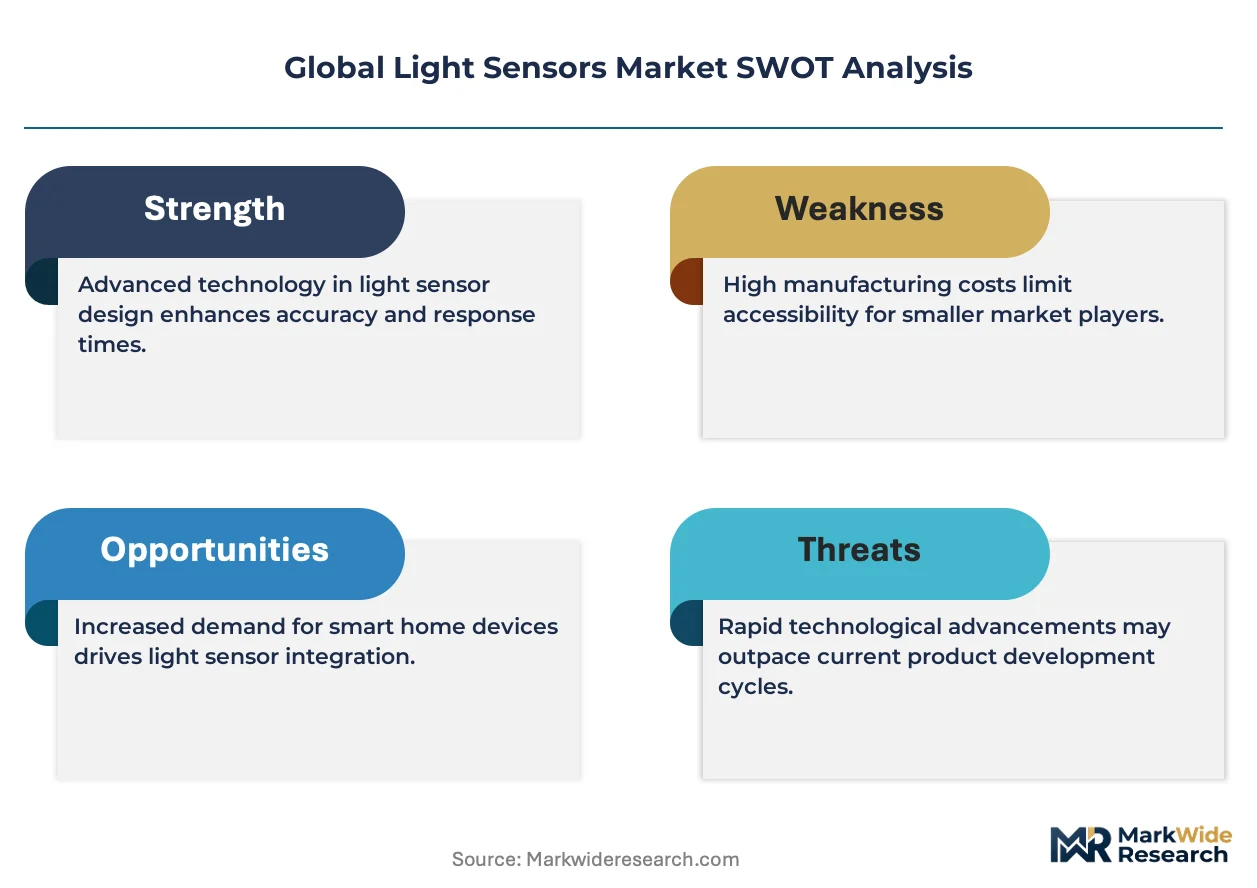
Automotive OEM qualification cycles and EU energy-efficiency mandates are compressing supplier timelines while elevating technical thresholds for ambient light detection modules. Component vendors face simultaneous pressure to certify against NHTSA lighting standards and Ecodesign requirements under divergent jurisdictional timelines.
Growth Catalysts
- EU F-Gas Regulation:Tightened energy-efficiency mandates for smart lighting components are redirecting procurement toward validated sensor vendors with proven luminaire integration.
- ADAS penetration:Ambient light and proximity detection are migrating from premium vehicles to mass-market automotive platforms, hardening supplier demand specifications.
- CMOS integration:On-chip signal processing circuitry is consolidating photodetection and conditioning functions, reducing bill-of-material complexity for smartphone manufacturers.
Market Restraints
- Epitaxial wafer supply concentration:Backward integration into III-V semiconductor substrates limits viable supplier pools to capital-intensive foundry operators.
- REACH compliance friction:Restricted substance declarations for optical coatings and packaging materials extend qualification cycles for non-European component vendors.
- Radiation-hardened photodiode cost structure:Aerospace and defense applications requiring cobalt-doped silicon substrates carry 4-6x material premiums over commercial CMOS alternatives.
Strategic Opportunities
- India building electrification:CEA mandates for smart street lighting in municipal infrastructure are creating specification windows for I2C-interface digital sensors.
- Spectral sensing convergence:Multi-channel photodiode arrays combined with machine learning inference are enabling real-time agricultural crop monitoring.
- SAMR GB standard alignment:China's dual carbon goals are accelerating sensor-driven lighting retrofit programs in industrial facilities.
Industry Challenges
- Automotive qualification timeline compression:OEM platform cycles now demand AEC-Q100 validation completion within 18-month windows.
- Legacy analog architecture integration:Smart lighting networks must bridge SPI-digital sensors with existing 0-10V dimming infrastructure without signal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Light Sensors Market |
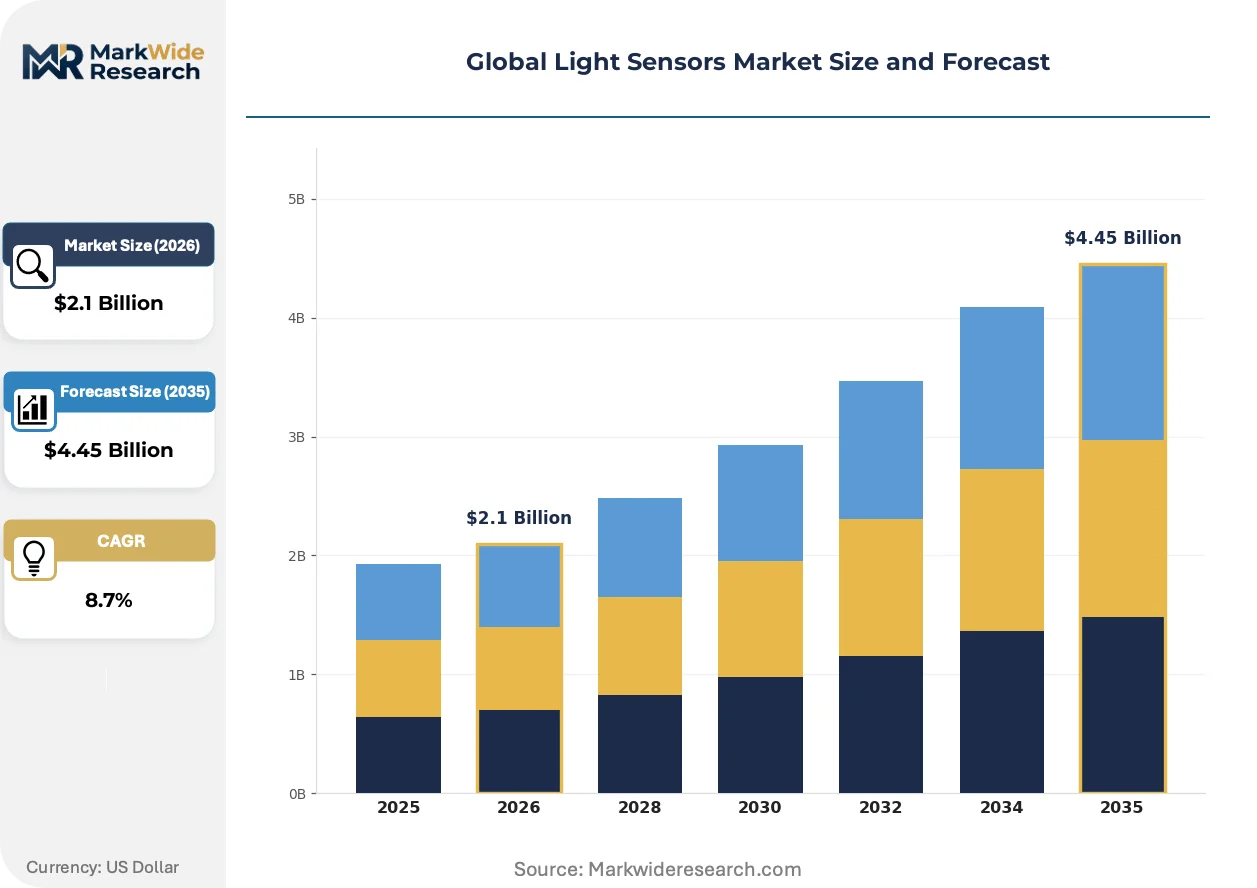
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photodiodes, Phototransistors, Charge-Coupled Devices, CMOS Sensors, Photovoltaic Cells Technology: Analog Light Sensors, Digital Light Sensors, Optical Sensors, Infrared Sensors, Ultraviolet Sensors Application: Consumer Electronics, Smart Lighting, Environmental Monitoring, Aerospace Systems, Security Systems End User: Lighting Manufacturers, Electronic Device Producers, Environmental Agencies, Defense Contractors, Automotive Suppliers |
| Companies Covered | ams-OSRAM AG, STMicroelectronics N.V., Broadcom Inc., Vishay Intertechnology Inc., Sharp Corporation, Analog Devices Inc., Everlight Electronics Co., Ltd., ROHM Co., Ltd., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Light Sensors Market Shifts & Advancements
Photonic integration and jurisdictional energy mandates are restructuring how light sensors are specified, manufactured, and deployed across end-use verticals. Three developments are reshaping competitive positioning and procurement patterns.
Edge-based spectral analysis is decentralizing processing workloads from centralized controllers to distributed sensor nodes. Agricultural automation suppliers in the Netherlands and California are deploying multi-band photodiode arrays with on-chip classification algorithms. This architecture is decentralizing data transmission requirements while compressing response latency for real-time irrigation and harvest-timing decisions.
The EU Green Deal's Ecodesign requirements are mandating minimum efficacy thresholds for sensor-driven luminaires across commercial and residential installations. Component vendors must now validate standby power consumption and dimming interoperability under standardized test protocols. German lighting OEMs are responding by consolidating procurement onto qualified suppliers with pre-certified module platforms.
Automotive Tier-1 suppliers are unbundling sensor specification from full-module procurement, engaging directly with semiconductor vendors for ambient light and proximity die. This pattern is fragmenting traditional distribution channels in Japan and Germany. Tier-1 engineering teams in Toyota City and Stuttgart are establishing parallel qualification tracks that bypass legacy module integrators.
Global Light Sensors Market Segmentation
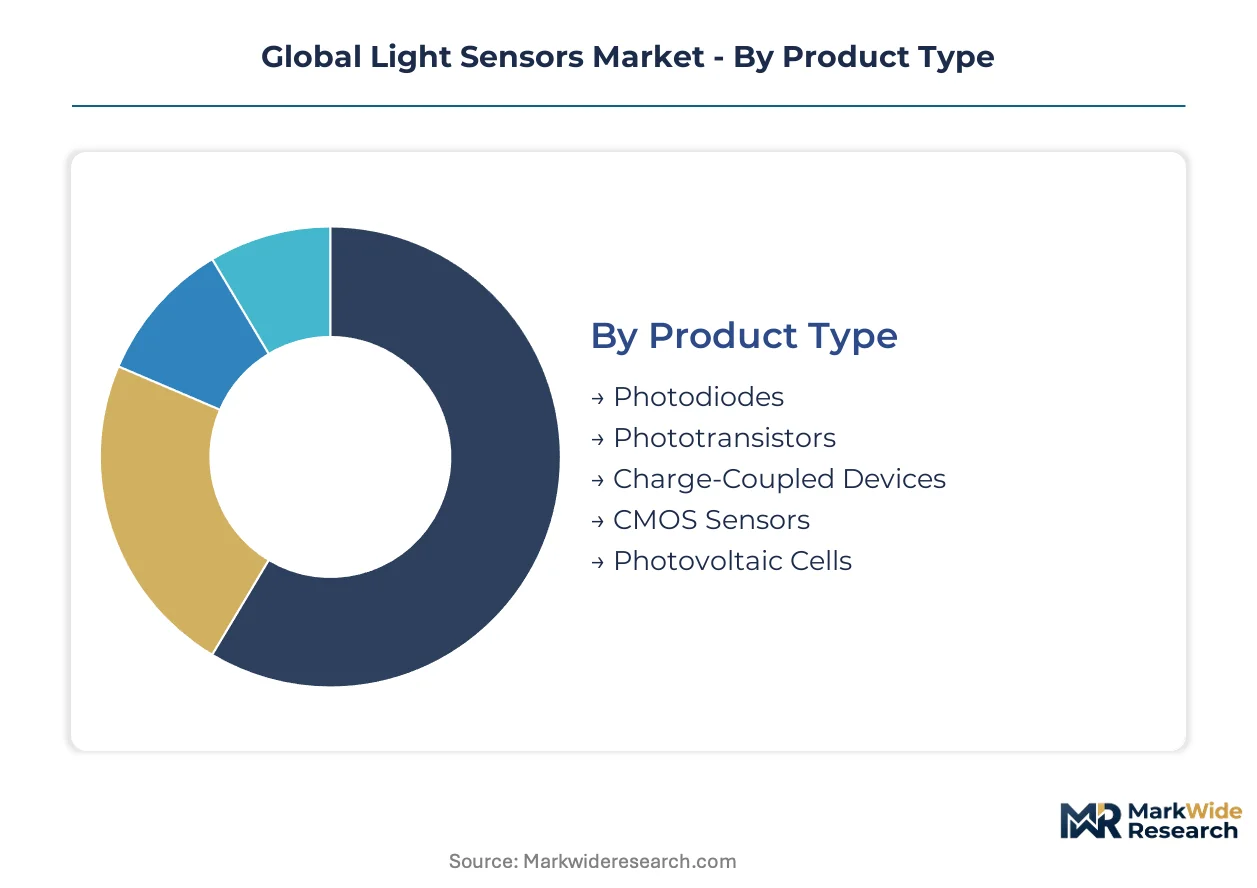
Component architecture and interface standards fragment procurement specifications across automotive, consumer, and industrial verticals. Understanding how photodetection technologies map to end-use requirements clarifies supplier positioning and qualification priorities.
Product Type:
CMOS sensors dominate unit shipments through on-chip integration economies, while photodiodes command material premiums in mission-critical deployments.
- Photodiodes:PN-junction semiconductor devices convert photons to current with nanosecond response times. Demand from Stuttgart and Toyota City automotive clusters concentrates on avalanche and PIN architectures for ambient light detection in ADAS modules.
- CMOS Sensors:Active-pixel arrays integrate photodetection with analog-to-digital conversion on single die. Smartphone manufacturers in Shenzhen and Cupertino specify these for compact camera modules where board space constraints dominate.
- Phototransistors:Bipolar junction devices amplify photocurrent without external transimpedance amplifiers.
- Charge-Coupled Devices:Analog shift-register architectures retain niche status in scientific imaging and spectroscopy equipment.
- Photovoltaic Cells:Self-powered photodetectors operate without external bias in remote environmental monitoring nodes.
Mature deployment sits with Photodiodes in automotive and aerospace qualification tracks. Newer deployment is concentrated in CMOS Sensors for consumer electronics integration.
Technology:
Interface architecture determines microcontroller pairing complexity and signal conditioning requirements across building automation and mobile device platforms.
- Digital Light Sensors:I2C and SPI protocol outputs eliminate external ADC components. Municipal lighting retrofits in Mumbai and Sao Paulo specify these for simplified network commissioning under CEA and ANEEL smart grid mandates.
- Analog Light Sensors:Voltage or current outputs require external signal conditioning. Legacy 0-10V dimming infrastructure in German commercial buildings continues procurement of these for backward compatibility with existing luminaire controllers.
- Optical Sensors:Broad-spectrum photodetectors span visible and near-infrared wavelengths.
- Infrared Sensors:Band-selective architectures filter visible wavelengths for proximity detection and thermal monitoring.
- Ultraviolet Sensors:Silicon carbide or gallium nitride substrates enable germicidal and flame detection applications.
Procurement volume clusters on Digital Light Sensors for new smart lighting networks. Analog Light Sensors sustain replacement demand in existing building stock.
Application:
End-use specifications diverge sharply between consumer price sensitivity and industrial reliability requirements.
- Consumer Electronics:Display brightness adjustment and camera auto-exposure drive specifications. South Korean and Chinese smartphone OEMs prioritize sub-millimeter package dimensions and sub-milliwatt standby consumption.
- Smart Lighting:Daylight harvesting and occupancy detection mandate networked sensor architectures. EU Ecodesign compliance and NHTSA exterior lighting standards elevate technical thresholds for validated component vendors.
- Environmental Monitoring:Spectral analysis and irradiance measurement applications span agricultural and meteorological deployments.
- Aerospace Systems:Radiation-hardened specifications and extended temperature ranges apply to satellite and avionics platforms.
- Security Systems:Perimeter intrusion detection and surveillance camera night-vision requirements specify near-infrared sensitivity.
Margin concentration follows Aerospace Systems qualification premiums. Volume expansion is climbing the fastest in Consumer Electronics module integration.
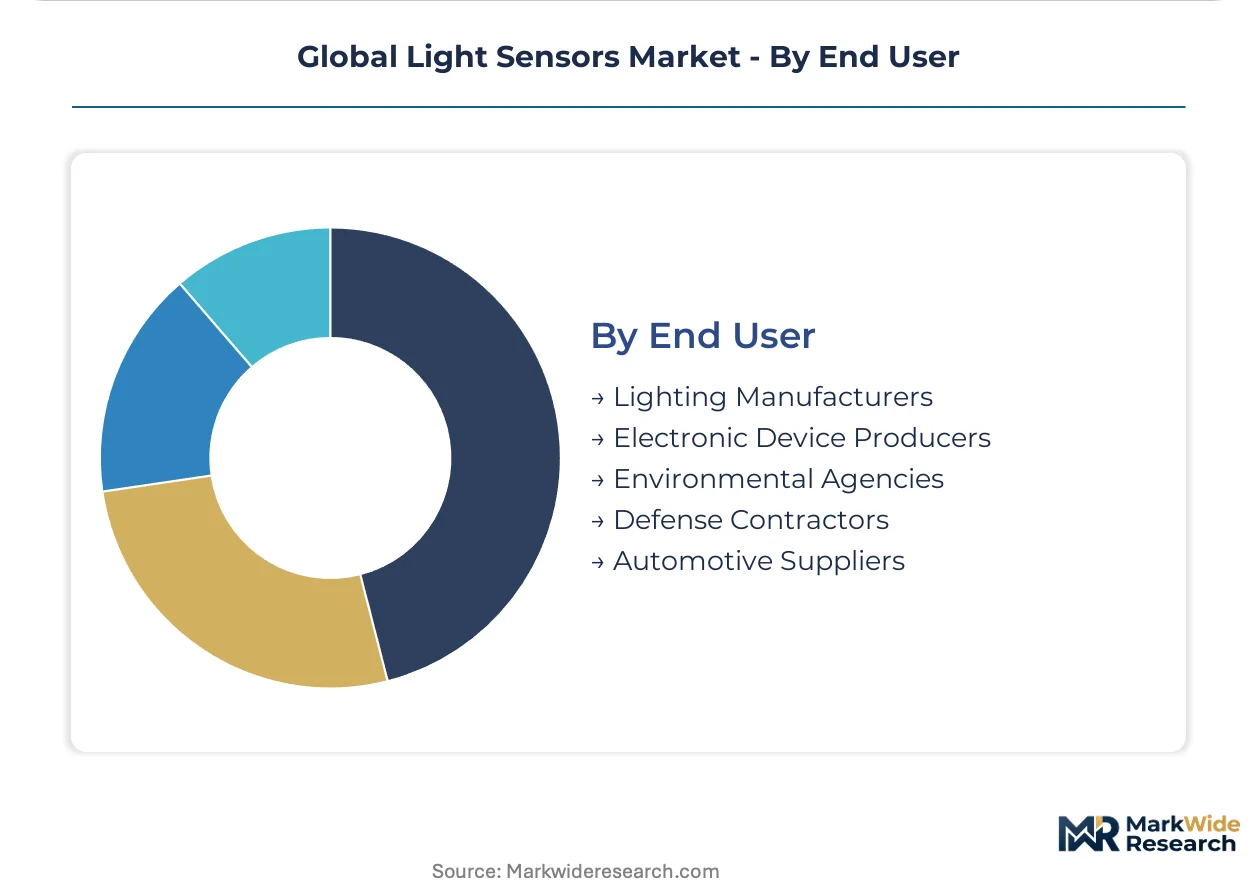
End User:
Customer procurement patterns separate qualified automotive supply chains from price-sensitive electronics manufacturing.
- Automotive Suppliers:Tier-1 module manufacturers in Germany and Japan conduct parallel die-level qualification with STMicroelectronics and ams-OSRAM. AEC-Q100 validation timelines compress to eighteen-month windows for new platform integration.
- Lighting Manufacturers:Luminaire OEMs in Italy and the Netherlands consolidate procurement onto pre-certified sensor modules. EU Green Deal Ecodesign mandates redirect specification toward vendors with documented standby power and dimming interoperability.
- Electronic Device Producers:Contract manufacturers in Vietnam and Mexico specify compact modules for smartphone and tablet assembly.
- Environmental Agencies:Government monitoring networks in India and Brazil deploy solar-powered sensor nodes for air quality and weather stations.
- Defense Contractors:ITAR and national security classification requirements restrict supplier pools for military imaging systems.
Longest qualification cycles characterize Defense Contractor procurement. Fastest specification evolution concentrates in Automotive Suppliers responding to ADAS platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters and Shenzhen manufacturing zones concentrate light sensor demand through divergent procurement channels. Stuttgart and Toyota City anchor precision sensor qualification tracks for ADAS integration. Shenzhen and Cupertino drive consumer electronics specifications through compact module integration.
United States
NHTSA exterior lighting standards and IRA clean energy incentives harden technical thresholds for automotive and smart building applications. EPA energy-efficiency mandates for commercial luminaires redirect municipal procurement toward validated digital sensor vendors. Detroit automotive engineering centers compress AEC-Q100 qualification timelines for ambient light detection modules.
Germany
EU F-Gas Regulation and Ecodesign requirements under the Green Deal mandate minimum efficacy thresholds for sensor-driven luminaires. KBA automotive safety standards elevate barrier-to-entry for uncertified component suppliers. Bavarian lighting OEMs consolidate procurement onto pre-certified module platforms with documented standby power consumption.
Japan
METI energy-efficiency roadmaps and JIS standards govern smart lighting retrofit programs in commercial buildings. Toyota City and Nagoya automotive clusters conduct parallel die-level qualification with semiconductor vendors for ADAS platform integration. Japanese Tier-1 suppliers fragment traditional distribution channels through direct semiconductor procurement.
China
SAMR GB standards and dual carbon goals accelerate sensor-driven lighting retrofit programs in industrial facilities. Shenzhen smartphone manufacturers specify CMOS sensors for compact camera modules where board space constraints dominate. Yangtze River Delta contract manufacturers drive volume procurement for consumer electronics integration.
India
CEA mandates for smart street lighting in municipal infrastructure create specification windows for I2C-interface digital sensors. BIS certification requirements for electronic components extend qualification cycles for non-domestic vendors. Maharashtra and Gujarat industrial corridors deploy solar-powered sensor nodes for environmental monitoring networks.
Global Light Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with automotive qualification tracks favoring integrated semiconductor vendors and consumer electronics rewarding compact module suppliers. The vendor base concentrates around three strategic archetypes: MEMS-imaging integrators serving European automotive OEMs, optical sensing specialists with backward wafer integration, and compact module designers reducing board space for smartphone manufacturers. M&A activity targets spectral sensing capabilities and automotive qualification assets. Geographic expansion focuses on Indian municipal lighting mandates and Chinese industrial retrofit programs.
Within the European automotive tier, STMicroelectronics N.V. and ams-OSRAM AG exemplify divergent integration strategies. STMicroelectronics anchors MEMS and imaging portfolio positions for design wins in Stuttgart and Toyota City qualification tracks. ams-OSRAM represents optical sensing dominance through captive supply of epitaxial wafer substrates. Among US-based module designers, Broadcom Inc. occupies a position serving consumer electronics manufacturers with space-constrained specifications.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| STMicroelectronics N.V. |
| Broadcom Inc. |
| Vishay Intertechnology Inc. |
| Sharp Corporation |
| Analog Devices Inc. |
| Everlight Electronics Co., Ltd. |
| ROHM Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Epitaxial wafer substrate costs cascade through three distinct pricing tiers, with III-V semiconductor ingots from German and Japanese foundries commanding premiums that filter down to automotive module procurement. Spot-market gallium arsenide pricing volatility feeds directly into photodiode cost structures, while CMOS sensor vendors in Taiwan and South Korea leverage silicon wafer abundance to compress unit economics for consumer electronics buyers.
Pricing Analysis
Lead-time-driven pricing stratification separates AEC-Q100 qualified automotive die from spot-market commercial inventory. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Price compression runs through consumer CMOS modules as Shenzhen contract manufacturers consolidate procurement onto qualified second-source vendors. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to platform-lock-in effects, while municipal lighting contractors in India and Brazil drive hardest bargain on I2C-interface digital sensors.
Supply Chain Analysis
Single-source vulnerability sits with epitaxial wafer supply concentrated in Germany, Japan, and the United States. Raw material dependencies span gallium arsenide substrates, cobalt-doped silicon for radiation-hardened applications, and specialty optical coatings. Tariff exposure on III-V compound semiconductor imports from Asia-Pacific manufacturing zones elevates landed cost uncertainty for European luminaire OEMs. Distribution runs through authorized component distributors in automotive channels and direct procurement relationships in consumer electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial wafer foundry capacity constraints prop pricing power for backward-integrated semiconductor vendors across automotive qualification tracks. Foundry slot scarcity limits second-source options for Tier-1 module manufacturers.
For Market Incumbents: Deepen captive wafer supply through long-term offtake agreements with German and Japanese epitaxial foundries. Defend against fabless entrants by accelerating AEC-Q100 validation completion within compressed eighteen-month OEM windows. Prioritize spectral sensing R&D to capture agricultural automation demand in the Netherlands and California.
For New Entrants and Emerging Players: Edge-based spectral analysis with on-chip machine learning inference offers entry wedge into agricultural crop monitoring applications. Target Indian municipal lighting retrofits under CEA mandates where BIS certification barriers filter out established European suppliers. Pursue direct engagement with Maharashtra and Gujarat industrial corridor contractors for solar-powered environmental monitoring nodes.
For Investors and Strategic Acquirers: Tier-1 automotive suppliers establishing parallel die-level qualification tracks is the leading indicator that traditional module integrator margins are compressing. Five-to-ten year viability favors semiconductor vendors with proven automotive design wins and backward wafer integration. Watch for SAMR GB standard acceleration in Chinese industrial facilities as signal of specification window opening for validated digital sensor vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Wafer Supply | Captive III-V substrate production insulates ams-OSRAM from foundry slot scarcity in Stuttgart automotive clusters. |
| AEC-Q100 Acceleration Program | Eighteen-month validation completion secures design wins with Toyota City and Nagoya Tier-1 engineering teams. |
| Spectral Sensing Platform Launch | Multi-band photodiode arrays with on-chip classification capture agricultural automation demand in Dutch greenhouse operations. |
| Indian Municipal Lighting Partnership | CEA-mandated smart street lighting retrofits in Mumbai and Pune open specification windows for I2C-interface digital sensors. |
| EU Ecodesign Pre-Certification | Documented standby power and dimming interoperability redirects Bavarian lighting OEM procurement onto validated module platforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with automotive Tier-1 procurement directors, semiconductor foundry operations managers, luminaire OEM technical specification leads, and municipal lighting contractors in India and Brazil combined with SEC 10-K disclosures, EU Ecodesign compliance databases, and SAMR GB standard documentation. Bottom-up shipment data triangulated against top-down automotive production and smartphone assembly estimates.
Granularity-level modeling disaggregated volume and value across photodiode, CMOS sensor, and phototransistor architectures by interface protocol, application vertical, and end-user procurement channel throughout the forecast period. CAGRs derived from regression analysis against automotive ADAS penetration curves and smart lighting retrofit installation rates. Industry-specific inputs included AEC-Q100 qualification timeline compression effects and EU F-Gas Regulation compliance cost pass-through assumptions.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, raw material export controls on gallium and germanium, and automotive platform cancellation decisions by individual OEMs. Forecasts reflect documented assumptions about regulatory timeline adherence and foundry capacity expansion plans. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Active Sensor Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
MEMS Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Barometer Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Middle East and Africa Pressure Sensors Market