
 Parking Sensors Market | 2026-2036
Parking Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Parking Sensors Market Intelligence
Integrated system software and data processing revenue is rewriting the profit landscape for parking sensor manufacturers. This shift moves value away from standalone hardware components toward complete perception solutions for driver-assistance systems. Robert Bosch GmbH leverages its deep expertise in automotive systems to offer bundled sensor and ECU packages. Continental AG competes through its extensive portfolio covering radar, camera, and ultrasonic technologies. Valeo specializes in developing and supplying complete ADAS modules to major automotive OEMs worldwide.
Parking sensors are proximity detection devices that alert drivers to obstacles during low-speed maneuvers. Most function by emitting ultrasonic waves, typically in the 40-60 kHz frequency range, and measuring the time it takes for the echo to return. Their primary purpose is to prevent collisions with objects in the vehicle's blind spots during parking. Ultrasonic sensors remain the dominant product type due to their cost-effectiveness and reliability. The OEM installation channel accounts for the vast majority of volume, as sensors are increasingly integrated at the factory level across passenger vehicles.
Regulatory mandates are a primary catalyst for market expansion. The EU's General Safety Regulation (GSR) requires certain advanced driver-assistance systems in new vehicles, directly boosting sensor fitment rates. In the United States, NHTSA safety ratings and guidelines encourage the adoption of parking aids. Policies from China's MIIT promoting intelligent connected vehicles also create a significant and stable demand base. The critical strategic decision for suppliers involves allocating R&D resources between refining cost-effective ultrasonic systems and developing next-generation sensor fusion capabilities for higher automation levels.
Market Dynamics
The market's primary structural force is the regulatory codification of vehicle safety. Mandates from governmental bodies like the European Union are transforming parking sensors from optional features into standard, non-negotiable equipment, creating a permanent and expanding demand floor for suppliers.
Growth Catalysts
- Regulatory Mandates:The European Union's General Safety Regulation (GSR) requires advanced driver-assistance systems in new vehicles, directly increasing the factory fitment rate of parking sensors across all vehicle classes.
- Automotive Production in China:Policies from China's MIIT that promote intelligent connected vehicles create a massive, stable demand base, driven by the country's unparalleled scale in automotive manufacturing.
- Passenger Vehicle Standardization:The shift to include parking assistance as standard equipment, even in economy-class passenger vehicles, expands the total addressable market beyond luxury and premium segments.
Market Restraints
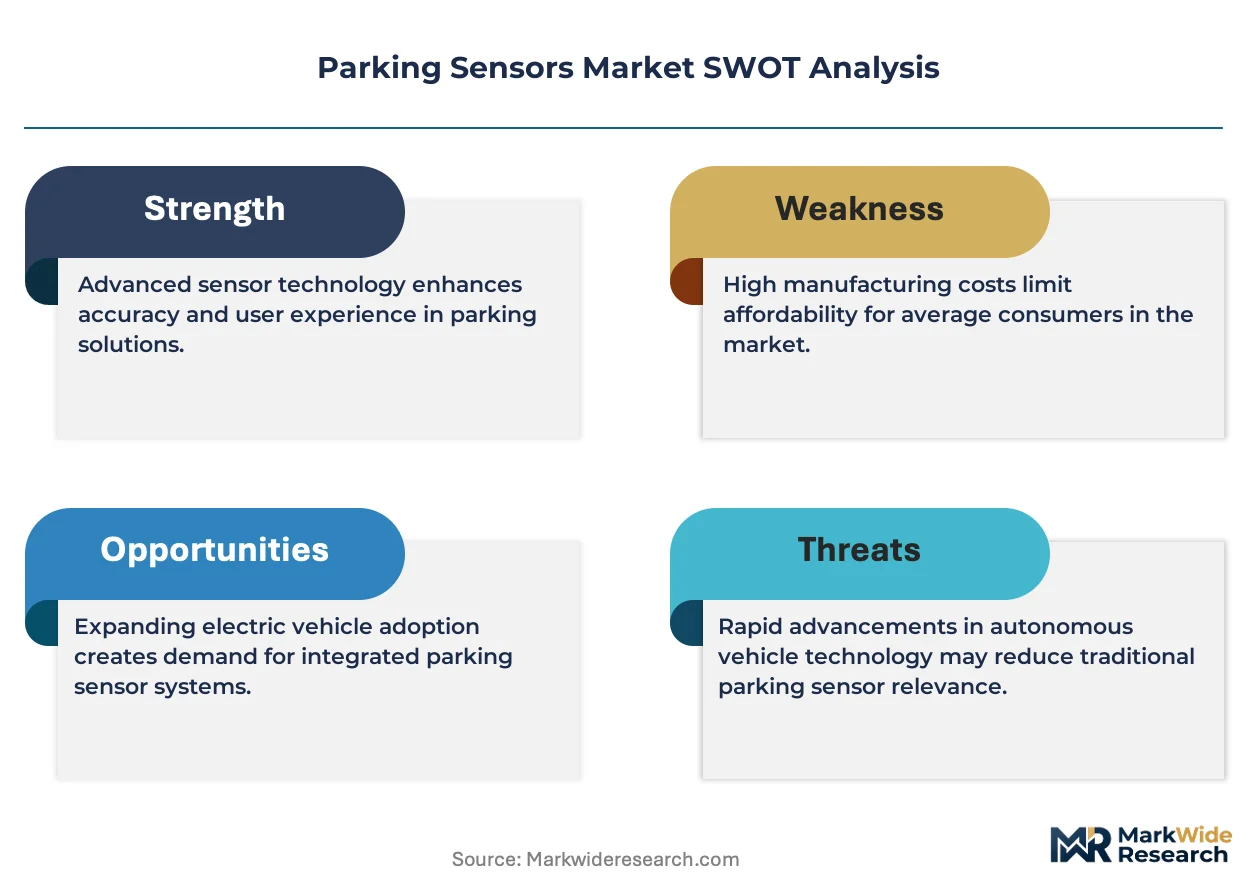
- Performance Limitations:Ultrasonic sensors, the dominant technology, can experience reduced accuracy and reliability in adverse weather conditions like heavy rain, snow, or mud, which can block or distort signals.
- Hardware Commoditization:Intense price pressure from automotive OEMs, particularly for high-volume ultrasonic units, compresses margins on standalone hardware components and favors large-scale, cost-optimized producers.
- Substitution from Vision Systems:The increasing integration of wide-angle cameras for backup and 360-degree surround-view systems presents a substitution threat, potentially reducing the required number of ultrasonic sensors per vehicle.
Strategic Opportunities
- Sensor Fusion Development:Integrating ultrasonic sensor data with inputs from camera and radar systems offers a path to higher-value perception modules for advanced levels of driver assistance and automation.
- Commercial Vehicle Penetration:The application of parking and maneuvering assistance systems in commercial trucks, buses, and off-highway equipment represents a significant, underpenetrated market segment with distinct safety needs.
- Emerging Market Adoption:Targeting nascent automotive manufacturing hubs in Southeast Asia and Latin America, where safety standards are beginning to tighten, provides a long-term growth vector.
Industry Challenges
- System Integration Complexity:Achieving seamless data fusion and reliable communication between multiple sensor types, the vehicle's ECU, and the user interface remains a significant software and hardware engineering hurdle for automakers.
- Lack of Standardization:The absence of universal communication protocols and data formats across different sensor suppliers and vehicle platforms increases development costs and lead times for OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parking Sensors Market |
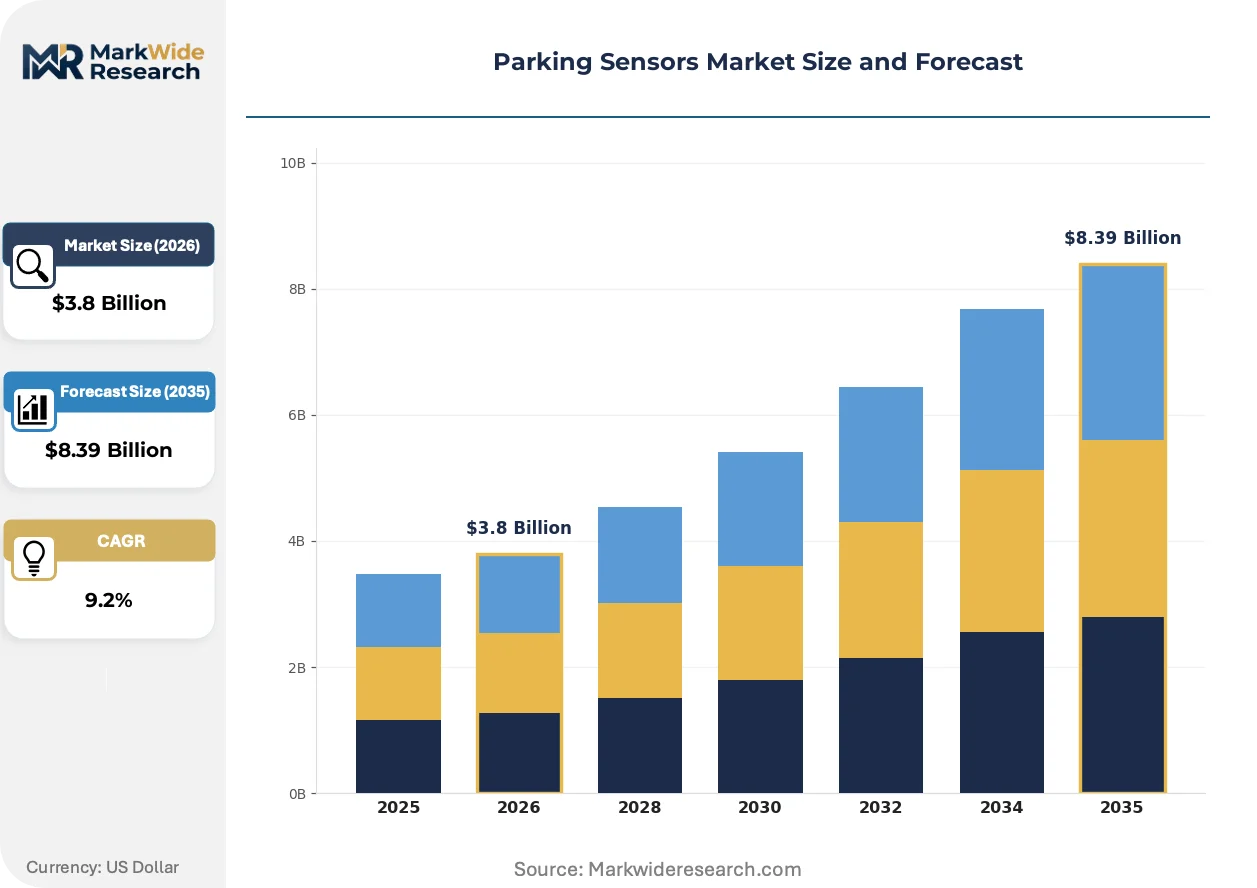
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Electromagnetic Sensors, Infrared Sensors, Laser Sensors Installation Type: OEM, Aftermarket, Portable, Fixed End User: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles Technology: Wired Technology, Wireless Technology, Bluetooth Technology, Radar Technology |
| Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, Valeo, Aptiv, Autoliv Inc., NXP Semiconductors, Texas Instruments Incorporated, Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parking Sensors Market Strategic Shifts & Innovations
The role of the parking sensor is fundamentally changing, evolving from a simple proximity alert device into a critical data-gathering node within the vehicle's broader software-defined architecture. This shift is reshaping product development and supplier relationships across the automotive industry.
Sensor fusion software combines inputs from ultrasonic, radar, and camera sensors to generate a cohesive environmental model for the vehicle. Automotive OEMs are rapidly adopting this technology, particularly in mid-range and premium vehicle segments, to enhance safety and enable more complex automated features. This integrated approach is rendering obsolete the standalone, single-function parking sensor that only provides a basic audible warning.
In the United States, NHTSA's New Car Assessment Program (NCAP) provides a powerful incentive for sensor adoption. While not a direct mandate, the program's five-star safety ratings strongly influence consumer choice and encourage automakers to equip vehicles with advanced safety systems, including sophisticated parking aids. This affects the feature set of new passenger vehicles sold in the US, accelerating fitment beyond just luxury models.
A significant behavioral shift involves automotive OEMs sourcing complete perception software solutions rather than just discrete hardware components. This change disrupts the traditional model of component-level procurement, favoring Tier 1 suppliers capable of delivering fully integrated sensor and ECU packages. The trend is most prominent in advanced automotive development centers like Germany and Japan, where work on next-generation vehicle electronic architectures is concentrated.
Parking Sensors Market Segmentation
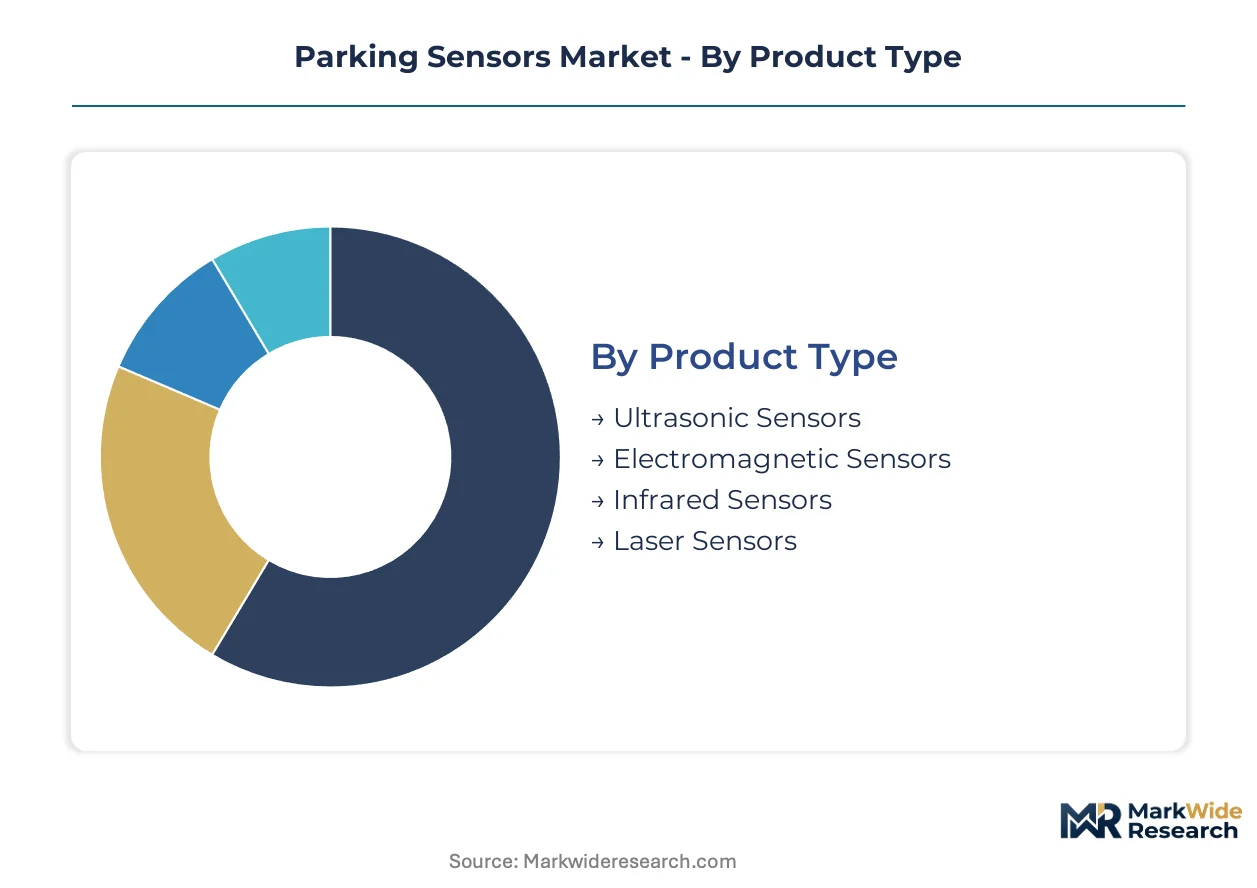
Understanding the distinct segments within the parking sensors market clarifies the diverse technological requirements and user preferences. This segmentation highlights where innovation is most impactful and where market demand is most concentrated.
Product Type:
Cost-effectiveness and sensing principles define product type segmentation, guiding supplier investment in specific sensor technologies.
- Ultrasonic Sensors:These sensors operate by emitting high-frequency sound waves and measuring the time it takes for the echo to return, primarily used for close-range obstacle detection. Demand is concentrating in high-volume passenger vehicles, driven by their reliability and low manufacturing cost for basic parking assistance systems.
- Electromagnetic Sensors:Electromagnetic sensors detect objects by creating an electromagnetic field and sensing distortions caused by nearby materials, offering a flush-mount solution. These are increasingly adopted in premium vehicle segments for their discreet integration and resistance to dirt accumulation.
- Infrared Sensors:Infrared sensors utilize infrared light to detect objects, offering good performance in certain conditions but limited range.
- Laser Sensors:Laser sensors provide highly accurate distance measurements, often integrated into more advanced driver-assistance systems for precise object mapping.
Ultrasonic Sensors commands the established base. The steepest expansion runs through Electromagnetic Sensors.
Installation Type:
Volume distribution across vehicle lifecycle stages differentiates installation types, impacting procurement channels and manufacturing scale.
- OEM:Original Equipment Manufacturer (OEM) installations integrate sensors directly into the vehicle's design during factory production. This channel accounts for the vast majority of volume, spurred by regulatory mandates like the EU's General Safety Regulation and safety ratings from NHTSA in the United States.
- Aftermarket:Aftermarket installations involve adding sensor systems to vehicles post-purchase, often by third-party providers or consumers. This segment serves older vehicle fleets and custom vehicle modifications, offering flexible upgrade options for improved safety.
- Portable:Portable systems are temporary, battery-operated devices that can be moved between vehicles, offering basic parking assistance for various applications.
- Fixed:Fixed installations refer to permanently mounted sensors, typically in commercial or industrial settings, for monitoring vehicle movement.
OEM installations dictate market volume, while aftermarket solutions offer flexibility.
End User:
Application scope and vehicle characteristics delineate end-user segments, reflecting varying safety needs and regulatory pressures.
- Passenger Vehicles:Passenger vehicles represent the largest end-user segment, encompassing sedans, SUVs, and hatchbacks. Regulatory pushes, such as the EU's GSR, are making parking sensors standard equipment, significantly boosting fitment rates across all classes.
- Commercial Vehicles:Commercial vehicles include trucks, buses, and vans used for business purposes, requiring robust sensing solutions for larger blind spots and complex maneuvering. This segment is experiencing growth as fleet operators prioritize safety and reduced damage costs in urban logistics.
- Luxury Vehicles:Luxury vehicles often integrate advanced parking sensor systems with sophisticated displays and automation features.
- Electric Vehicles:Electric vehicles incorporate parking sensors as part of their advanced driver-assistance systems, leveraging their inherent electrical architecture for integration.
Passenger vehicles represent the largest user base. Commercial vehicles are rapidly integrating these systems for operational safety.
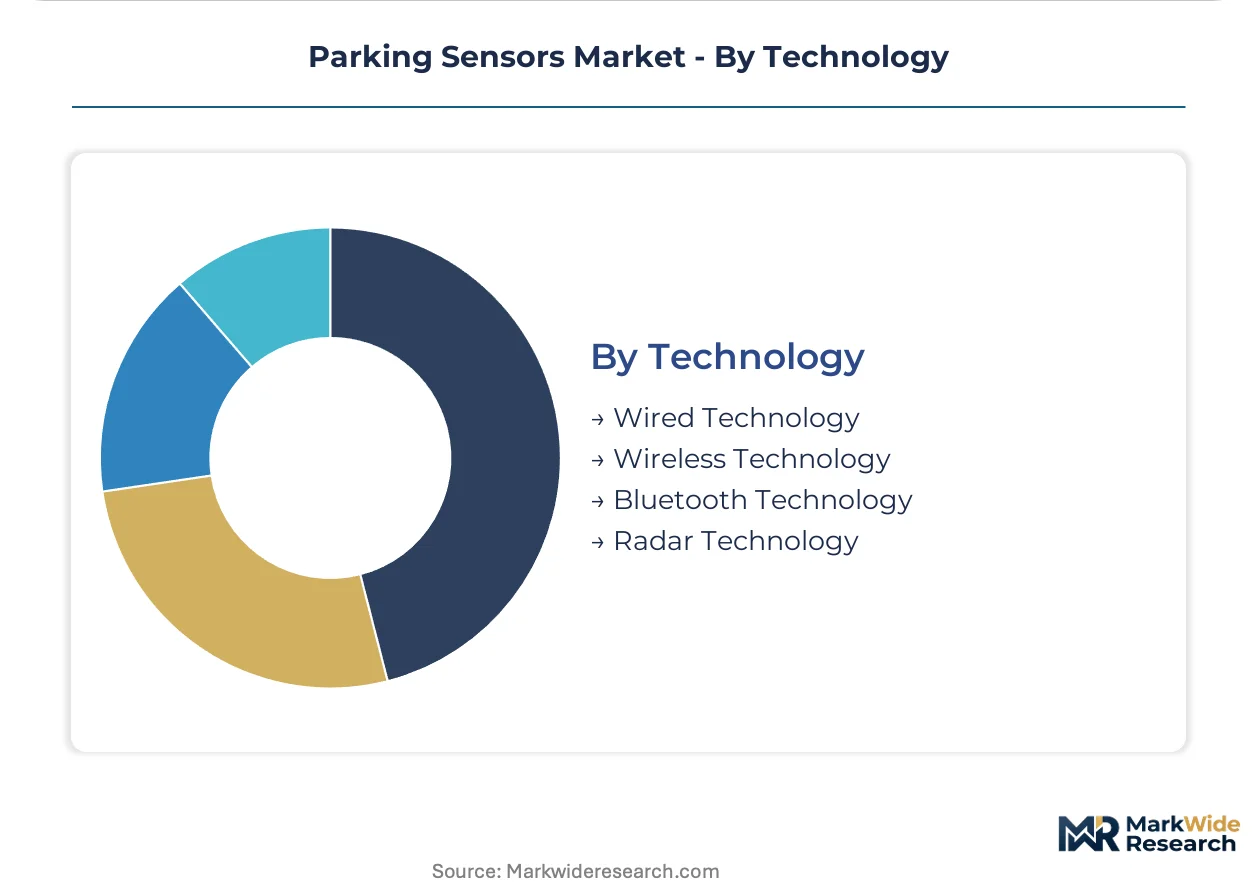
Technology:
Data transmission methods and integration approaches define technology segmentation, influencing system complexity and performance.
- Wired Technology:Wired technology connects sensors directly to the vehicle's electronic control unit (ECU) via physical cables for stable data transfer and power supply. This method forms the backbone of most factory-installed systems, ensuring low latency and high reliability in critical safety functions.
- Wireless Technology:Wireless technology enables sensor communication without physical cabling, often using radio frequencies or other short-range protocols for data transmission. This approach simplifies installation, particularly in aftermarket solutions, and supports flexible system architectures for new vehicle designs.
- Bluetooth Technology:Bluetooth technology offers short-range wireless connectivity, primarily used for connecting portable parking sensors to smartphone displays.
- Radar Technology:Radar technology employs radio waves to detect objects and measure distance, often used in conjunction with ultrasonic sensors for enhanced perception.
Wired systems form the foundation of current vehicle architectures. Wireless solutions are gaining traction for their integration ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Europe and China drive demand through regulatory mandates and automotive production, the United States' market expansion is more influenced by consumer safety ratings. This creates distinct regional consumption patterns for parking sensor technologies. Different regulatory frameworks and consumer preferences shape market dynamics across key geographies.
China
Demand is heavily influenced by the country's massive automotive manufacturing base. Policies from China's MIIT promote intelligent connected vehicles, creating a stable demand base for advanced driver-assistance systems. Major automotive production hubs like Shanghai and Guangzhou are integrating parking sensors as standard equipment. This focus on domestic production drives high fitment rates.
Germany
The European Union's General Safety Regulation (GSR) directly boosts sensor fitment rates across new vehicles in Germany. German automotive OEMs emphasize integrated sensor solutions for premium and mid-range segments. Stuttgart and Munich, major automotive development centers, concentrate R&D on next-generation sensor fusion capabilities. This prioritizes high-value perception modules.
United States
NHTSA safety ratings and guidelines encourage the adoption of parking aids in the US market. These ratings strongly influence consumer choice, accelerating feature fitment beyond luxury models. Automotive manufacturing clusters in Michigan and the Southeast are rapidly integrating advanced parking assistance into new passenger vehicles. This safety push drives demand for sophisticated systems.
Japan
Leading Japanese automotive manufacturers are integrating parking sensors as standard features across vehicle lines. METI initiatives supporting advanced driver-assistance systems further bolster market expansion. Major automotive R&D centers in Aichi Prefecture and Kanagawa are focusing on sensor fusion technologies. This ensures high accuracy and reliability in driver assistance.
India
The expanding automotive production sector in India is increasingly adopting parking sensors. BIS safety standards and local manufacturing incentives are driving the integration of these systems. Automotive clusters in Chennai and Pune are becoming significant centers for sensor fitment in new vehicles. This domestic production focus supports market growth.
Parking Sensors Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, defining the parking sensors market structure. This market exhibits a tiered competitive landscape with established automotive suppliers dominating the OEM channel. Strategic archetypes include integrated system providers, specialized hardware manufacturers, and software solution developers. Key competitive moves involve portfolio diversification into sensor fusion and strategic partnerships to enhance system integration.
Integrated system providers like Robert Bosch GmbH, a German multinational engineering and technology company, exemplify the shift towards bundled sensor and ECU packages. Continental AG, another German automotive supplier, occupies a position through its extensive portfolio covering radar, camera, and ultrasonic technologies. Valeo, a French automotive supplier, represents specialists in developing and supplying complete ADAS modules to major automotive OEMs worldwide. These companies anchor the market with their comprehensive perception solutions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Valeo |
| Aptiv |
| Autoliv Inc. |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| Murata Manufacturing Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Commodity price volatility for critical electronic components shapes both pricing tier spreads and the supply chain structure for parking sensors. This directly impacts manufacturing costs for hardware and supplier margins across the industry.
Pricing Analysis
Long-term, contract-based off-take agreements characterize OEM pricing for parking sensors, particularly for high-volume ultrasonic units. Price differentiation stems from sensor technology (ultrasonic vs. electromagnetic) and the level of software integration provided within complete ADAS modules. Pricing softness stems from intense cost compression demanded by automotive OEMs for basic, high-volume hardware components. Passenger vehicle OEMs for entry-level models are highly price-sensitive, while luxury vehicle manufacturers prioritize advanced feature sets and are less sensitive to component cost.
Supply Chain Analysis
Contract manufacturing concentration for parking sensors often centers in East Asia, particularly China, and European hubs like Germany, where major automotive suppliers operate. The supply chain draws from specialized inputs including ultrasonic transducers, application-specific integrated circuit (ASIC) chips, and automotive-grade plastics. Single-source vulnerability for specific semiconductor components represents a structural supply chain risk, impacting lead times and production stability. Downstream distribution runs predominantly through direct sales to automotive OEMs for factory integration across diverse vehicle platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The parking sensors market sits at a platform-economics inflection point, driven by the shift towards integrated ADAS ecosystems. This requires seamless interoperability between various sensor types and the vehicle's central ECU.
For Market Incumbents: Pre-empt the commoditization of standalone ultrasonic hardware by accelerating R&D into advanced sensor fusion capabilities. Consolidate market share through strategic acquisitions of specialized software firms focused on perception algorithms. This defends against the threat of substitution from advanced vision systems. Deepening vertical integration into software development serves as a critical lever.
For New Entrants and Emerging Players: Establish a beachhead in the commercial vehicle segment by offering robust, application-specific maneuvering assistance systems. Target underpenetrated emerging markets in Southeast Asia with cost-effective, reliable ultrasonic solutions. This segment offers significant white space for safety upgrades. A go-to-market angle focusing on reduced operational damage and enhanced fleet safety will resonate with fleet operators.
For Investors and Strategic Acquirers: The market sits at a maturation phase that favors integrated system providers capable of delivering complete perception solutions. Long-term viability is strong, driven by regulatory mandates and standardization of safety features in passenger vehicles. Acquisition targets should include software-centric firms specializing in sensor fusion algorithms and advanced ECU integration. Watch for a definitive shift in OEM procurement away from discrete sensors towards bundled ADAS modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Sensor Fusion R&D | Enhances perception capabilities for advanced driver-assistance systems across vehicle platforms. |
| Acquire ADAS Software Specialists | Strengthens integrated system offerings, responding to OEM demand for complete solutions. |
| Expand Commercial Vehicle Offerings | Addresses specific safety requirements for trucks and buses, tapping an underpenetrated market. |
| Develop Cost-Effective Wireless Solutions | Simplifies aftermarket installations and enables flexible new vehicle designs for emerging markets. |
| Standardize Communication Protocols | Reduces system integration complexity for automotive OEMs, accelerating adoption rates. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted, providing a comprehensive market perspective. Primary interviews with automotive OEM platform engineers, Tier 1 procurement managers, and ADAS software developers yielded critical insights. This was triangulated with secondary validation from NHTSA safety ratings, EU General Safety Regulation documents, and automotive production databases. A bottom-up approach to market sizing was reconciled with top-down industry estimates.
Market forecast calibration relied on a multi-stage analytical framework applied across the analysis window. Segmentation dimensions modeled included product type, installation channel, end-user segment, technology, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected adoption rates. Key industry-specific forecast inputs included vehicle production volumes and advanced driver-assistance system fitment rates.
Stress conditions across regulatory changes, technological disruptions, and economic shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding automotive OEM strategies. Quarterly review of regulatory updates and OEM technology roadmaps is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Wireless Ph Monitoring Systems Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
North America Wireless Sensors Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Inline Viscosity Sensor Market
Sensors and Controls
Conveyor Belt Tracking Devices Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Laser Scanner Market