
 North America Weapon Night Sight Market | 2026-2036
North America Weapon Night Sight Market Size, Share, and Industry Trends Forecast 2026-2036
North America Weapon Night Sight Market Insights
Subscription-based firmware and software-defined reticle updates is consolidating recurring revenue into hardware contracts across the North America Weapon Night Sight Market. L3Harris Technologies leverages its vertically integrated sensor foundries to sustain cost advantages on image intensification tubes. Teledyne FLIR anchors thermal core supply for multiple prime integrators. Elbit Systems competes through specialized clip-on thermal weapon sight architectures optimized for modular rifle platforms.
A weapon night sight is an electro-optical aiming device that amplifies ambient light or detects infrared radiation to enable target acquisition in near-total darkness, typically incorporating gallium arsenide photocathodes or vanadium oxide microbolometer arrays with detection thresholds below 50 millikelvin noise-equivalent temperature difference. These systems serve military, law enforcement, and civilian shooters requiring positive target identification beyond unaided human visual range. Thermal imaging technology leads value generation due to its passive operation and all-weather performance, while digital night vision represents the fastest-expanding category as solid-state sensors displace legacy vacuum tube architectures. Image intensification remains mature with concentrated margin pools in specialized tube manufacturing, and rail-mounted installation types dominate volume through MIL-STD-1913 compatibility requirements.
The U.S. State Department Directorate of Defense Trade Controls enforces ITAR restrictions that limit foreign participation and shape domestic supplier ecosystems, while the FDA regulates laser-emitting components under 21 CFR 1040.10 performance standards affecting laser sight product configurations. Industry stakeholders must monitor evolving CMMC cybersecurity certification requirements for defense contractors and assess digital sensor supply chain exposure to export control classifications on focal plane arrays.
Market Dynamics
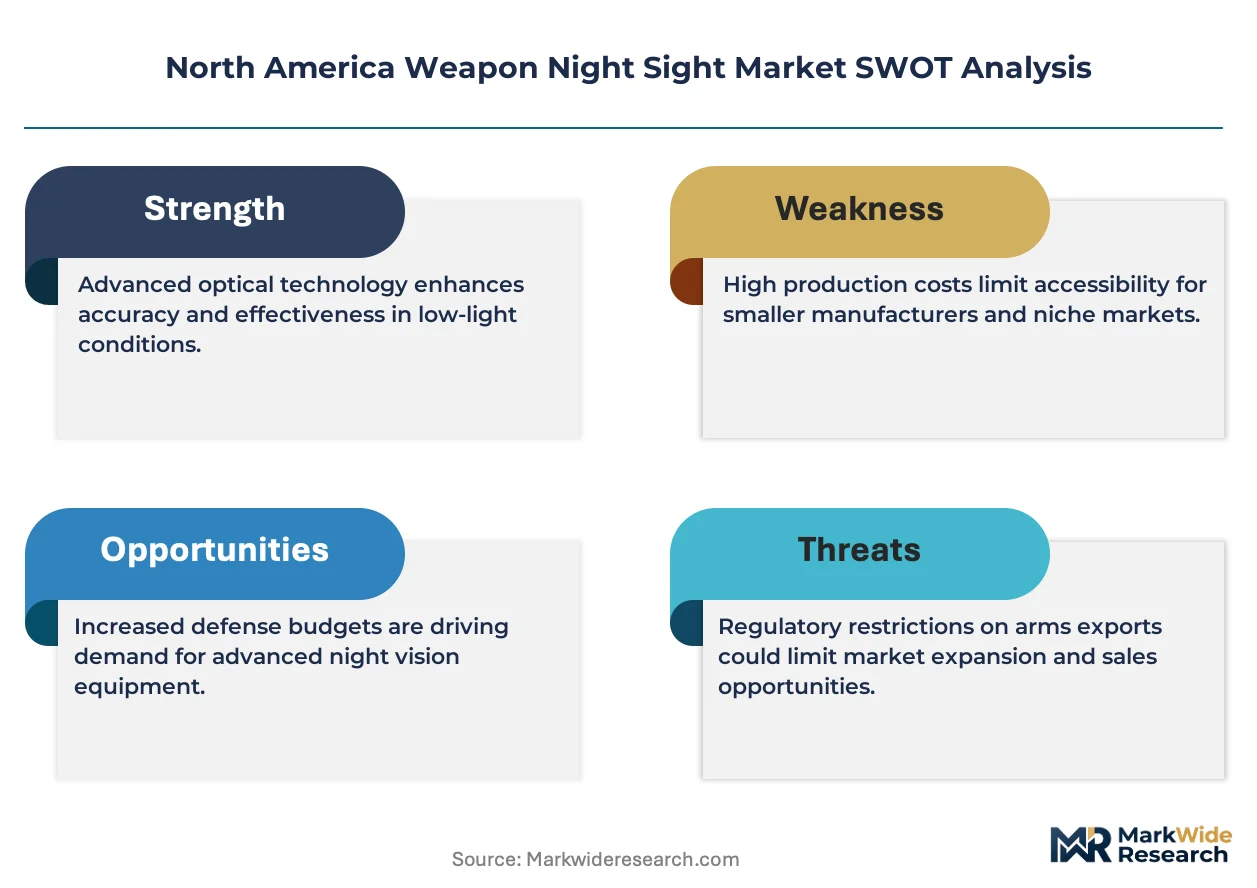
ITAR compliance requirements and CMMC cybersecurity mandates are forcing domestic supplier consolidation across the North America Weapon Night Sight Market, as foreign component sourcing faces escalating export control scrutiny on focal plane arrays and image intensification tubes.
Growth Catalysts
- Military Modernization Programs:The United States Department of Defense accelerates thermal imaging procurement for infantry and special operations units. Canadian Armed Forces follow with parallel equipment refresh cycles.
- Fused Digital Night Vision:Solid-state sensor architectures combining thermal cores with low-light CMOS arrays enable single-device versatility. Warfighter demand drives rapid qualification of these hybrid systems.
- Law Enforcement Equipment Standards:POST certification requirements in California and Texas mandate night vision capability for tactical response teams. State-level procurement creates secondary demand channels beyond federal contracts.
Market Restraints
- Gallium Arsenide Photocathode Supply:Image intensification tube production depends on constrained rare earth processing capacity concentrated in domestic specialty chemical facilities.
- ITAR Compliance Friction:The U.S. State Department Directorate of Defense Trade Controls creates 12-18 month approval timelines for technical data sharing with Canadian partners, slowing cross-border development programs.
- Uncooled Microbolometer Cost Structure:Vanadium oxide focal plane arrays require precision MEMS fabrication with limited North American foundry capacity, pressuring thermal sight margins.
Strategic Opportunities
- Civilian Sporting Applications:Texas and Arizona state regulations permit night vision equipment for feral hog and predator control. Ranching and agricultural sectors represent underpenetrated end-uses.
- Subscription Firmware Models:Software-defined reticle updates and ballistic calculator integrations create recurring revenue streams alongside hardware sales.
- CMMC Certification Services:Defense contractors require third-party assessment organizations to achieve cybersecurity maturity model compliance, opening adjacent service revenue for qualified integrators.
Industry Challenges
- Image Intensification Tube Engineering Talent:Gallium arsenide photocathode fabrication and MCP assembly require skills concentrated among retiring workforce cohorts at legacy defense suppliers.
- Legacy System Integration:MIL-STD-1913 rail compatibility demands create mechanical interface complexity when mating digital thermal sights to Vietnam-era weapon platforms still in reserve inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Weapon Night Sight Market |
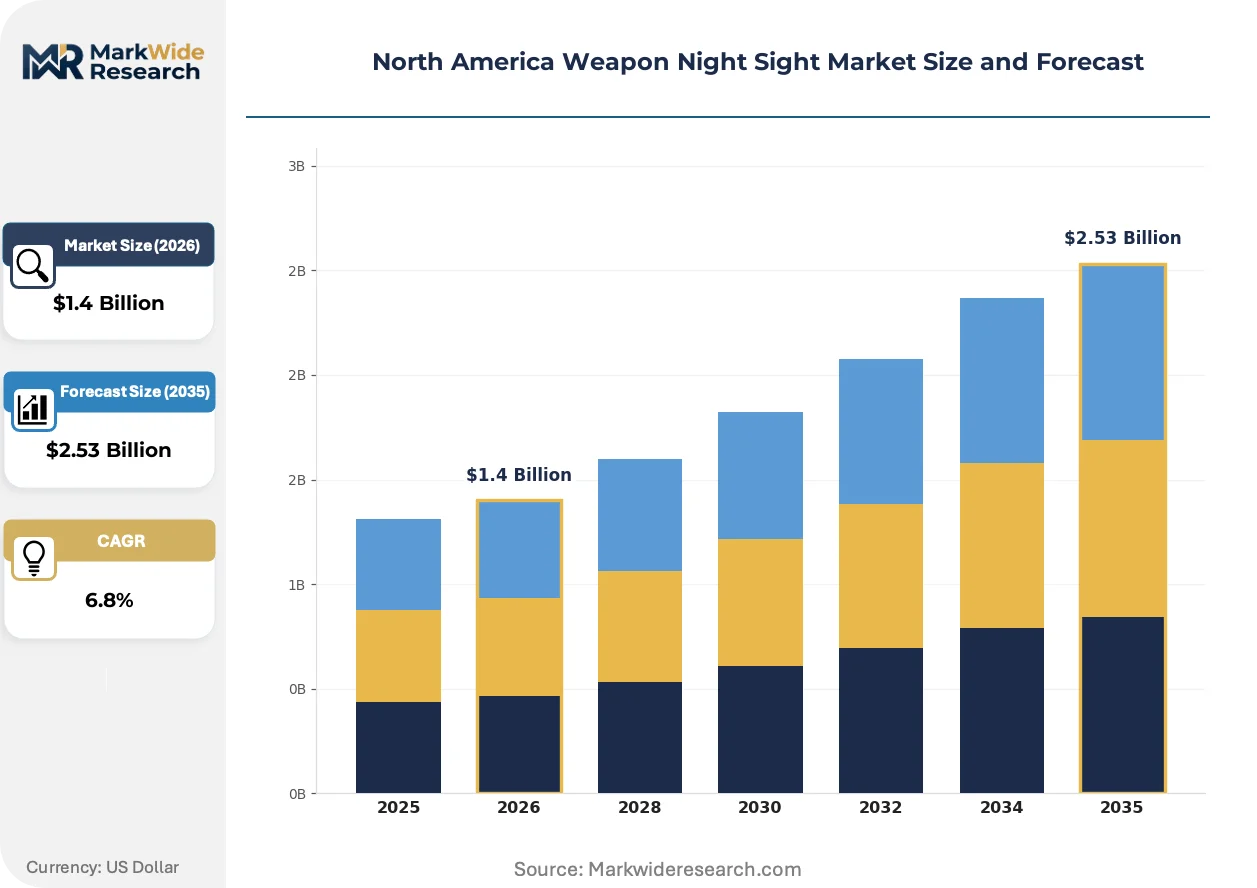
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared Sights, Thermal Sights, Low-Light Sights, Laser Sights Technology: Image Intensification, Thermal Imaging, Digital Night Vision, Bi-ocular Systems End User: Military, Law Enforcement, Civilian, Hunters Installation Type: Rail-Mounted, Integrated Systems, Standalone Units, Clip-On Devices |
| Companies Covered | L3Harris Technologies, Inc., BAE Systems Plc, Raytheon Technologies Corporation, Elbit Systems Ltd., Thales Group, Teledyne FLIR LLC, Excelitas Technologies Corp., Leonardo DRS, Inc., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Weapon Night Sight Market Trends and Innovations
Fused sensor architectures and software-defined functionality are compressing hardware replacement cycles across military and law enforcement procurement channels. Technical evolution favors modular platforms over fixed-configuration legacy systems.
Digital night vision is unifying thermal detection and image intensification within single electro-optical packages. U.S. Army Soldier Lethality Cross-Functional Team accelerates fielding of these fused systems for close combat formations. The technology is unifying previously separate thermal and I2 supply chains into consolidated vendor ecosystems.
The U.S. State Department CMMC framework mandates cybersecurity certification for all defense contractors handling controlled unclassified information. Prime integrators now require CMMC Level 2 attestation from thermal core and tube suppliers. Small specialty manufacturers in Arizona and Texas face 18-24 month compliance timelines.
Unit-level procurement authority is fragmenting traditional bulk acquisition patterns. Individual special operations elements and state National Guard units now source clip-on thermal weapon sights through simplified commercial channels. This behavioral shift concentrates in the southwestern United States defense corridor where proximity to border operations drives immediate equipment needs.
North America Weapon Night Sight Market Segmentation
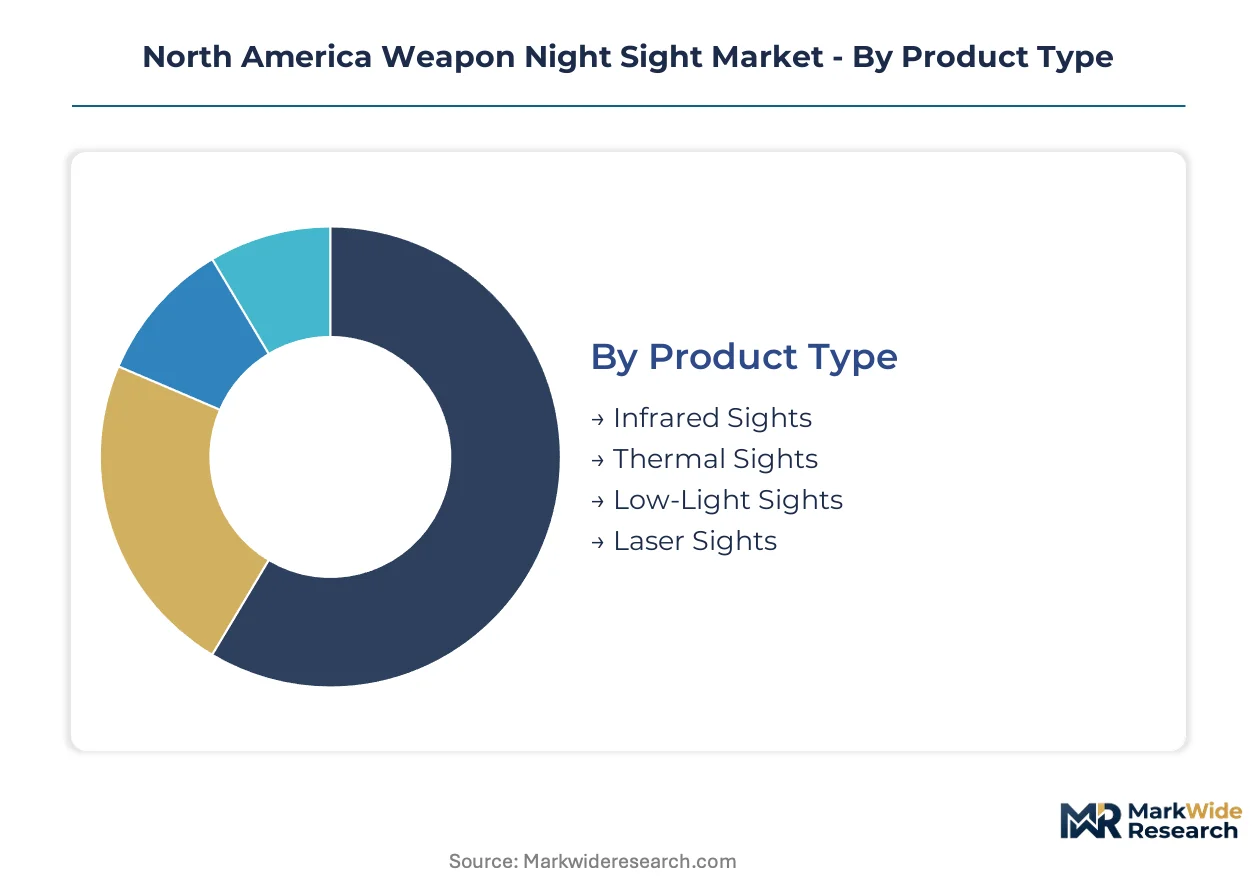
Weapon night sight procurement patterns diverge sharply between volume-driven military contracts and premium-tier special operations requirements. Technology maturity and ITAR compliance status further stratify supplier access across end-user categories.
Product Type:
Volume concentrates in standardized thermal configurations, while premium capture sits with multi-sensor fused systems.
- Thermal Sights:Vanadium oxide microbolometer arrays detect infrared radiation passively, enabling all-weather target acquisition without active illumination. U.S. Army infantry brigades and Texas state tactical teams drive procurement concentration, constrained by limited North American MEMS foundry capacity for focal plane arrays.
- Infrared Sights:Near-infrared laser-aiming modules paired with compatible image intensification tubes provide precision engagement at squad-level distances. Demand clusters in Arizona and Texas border operations where federal task forces coordinate with state agencies on interdiction missions.
- Low-Light Sights:Solid-state CMOS sensors amplify residual ambient illumination for cost-sensitive applications.
- Laser Sights:FDA 21 CFR 1040.10 compliance requirements shape emitter power classifications and eye-safety interlocks.
Mature deployment sits with Infrared Sights. Newer deployment is concentrated in Thermal Sights.
Technology:
Legacy vacuum tube architectures retain installed base dominance, though solid-state platforms command development investment priority.
- Digital Night Vision:Fused architectures combining thermal cores with low-light CMOS arrays unify previously separate detection modalities within single electro-optical packages. U.S. Army Soldier Lethality Cross-Functional Team accelerates fielding for close combat formations, displacing legacy I²-only equipment.
- Thermal Imaging:Uncooled microbolometers eliminate cryogenic cooling requirements, reducing size and power burden for dismounted warfighters. Canadian Armed Forces procurement and southwestern U.S. law enforcement agencies represent parallel demand channels.
- Image Intensification:Gallium arsenide photocathodes and microchannel plate assemblies deliver extreme low-light sensitivity for specialized applications.
- Bi-ocular Systems:Dual-tube configurations provide depth perception and extended observation comfort for sustained surveillance operations.
Established procurement favors Image Intensification. Steepest expansion trajectory belongs to Digital Night Vision.
End User:
Federal defense contracts anchor volume, with state-level law enforcement creating secondary demand fragmentation.
- Military:Department of Defense modernization programs prioritize thermal imaging procurement for infantry and special operations units, with unit-level acquisition authority fragmenting traditional bulk purchasing patterns. ITAR compliance and CMMC Level 2 certification filter supplier participation.
- Law Enforcement:POST certification mandates in California and Texas require night vision capability for tactical response teams, generating state-procurement channels outside federal contracting vehicles. Border corridor agencies show highest equipment refresh rates.
- Civilian:Ranching and agricultural pest control applications in Texas and Arizona represent emerging adoption segments.
- Hunters:State regulations permitting night vision equipment for feral hog and predator control create localized demand pockets.
Institutional procurement dominates Military end-use. Fastest-growing participation is emerging among Civilian users.
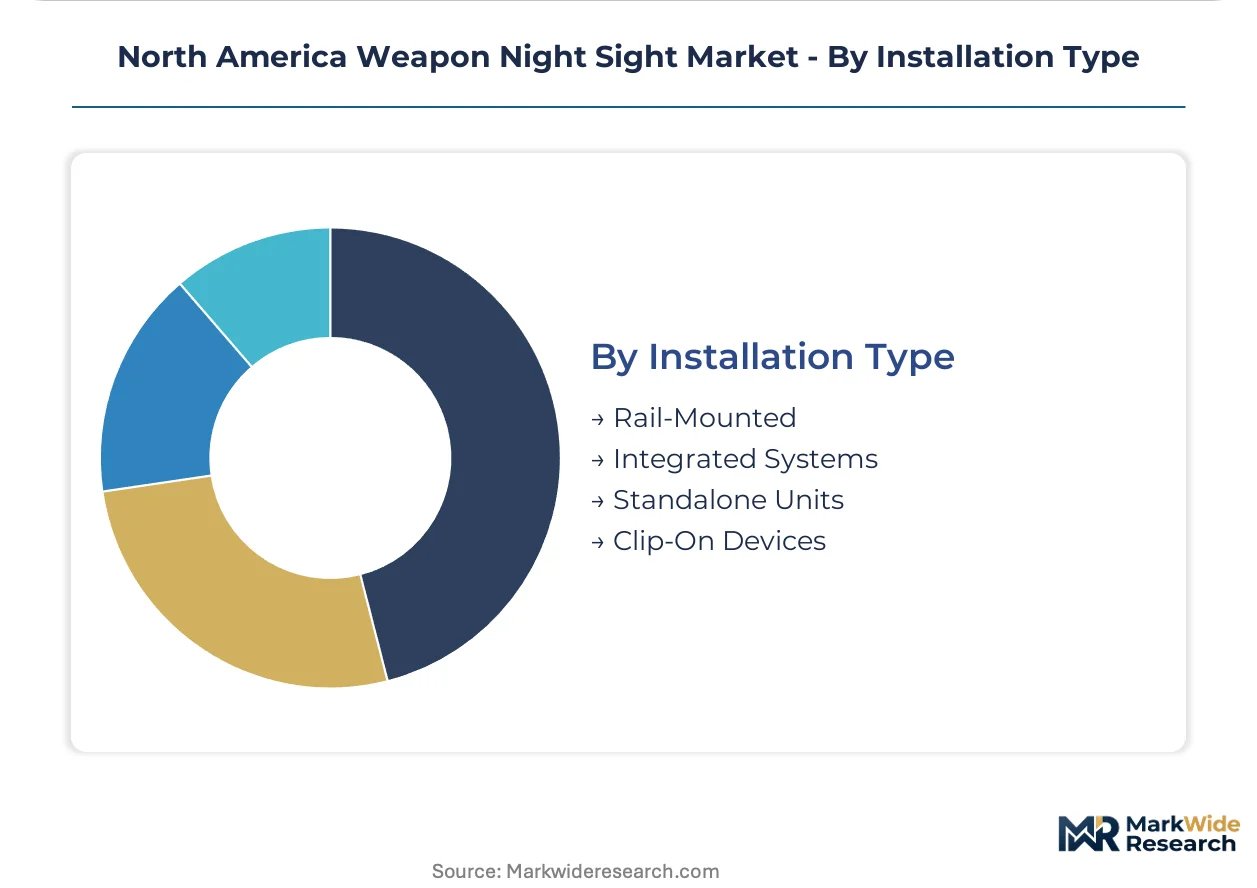
Installation Type:
MIL-STD-1913 rail compatibility governs mechanical interface standardization across weapon platforms.
- Rail-Mounted:Picatinny rail attachment systems enable rapid optic transfer between weapon hosts without armorer intervention. Volume concentration reflects universal compatibility with legacy and modern rifle platforms across U.S. and Canadian inventories.
- Clip-On Devices:Thermal weapon sights designed for forward-mounted installation ahead of existing day optics preserve zeroed ballistic solutions. Special operations elements and National Guard units in southwestern states source these through simplified commercial channels for immediate operational needs.
- Integrated Systems:Factory-embedded electro-optical packages optimize weight distribution and bore alignment.
- Standalone Units:Dedicated night vision weapon sights with self-contained power and control architectures suit non-standard weapon configurations.
Conventional deployment favors Rail-Mounted systems. Modular adoption is accelerating through Clip-On Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the majority of regional output while Canadian defense procurement creates secondary demand channels. Mexico maintains limited indigenous production capacity, serving primarily as a logistics corridor for cross-border military shipments.
United States
Department of Defense modernization programs drive thermal imaging procurement for infantry brigades and special operations formations. The U.S. State Department enforces ITAR restrictions that limit foreign component sourcing and shape domestic supplier ecosystems. Arizona and Texas host concentrated defense industrial corridors where unit-level acquisition authority fragments traditional bulk purchasing patterns.
Canada
Canadian Armed Forces equipment refresh cycles parallel U.S. procurement timelines, creating synchronized demand for clip-on thermal weapon sights. Health Canada and PMRA coordinate with U.S. FDA on laser-emitting component standards affecting cross-border product configurations. Ontario and Quebec defense contractors face 12-18 month ITAR approval timelines for technical data sharing with American partners.
Mexico
Federal police and military counter-narcotics operations generate modest demand for night vision equipment through U.S. foreign military sales channels. The Secretariat of National Defense regulates electro-optical imports under domestic security equipment classifications. Northern border states function as transshipment nodes rather than consumption centers, with Baja California and Chihuahua serving logistical roles for southwestern U.S. defense corridors.
Southwestern U.S. Defense Corridor
Proximity to border operations drives immediate equipment needs among National Guard units and federal task forces. POST certification requirements in Texas and California mandate night vision capability for state tactical response teams. Arizona and New Mexico host emerging specialty manufacturers facing 18-24 month CMMC compliance timelines.
Pacific Northwest
Specialized research institutions contribute to solid-state sensor development for next-generation fused digital systems. Regional defense contractors leverage proximity to Seattle and Portland technology clusters for CMOS array integration. Washington state facilities focus on prototype qualification rather than volume production.
North America Weapon Night Sight Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North America Weapon Night Sight Market. Vertically integrated sensor foundries sustain cost advantages on image intensification tubes and focal plane arrays. Three strategic archetypes dominate: prime system integrators with captive component production, specialized thermal core suppliers selling to multiple integrators, and modular clip-on sight specialists. Competitive moves concentrate on CMMC certification attainment and fused sensor architecture qualification.
Among U.S.-based prime integrators, L3Harris Technologies, Inc. and Raytheon Technologies Corporation occupy positions anchored by defense electronics heritage. Teledyne FLIR LLC represents the specialized thermal core supplier archetype, serving multiple prime integrators from its sensor foundry base. Elbit Systems Ltd. exemplifies the modular specialist approach through clip-on thermal weapon sight architectures. These three anchors reflect the market's tripartite structure: integrated primes, component specialists, and modular innovators.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| BAE Systems Plc |
| Raytheon Technologies Corporation |
| Elbit Systems Ltd. |
| Thales Group |
| Teledyne FLIR LLC |
| Excelitas Technologies Corp. |
| Leonardo DRS, Inc. |
| Rheinmetall AG |
| Others |
Pricing and Supply Chain Analysis
Vanadium oxide microbolometer wafers flow from limited North American MEMS foundries through three pricing tiers before reaching defense integrators and state law enforcement buyers.
Pricing Analysis
Margin tightening in thermal core procurement reflects gallium arsenide photocathode scarcity and ITAR compliance overhead. Three-tier pricing structure across ITAR-certified, CMMC-attested, and commercial-grade levels separates defense prime contracts from state agency procurement and civilian sporting channels. Cost-down pressure on uncooled focal plane arrays accelerates because foundry capacity constraints persist in Arizona and Texas. Military end-users show lowest price sensitivity due to mission-critical requirements, while ranching and agricultural segments in southwestern states demonstrate highest elasticity.
Supply Chain Analysis
Freight consolidation costs for ITAR-controlled components escalate as technical data sharing approvals extend cross-border timelines with Canadian partners. Image intensification tube production draws from domestic specialty chemical facilities in the United States, while thermal sensor assembly rests on Mexican contract manufacturing near the Arizona border. Single-source vulnerability concentrates in gallium arsenide photocathode processing capacity. Distribution runs through defense prime integrators to military units, with simplified commercial channels serving National Guard and law enforcement procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMMC cybersecurity mandates and ITAR compliance friction are forcing supplier consolidation across the North America Weapon Night Sight Market, eliminating undercapitalized component manufacturers unable to sustain 18-24 month certification timelines.
For Market Incumbents: Hedge against focal plane array supply concentration by securing captive MEMS foundry capacity or long-term offtake agreements with Arizona and Texas specialty manufacturers. Deepen backward integration into gallium arsenide photocathode processing to offset rare earth chemical supply constraints. Prioritize CMMC Level 2 attestation investments to filter competitor access to prime integrator supply chains. For New Entrants and Emerging Players: Solid-state fused sensor architectures offer entry pathways into modular clip-on thermal weapon sight segments where special operations elements and National Guard units exercise unit-level procurement authority. Target civilian sporting applications in Texas and Arizona where state regulations permit night vision equipment for agricultural pest control. Pursue direct commercial sales channels bypassing traditional defense contracting vehicles. For Investors and Strategic Acquirers: CMMC certification backlog clearing is the leading indicator that consolidation velocity will accelerate among Arizona and Texas specialty manufacturers. Five-to-ten-year viability favors asset-light designers with software-defined reticle platforms over capital-heavy tube fabricators facing workforce retirement cliffs. Acquisition target archetype: modular clip-on sight specialists with existing ITAR registration and proven thermal core supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| CMMC Level 2 Certification Attainment | Unlocks prime integrator supply chain access for thermal core and tube suppliers competing for Department of Defense contracts. |
| Fused Digital Night Vision Qualification | Accelerates fielding through U.S. Army Soldier Lethality Cross-Functional Team procurement channels displacing legacy I² equipment. |
| Civilian Channel Development | Captures ranching and agricultural demand in Texas and Arizona where state regulations permit night vision for predator control. |
| Subscription Firmware Platform Launch | Generates recurring revenue streams through software-defined reticle updates and ballistic calculator integrations alongside hardware sales. |
| Cross-Border Technical Data Agreement | Reduces 12-18 month ITAR approval timelines with Canadian partners for synchronized equipment refresh cycles. |
Research Methodology
Defense procurement databases, ITAR registration filings, and state-level POST certification records formed the secondary backbone for demand quantification. Primary interviews with thermal core procurement officers at prime integrators, CMMC assessment organization leads, and Arizona and Texas specialty manufacturer executives validated supply-side constraints. Bottom-up and top-down triangulation reconciled unit-level acquisition patterns with aggregate Department of Defense modernization program budgets.
Bottom-up modeling aggregated segment-specific demand across military, law enforcement, and civilian end-users, while top-down validation cross-checked against aggregate defense electronics procurement disclosures. Segmentation dimensions included technology type, installation configuration, and end-user category across the projection horizon. CAGRs derived from equipment refresh cycle timing, ITAR approval velocity, and MEMS foundry capacity expansion trajectories. Industry-specific inputs incorporated Soldier Lethality Cross-Functional Team fielding schedules and Texas and Arizona state regulatory developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control reclassification of focal plane arrays or accelerated gallium arsenide supply disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Electrical Weapon Market
Weapons and Ammunition
Military Fuze Market
Weapons and Ammunition
Surface to Air Missiles Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Torpedo Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
North America Small Arms Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
High Power Microwave Directed Energy Weapons Market
Weapons and Ammunition
Medium Caliber Ammunition Market
Weapons and Ammunition
Close-In Weapon Systems Market
Weapons and Ammunition
Programmable Ammunition Market