
 Nimodipine Market | 2026-2036
Nimodipine Market Size, Share, and Industry Trends Forecast 2026-2036
Nimodipine Market Analysis
Market Context with Strategic Players
Hospital procurement for nimodipine is hardening around large integrated delivery networks and specialized neurocritical care centers. Arbor Pharmaceuticals LLC leverages its orphan-drug positioning and concentrated hospital channel relationships. Fresenius Kabi AG anchors the injectable segment through parenteral manufacturing scale and ICU formulary presence. Zhejiang Huahai Pharmaceutical Co. Ltd. competes on API cost structure and regulatory dossier breadth across multiple national markets.
Technical Definition and Structural Segments
Nimodipine is a dihydropyridine calcium channel blocker formulated at 30 mg oral dosage and 0.2 mg/mL injectable concentration, selectively antagonizing calcium influx in cerebral vascular smooth muscle to prevent vasospasm following subarachnoid hemorrhage. The injectable formulation dominates acute-phase hospital revenue due to ICU protocol adherence and inability to administer oral agents in intubated patients. Tablet and capsule segments serve step-down and outpatient continuation therapy, with oral solution capturing pediatric and dysphagia populations where swallowing function is compromised. Subarachnoid hemorrhage therapy area commands the largest patient-treatment volume, while cerebral aneurysm prophylaxis represents the fastest-growing indication as endovascular coiling procedures expand.
Regulatory Framework and Forward Outlook
FDA bioequivalence standards for nimodipine generics, EMA's centralized marketing authorization requirements, and USP dissolution specifications collectively govern product approval and interchangeability across jurisdictions. The FDA's Risk Evaluation and Mitigation Strategy for oral nimodipine, combined with EMA's pharmacovigilance obligations for calcium channel blockers, elevates compliance costs for new entrants. Stakeholders must monitor evolving neurocritical care protocol standardization and generic substitution policies at major hospital systems.
Market Dynamics
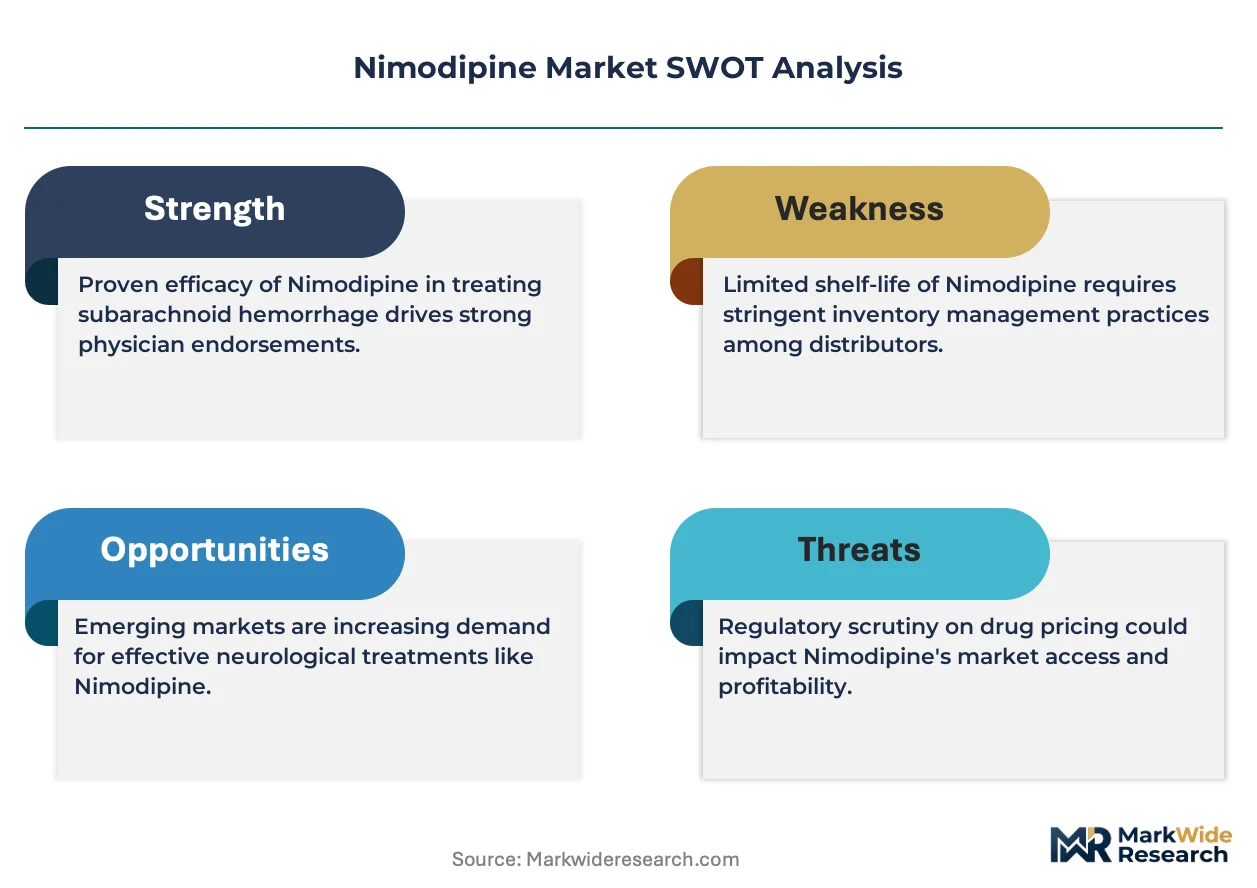
Hospital procurement consolidation around integrated delivery networks is concentrating purchasing power for nimodipine, forcing manufacturers to negotiate directly with centralized pharmacy committees rather than individual neurocritical care units. This structural shift favors suppliers with dedicated hospital channel infrastructure and REMS compliance capabilities.
Growth Catalysts
- FDA Risk Evaluation and Mitigation Strategy:The mandatory REMS for oral nimodipine creates compliance barriers that protect validated suppliers from price erosion, preserving margin structures for certified manufacturers.
- Endovascular coiling expansion:Minimally invasive cerebral aneurysm repair is extending prophylactic nimodipine protocols to pre-intervention and post-procedure windows, enlarging the addressable patient population.
- Japan's aging neurosurgical demographic:Rising subarachnoid hemorrhage incidence among elderly populations is expanding tertiary center admissions and sustained-release formulation demand.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in select Chinese manufacturing zones, exposing finished dose formulators to geopolitical disruption and quality inspection backlogs.
- EMA pharmacovigilance burden:Post-market surveillance obligations for calcium channel blockers elevate compliance costs disproportionately for generic entrants without established pharmacovigilance infrastructure.
- Alternative vasospasm management:Intra-arterial verapamil and balloon angioplasty protocols in select German and US centers reduce protocol adherence to oral nimodipine continuation therapy.
Strategic Opportunities
- Pediatric oral solution expansion:Dysphagia and pediatric subarachnoid hemorrhage populations remain underserved by current tablet-centric supply, creating white space for taste-masked liquid formulations.
- Japan's regenerative medicine acceleration:METI funding for neuroprotective drug-device combinations opens pathways for nimodipine-eluting stent coatings in cerebral aneurysm repair.
- Direct-to-hospital distribution:Bypassing wholesale intermediaries through 340B program compliance and specialty pharmacy partnerships captures margin and improves cold chain integrity for injectable formulations.
Industry Challenges
- Neurocritical care pharmacist scarcity:Specialized expertise in calcium channel blocker titration and drug interaction management limits protocol standardization across community hospital expansions.
- REMS audit preparation:Documentation requirements for patient counseling, pharmacy verification, and prescriber certification consume operational bandwidth without revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nimodipine Market |
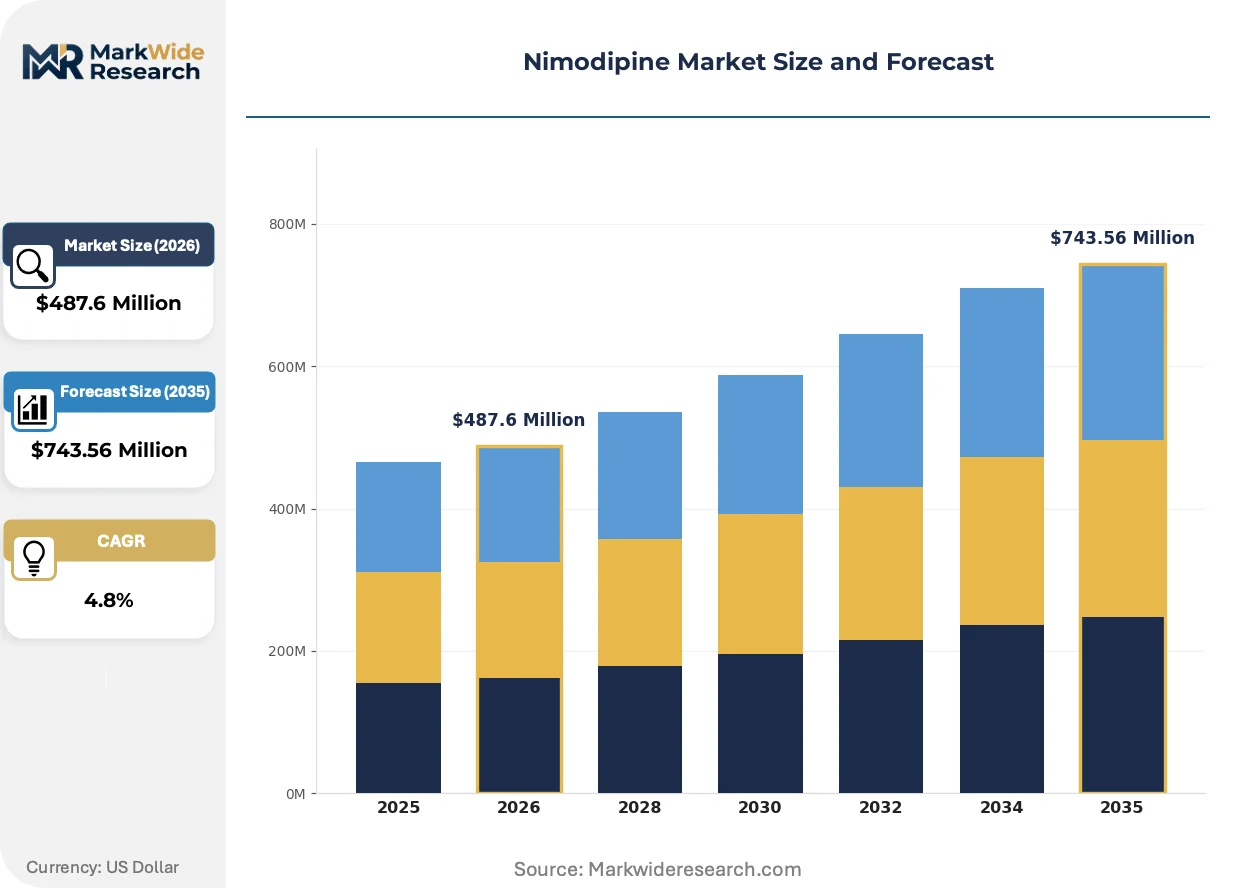
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Tablets, Oral Solution, Capsules End User: Hospitals, Clinics, Rehabilitation Centers, Homecare Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Drug Wholesalers Therapy Area: Cerebral Aneurysm, Subarachnoid Hemorrhage, Vascular Disorders, Neurological Conditions |
| Companies Covered | Arbor Pharmaceuticals LLC, Sandoz International GmbH, Sun Pharmaceutical Industries Ltd., Aurobindo Pharma, Fresenius Kabi AG, Bayer Vital GmbH, Teva Pharmaceutical Industries Ltd., Zhejiang Huahai Pharmaceutical Co. Ltd., Bionpharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nimodipine Market Emerging Trajectories
Formulation science and delivery mechanism innovation are reshaping competitive differentiation in nimodipine, moving beyond bioequivalence toward administration convenience and adherence engineering in acute and step-down settings.
Nanoparticle-based nimodipine formulations are integrating enhanced bioavailability engineering with parenteral compatibility profiles. Neurocritical care units in US academic medical centers are piloting these platforms for patients with compromised gastrointestinal absorption. This technology is integrating sustained-release kinetics into existing ICU protocols without requiring line changes or compatibility testing.
EMA's Medical Device Regulation harmonization is compressing the pathway for drug-device combination products in cerebrovascular intervention. Manufacturers with dual regulatory capabilities are positioning nimodipine-coated flow diverters and stent systems. The neurointerventional device segment is responding by consolidating supplier relationships around platforms with existing pharmaceutical quality systems.
Hospital pharmacy consolidation into centralized 340B purchasing entities is compressing vendor rosters and extending contract durations. Neurocritical care service lines are ceding procurement autonomy to system-level pharmacy directors. This concentration is most visible in US integrated delivery networks spanning multiple states, where formulary standardization overrides individual physician preference.
Nimodipine Market Segmentation
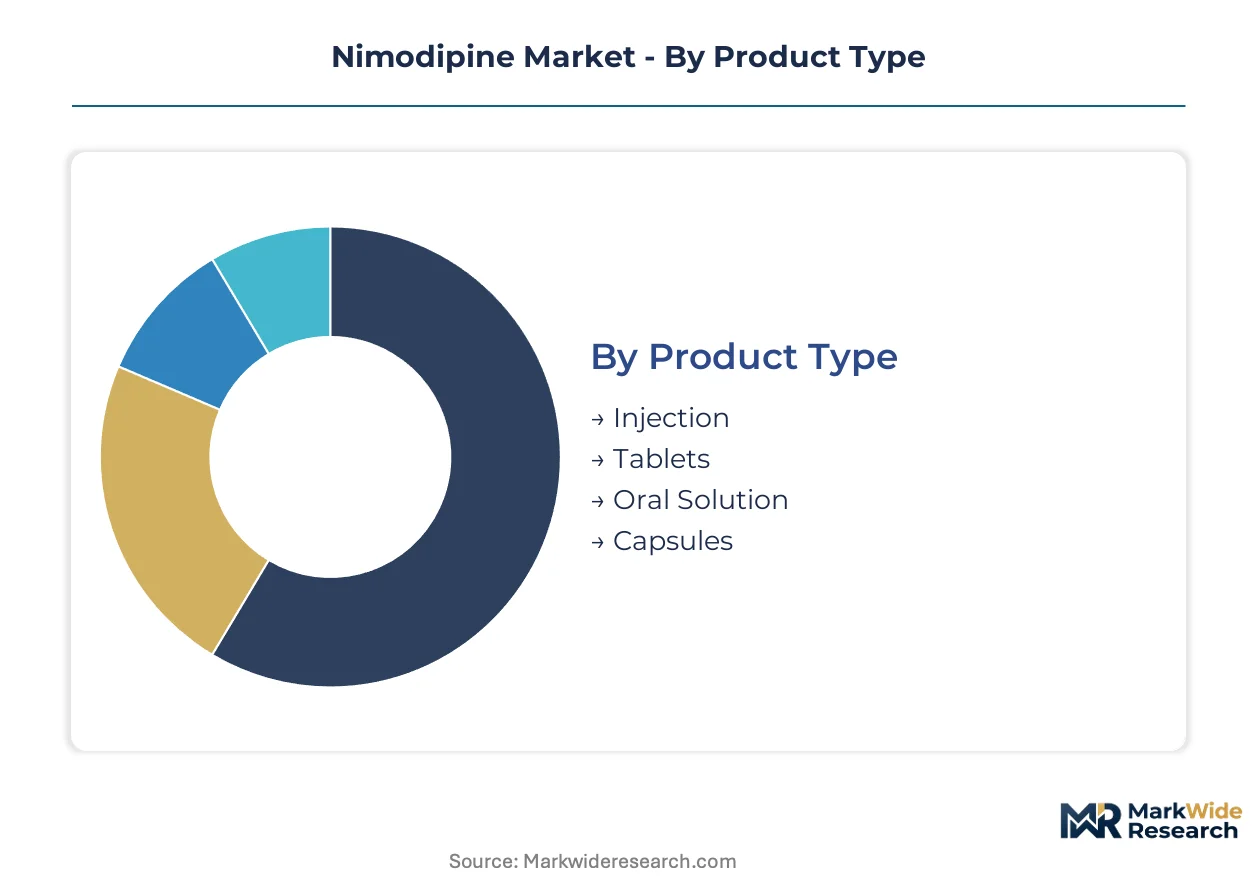
Hospital procurement consolidation and REMS compliance requirements are fragmenting nimodipine demand across formulation types and channel structures. Understanding how supply concentration maps to segment performance reveals where manufacturers must anchor manufacturing scale versus specialty capabilities.
Product Type:
Injectable capacity clusters around parenteral manufacturing specialists with ICU formulary access, while oral formulations compete on bioequivalence dossiers and taste-masking technology.
- Injection:Formulated at 0.2 mg/mL for intravenous or intra-arterial administration in intubated patients unable to tolerate oral therapy. Demand concentrates in US tertiary neurosurgical centers where ICU protocol adherence mandates parenteral initiation; Fresenius Kabi's manufacturing scale anchors supply security for this segment.
- Tablets:30 mg immediate-release oral dosage forms dominate step-down therapy and outpatient continuation. German hospital pharmacies are standardizing on specific bioequivalence-certified suppliers to simplify REMS documentation; tablet volume reflects discharge protocol adherence rates.
- Oral Solution:Liquid formulations serve dysphagia patients and pediatric subarachnoid hemorrhage cases where swallowing function is compromised. Taste-masked suspensions remain underdeveloped relative to tablet infrastructure.
- Capsules:Alternative oral dosage form with limited differentiation from tablets; capsule demand tracks regional pharmacy compounding preferences and insurance reimbursement tiering.
Injection absorbs the bulk of installed capacity; oral solution is expanding most quickly as pediatric neurocritical care protocols mature.
End User:
Patient acuity and reimbursement structures are concentrating nimodipine consumption around facilities with neurocritical care certification and 340B program eligibility.
- Hospitals:Integrated delivery networks with specialized neurosurgical units command procurement volume through centralized pharmacy committees. US academic medical centers in Boston, Houston, and Baltimore anchor demand for injectable formulations; REMS compliance infrastructure separates approved suppliers from excluded vendors.
- Clinics:Outpatient neurology and vascular surgery clinics manage continuation therapy for stabilized patients. Clinic prescribing patterns in Germany's ambulatory sector favor oral generics with simplified pharmacy verification workflows.
- Rehabilitation Centers:Post-acute facilities handle extended oral nimodipine courses for patients recovering from endovascular coiling. Rehabilitation demand tracks aneurysm repair procedure volume and step-down protocol standardization.
- Homecare:Home infusion and specialty pharmacy services deliver oral and limited injectable therapy for discharged patients. Homecare penetration remains constrained by REMS patient counseling documentation requirements.
Hospitals command the dominant share of procurement volume; homecare is climbing the fastest as discharge optimization programs expand.
Distribution Channel:
Cold chain requirements for injectable formulations and REMS verification steps are reshaping channel economics toward direct manufacturer-hospital relationships.
- Hospital Pharmacies:Internal pharmacy operations within integrated delivery networks manage formulary placement and REMS compliance verification. Hospital pharmacy consolidation in US multi-state systems is compressing vendor rosters to three or fewer approved suppliers per network.
- Retail Pharmacies:Community and specialty pharmacies dispense oral continuation therapy with prescriber certification checks. Retail channel share reflects outpatient prescription volume and insurance network participation.
- Online Pharmacies:Mail-order and digital pharmacy platforms serve maintenance therapy patients with established prescriptions. Online penetration tracks specialty pharmacy benefit design and prior authorization automation.
- Drug Wholesalers:Traditional wholesale intermediaries face margin compression as 340B direct purchasing and specialty distribution bypass their infrastructure. Wholesaler relevance concentrates on generic oral products without REMS requirements.
Hospital pharmacies handle the majority of acute-phase volume; online pharmacies are gaining share fastest in maintenance therapy segments.
Therapy Area:
Procedure expansion in cerebrovascular intervention is extending nimodipine protocols beyond traditional subarachnoid hemorrhage treatment windows.
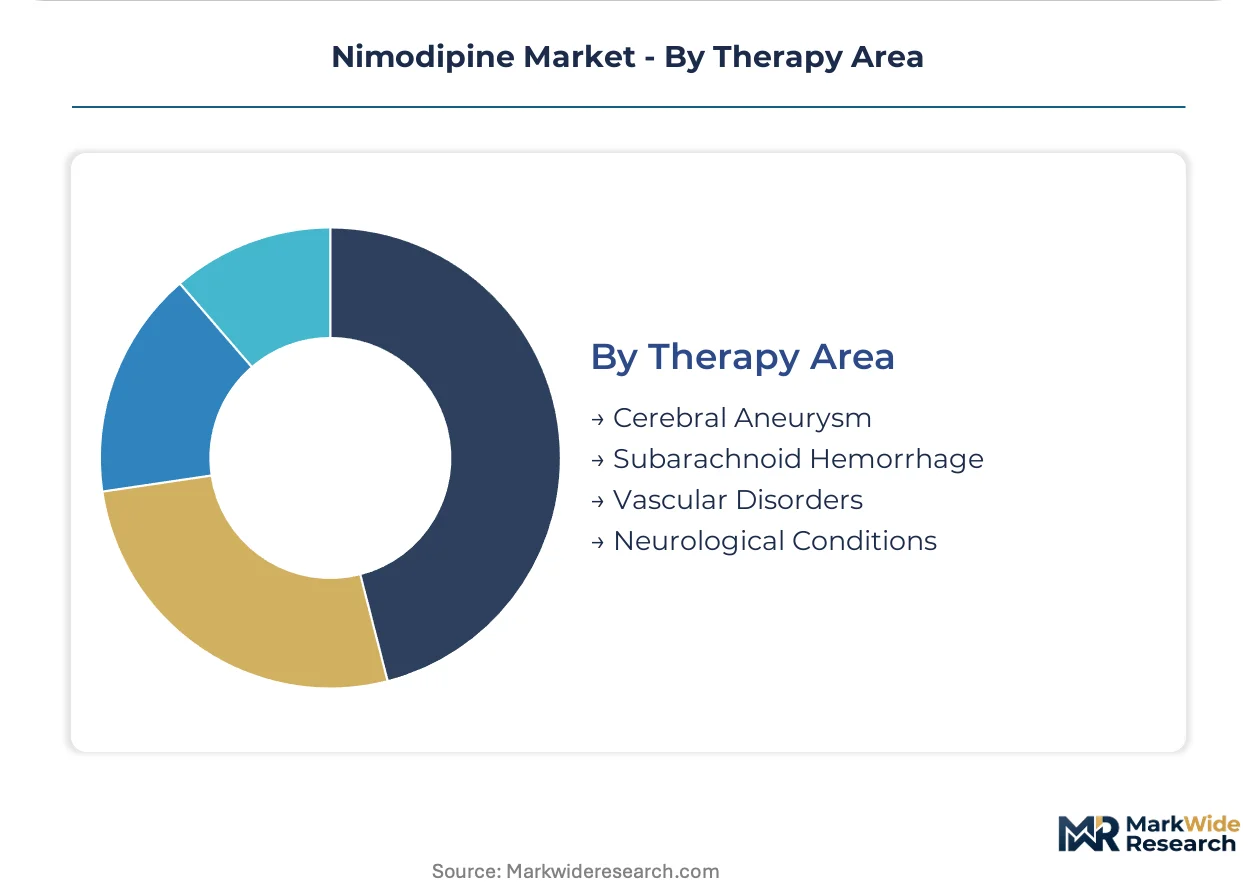
- Subarachnoid Hemorrhage:Established indication for vasospasm prevention following aneurysmal bleeding. US and Japanese tertiary centers anchor patient volume; protocol adherence rates determine per-facility consumption intensity.
- Cerebral Aneurysm:Prophylactic administration before and after endovascular coiling procedures. German neurointerventional centers are expanding aneurysm protocols to pre-intervention windows; this segment reflects steepest expansion trajectory as minimally invasive repair volumes climb.
- Vascular Disorders:Off-label and investigational applications in broader cerebrovascular disease management. Vascular disorder prescribing remains fragmented across academic research protocols.
- Neurological Conditions:Exploratory use in traumatic brain injury and other neurocritical care contexts without formal indication. Neurological condition demand tracks clinical trial enrollment and compassionate use program scope.
Subarachnoid hemorrhage therapy absorbs the bulk of clinical utilization; cerebral aneurysm prophylaxis is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis for nimodipine concentrates in Zhejiang Province manufacturing corridors, with finished dose formulation and neurocritical care consumption distributing across tertiary hospital networks in North America, Europe, and East Asia.
United States
Integrated delivery networks in Boston, Houston, and Baltimore anchor injectable nimodipine demand through specialized neurosurgical ICU protocols. FDA REMS compliance requirements for oral formulations create supplier certification barriers that protect validated manufacturers from price erosion. Massachusetts General Hospital and Johns Hopkins anchor clinical utilization intensity through standardized vasospasm prevention pathways.
Germany
Endovascular coiling expansion in Munich and Berlin neurointerventional centers is extending prophylactic nimodipine protocols to pre-intervention windows. EMA centralized marketing authorization procedures govern generic substitution dynamics across hospital pharmacy committees. Baden-Württemberg's medical device corridor is piloting nimodipine-eluting stent coatings under MDR harmonization pathways.
Japan
Aging demographics are elevating subarachnoid hemorrhage incidence among elderly populations in Tokyo and Osaka tertiary centers. METI funding for neuroprotective drug-device combinations is opening regulatory pathways for sustained-release formulation innovation. Kanto region hospitals are standardizing on specific bioequivalence-certified suppliers to simplify pharmacovigilance documentation.
China
Zhejiang Huahai Pharmaceutical's API cost structure anchors global supply security for finished dose formulators. NMPA marketing authorization requirements are elevating dossier breadth expectations for domestic manufacturers. Yangtze River Delta pharmaceutical clusters are consolidating regulatory affairs capabilities to serve multiple national markets simultaneously.
India
Sun Pharmaceutical and Aurobindo Pharma leverage generic manufacturing scale to serve price-sensitive hospital procurement in South Asia and export markets. CDSCO bioequivalence standards are tightening for calcium channel blocker substitutions. Hyderabad and Ahmedabad API-to-finished-dose corridors are deepening backward integration into dihydropyridine chemistry.
Nimodipine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pediatric oral solution and drug-device combination spaces where regulatory barriers remain navigable. Hospital procurement consolidation around integrated delivery networks is compressing vendor rosters to three or fewer approved suppliers per network. Three archetypes dominate: parenteral manufacturing specialists with ICU formulary presence, API-integrated generics with multi-market dossier breadth, and orphan-drug positioned players with concentrated hospital channel relationships. Competitive moves concentrate on REMS compliance infrastructure investment and direct-to-hospital distribution partnerships bypassing wholesale intermediaries.
Among US-based pharmaceutical specialists, Arbor Pharmaceuticals LLC exemplifies orphan-drug positioning with concentrated neurocritical care channel access. German parenteral manufacturing scale is represented by Fresenius Kabi AG, which anchors supply security for injectable formulations through ICU formulary presence. Chinese API and finished dose integration is occupied by Zhejiang Huahai Pharmaceutical Co. Ltd., leveraging regulatory dossier breadth across multiple national markets.
| Leading Market Players |
|---|
| Arbor Pharmaceuticals LLC |
| Sandoz International GmbH |
| Sun Pharmaceutical Industries Ltd. |
| Aurobindo Pharma |
| Fresenius Kabi AG |
| Bayer Vital GmbH |
| Teva Pharmaceutical Industries Ltd. |
| Zhejiang Huahai Pharmaceutical Co. Ltd. |
| Bionpharma Inc. |
| Others |
Supply Flow & Price Mechanics
Nanoparticle formulation engineering is compressing manufacturing cost curves for enhanced bioavailability nimodipine while simultaneously concentrating production capacity among parenteral specialists with sterile processing infrastructure. This dual effect reshapes competitive economics across injectable and oral dosage tiers.
Pricing Analysis
REMS compliance service bundling separates certified manufacturers from uncertified competitors in oral nimodipine tiers. Three-tier pricing structure across REMS-certified premium, standard bioequivalence, and economy unbundled levels reflects documentation burden and liability coverage. Pricing pressure stems from 340B program expansion forcing direct-to-hospital contract renegotiation. Integrated delivery networks exhibit lowest price sensitivity due to formulary standardization imperatives; independent community hospitals face highest sensitivity to generic substitution.
Supply Chain Analysis
Specialized pharmaceutical workforce availability in Zhejiang Province, Hyderabad, and the Rhine-Ruhr corridor anchors API synthesis and finished dose formulation. Active pharmaceutical ingredient production draws from dihydropyridine chemistry clusters in China and India, with parenteral manufacturing resting on sterile fill-finish capabilities in Germany and the United States. Single-source vulnerability concentrates in Zhejiang Huahai's API dominance for calcium channel blocker intermediates. Distribution runs through hospital pharmacy direct purchasing with wholesale bypass accelerating for injectable cold chain products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nimodipine market functions as a cost-of-compliance story where FDA REMS certification creates a barrier-to-entry moat protecting validated manufacturers from price erosion and generic substitution.
For Market Incumbents: To counter API supply concentration risk, secure backward integration into dihydropyridine chemistry through captive manufacturing or long-term offtake agreements with Zhejiang and Hyderabad producers. Reinforce hospital channel control by embedding REMS compliance infrastructure directly into integrated delivery network pharmacy systems, creating switching costs for competitor displacement. For New Entrants and Emerging Players: Specialty pharmacy partnerships offer the most penetrable pathway around established wholesale relationships and incumbent formulary locks. Target pediatric oral solution and taste-masked liquid formulations where REMS documentation requirements remain lighter and dysphagia patient populations are underserved. Pursue 340B program eligibility and direct-to-hospital distribution agreements to bypass traditional intermediary markups. For Investors and Strategic Acquirers: Exit pathways concentrate in parenteral manufacturing specialists with ICU formulary presence and dual regulatory capabilities for drug-device combinations. Long-term viability favors platforms with demonstrated REMS audit resilience and neurocritical care channel density. Watch EMA Medical Device Regulation harmonization progress as the signal for nimodipine-eluting stent coating commercialization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Investment | FDA certification protects margin structures and excludes uncertified competitors from hospital formularies. |
| Pediatric Oral Solution Development | Taste-masked liquid formulations capture dysphagia and pediatric populations underserved by tablet-centric supply. |
| Direct-to-Hospital Distribution Partnership | 340B program compliance and specialty pharmacy relationships bypass wholesale intermediaries and improve cold chain integrity. |
| Drug-Device Combination Regulatory Pathway | EMA MDR harmonization enables nimodipine-eluting stent coatings for cerebral aneurysm repair expansion. |
| API Supply Security Arrangement | Long-term offtake agreements with Zhejiang and Hyderabad producers mitigate geopolitical disruption exposure. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nimodipine market assessment. Primary interviews with neurocritical care pharmacists, hospital procurement directors, regulatory affairs leads, and formulary committee members combined with FDA Orange Book entries, EMA centralized marketing authorization databases, and USP dissolution specifications. Bottom-up patient-volume modeling and top-down pharmaceutical spending triangulation validated segment-level estimates.
Granularity-level modeling disaggregated demand across formulation type, therapy area, end-user facility tier, and distribution channel structure. Injectable, tablet, oral solution, and capsule segments were projected with separate bioequivalence certification and REMS compliance assumptions. CAGRs were derived from protocol adherence rate trajectories, endovascular coiling procedure expansion, and aging demographic incidence modeling. Neurocritical care service line standardization and generic substitution policy evolution served as key forecast inputs.
Several conditions sit outside the modeled scope, including compassionate use program scale, off-label vascular disorder prescribing, and intra-arterial verapamil protocol substitution rates. Forecasts reflect assumptions around REMS audit continuity, API inspection clearance timelines, and hospital pharmacy consolidation pace. Material deviation in FDA enforcement posture, EMA pharmacovigilance burden adjustment, or major API manufacturing facility regulatory action warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Betahistine Mesilate Market
Pharmaceuticals
North America Anticoccidial Drugs Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
PARP Inhibitors Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Antiplatelet Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Global RFID in Pharmaceuticals Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Blood Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Vaginal Ring Market