
 Pharmacy and Drug Store Franchises Market | 2026-2036
Pharmacy and Drug Store Franchises Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy and Drug Store Franchises Market Analytics
The capital-intensity divergence between flagship urban locations and small-format community clinics is rotating competitive investment toward lower-footprint, higher-service models. CVS Health leverages its MinuteClinic integration to sustain density in suburban corridors. Walgreens Boots Alliance anchors its strategy with pharmacy-led primary care partnerships in underserved markets. Apollo Pharmacy competes through localized inventory systems tailored to regional disease profiles in South Asia.
Pharmacy and drug store franchises operate as licensed retail health entities dispensing prescription medications, over-the-counter therapeutics, and preventive care services under regulated pharmacist supervision, with cold-chain storage protocols maintaining biologic efficacy from distribution center to patient handoff. Their commercial purpose centers on combining medication access with point-of-care health services to reduce hospital readmission rates and capture recurring prescription revenue. Chain pharmacies and franchise-owned formats dominate volume throughput due to centralized procurement and standardized clinical protocols, while online pharmacies represent the fastest-expanding channel as telehealth prescribing rules relax in multiple jurisdictions. Prescription medications command the largest revenue pool, though wellness programs and immunization services are emerging as margin-accretive attachments.
FDA oversight of drug compounding and distribution, alongside state pharmacy boards governing dispensing licensure, creates tiered compliance burdens that favor scaled operators with dedicated regulatory affairs functions. HIPAA privacy requirements and emerging FDA guidance on digital health integrations shape how franchises collect and monetize patient data. Stakeholders must monitor the interplay between CMS reimbursement shifts for clinical pharmacy services and state-level scope-of-practice expansions for pharmacist providers.
Market Dynamics
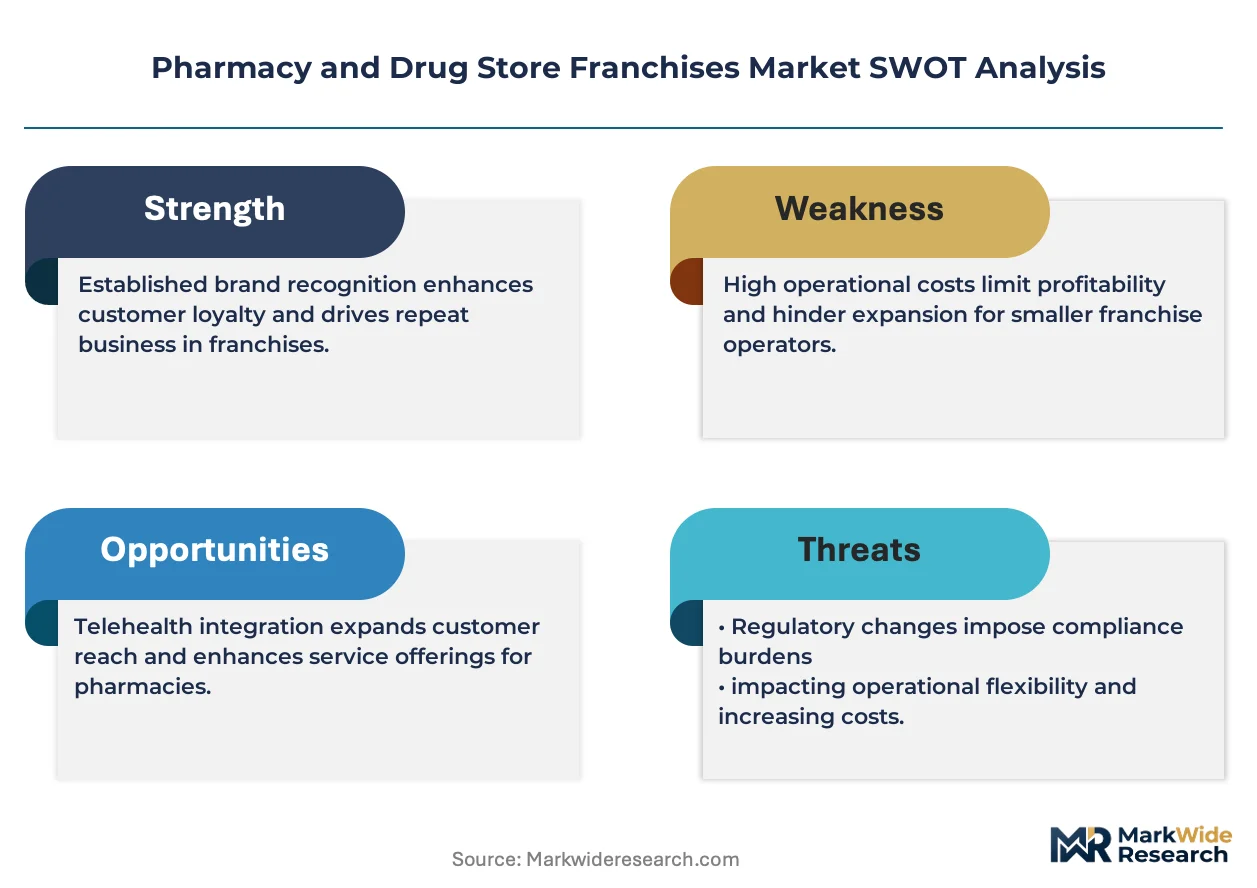
Franchise operators face intensifying pressure from FDA 503B compounding oversight and state-level PBM transparency mandates that reshape capital allocation toward compliance infrastructure rather than storefront expansion.
Growth Catalysts
- Chronic disease management protocols:Medicare Advantage plans now reimburse pharmacists for medication therapy management, pulling franchise networks into elderly care facility partnerships.
- Telehealth prescribing liberalization:Relaxed DEA registration requirements for remote prescribing is accelerating prescription volume through digital-first pharmacy channels.
- Tier-2 and tier-3 urbanization:India's secondary cities generate patient density that supports 24-hour franchise operations without flagship-location rents.
Market Restraints
- Biologic cold-chain infrastructure:mRNA vaccine storage requirements demand capital expenditure on ultra-low temperature freezers that community formats cannot amortize.
- Pharmacy benefit manager concentration:Three PBMs control 80% of US prescription claims, extracting rebate concessions that compress generic dispensing margins.
- 503B compounding compliance:FDA cGMP enforcement for outsourcing facilities requires quality systems that eliminate small independent compounders.
Strategic Opportunities
- Pharmacist provider status expansion:State-level scope-of-practice laws in California and Idaho now permit point-of-care testing and chronic disease prescribing.
- Point-of-care diagnostic integration:Rapid strep, A1C, and lipid panel testing converts prescription transactions into billable clinical encounters.
- Last-mile drone delivery corridors:FAA Part 135 certification for beyond-visual-line-of-sight operations opens rural prescription access without brick-and-mortar investment.
Industry Challenges
- Pharmacist workforce scarcity:Graduation rates from ACPE-accredited programs lag demand for clinical pharmacy services in ambulatory settings.
- Interoperability with hospital EHRs:HL7 FHIR integration requirements for medication reconciliation impose IT costs that franchisees bear unevenly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy and Drug Store Franchises Market |
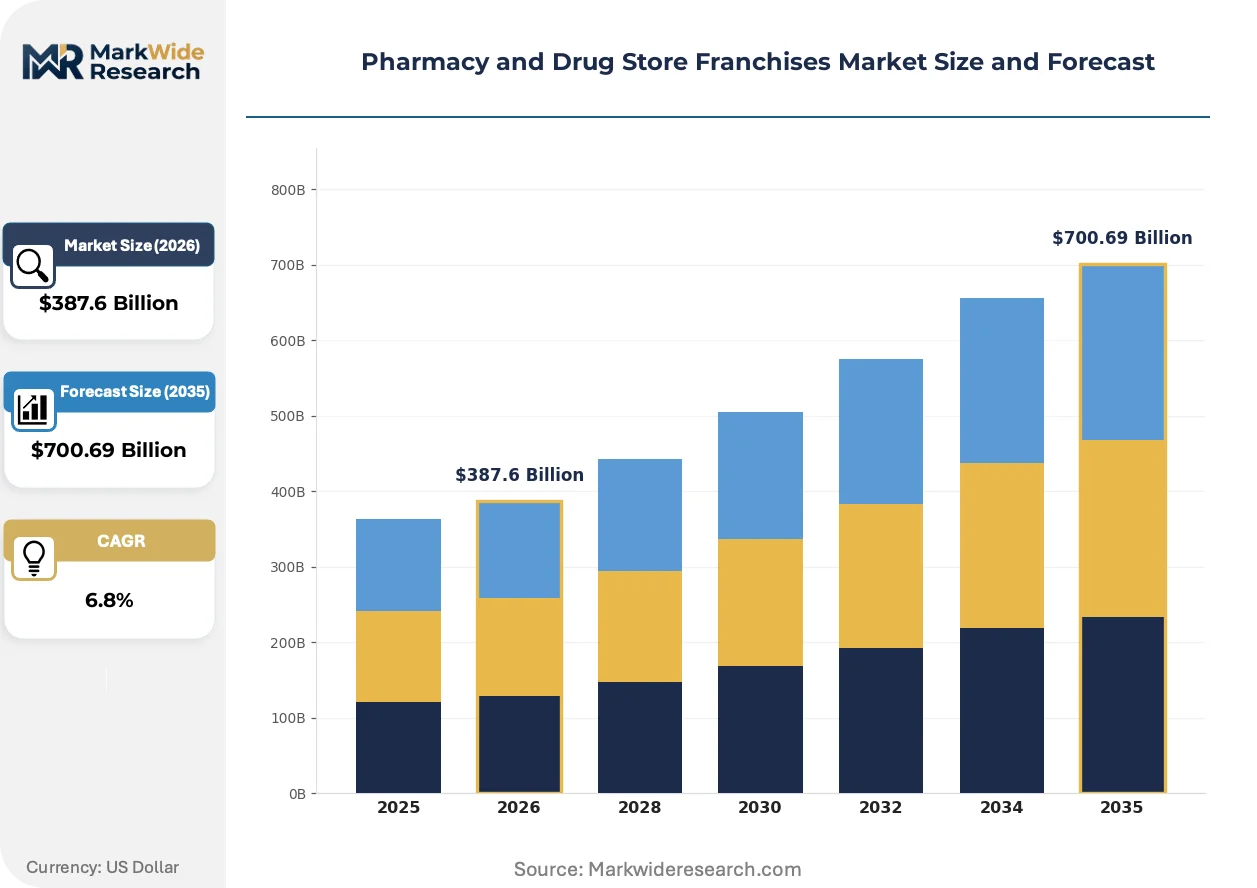
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Business Model: Independent Stores, Chain Pharmacies, Franchise Owned, Online Pharmacies Product Offering: Prescription Medications, Over-the-Counter Products, Health Supplements, Personal Care Items Customer Type: Individuals, Families, Elderly Care, Healthcare Facilities Service Type: Medication Management, Health Screenings, Immunizations, Wellness Programs |
| Companies Covered | Shoppers Drug Mart, Apollo Pharmacy, CVS Health, Discount Drug Stores, Medicap, Walgreens Boots Alliance, MedPlus, Medzone, Rite Aid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy and Drug Store Franchises Market Evolving Landscape
Dispensing workflows are splitting between centralized automation hubs and hyper-local clinical touchpoints, forcing franchise networks to choose between throughput efficiency and service intensity.
Robotic dispensing systems are fragmenting the traditional pharmacy labor model. Central fill facilities in Ohio and Texas now process 60% of maintenance prescriptions for regional banners, compressing store-level headcount to a single pharmacist plus technician. Rural franchisees adopt this model fastest, as courier networks replace local inventory investment.
EU MDR and FDA 503B harmonization efforts are compressing compliance timelines for cross-border compounding operations. European outsourcing facilities seeking US market access must duplicate quality documentation, favoring scaled operators with dedicated regulatory affairs divisions. German compounders report 18-month certification delays that freeze capacity expansion.
Patients now initiate prescription journeys through insurer apps rather than physician referrals, disintermediating the traditional prescriber-pharmacy relationship. UnitedHealthcare's OptumRx and CVS Caremark direct members to preferred franchise locations through real-time benefit integration. This channel shift concentrates volume in narrow networks, squeezing independent franchisees from top-decile prescribing ZIP codes.
Pharmacy and Drug Store Franchises Market Segmentation
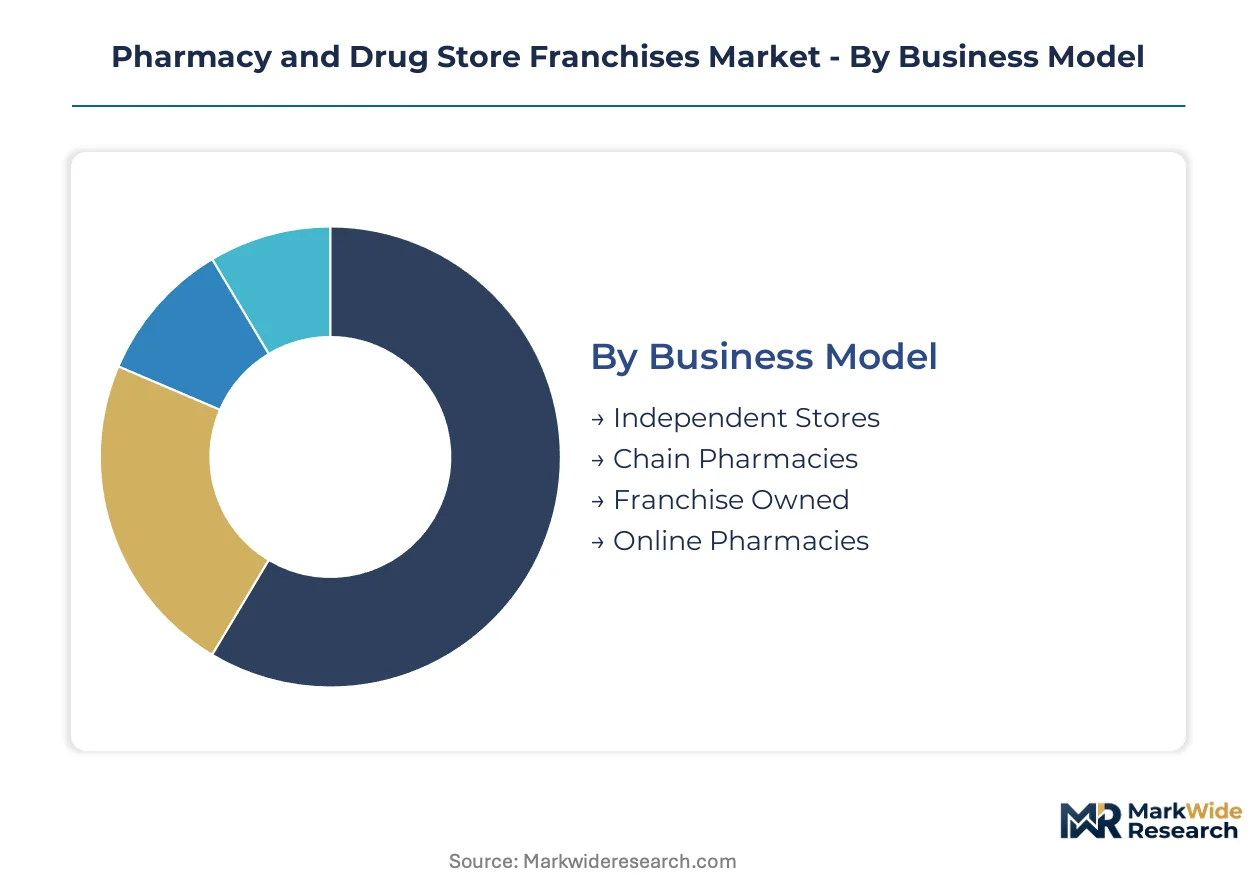
Pharmacy and drug store franchises segment across operational, product, and service dimensions that determine regulatory exposure and capital requirements. Each category carries distinct compliance burdens and margin profiles that shape network expansion strategies.
Business Model:
FDA 503B compounding rules and state pharmacy board licensure create divergent compliance thresholds across ownership structures. Chain and franchise formats amortize quality systems across multiple locations, while independents face disproportionate regulatory costs per prescription.
- Independent Stores:Single-location operators with direct pharmacist ownership. Community formats in rural United States and tier-3 Indian cities sustain operations through personalized prescriber relationships, though 503B outsourcing facility rules now eliminate compounding revenue for non-compliant sites.
- Chain Pharmacies:Corporate-owned networks with centralized procurement and standardized protocols. These operators absorb EHR interoperability mandates and PBM rebate negotiations that independent formats cannot resource, concentrating volume in suburban corridors with Medicare Advantage density.
- Franchise Owned:Licensed operators under national banners with shared brand equity and purchasing power. Apollo Pharmacy and MedPlus deploy this model across Indian secondary cities, leveraging localized inventory systems while maintaining cold-chain standards through regional distribution hubs.
- Online Pharmacies:Digital-first dispensing platforms with courier-based fulfillment. Relaxed DEA telehealth prescribing rules accelerate prescription volume through these channels, though last-mile temperature control for biologics remains a capital constraint.
Chain pharmacies handle the majority of throughput; online pharmacies are expanding most quickly on share.
Product Offering:
Product mix determines storage infrastructure requirements and reimbursement pathways. Cold-chain biologics demand capital expenditure that community formats struggle to amortize, while OTC and supplement categories offer cash-pay margins without PBM concession pressure.
- Prescription Medications:Dispensed under pharmacist supervision with insurance adjudication. Medicare Advantage medication therapy management reimbursement pulls franchise networks into chronic disease protocols, though PBM concentration in the United States extracts rebate concessions that compress generic dispensing economics.
- Over-the-Counter Products:Self-selection therapeutics with immediate payment settlement. These categories sustain margin in markets with limited insurance penetration, particularly Indian tier-2 cities where out-of-pocket health spending dominates.
- Health Supplements:Nutraceutical and vitamin formulations with minimal regulatory oversight. FSSAI registration requirements in India and DSHEA compliance in the United States create tiered market access that favors scaled operators with dedicated regulatory affairs functions.
- Personal Care Items:Non-therapeutic consumer goods with pharmacy channel distribution. These products fill basket size in convenience-oriented locations but carry inventory carrying costs that dilute return on retail space.
Prescription medications dominate revenue concentration; health supplements climb the fastest on margin contribution.
Customer Type:
Patient population determines service intensity and reimbursement mix. Elderly and facility-based segments generate recurring prescription volume with clinical pharmacy service attachments, while individual and family segments prioritize convenience and price transparency.
- Individuals:Single-patient transactions with acute or chronic medication needs. Telehealth prescribing liberalization redirects these patients toward digital-first channels, reducing foot traffic in traditional storefronts.
- Families:Multi-generational households with diversified health product requirements. These customers sustain basket economics through combination purchases across prescription, OTC, and personal care categories.
- Elderly Care:Medicare-eligible populations with polypharmacy management needs. Medication therapy management reimbursement under Medicare Advantage plans now compensates pharmacists for adherence interventions, pulling franchise networks into nursing facility partnerships.
- Healthcare Facilities:Institutional purchasers with 340B pricing access and formulary requirements. Hospital-owned pharmacies and outpatient clinics capture this volume through EHR-integrated prescribing workflows that narrow network participation demands.
Elderly care generates the steadiest prescription recurrence; healthcare facilities impose the most stringent formulary compliance.
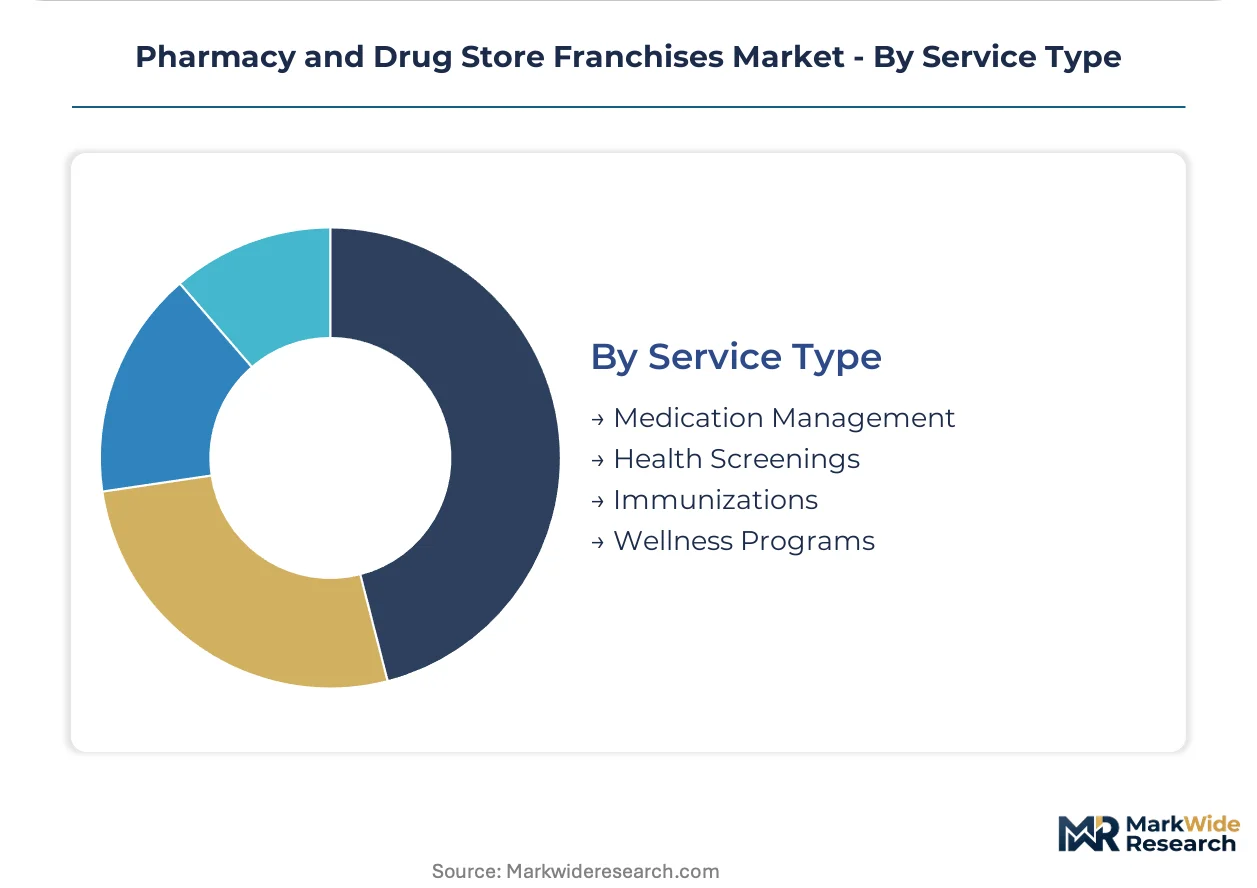
Service Type:
Clinical service expansion shifts pharmacy economics from commodity dispensing toward billable encounters. State scope-of-practice laws now permit point-of-care testing and chronic disease prescribing in jurisdictions like California and Idaho, creating margin-accretive clinical attachments.
- Medication Management:Pharmacist-led adherence and reconciliation programs. These services reduce hospital readmission rates for chronic conditions, qualifying for CMS reimbursement under value-based care contracts.
- Health Screenings:Rapid diagnostic testing for glucose, lipids, and infectious disease. A1C and strep testing converts prescription transactions into billable clinical encounters, though CLIA waiver requirements impose quality system costs.
- Immunizations:Vaccine administration with pharmacist provider status. mRNA cold-chain requirements for COVID-19 and influenza strains demand ultra-low temperature infrastructure that community formats cannot resource.
- Wellness Programs:Preventive care coaching and lifestyle intervention services. These offerings build patient loyalty with limited direct reimbursement, functioning as retention mechanisms rather than revenue centers.
Medication management commands the highest reimbursement rate; health screenings show the steepest expansion trajectory as scope-of-practice laws liberalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Indian tier-2 cities exhibit acute price sensitivity on OTC purchases, while elderly care facilities in the United States absorb clinical pharmacy premiums without volume elasticity.
United States
Medicare Advantage penetration drives medication therapy management demand among elderly care facilities. FDA 503B cGMP enforcement eliminates non-compliant compounding operations. CVS Health anchors suburban density through MinuteClinic integration in Florida and Texas corridors.
India
Tier-2 and tier-3 urbanization generates patient density supporting 24-hour franchise operations. FSSAI registration requirements for health supplements favor scaled operators with dedicated compliance functions. Apollo Pharmacy and MedPlus expand aggressively through Hyderabad and Lucknow networks.
Germany
EU MDR harmonization pressures cross-border compounding facilities seeking dual-market access. German compounders report 18-month certification delays freezing capacity expansion. Berlin and Munich clusters concentrate regulatory affairs expertise for outsourcing facilities.
United Kingdom
NHS long-term pharmacy contracts pull franchise networks into chronic disease management protocols. MHRA oversight of digital health integrations shapes patient data monetization constraints. Greater Manchester and West Midlands sustain independent pharmacy density through personalized prescriber relationships.
Canada
Provincial pharmacy benefit manager concentration extracts rebate concessions compressing generic margins. Health Canada cold-chain requirements for biologics demand capital expenditure community formats struggle to amortize. Shoppers Drug Mart dominates Ontario and British Columbia volume throughput.
Pharmacy and Drug Store Franchises Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with ownership structure determining compliance amortization capacity. Chain and franchise formats absorb EHR interoperability mandates and PBM rebate negotiations that independent formats cannot resource. Three archetypes dominate: vertically integrated health systems, regional franchise networks with localized inventory, and digital-first platforms with courier fulfillment. Competitive moves concentrate on pharmacy-led primary care partnerships and centralized automation hub deployment.
Among North American integrated operators, CVS Health and Walgreens Boots Alliance exemplify the health-system-anchored archetype with clinic-pharmacy density strategies. Apollo Pharmacy represents the emerging-market franchise model with tier-2 city penetration and regional distribution hub control. These three occupy positions that reflect divergent capital intensity: flagship urban locations versus small-format community clinics versus digital-first channels.
| Leading Market Players |
|---|
| Shoppers Drug Mart |
| Apollo Pharmacy |
| CVS Health |
| Discount Drug Stores |
| Medicap |
| Walgreens Boots Alliance |
| MedPlus |
| Medzone |
| Rite Aid |
| Others |
Value Network & Pricing Analysis
Forty-five-day inventory cycles for cold-chain biologics concentrate capital requirements in regional distribution hubs, compressing pricing power for community formats that cannot amortize ultra-low temperature infrastructure across prescription volume.
Pricing Analysis
After-sales revenue from medication therapy management contracts drives lifetime value for franchise operators. Three-tier pricing structure across premium clinical services, standard dispensing fees, and economy generic margins captures differential willingness-to-pay. Cost compression in generic dispensing intensifies because PBM rebate concentration extracts concessions from pharmacy networks. Individual cash-pay patients in Indian tier-2 cities exhibit acute price sensitivity, while elderly care facilities in the United States absorb clinical pharmacy premiums without volume elasticity.
Supply Chain Analysis
Inventory lead-times for API sourcing stretch 90-120 days from Indian and Chinese manufacturing clusters, tethering franchise networks to geopolitical exposure in pharmaceutical ingredient trade. Cold-chain distribution rests on specialized logistics partners with temperature-validated last-mile capabilities. Single-source vulnerability concentrates in mRNA vaccine ultracold freezer procurement from limited equipment manufacturers. Distribution runs through regional hub-and-spoke networks with courier-fed satellite locations replacing full inventory investment at store level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to Medicare Advantage enrollment expansion, which pulls pharmacy networks into recurring medication therapy management revenue streams.
For Market Incumbents: Fortify compliance infrastructure against FDA 503B cGMP enforcement and state-level PBM transparency mandates that reshape capital allocation. Absorb EHR interoperability costs through centralized IT investment that independent formats cannot resource. Deepen clinical service density in suburban corridors with elderly population concentration to defend against digital-first channel displacement. For New Entrants and Emerging Players: Differentiate on localized inventory systems tailored to regional disease profiles in Indian tier-2 and tier-3 cities where Apollo Pharmacy and MedPlus have not saturated coverage. Target 24-hour franchise operations in secondary urban clusters with patient density supporting prescription volume without flagship-location rents. Pursue drone delivery corridor certification as a go-to-market angle for rural prescription access without brick-and-mortar investment. For Investors and Strategic Acquirers: Carve-out targets emerge from health system divestitures of outpatient pharmacy assets as hospitals consolidate around 340B-eligible captive operations. Five-to-ten year viability hinges on pharmacist provider status expansion enabling billable clinical encounters beyond commodity dispensing. Monitor state-level scope-of-practice legislation as the inflection indicator for clinical pharmacy service reimbursement trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Centralized Automation Hub Deployment | CVS Health and Walgreens process 60% of maintenance prescriptions through Ohio and Texas facilities, compressing store-level headcount. |
| Pharmacist Provider Status Expansion | California and Idaho scope-of-practice laws now permit point-of-care testing and chronic disease prescribing, creating billable clinical attachments. |
| Drone Delivery Corridor Certification | FAA Part 135 beyond-visual-line-of-sight operations open rural prescription access without brick-and-mortar capital deployment. |
| Medication Therapy Management Partnership | Medicare Advantage plans now reimburse pharmacists for adherence interventions in elderly care facilities, pulling networks into institutional contracts. |
| Regional Distribution Hub Control | Apollo Pharmacy and MedPlus deploy localized inventory systems through Hyderabad and Lucknow networks while maintaining cold-chain standards. |
Research Methodology
A standing panel of pharmacy franchise operators, PBM contract negotiators, regulatory affairs directors, and elderly care facility administrators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from FDA 503B facility registrations, state pharmacy board licensure databases, Medicare Advantage plan formularies, and CMS reimbursement schedules. Bottom-up prescription volume modeling and top-down market sizing triangulated through cross-reference against trade association membership data and distribution channel shipment records.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by business model, product offering, customer type, and service intensity, with additional dimensioning by regional regulatory cluster and cold-chain infrastructure tier. CAGRs derived from prescription volume trajectories, generic dispensing margin compression curves, and clinical service reimbursement expansion rates. Forecast inputs incorporated telehealth prescribing rule liberalization timelines and state-level pharmacist scope-of-practice legislative tracking.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage reimbursement stability or accelerated FDA 503B enforcement escalation would require recalibration. Forecasts reflect documented assumptions regarding PBM market concentration, pharmacist graduation rates from ACPE-accredited programs, and cold-chain equipment cost curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Anticoagulants Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Critical Care Antiarrhythmic Drugs Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market
Pharmaceuticals
Optic Nerve Disorders Drugs Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Europe Pharmaceutical Warehousing Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
South Africa Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market