
 Global General Anesthesia Drugs Market | 2026-2036
Global General Anesthesia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global General Anesthesia Drugs Market Foresight
The gap between intravenous and inhalational delivery platforms is narrowing as pharmaceutical manufacturers pursue formulation innovations that bridge pharmacokinetic precision with operational simplicity. Fresenius SE & Co. KGaA anchors its position through captive supply chains for propofol emulsions across European hospital networks. Baxter International Inc. leverages its anesthesia workstation ecosystem to bundle gas delivery with proprietary sevoflurane supplies. Pfizer Inc. competes in neuromuscular blockade through differentiated rocuronium portfolios that sustain premium positioning in academic medical centers.
General anesthesia drugs comprise pharmacological agents that induce reversible loss of consciousness, analgesia, muscle relaxation, and autonomic reflex suppression, typically formulated as propofol emulsions, volatile halogenated ethers, or neuromuscular blocking peptides administered via calibrated vaporizers or precision infusion pumps. Intravenous anesthetics dominate current revenue pools due to propofol's ubiquity in induction protocols, while inhalational anesthetics retain structural importance in maintenance phases of prolonged thoracic and cardiac surgeries. Neuromuscular blockers represent the fastest-growing formulation category as robotic surgery adoption necessitates deeper paralysis control with sugammadex-enabled reversal protocols.
The FDA and EMA enforce Good Manufacturing Practice standards for sterile injectable emulsions, while the EU F-Gas Regulation constrains desflurane utilization through environmental discharge controls that reshape hospital procurement criteria. ISO 13485 certification requirements for anesthesia workstation integration further gate market access for device-drug combination offerings. Stakeholders must monitor how pharmacovigilance databases track malignant hyperthermia incidents and how regulatory bodies respond with label restrictions or Risk Evaluation and Mitigation Strategies.
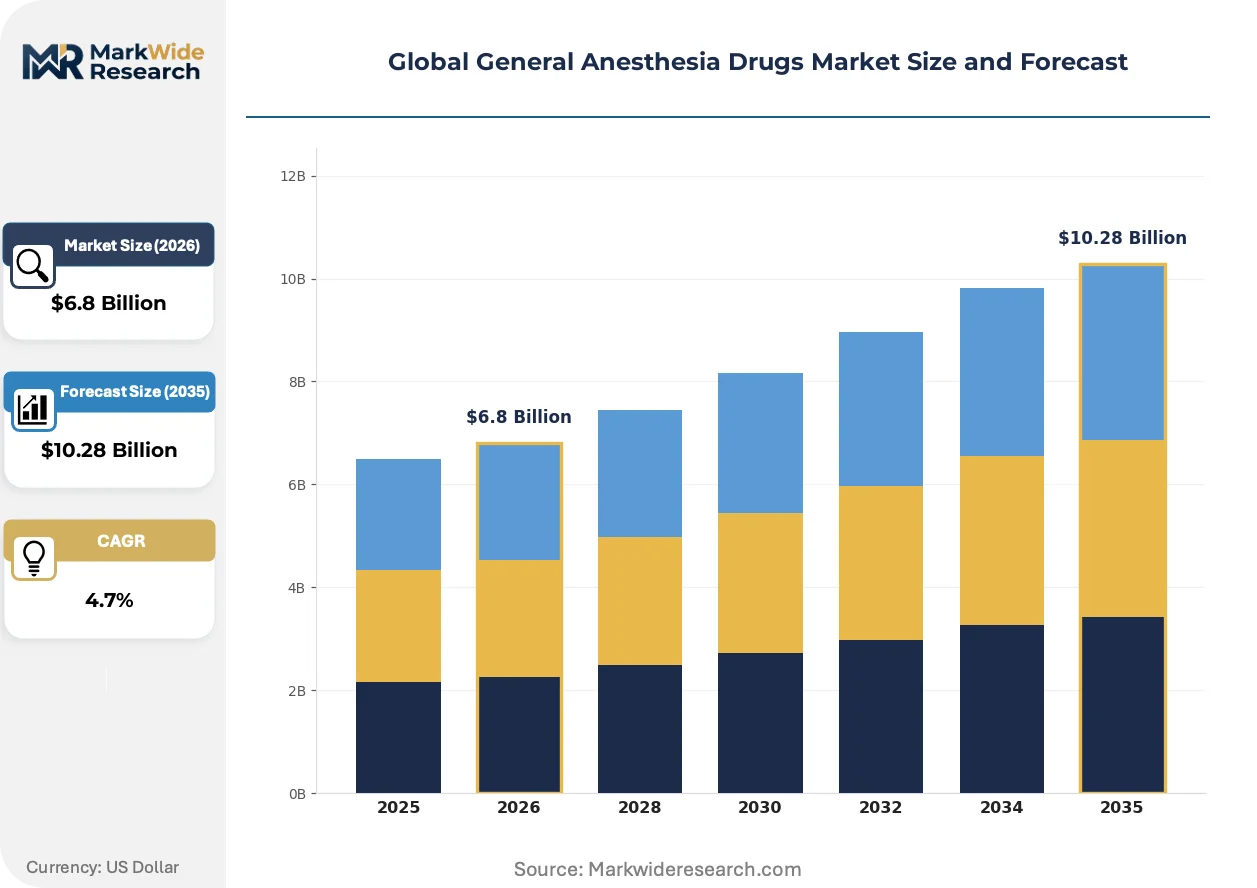
Market Dynamics
Pharmacovigilance tightening by the FDA and EMA is compressing approval timelines for neuromuscular blockers while hospital procurement consolidators demand real-world safety data before formulary inclusion.
Growth Catalysts
- Robotic Surgery Penetration:Da Vinci system installations in German and Chinese academic medical centers drive demand for sugammadex-reversible rocuronium protocols that enable rapid paralysis adjustment.
- F-Gas Regulation Compliance:The EU F-Gas Regulation forces hospital pharmacy committees to evaluate sevoflurane against desflurane based on global warming potential scores, favoring suppliers with closed-capture vaporizer systems.
- Propofol Emulsion Manufacturing:Captive production of intravenous anesthetics by European hospital networks secures supply continuity amid sterile injectable shortages.
Market Restraints
- Soybean Oil Input Volatility:Propofol emulsion formulations depend on refined soybean lecithin supplies concentrated in Argentine and Brazilian agricultural processing.
- Halogenated Ether Production Concentration:Sevoflurane and desflurane active pharmaceutical ingredient synthesis clusters in Chinese and Indian chemical manufacturing zones.
- Malignant Hyperthermia Liability:Volatile anesthetic labels carry boxed warnings that constrain marketing claims and expand institutional risk management costs.
Strategic Opportunities
- Indian Hospital Infrastructure Expansion:Ayushman Bharat health coverage expansion creates addressable surgical volume in tier-two and tier-three cities currently served by basic ether anesthesia.
- Closed-Circuit Anesthesia Workstations:Integration of gas scavenging with low-flow vaporizer technology converges environmental compliance with cost-per-MAC-hour reduction.
- Pharmacogenomic-Guided Dosing:CYP2B6 and CYP2C19 genotyping protocols enable personalized propofol infusion algorithms that reduce emergence delirium in pediatric populations.
Industry Challenges
- Certified Nurse Anesthetist Shortage:US healthcare systems face pipeline constraints in CRNA training programs that limit operating room throughput regardless of drug availability.
- ISO 13485 Device-Drug Integration:Anesthesia workstation manufacturers must synchronize vaporizer calibration software with proprietary canister RFID systems, extending validation timelines.
- Legacy Vaporizer Fleet Compatibility:Hospital capital budgets prioritize MRI suites over anesthesia machine replacement, fragmenting gas delivery standardization across surgical suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global General Anesthesia Drugs Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Anesthetics, Inhalational Anesthetics, Neuromuscular Blockers, Opioids, Sedatives Therapy Area: Surgical Procedures, Pain Management, Critical Care, Diagnostic Procedures, Obstetrics End User: Hospitals, Ambulatory Surgery Centers, Dental Clinics, Specialty Clinics, Academic Institutes Formulation: Liquid Injection, Powder, Gas, Emulsion, Premixed Solutions |
| Companies Covered | AbbVie Inc., Baxter International Inc., Fresenius SE & Co. KGaA, Aspen Pharmacare Holdings Ltd., B. Braun SE, Pfizer Inc., Hikma Pharmaceuticals PLC, Abbott Laboratories, AstraZeneca plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global General Anesthesia Drugs Market Shifts & Advancements
Closed-loop anesthesia delivery systems are converging with pharmacokinetic modeling software to automate propofol and remifentanil titration, compressing the role of manual infusion management in high-volume surgical settings.
AI-enabled depth-of-monitoring platforms are digitizing the interpretation of bispectral index signals to reduce anesthetic overdose incidents. Academic medical centers in the United States and Germany deploy these systems in cardiac surgery suites where hemodynamic instability complicates manual dosing. The technology is digitizing anesthesiologist workflow allocation, shifting human oversight toward exception handling rather than continuous parameter adjustment.
The EU F-Gas Regulation's 2024 phasedown schedule for hydrofluorocarbon medical uses is forcing hospital pharmacy committees to renegotiate sevoflurane supply contracts with environmental discharge clauses. Manufacturers must now certify vaporizer capture efficiency to maintain formulary position. German and French hospital procurement coalitions have begun bundling gas delivery hardware with anesthetic supply agreements to ensure closed-circuit compliance.
Hospital buying groups in the United States are consolidating anesthesia drug purchasing through 340B program participation and group purchasing organization tiered contracts. Independent ambulatory surgery centers face exclusion from these volume tiers, pushing them toward alternative distribution channels including specialty pharmaceutical wholesalers. This concentration is most visible in California and Texas metropolitan markets where health system consolidation has reduced viable supplier alternatives.
Global General Anesthesia Drugs Market Segmentation
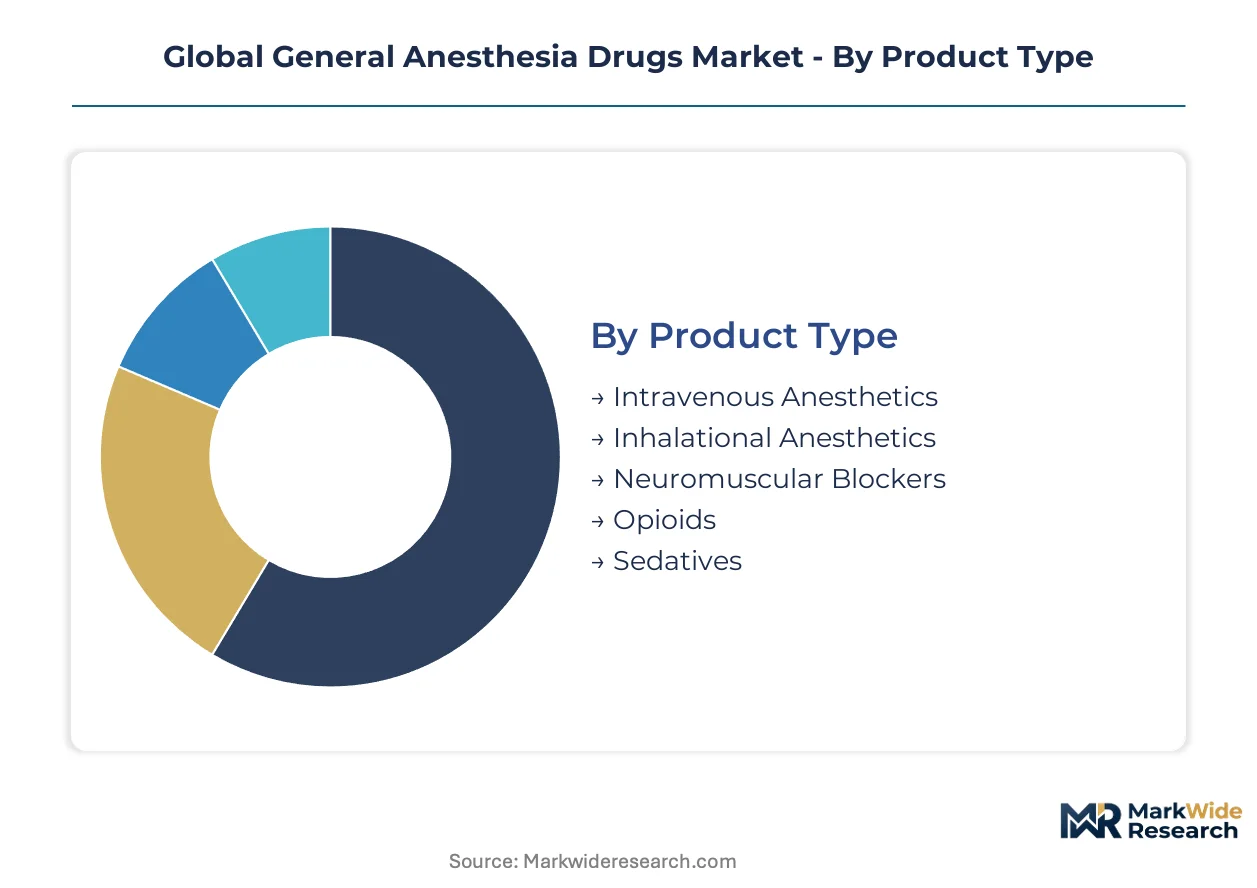
Anesthesia drug segmentation reveals how formulation chemistry, delivery mechanism, and care setting intersect to determine procurement patterns. Hospital pharmacy committees evaluate segments through distinct lenses: pharmacokinetic precision for intravenous protocols, environmental compliance for inhalational agents, and reversal capability for neuromuscular blockade.
Product Type:
Intravenous induction maintains dominance in high-volume surgical corridors, while inhalational platforms retain structural importance in cardiac and thoracic maintenance phases.
- Intravenous Anesthetics:Propofol emulsions and etomidate formulations enable rapid induction with predictable redistribution kinetics. Demand concentrates in United States academic medical centers where closed-loop infusion systems automate titration protocols.
- Inhalational Anesthetics:Sevoflurane and desflurane halogenated ethers deliver titratable maintenance anesthesia through calibrated vaporizers. German hospital procurement coalitions now bundle gas supply with closed-capture workstation contracts to satisfy EU F-Gas Regulation discharge limits.
- Neuromuscular Blockers:Rocuronium and vecuronium peptides enable precise paralysis control for robotic surgery platforms. Sugammadex reversal capability drives formulary preference in Chinese tertiary hospitals expanding Da Vinci system installations.
- Opioids:Remifentanil and fentanyl analogs provide intraoperative analgesia with context-sensitive half-lives.
- Sedatives:Midazolam and dexmedetomidine support procedural sedation outside operating room environments.
Established volume favors intravenous anesthetics; emerging adoption favors neuromuscular blockers as robotic surgery penetration accelerates.
Therapy Area:
Procedure complexity and reimbursement intensity determine segment prioritization across hospital service lines.
- Surgical Procedures:General anesthesia for open, laparoscopic, and robotic interventions generates the largest pharmaceutical consumption volumes. United States health systems account for disproportionate sevoflurane and propofol utilization amid high per-capita surgery rates.
- Pain Management:Chronic and acute pain protocols employ lower-dose opioid and sedative combinations outside surgical settings.
- Critical Care:ICU sedation for mechanically ventilated patients requires extended-duration propofol or dexmedetomidine infusions with daily interruption protocols.
- Diagnostic Procedures:Colonoscopy, endoscopy, and imaging-guided interventions drive midazolam-fentanyl demand in ambulatory settings.
- Obstetrics:Epidural anesthesia and cesarean section protocols utilize reduced-dose inhalational and intravenous agents with fetal monitoring constraints.
Surgical procedures anchor revenue concentration; diagnostic procedures expand most quickly as ambulatory volume shifts accelerate.
End User:
Capital intensity and regulatory oversight create sharp segmentation in purchasing authority and formulary autonomy.
- Hospitals:Integrated health systems with captive pharmacy operations and anesthesia departments command volume-tier pricing on propofol emulsions and neuromuscular blockers. China's tier-three hospital expansion under regional health reform sustains double-digit pharmaceutical procurement growth.
- Ambulatory Surgery Centers:Freestanding facilities with lower case-mix complexity favor rapid-turnover intravenous protocols over inhalational maintenance.
- Dental Clinics:Nitrous oxide and midazolam sedation support oral surgery and implant procedures with limited anesthesia specialist presence.
- Specialty Clinics:Ophthalmology, gastroenterology, and pain management centers deploy procedure-specific sedation without full operating room infrastructure.
- Academic Institutes:Teaching hospitals with residency programs maintain broader formularies to support training across anesthesia techniques and drug classes.
Hospital concentration dominates current procurement; ambulatory surgery centers gain share fastest as case migration accelerates.
Formulation:
Manufacturing complexity and supply chain resilience differentiate formulation economics.
- Liquid Injection:Aqueous solutions of propofol, etomidate, and neuromuscular blockers enable immediate intravenous administration without reconstitution. Fresenius SE & Co. KGaA's captive European production networks secure supply continuity for hospital system contracts.
- Emulsion:Lipid-based propofol formulations require sterile manufacturing with soybean lecithin inputs vulnerable to Argentine agricultural volatility.
- Powder:Lyophilized peptides and antibiotics require reconstitution but extend shelf stability for stockpiling scenarios.
- Gas:Volatile halogenated ethers demand specialized vaporizer infrastructure with scavenging systems for occupational safety compliance.
- Premixed Solutions:Pharmacy-prepared or manufacturer-compounded combinations reduce preparation error risk in high-volume surgical settings.
Liquid injection commands production scale; emulsion formulations face input cost pressure from agricultural commodity volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement coalitions in the United States, Germany, and China command disproportionate volume tiers, while regulatory divergence across FDA, EMA, and NMPA jurisdictions reshapes supplier qualification requirements. Surgical volume concentration in academic medical centers drives anesthetic drug consumption patterns.
United States
Academic medical centers in Boston and Houston deploy closed-loop propofol infusion systems at scale, compressing manual anesthesia management. FDA pharmacovigilance mandates for neuromuscular blockers extend approval timelines and expand post-market surveillance obligations. The 340B drug pricing program enables hospital buying groups to extract volume discounts from intravenous anesthetic suppliers.
Germany
Da Vinci robotic surgery installations in Munich and Berlin tertiary hospitals accelerate sugammadex-reversible rocuronium adoption. EMA enforcement of EU F-Gas Regulation discharge limits forces pharmacy committees to bundle sevoflurane supply with closed-capture vaporizer contracts. Bavarian hospital networks maintain captive propofol emulsion production lines to secure sterile injectable continuity.
China
Tier-three hospital expansion under regional health reform sustains double-digit pharmaceutical procurement growth in Shanghai and Guangzhou surgical corridors. NMPA tightening of Good Manufacturing Practice standards for sterile injectables elevates entry barriers for domestic emulsion manufacturers. Yangtze River Delta chemical clusters concentrate sevoflurane active pharmaceutical ingredient synthesis.
India
Ayushman Bharat health coverage expansion creates addressable surgical volume in tier-two cities currently served by basic ether anesthesia protocols. CDSCO import licensing requirements for halogenated ether vaporizers delay equipment upgrades in Maharashtra and Gujarat hospital systems. Mumbai-based specialty pharmaceutical distributors bridge supply gaps for independent ambulatory surgery centers excluded from corporate hospital procurement tiers.
Japan
Aging demographic compression drives per-capita surgery rates in Tokyo and Osaka metropolitan hospital networks. PMDA pharmacovigilance databases track malignant hyperthermia incidents with mandatory reporting thresholds that constrain volatile anesthetic marketing claims. Kansai region medical device manufacturers integrate anesthesia workstation calibration software with proprietary gas canister RFID systems.
Global General Anesthesia Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation categories where sterile manufacturing credentials and device integration capabilities determine contract viability. Market structure tilts toward consolidated supply relationships in United States and European hospital systems, while fragmented distributor networks persist in emerging surgical markets. Two archetypes dominate: integrated pharmaceutical-device conglomerates with captive vaporizer ecosystems, and pure-play anesthetic manufacturers competing on emulsion quality and reversal agent portfolios. Competitive moves concentrate on backward integration into active pharmaceutical ingredient synthesis and strategic partnerships with robotic surgery platform vendors.
Among diversified healthcare conglomerates, Fresenius SE & Co. KGaA anchors European supply continuity through hospital network integration, while Baxter International Inc. exemplifies device-drug bundling strategies. Pfizer Inc. occupies a position within neuromuscular blockade formulation tiers where reversal-enabled portfolios sustain academic medical center preference.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Baxter International Inc. |
| Fresenius SE & Co. KGaA |
| Aspen Pharmacare Holdings Ltd. |
| B. Braun SE |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| Abbott Laboratories |
| AstraZeneca plc |
| Others |
Supply & Pricing Matrix
Rotterdam-to-Mumbai container freight corridors transmit soybean lecithin cost volatility from Argentine processing plants into European propofol emulsion pricing tiers, compressing margins for sterile injectable manufacturers while amplifying price differentiation between captive hospital network supply and spot-market procurement.
Pricing Analysis
Cost-plus contracts with soybean commodity indexation dominate propofol emulsion procurement between Fresenius and Bavarian hospital networks. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified workstation-integrated supply from basic vaporizer-compatible offerings. Pricing pressure stems from EU F-Gas Regulation compliance costs embedding into sevoflurane supply agreements. Ambulatory surgery centers exhibit highest price sensitivity due to exclusion from 340B volume tiers, while academic medical centers absorb premium positioning for sugammadex-reversal protocols.
Supply Chain Analysis
Supplier-financing through 90-day extended payment terms anchors relationships between Yangtze River Delta sevoflurane API manufacturers and Indian specialty distributors. Active pharmaceutical ingredient synthesis concentrates in China, India, and Germany, drawing from halogenated ether precursors, refined soybean lecithin, and peptide fermentation feedstocks. Single-source vulnerability pervades Argentine agricultural inputs for lipid emulsion manufacturing. Distribution runs through hospital buying groups in the United States and European procurement coalitions, with fragmented distributor networks persisting in tier-two Indian cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-capture vaporizer maintenance contracts and sugammadex reversal agent subscriptions expand recurring revenue faster than anesthesia workstation hardware sales, repositioning drug-device bundling as a service-attach play.
For Market Incumbents: Entrench position through backward integration into sevoflurane API synthesis and captive propofol emulsion production lines that neutralize Argentine soybean input volatility. Secure ISO 13485 certification for next-generation workstation vaporizer calibration software to defend against emerging robotics-integrated anesthesia platforms. Channel control through hospital network exclusivity agreements remains the priority defensive lever. For New Entrants and Emerging Players: Build out pharmacogenomic-guided dosing algorithms for pediatric propofol protocols as the most penetrable white-space target, with Ayushman Bharat tier-two Indian cities offering lowest competitive density. Target independent ambulatory surgery centers excluded from consolidated procurement tiers through specialty pharmaceutical distributor partnerships. Direct-to-clinic reversal agent sampling programs provide the clearest go-to-market angle against incumbent formulary lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors device-drug integration specialists with closed-loop anesthesia delivery software capabilities over pure-play generic manufacturers. Long-term viability across the projection horizon hinges on regulatory compliance infrastructure rather than molecule exclusivity. Watch for NMPA GMP enforcement actions against domestic Chinese emulsion manufacturers as the inflection signal for supply consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Propofol Emulsion Manufacturing | Fresenius secures supply continuity for European hospital network contracts against Argentine input volatility. |
| Closed-Capture Vaporizer Bundling | Baxter satisfies EU F-Gas Regulation discharge limits while embedding sevoflurane supply into hardware contracts. |
| Sugammadex Reversal Portfolio Expansion | Pfizer sustains premium positioning in academic medical centers deploying Da Vinci robotic surgery platforms. |
| Pharmacogenomic Dosing Algorithm Development | Personalized CYP2B6 protocols reduce emergence delirium liability in pediatric populations across German tertiary hospitals. |
| Robotic Surgery Platform Partnership | Neuromuscular blocker suppliers align rocuronium formulations with sugammadex reversal for intraoperative paralysis control. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA pharmacovigilance databases, EMA submission filings, ClinicalTrials.gov records, and hospital procurement contract registries. Anesthesia department heads, hospital pharmacy directors, GPO contracts managers, and regulatory affairs specialists at sterile injectable manufacturers provided structured input. Bottom-up demand modeling from surgical procedure volumes triangulates against top-down pharmaceutical consumption data from national health accounts.
Forecast inputs span intravenous versus inhalational delivery preference curves, robotic surgery installation trajectories, and EU F-Gas Regulation compliance cost pass-through rates across the projection horizon. Segmentation dimensions include formulation chemistry, therapy area complexity, end-user capital intensity, and regional regulatory cluster stringency. CAGRs derive from procedure volume elasticity to health coverage expansion and anesthetic drug utilization per surgery type.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese API manufacturers into European formulation markets would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Anticoagulant Reversal Drugs Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Compound Glycyrrhizin Injection Market
Pharmaceuticals
Antispasmodics Drugs Market
Pharmaceuticals
Prostaglandin Analogs Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Global Contraceptive Drugs and Devices Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market