
 Antithrombotic Drugs Market | 2026-2036
Antithrombotic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antithrombotic Drugs Market Analysis
Heparin is decoupling from standard prophylaxis regimens as direct oral anticoagulants capture hospital formularies. Bayer AG leverages its established anticoagulant portfolio to sustain European hospital contracts. Pfizer Inc. competes through manufacturing scale in injectable anticoagulant supply chains. Bristol-Myers Squibb Company anchors North American prescribing patterns with its cardiovascular franchise.
Antithrombotic drugs comprise pharmaceutical agents that inhibit platelet aggregation, coagulation cascade activation, or fibrin clot dissolution, formulated for oral, injectable, intravenous, or subcutaneous delivery. These agents prevent thrombus formation in arterial and venous circulations, with direct oral anticoagulants displacing warfarin due to fixed dosing and reduced monitoring burdens. Anticoagulants and antiplatelets together occupy the majority of prescription volume, while thrombolytics retain concentrated use in acute ischemic stroke and myocardial infarction protocols. Oral delivery dominates chronic outpatient management, whereas intravenous and subcutaneous routes command perioperative and intensive care settings where rapid onset or precise titration is required.
The FDA, EMA, and national pharmacovigilance agencies shape market access through bleeding-risk labeling, reversal agent requirements, and post-market surveillance mandates that extend development timelines. The FDA's Division of Cardiovascular and Renal Products evaluates novel anticoagulants against warfarin efficacy benchmarks, while the EMA's Pharmacovigilance Risk Assessment Committee monitors real-world hemorrhage signals across member states. Stakeholders must track evolving regulatory positions on anticoagulant reversal strategies and perioperative bridging protocols as these determine competitive positioning in hospital procurement.
Market Dynamics
Direct oral anticoagulants are compressing hospital formularies through fixed-dosing protocols that eliminate INR monitoring infrastructure, forcing wholesale protocol rewrites across perioperative care pathways.
Growth Catalysts
- Medicare reimbursement expansion:The United States Centers for Medicare & Medicaid Services expanded coverage categories for atrial fibrillation stroke prevention, pulling volume into outpatient oral anticoagulant regimens.
- EMA switching guidance:The European Medicines Agency's evolving protocols for direct oral anticoagulant transitions are standardizing prescriber confidence across member state hospital systems.
- Aging surgical populations:North American hospital systems are expanding prophylactic anticoagulation coverage for patients over 75 undergoing orthopedic and cardiac procedures.
Market Restraints
- Heparin supply concentration:Injectable anticoagulant active pharmaceutical ingredient production clusters in Chinese and Indian contract manufacturers, creating single-source vulnerability for Western hospital systems.
- Reversal agent cost structure:Andexanet alfa and idarucizumab carry premium pricing that limits formulary adoption in budget-constrained European hospitals.
- Warfarin residual protocols:Mechanical heart valve patients remain excluded from direct oral anticoagulant labeling, preserving legacy monitoring infrastructure.
Strategic Opportunities
- Sub-Saharan Africa prophylaxis gaps:Venous thromboembolism prevention remains underpenetrated in South African and Nigerian hospital systems lacking standardized perioperative protocols.
- Biosimilar enoxaparin pathways:The FDA's abbreviated approval framework for low-molecular-weight heparin biosimilars opens margin compression strategies for injectable portfolio managers.
- Telemedicine anticoagulation clinics:Remote INR monitoring and direct oral anticoagulant adherence platforms are capturing chronic patient management from traditional anticoagulation clinics.
Industry Challenges
- Hemorrhage risk quantification:Real-world bleeding signal detection requires pharmacovigilance infrastructure that mid-scale hospital systems lack, complicating formulary defense.
- Perioperative bridging standardization:The absence of universal protocols for anticoagulant interruption and resumption creates liability exposure and outcome variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antithrombotic Drugs Market |
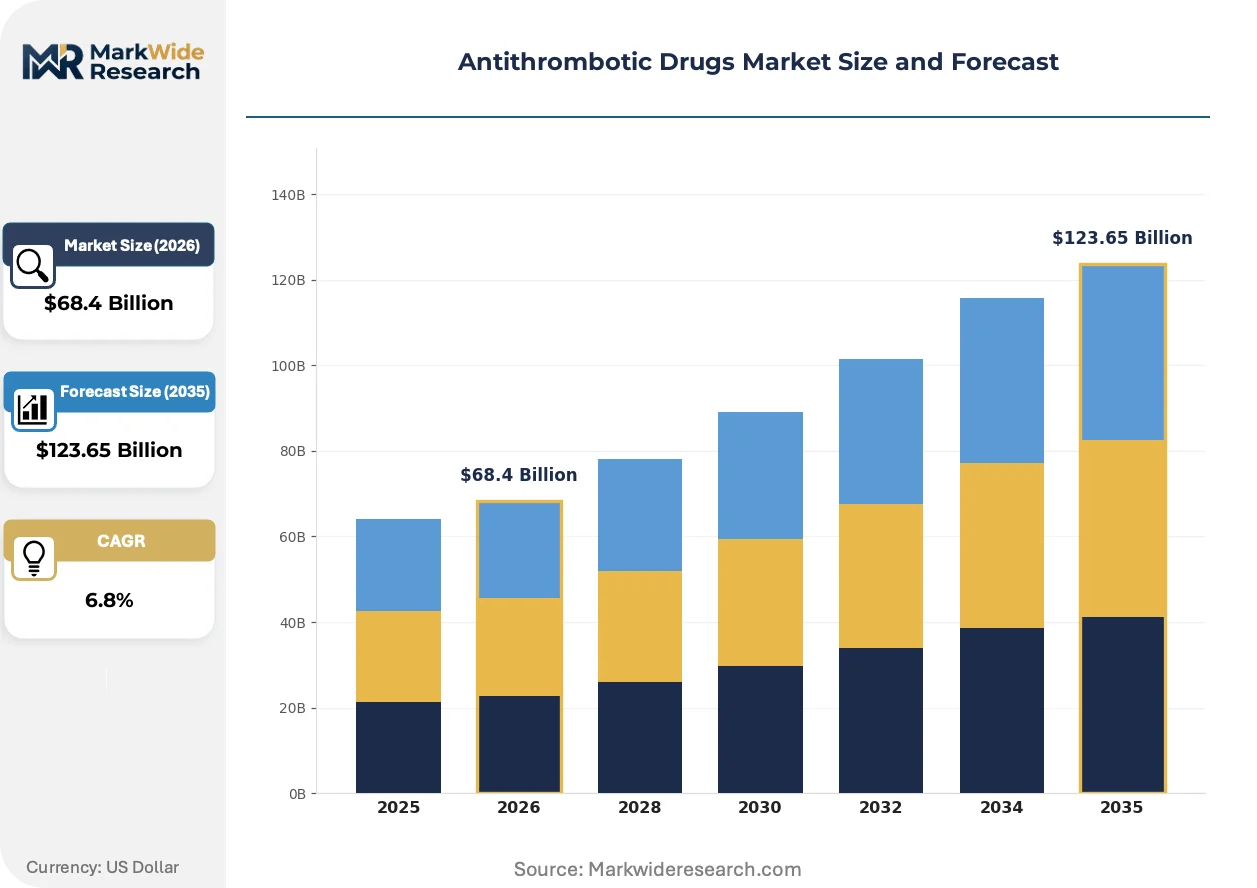
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Antiplatelets, Thrombolytics, Direct Oral Anticoagulants Delivery Mode: Oral, Injectable, Intravenous, Subcutaneous Application: Cardiovascular Disorders, Thrombosis Prevention, Surgery, Atrial Fibrillation End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers |
| Companies Covered | Bayer AG, Pfizer Inc., Bristol-Myers Squibb Company, Sanofi, Boehringer Ingelheim International GmbH, AstraZeneca plc, Johnson & Johnson Services Inc., Novartis AG, Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antithrombotic Drugs Market Emerging Trajectories
Antithrombotic development is pivoting from anticoagulant-antiplatelet silos toward integrated thrombosis management platforms that span acute intervention through chronic outpatient care.
Factor XI inhibition is decentralizing coagulation cascade targeting away from Factors IIa and Xa. Cardiovascular trial sponsors are advancing antisense and monoclonal antibody modalities that preserve hemostasis while blocking pathologic thrombosis. Hospital pharmacy committees are evaluating these candidates for surgical prophylaxis where bleeding risk currently limits heparin and direct oral anticoagulant use.
The FDA's accelerated approval pathway for novel oral anticoagulants is compressing Phase III evidence requirements against warfarin benchmarks. This regulatory architecture rewards sponsors with established cardiovascular safety databases, tilting competitive dynamics toward incumbents with legacy trial infrastructure. Prescriber education burdens are shifting onto hospital systems adapting to abbreviated labeling.
Integrated care networks are consolidating antithrombotic prescribing authority within cardiovascular service lines, displacing fragmented specialist-driven decision-making. Hospital administrators are capturing formulary control from individual clinicians through protocol-driven order sets and clinical decision support. The United States exhibits the most pronounced concentration, where Medicare Advantage contracting rewards standardized therapeutic substitution.
Antithrombotic Drugs Market Segmentation
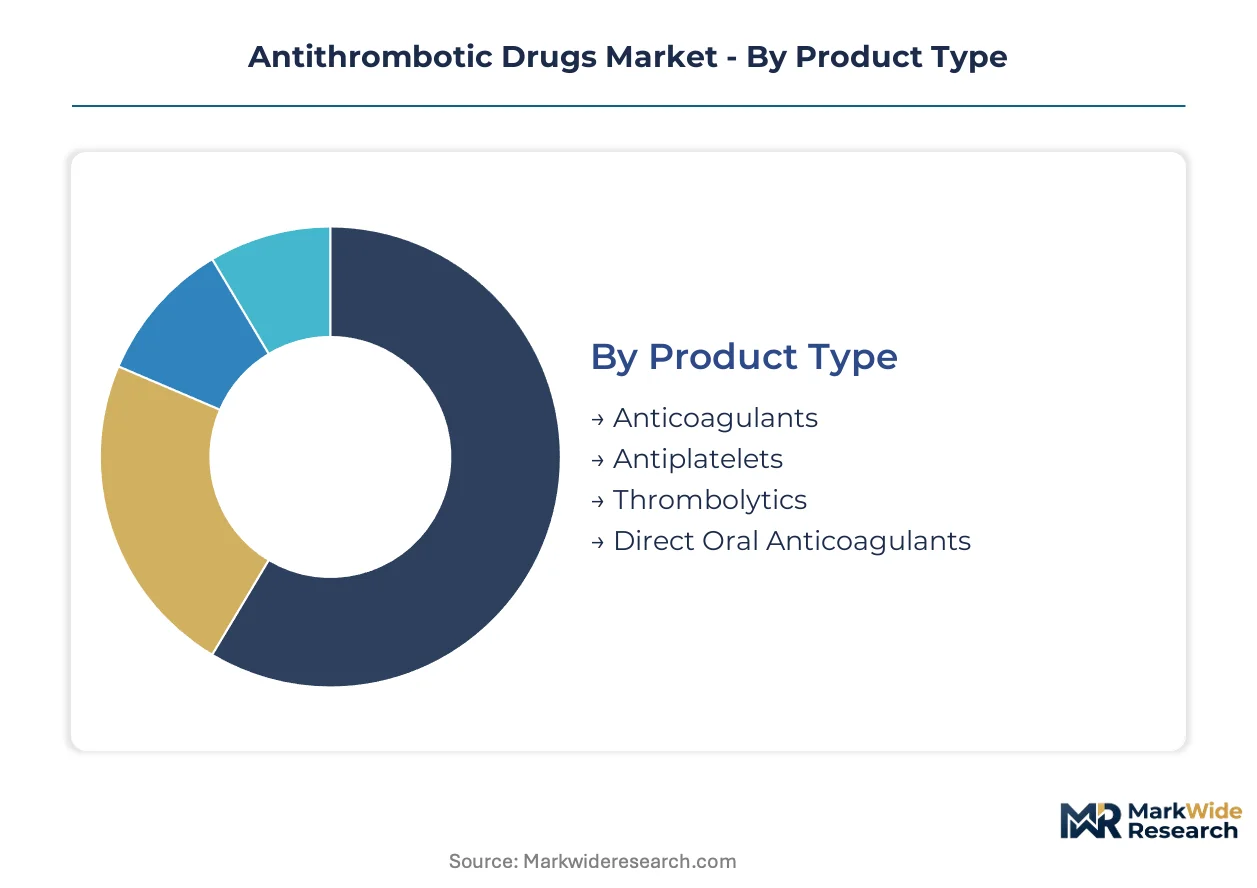
Antithrombotic drug segmentation reveals how formulation choices and care settings determine competitive positioning. Supply chain configuration varies sharply across delivery modes and end-user channels, dictating margin structures and procurement leverage.
Product Type:
Supply concentration in anticoagulant active pharmaceutical ingredients clusters around heparin derivatives and direct oral anticoagulant synthesis, with contract manufacturing geography shaping availability.
- Anticoagulants:Heparin and low-molecular-weight heparin formulations dominate perioperative protocols across United States hospital systems. Demand concentrates in orthopedic and cardiac surgery units where injectable prophylaxis remains standard despite direct oral anticoagulant encroachment.
- Antiplatelets:P2Y12 inhibitors and aspirin combinations anchor secondary stroke prevention and post-stenting regimens. Cardiology service lines in Germany and Japan drive volume through protocol-driven dual antiplatelet therapy durations.
- Thrombolytics:Tissue plasminogen activator variants retain concentrated use in acute ischemic stroke protocols with narrow therapeutic windows.
- Direct Oral Anticoagulants:Factor Xa and direct thrombin inhibitors displace warfarin in atrial fibrillation stroke prevention through fixed-dosing advantages.
Anticoagulants absorb the bulk of installed capacity; direct oral anticoagulants are expanding most quickly.
Delivery Mode:
Cost tier differentiation separates chronic outpatient management from acute inpatient interventions, with route selection determining reimbursement coding and pharmacy budget allocation.
- Oral:Tablet and capsule formulations enable outpatient adherence for chronic conditions. United States Medicare Advantage plans favor oral direct oral anticoagulants for atrial fibrillation populations to reduce monitoring infrastructure costs.
- Injectable:Prefilled syringes and vials command perioperative prophylaxis in European hospital systems with standardized venous thromboembolism prevention protocols.
- Intravenous:Rapid-onset anticoagulation for intensive care and emergency settings where precise titration is required.
- Subcutaneous:Self-administered low-molecular-weight heparin bridges hospital discharge to home care transitions.
Oral delivery captures the highest prescription volume; subcutaneous routes are climbing the fastest through home care expansion.
Application:
Volume concentration tracks cardiovascular disease prevalence and surgical procedure rates, with atrial fibrillation driving the steepest demand expansion through aging demographics.
- Cardiovascular Disorders:Post-myocardial infarction and peripheral artery disease management requires sustained antithrombotic coverage. German and Italian hospital systems standardize dual pathway inhibition protocols across cardiology departments.
- Thrombosis Prevention:Venous thromboembolism prophylaxis extends to medical inpatients beyond surgical populations. United States Joint Commission accreditation mandates drive hospital formulary compliance.
- Surgery:Orthopedic and cardiac procedures require perioperative interruption and resumption protocols.
- Atrial Fibrillation:Stroke prevention in non-valvular atrial fibrillation represents the primary growth vector for direct oral anticoagulant prescribing.
Cardiovascular disorders absorb the bulk of installed capacity; atrial fibrillation is gaining share fastest through Medicare reimbursement expansion.
End User:
Customer type determines procurement scale and protocol standardization, with hospital systems consolidating purchasing authority away from individual clinicians.
- Hospitals:Integrated delivery networks in the United States and national health systems in France centralize formulary decisions through pharmacy and therapeutics committees. Anticoagulation stewardship programs reduce bleeding complications through order set standardization.
- Clinics:Cardiology and hematology outpatient practices manage chronic anticoagulation with remote monitoring support.
- Home Care:Subcutaneous administration and oral regimens shift postoperative prophylaxis outside institutional settings.
- Ambulatory Surgical Centers:Same-day procedures require abbreviated anticoagulant interruption protocols.
Hospitals absorb the bulk of installed capacity; home care is expanding most quickly through discharge optimization initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in Ireland and Singapore concentrate active pharmaceutical ingredient synthesis for antithrombotic supply chains. Tax-advantaged jurisdictions attract multinational fill-finish operations and regional distribution hubs.
United States
Medicare reimbursement expansion for atrial fibrillation stroke prevention drives outpatient oral anticoagulant volume through Medicare Advantage plans. The FDA's Division of Cardiovascular and Renal Products evaluates novel agents against warfarin benchmarks, compressing approval timelines for sponsors with established safety databases. The Research Triangle Park corridor in North Carolina hosts clinical trial operations and pharmacovigilance centers monitoring real-world bleeding signals.
Germany
Cardiology service lines standardize dual antiplatelet therapy durations, anchoring European prescribing patterns for post-stenting regimens. The national pharmaceutical regulator coordinates with the EMA's Pharmacovigilance Risk Assessment Committee on hemorrhage surveillance across member states. The Rhine-Main cluster around Frankfurt concentrates hospital pharmacy procurement authority and anticoagulation stewardship program development.
Japan
Aging demographics expand venous thromboembolism prophylaxis coverage for surgical patients over 75, matching North American protocol expansion. METI oversees domestic pharmaceutical pricing negotiations that determine reimbursement for novel oral anticoagulants. The Kansai region around Osaka maintains concentrated manufacturing capacity for heparin derivatives and low-molecular-weight heparin formulations.
India
Contract manufacturing organizations produce injectable anticoagulant active pharmaceutical ingredients for Western hospital systems, creating supply concentration vulnerability. CDSCO abbreviated approval pathways for biosimilar enoxaparin open margin compression strategies for domestic portfolio managers. The Hyderabad-Visakhapatnam corridor hosts fermentation-based heparin production facilities serving global generic supply chains.
Switzerland
Specialized cardiovascular research institutes advance Factor XI inhibition candidates through antisense and monoclonal antibody modalities. Swissmedic coordinates with the EMA on perioperative bridging protocol guidance while maintaining independent national labeling authority. The Basel-Zurich corridor concentrates pharmaceutical headquarters operations and early-phase cardiovascular development infrastructure.
Antithrombotic Drugs Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-intensive developers commanding premium positioning in oral anticoagulant categories while injectable supply chains consolidate around manufacturing scale. The market structure tiers across three archetypes: legacy cardiovascular franchises with established hospital formularies, mid-scale specialists pursuing biosimilar pathways, and contract manufacturers capturing active pharmaceutical ingredient supply concentration. Dominant competitive moves include strategic partnerships for reversal agent co-development and geographic expansion into underpenetrated prophylaxis markets.
Within the legacy cardiovascular franchise tier, Bayer AG and Pfizer Inc. occupy positions reflecting established European hospital contracts and manufacturing scale in injectable supply chains respectively. Bristol-Myers Squibb Company anchors North American prescribing patterns through its cardiovascular service line concentration. Boehringer Ingelheim International GmbH exemplifies the mid-scale specialist archetype with concentrated development focus on direct oral anticoagulant portfolios. These named entities represent strategic positioning patterns rather than exhaustive market coverage, with additional concentration residing in diversified pharmaceutical conglomerates and regional generic manufacturers.
| Leading Market Players |
|---|
| Bayer AG |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Sanofi |
| Boehringer Ingelheim International GmbH |
| AstraZeneca plc |
| Johnson & Johnson Services Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Factor XI inhibitor development programs are compressing synthesis cost curves while fragmenting active pharmaceutical ingredient supplier tiers between legacy heparin fermenters and novel biologic contract manufacturers. This technology transition simultaneously erodes pricing power in mature anticoagulant categories and concentrates margin capture among antisense modality specialists with captive manufacturing infrastructure.
Pricing Analysis
Volume concentration in generic enoxaparin compresses margins at the economy tier while novel oral anticoagulants defend premium positioning through FDA breakthrough therapy designation and EMA conditional approval pathways. Price differentiation hinges on reversal agent availability and perioperative bridging protocol clarity, with United States Medicare Advantage plans exhibiting highest price sensitivity due to standardized therapeutic substitution mandates. Pricing pressure intensifies in injectable prophylaxis segments as Indian and Chinese contract manufacturers expand biosimilar enoxaparin capacity.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems and European national health services mandate qualified backup suppliers for heparin sodium and low-molecular-weight heparin active pharmaceutical ingredients. Supply concentration clusters in China, India, and the United States for fermentation-based heparin precursors and synthetic direct oral anticoagulant intermediates. Raw material dependencies center on porcine intestinal mucosa, synthetic pyridines, and specialized chromatography resins. Single-source vulnerability in Chinese contract manufacturing creates exposure to export license restrictions. Distribution runs through regional distribution hubs in Ireland and Singapore serving Western hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct oral anticoagulant fixed-dosing protocols are displacing warfarin monitoring infrastructure, compressing the technology-transition window for legacy anticoagulant portfolios. Incumbents, new entrants, and investors face divergent strategic imperatives as Factor XI inhibitors resegment prophylaxis markets.
For Market Incumbents: Hedge exposure to heparin volume erosion by securing biosimilar enoxaparin abbreviated approval pathways through CDSCO and FDA parallel submissions. Anchor hospital formulary position through anticoagulation stewardship program partnerships that embed protocol-driven order sets. Invest in reversal agent co-development to defend premium direct oral anticoagulant pricing against andexanet alfa cost compression. For New Entrants and Emerging Players: The premium-economy price gap in subcutaneous prophylaxis creates white-space opportunity for differentiated low-molecular-weight heparin formulations with extended half-life profiles. Target South African and Nigerian hospital systems lacking standardized venous thromboembolism protocols. Pursue telemedicine anticoagulation clinic partnerships as a go-to-market angle that bypasses entrenched hospital pharmacy committee gatekeeping. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale cardiovascular specialists with Phase II Factor XI inhibitor assets and established European hospital contracts. Long-term viability favors developers with integrated manufacturing infrastructure spanning fermentation and synthetic chemistry capabilities. Watch EMA perioperative bridging protocol guidance revisions as the inflection signal for anticoagulant switching velocity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Reversal Agent Co-Development | Andexanet alfa and idarucizumab partnerships secure formulary access in budget-constrained European hospitals. |
| Biosimilar Enoxaparin Pathway | CDSCO and FDA abbreviated approvals enable margin compression strategies in injectable prophylaxis segments. |
| Anticoagulation Stewardship Programs | Hospital system partnerships embed protocol-driven order sets that displace fragmented specialist prescribing. |
| Factor XI Inhibitor Clinical Advancement | Antisense and monoclonal antibody modalities preserve hemostasis while blocking pathologic thrombosis in surgical populations. |
| Telemedicine Clinic Platform | Remote INR monitoring and adherence platforms capture chronic patient management from traditional anticoagulation clinics. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for this analysis, supplemented by formulary database reviews and Medicare reimbursement documentation. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated secondary findings. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Historical trendline analysis across approved anticoagulant prescribing patterns informed projection frameworks segmented by product type, delivery mode, application, and end user. Treatment line positioning, dosage form preferences, and regional regulatory clusters shaped analytical boundaries. CAGRs were derived from patent expiry timelines, biosimilar entry assumptions, and Medicare Advantage contracting velocity across the modeling period. Forecast inputs incorporated EMA switching guidance adoption rates and FDA accelerated approval pathway utilization.
Inputs from hospital procurement databases and GPO contracts were available through the study window; gaps in real-world bleeding signal surveillance infrastructure introduce uncertainty bands around formulary adoption timelines. Forecasts reflect assumptions regarding EMA perioperative bridging protocol finalization and Medicare reimbursement category stability. Deviation in FDA reversal agent labeling requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Ibuprofen API Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Global Pharmacokinetics Services Market
Pharmacology
Pegylated Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Anti-Asthma Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Influenza Medication Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Hepatitis C Drug Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Cough Remedies Market
Pharmacology
Semaglutide API Market