
 Istradefylline API Market | 2026-2036
Istradefylline API Market Size, Share, and Industry Trends Forecast 2026-2036
Istradefylline API Market Insights
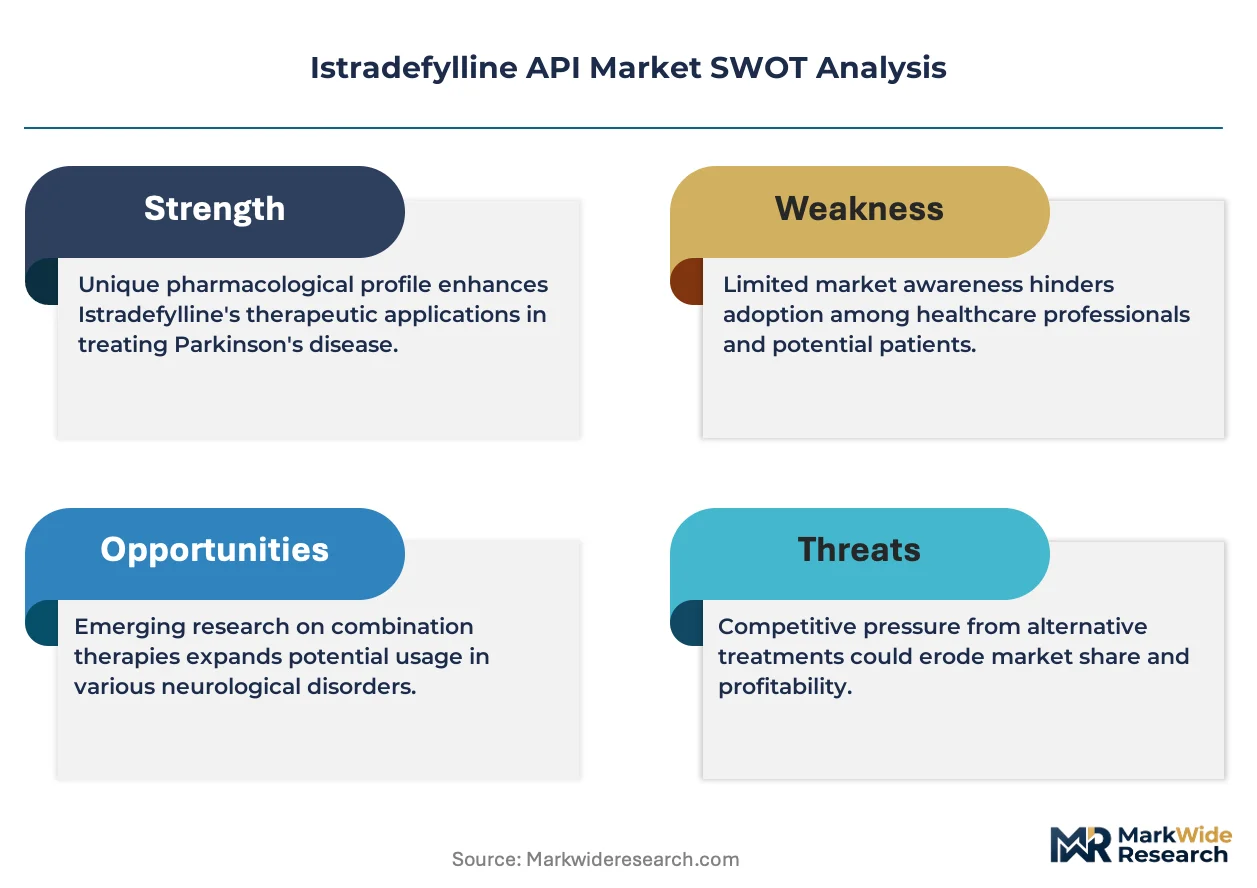
Project finance for dedicated API manufacturing facilities is narrowing the competitive field to firms with balance-sheet capacity for multi-year capital commitments. Hunan Huateng Pharmaceutical leverages vertical integration across intermediate synthesis to finished API, sustaining cost advantages in bulk quotations. Zhejiang Ausun Pharmaceutical anchors its position through specialized expertise in heterocyclic chemistry required for istradefylline's purine core. Transo-Pharm competes via geographic proximity to European formulation clients, reducing logistics complexity for just-in-time supply.
Istradefylline API is the active pharmaceutical ingredient of an adenosine A2A receptor antagonist used in Parkinson's disease adjunct therapy, typically synthesized through multi-step organic routes involving xanthine derivative formation with stringent purity requirements above 99.5%. The molecule serves as the critical input for finished dosage forms addressing motor fluctuation management in patients on levodopa regimens. Oral solid dosage forms dominate current procurement volumes due to established bioequivalence profiles and patient compliance advantages, while extended release formulations represent the fastest-growing delivery technology as developers seek reduced dosing frequency. Parkinson's disease anchors the therapy area segmentation with mature demand patterns, whereas neurodegenerative disorder applications outside Parkinson's hold emerging margin pools for early movers.
Japan's PMDA maintains stringent GMP inspection protocols for imported APIs, while China's NMPA enforces drug master file filing requirements that shape market access timelines for foreign suppliers. The US FDA's drug substance pre-approval inspection framework further conditions entry for manufacturers targeting ANDA filings for generic istradefylline formulations. Stakeholders must monitor evolving bioequivalence study requirements for extended release variants as regulatory agencies refine dissolution testing standards.
Market Dynamics
Japan's Parkinson's disease treatment protocols are expanding istradefylline API volumes as hospital systems standardize adenosine A2A receptor antagonist adjunct therapy. Kyowa Kirin's original brand established prescriber familiarity, creating pull-through demand that API manufacturers must now satisfy under stringent purity specifications.
Growth Catalysts
- Japan's formulary expansion:Major hospital systems in Tokyo and Osaka are adding istradefylline to standard Parkinson's protocols, creating institutional demand pull.
- PMDA GMP harmonization:Streamlined inspection protocols for imported APIs are reducing market access timelines for qualified foreign suppliers.
- Extended release development:Formulation innovators are investing in modified-release technologies to reduce dosing frequency and improve patient compliance.
Market Restraints
- Purine intermediate volatility:Xanthine derivative precursors face supply concentration in Chinese chemical clusters, exposing margins to input cost swings.
- PMDA inspection backlog:Japan's stringent on-site verification requirements create 12-18 month approval delays for new API entrants.
- Levodopa optimization competition:Advanced carbidopa-levodopa formulations and surgical interventions compete for adjunct therapy positioning.
Strategic Opportunities
- China's NMPA pathway acceleration:Revised drug master file rules enable faster registration for domestic API producers serving both local and export markets.
- Neurodegenerative expansion:Clinical investigators are exploring istradefylline applications beyond Parkinson's in atypical parkinsonism syndromes.
- Continuous manufacturing adoption:Flow chemistry integration with real-time release testing promises yield improvements and batch-to-batch consistency gains.
Industry Challenges
- Heterocyclic synthesis expertise scarcity:Purine core construction requires specialized chemists with rare skill sets in xanthine chemistry.
- Multi-year capex cycles:Dedicated API facilities demand 4-6 year construction timelines with no revenue generation during qualification phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Istradefylline API Market |
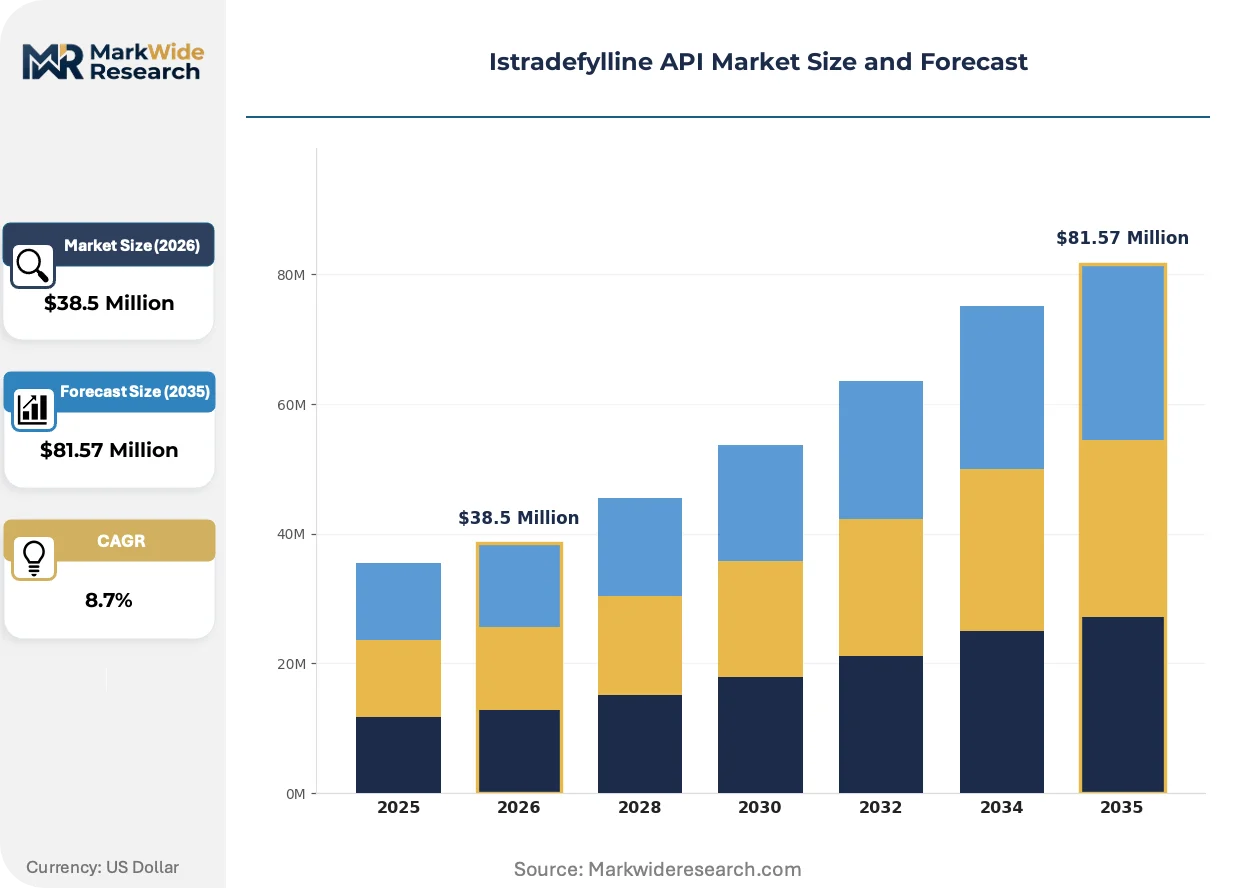
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $81.57 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Oral, Extended Release, Immediate Release Therapy Area: Parkinson's Disease, Restless Legs Syndrome, Neurodegenerative Disorders, Cognitive Impairments Delivery Mode: Intravenous, Subcutaneous, Oral Solid Dosage, Oral Liquid End User: Pharmaceutical Companies, Contract Research Organizations, Hospitals, Clinics |
| Companies Covered | Hunan Huateng Pharmaceutical, Zhejiang Ausun Pharmaceutical, Transo-Pharm, TATEYAMA KASEI, Kyowa Pharma Chemical, OUCHI SHINKO CHEMICAL INDUSTRIAL, Lifecare Laboratories Pvt Ltd, MSN Laboratories, ALP Pharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Istradefylline API Market Trends and Innovations
Process intensification and regulatory science advances are compressing development timelines for istradefylline API while raising the bar for impurity profiling. Manufacturers are reconfiguring synthesis routes to accommodate evolving pharmacopeial standards.
Continuous flow chemistry is hybridizing with traditional batch processing in istradefylline synthesis. European contract manufacturers are piloting integrated reaction-separation modules for the critical cyclization step. This technology convergence is enabling tighter process control and reducing solvent waste volumes.
Japan's PMDA has tightened residual solvent guidelines for APIs used in chronic neurological indications. The revised ICH Q3C implementation requires additional validation studies for Class 2 solvents. Extended release formulation developers face the steepest compliance burden as dissolution specification ranges narrow.
Hospital procurement consortia are consolidating API sourcing decisions across regional health systems. Japan's university hospital networks now negotiate annual API supply agreements through centralized pharmaceutical committees. This buyer concentration is compressing supplier margins while favoring manufacturers with demonstrated PMDA inspection histories.
Istradefylline API Market Segmentation
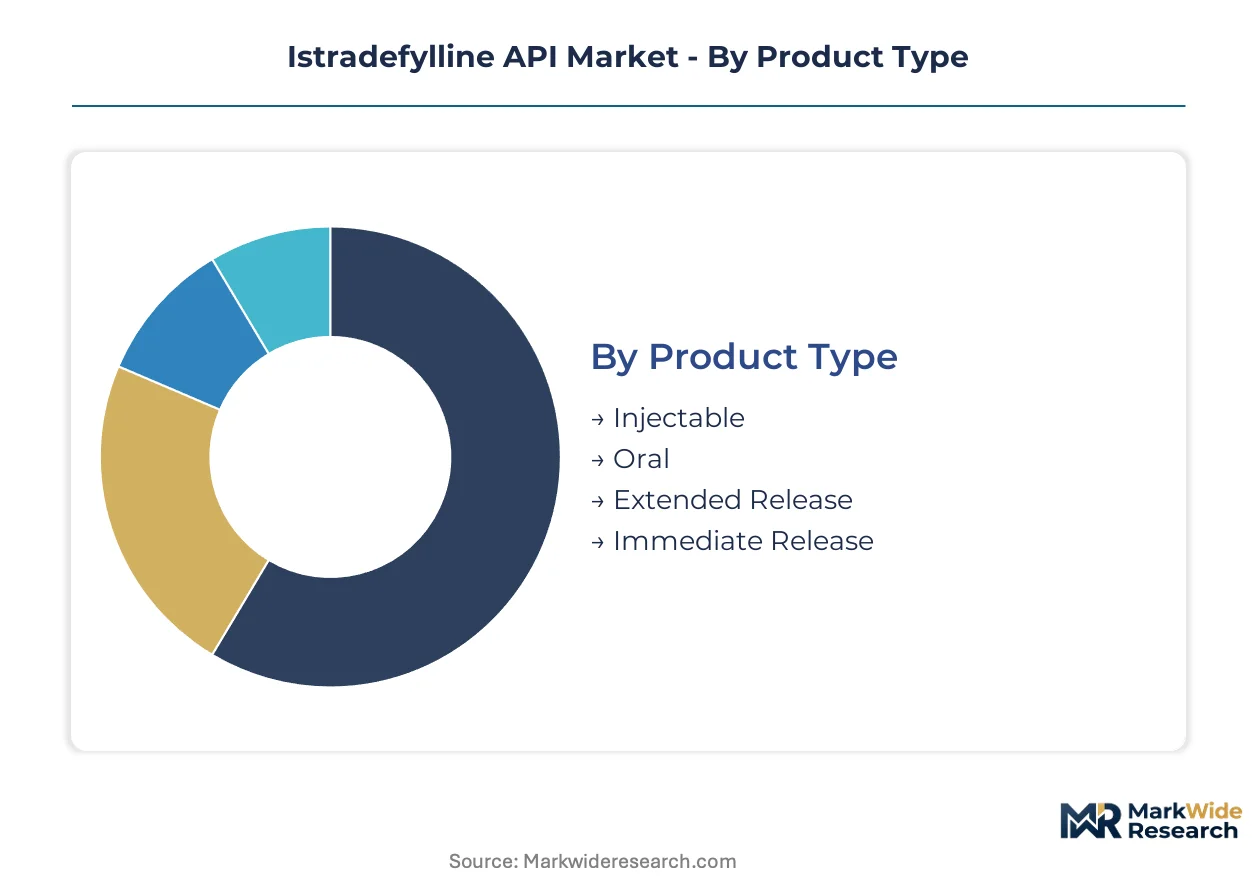
Istradefylline API demand fragments across formulation technologies and clinical applications, with each segment imposing distinct purity specifications and regulatory validation burdens. Manufacturers configure production assets around specific delivery modes, creating specialization premiums that resist commoditization.
Product Type:
Mature oral formats dominate procurement volumes, while emerging extended-release technologies command development investment and margin premiums.
- Oral:Solid dosage forms incorporating istradefylline API require micronization to achieve consistent dissolution profiles for bioequivalence. Hospital formularies in Japan source these formats for outpatient Parkinson's management, with procurement committees favoring established bioequivalence data over novel presentations.
- Extended Release:Matrix-formulation technologies enable reduced dosing frequency through controlled istradefylline release kinetics. European formulation developers are advancing these programs to differentiate against immediate-release generics, though PMDA dissolution specification ranges have tightened validation requirements.
- Injectable:Parenteral-grade API demands endotoxin limits below established oral thresholds, restricting qualified supplier pools.
- Immediate Release:Conventional tablet formulations anchor current generic substitution strategies for cost-sensitive markets.
Oral formats handle the majority of throughput; extended release is expanding most quickly on share.
Therapy Area:
Application concentration varies sharply across neurological indications, with established disease areas offering volume stability versus exploratory uses promising margin expansion.
- Parkinson's Disease:Adenosine A2A receptor antagonism in levodopa adjunct therapy represents the validated clinical application with defined reimbursement pathways. Japanese neurologists at university hospitals have standardized istradefylline prescribing protocols, creating predictable API demand patterns for qualified suppliers.
- Neurodegenerative Disorders:Investigators are probing istradefylline efficacy in atypical parkinsonism and related tauopathies through expanded access programs. Early movers in API supply for these trials are securing preferential relationships with academic medical centers running investigator-sponsored studies.
- Restless Legs Syndrome:Off-label utilization remains limited by sparse clinical evidence and competing dopaminergic therapies.
- Cognitive Impairments:Preclinical exploration of adenosine modulation in vascular cognitive decline has not advanced to registrational trials.
Parkinson's Disease absorbs the bulk of manufacturing capacity; Neurodegenerative Disorders is gaining share fastest.
Delivery Mode:
Route of administration determines facility qualification requirements, with parenteral formats imposing sterility assurance burdens that oral routes avoid.
- Oral Solid Dosage:Tablet and capsule formulations require standard GMP compliance without aseptic processing constraints. Chinese API producers have optimized crystallization and drying protocols specifically for oral-grade istradefylline, achieving cost structures that undercut European contract manufacturers.
- Intravenous:Solution formulations for hospital infusion demand pyrogen-free API with particulate matter specifications exceeding oral grades. PMDA inspection protocols for sterile API manufacturing have concentrated qualified supply among Japanese domestic producers and established European CMOs.
- Subcutaneous:Depot formulations remain developmental, with no commercial istradefylline products approved for this route.
- Oral Liquid:Suspension formulations address dysphagia populations in aged Parkinson's cohorts, though stability challenges limit commercial adoption.
Oral Solid Dosage carries the volume base; Intravenous is climbing the fastest on share.
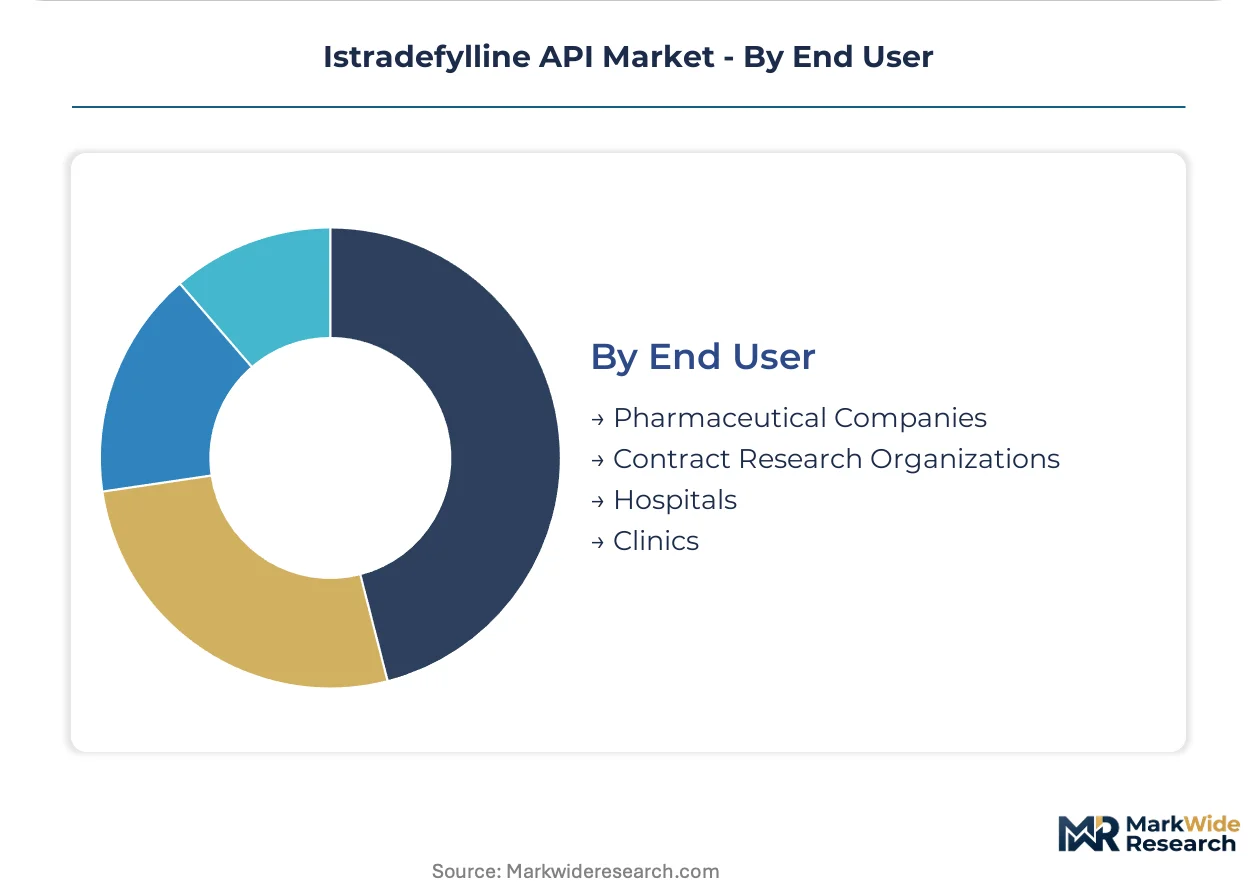
End User:
Customer type shapes contract structures, with pharmaceutical companies negotiating multi-year supply agreements while clinical research organizations drive spot demand for investigational batches.
- Pharmaceutical Companies:Finished dosage form manufacturers procure istradefylline API under master service agreements with defined quality agreements and audit rights. Kyowa Kirin's original Nourioz brand suppliers have transitioned to generic API customers, transferring process knowledge under technology transfer protocols.
- Hospitals:University medical centers in Japan operate compounding pharmacies preparing istradefylline for specialized protocols. Centralized pharmaceutical committees at Tokyo and Osaka hospital networks now aggregate API sourcing decisions, compressing supplier margins through volume concentration.
- Contract Research Organizations:Clinical trial material suppliers require small-batch API with accelerated analytical release timelines.
- Clinics:Outpatient neurology practices rely on commercial finished products rather than direct API procurement.
Pharmaceutical Companies manage the predominant share of orders; Hospitals are expanding their sourcing role fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese API manufacturers dominate supply to Japanese formulation sites, while European contract manufacturers serve niche parenteral-grade demand. Import dependency in Japan creates regulatory friction through PMDA inspection queues.
Japan
University hospital networks in Tokyo and Osaka drive prescription volume for istradefylline adjunct therapy. PMDA maintains 12-18 month inspection backlogs for foreign API facilities seeking market entry. Kyowa Pharma Chemical anchors domestic supply from its Toyama prefecture manufacturing base.
China
NMPA's revised drug master file rules accelerated domestic API registration timelines for export-oriented producers. The country's national pharmaceutical regulator now permits parallel filing for domestic approval and international supply contracts. Hunan and Zhejiang provinces host concentrated heterocyclic synthesis clusters serving istradefylline intermediate demand.
United States
ANDA filers targeting generic istradefylline formulations await FDA drug substance pre-approval inspections. The agency's risk-based facility assessment framework prioritizes chronic neurological indication APIs for enhanced surveillance. New Jersey and Massachusetts formulation developers source oral-grade material under quality agreements with Asian suppliers.
India
CDSCO's alignment with ICH Q3C residual solvent standards positions domestic API producers for contract manufacturing opportunities. The national pharmaceutical regulator accelerated stability study waivers for established xanthine derivative manufacturers. Hyderabad and Mumbai pharmaceutical corridors house analytical testing capacity supporting istradefylline impurity profiling.
Germany
EMA's centralized procedure for orphan neurological indications creates reference country status for istradefylline generic approvals. The European Medicines Agency's GMP inspection mutual recognition agreements reduce redundant facility audits. Bavarian and North Rhine-Westphalian contract manufacturers specialize in high-potency API containment for neuroactive compounds.
Istradefylline API Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated Chinese producers and specialized Japanese chemical manufacturers. The competitive set organizes around three strategic archetypes: purine chemistry specialists, hospital-proximate formulators, and regulatory navigation services. Dominant competitive moves include backward integration into xanthine intermediate production and technology transfer partnerships with originator process knowledge holders.
Among Chinese API producers, Hunan Huateng Pharmaceutical and Zhejiang Ausun Pharmaceutical exemplify the integrated-manufacturer archetype, while Transo-Pharm represents the European geographic-proximity model for just-in-time supply to formulation clients.
| Leading Market Players |
|---|
| Hunan Huateng Pharmaceutical |
| Zhejiang Ausun Pharmaceutical |
| Transo-Pharm |
| TATEYAMA KASEI |
| Kyowa Pharma Chemical |
| OUCHI SHINKO CHEMICAL INDUSTRIAL |
| Lifecare Laboratories Pvt Ltd |
| MSN Laboratories |
| ALP Pharm |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Osaka container freight corridors transmit cost volatility directly into API procurement economics, compressing margins for European contract manufacturers while amplifying price differentiation between PMDA-certified and uncertified supply tiers. Xanthine intermediate concentration in Hunan and Zhejiang provinces creates upstream leverage that downstream formulation clients struggle to offset through volume commitments.
Pricing Analysis
Pharmaceutical company procurement teams anchor contract structures around multi-year master service agreements with defined quality tiers. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-inspected Japanese suppliers from NMPA-registered Chinese producers and uncertified spot-market entrants. Cost compression in the standard tier is intensifying because hospital procurement consortia aggregate demand across Tokyo and Osaka networks. Generic ANDA filers exhibit highest price sensitivity, while innovator formulation developers maintain lowest sensitivity due to bioequivalence study cost absorption.
Supply Chain Analysis
Hunan Huateng Pharmaceutical, Zhejiang Ausun Pharmaceutical, and Kyowa Pharma Chemical hold concentrated heterocyclic synthesis capacity for purine core construction. China, Japan, and India anchor geographic supply, with xanthine derivative precursors, specialized solvents, and analytical reference standards feeding production pipelines. Single-source vulnerability in xanthine intermediate supply exposes margins to input cost swings from Zhejiang chemical clusters. Distribution runs through formulation developers under technology transfer protocols rather than direct hospital API procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Istradefylline API demand follows cyclical patterns tied to Parkinson's disease prevalence demographics, with Japan's aging population structure supporting sustained volume recovery across the projection horizon.
For Market Incumbents: Entrench PMDA inspection histories through proactive facility upgrades ahead of guideline revisions, while securing backward integration into xanthine intermediate production to defend against Chinese cost structures. Kyowa Kirin technology transfer partnerships represent a critical lever for process knowledge retention as generic formulation developers enter procurement.
For New Entrants and Emerging Players: Establish a beachhead in neurodegenerative disorder clinical trial material supply, where investigator-sponsored studies at European academic medical centers offer lower regulatory barriers than Japanese commercial entry. Parenteral-grade API for hospital infusion protocols presents the most penetrable segment given concentrated qualified supplier pools.
For Investors and Strategic Acquirers: Carve-out targets emerge from Japanese chemical conglomerates divesting non-core pharmaceutical intermediates divisions, particularly those with dormant PMDA inspection credentials. Long-term viability hinges on continuous manufacturing adoption curves; the signal to watch is flow chemistry pilot announcements from European contract manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Flow chemistry integration with PMDA real-time release testing protocols reduces batch-to-batch variability for oral solid dosage forms. |
| Backward Integration into Xanthine Intermediates | Captive supply of purine core precursors insulates margin structures from Zhejiang chemical cluster price volatility. |
| Extended Release Formulation Partnership | Matrix-technology collaborations with European developers access premium pricing for reduced dosing frequency protocols. |
| PMDA Pre-Approval Inspection Preparation | Proactive facility qualification reduces 12-18 month market access delays for foreign API entrants targeting Japanese hospital networks. |
| Neurodegenerative Clinical Trial Supply Agreement | Preferential relationships with academic medical centers secure early-mover positioning in atypical parkinsonism applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with API manufacturing executives, regulatory affairs specialists at NMPA and PMDA, hospital pharmaceutical committee directors, and generic formulation development leads. Secondary validation drew from FDA drug master file submissions, EMA centralized procedure documentation, Japanese Ministry of Health reimbursement bulletins, and customs trade flow records. Bottom-up volume estimates from individual facility capacities were triangulated against top-down therapy area demand projections.
Calibration against historical API price trajectories and Parkinson's disease prescription volumes anchored the analytical framework across the analysis window. Segmentation dimensions modeled include delivery mode, therapy area application, purity grade tier, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized volume curves. Forecast inputs incorporated PMDA inspection queue dynamics and NMPA drug master file processing timelines as industry-specific modifiers.
Macroeconomic conditions sit as an overlay; deviation in yen-dollar exchange rates, container freight indices, and Chinese environmental enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding PMDA inspection harmonization progress and extended release bioequivalence study completion rates. Quarterly review of hospital procurement consortium tender announcements and clinical trial registration flows is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Sodium-Dependent Glucose Cotransporter 2 (SGLT-2) Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Global Cyclosporine Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
3D Printing Drug Market