
 Oxaliplatin Market | 2026-2036
Oxaliplatin Market Size, Share, and Industry Trends Forecast 2026-2036
Oxaliplatin Market Outlook
Lyophilized formulation technology is rewriting how oxaliplatin products achieve stability and cold-chain efficiency across distribution networks. Sanofi leverages its original research heritage to sustain brand loyalty among oncologists in European and North American hospitals. Fresenius Kabi anchors its position through vertical integration into sterile injectable manufacturing, controlling cost structures for infusion-grade oxaliplatin. Teva Pharmaceutical Industries competes aggressively on price across emerging markets where generic substitution policies accelerate volume shifts.
Oxaliplatin is a platinum-based antineoplastic agent containing a diaminocyclohexane carrier ligand and oxalate leaving group, formulated for intravenous administration at concentrations typically ranging from 2 mg/mL to 5 mg/mL in sterile solutions or lyophilized powders requiring reconstitution. The compound exerts cytotoxicity through DNA cross-linking, primarily indicated for adjuvant and metastatic colorectal cancer in combination with fluoropyrimidines. Injection formulations dominate current revenue pools due to hospital preference for precise dosing control, while infusion presentations represent the fastest-expanding segment as outpatient cancer centers seek longer-duration administration protocols. Colorectal cancer applications command the largest patient volume, though gastric cancer protocols are gaining traction in East Asian treatment guidelines where diffuse-type adenocarcinoma prevalence drives protocol diversification.
FDA bioequivalence standards and EMA good manufacturing practice requirements shape product approval timelines and facility qualification costs for oxaliplatin manufacturers seeking market access. CDSCO in India enforces import testing protocols that delay generic entry, while China's NMPA accelerates local approvals for domestic producers such as Qilu Pharmaceutical and Jiangsu Hengrui Medicine. Stakeholders must monitor evolving pharmacopeial monograph revisions and biosimilar guidance documents that could redefine purity specifications and analytical method requirements for platinum-based cytotoxics.
Market Dynamics
FDA and EMA bioequivalence standards for generic platinum compounds are compressing approval timelines while raising facility qualification costs, forcing manufacturers to prioritize lyophilized formulation investments over liquid presentations.
Growth Catalysts
- EMA Good Manufacturing Practice harmonization:Streamlined cross-border facility inspections reduce redundant compliance burdens for sterile injectable producers serving multiple European markets.
- Outpatient cancer center expansion:Extended-duration infusion protocols enable same-day discharge, expanding addressable patient volume beyond traditional inpatient settings.
- East Asian gastric cancer protocols:Diffuse-type adenocarcinoma prevalence in Japan and South Korea drives protocol diversification beyond colorectal applications.
Market Restraints
- Platinum raw material concentration:Refining capacity clusters in South Africa and Russia expose manufacturers to geopolitical supply disruptions and price volatility.
- Cold-chain infrastructure gaps:Temperature-controlled distribution requirements limit market penetration in regions with unreliable logistics networks.
- Fluoropyrimidine combination toxicity:Dose-limiting neurotoxicity profiles constrain long-term therapy adherence and retreatment eligibility.
Strategic Opportunities
- India CDSCO import testing reform:Streamlined generic approval pathways would accelerate market entry for qualified sterile injectable producers.
- Subcutaneous delivery convergence:Combination with sustained-release polymer technologies could enable home administration and reduce infusion center dependency.
- China NMPA domestic preference policies:Joint venture structures with local producers such as Qilu Pharmaceutical unlock priority review status and provincial procurement access.
Industry Challenges
- Aseptic manufacturing skill scarcity:Qualified personnel for platinum compound handling and sterile filling operations command premium wages and extended recruitment cycles.
- Multi-jurisdiction pharmacopeial divergence:USP, EP, and ChP monograph inconsistencies force redundant analytical method validation and release testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxaliplatin Market |
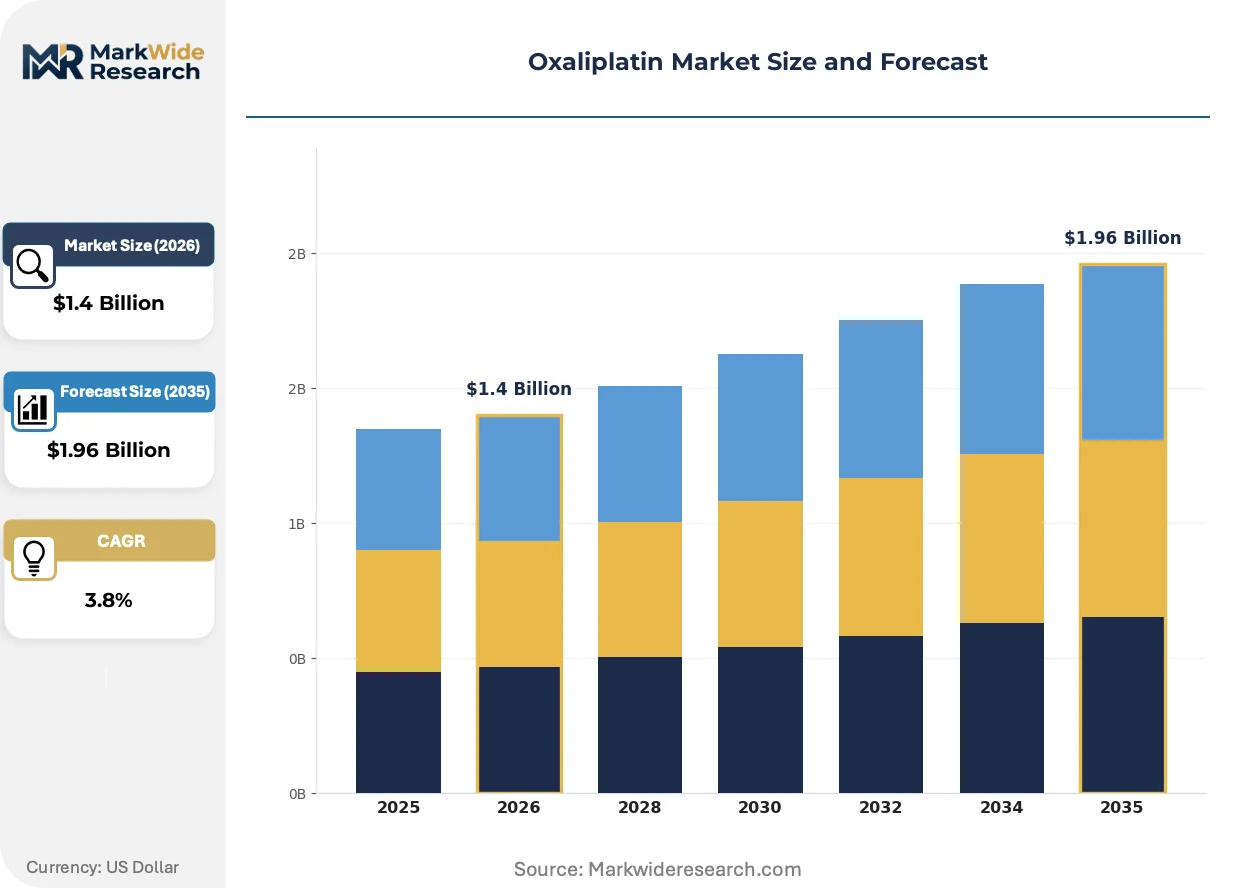
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection, Infusion, Tablet, Solution Application: Colorectal Cancer, Gastric Cancer, Pancreatic Cancer, Ovarian Cancer End User: Hospitals, Clinics, Research Institutions, Home Care Delivery Mode: Intravenous, Oral, Subcutaneous, Others |
| Companies Covered | Sanofi, Fresenius Kabi, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Sun Pharmaceutical Industries Ltd, Dr. Reddy's Laboratories Ltd., Qilu Pharmaceutical Co., Ltd, Jiangsu Hengrui Medicine, Hisun Pharmaceutical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxaliplatin Market Strategic Shifts
Lyophilized stability technologies and regulatory convergence are compressing product development cycles while enabling geographic expansion into markets previously inaccessible due to cold-chain limitations.
Lyophilized powder formulations are migrating from niche stability solutions to standard-of-care presentations across major hospital systems. European oncology pharmacies are adopting these formats to reduce wastage from multi-dose vial sharing. This migration from liquid to solid-state presentations is enabling direct-to-hospital distribution models that bypass wholesale temperature controls.
EMA's revised sterile manufacturing guidelines are mandating isolator-based filling lines for all new platinum cytotoxic approvals. Legacy open-facility operations face mandatory upgrade timelines or market withdrawal. German and French hospital procurement consortia are now requiring documentation of isolator technology for all new supplier qualifications.
Hospital buying groups are consolidating chemotherapy purchasing across regional networks, displacing individual pharmacy-level contracting. This concentration is compressing price negotiation cycles and favoring suppliers with multi-site distribution capabilities. The United States and Germany exhibit the most advanced consolidation, with three to five buying groups now controlling majority volume in major metropolitan areas.
Oxaliplatin Market Segmentation
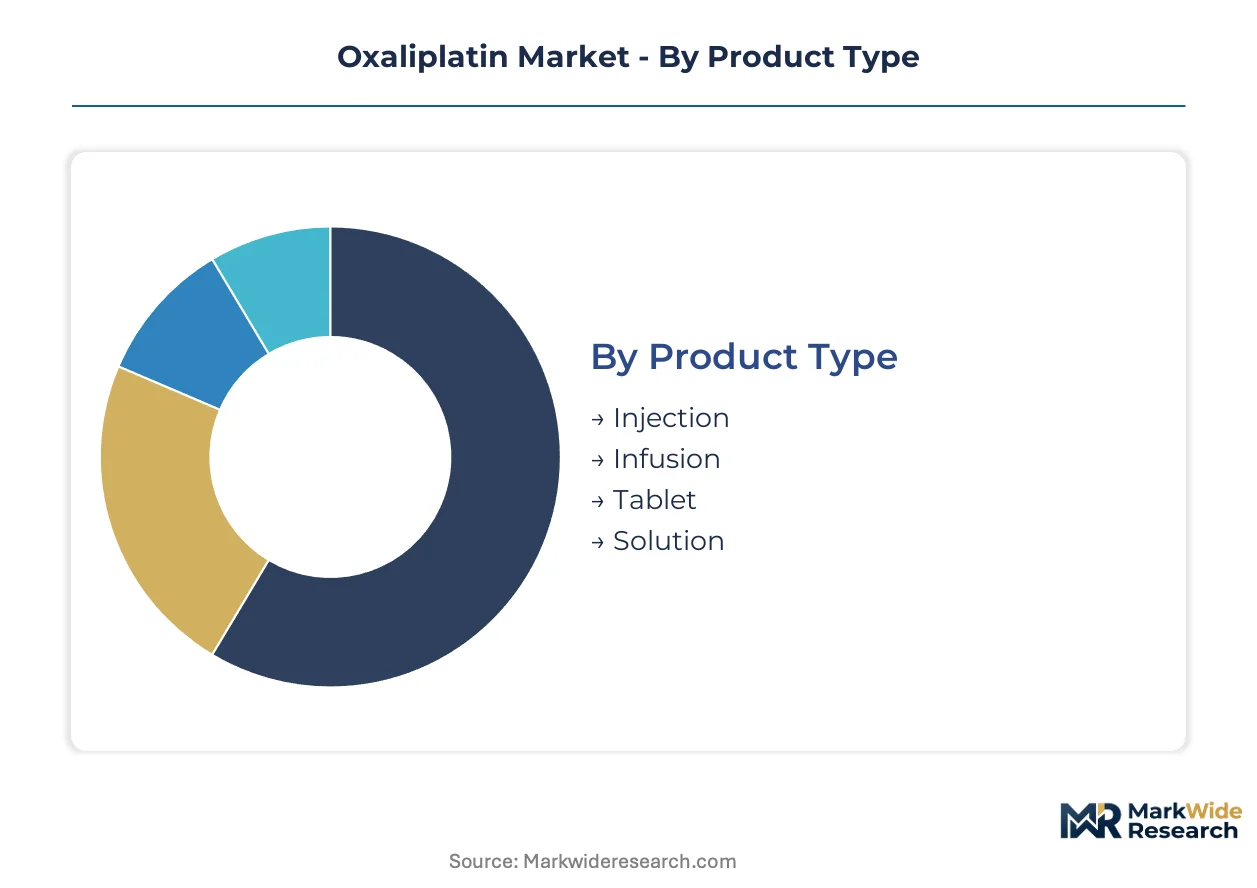
Oxaliplatin product differentiation determines cold-chain requirements, dosing precision, and site-of-care economics. Hospital procurement teams segment purchases by formulation stability and administration protocol compatibility.
Product Type:
After-sales service intensity varies sharply across formulation formats, with lyophilized powders demanding technical support for reconstitution and liquid presentations requiring cold-chain monitoring infrastructure.
- Injection:Sterile solutions at 2-5 mg/mL concentrations enable precise bolus administration in hospital infusion centers. Demand concentrates in the United States and Germany where FOLFOX protocols dominate adjuvant colorectal cancer treatment; hospital preference for single-dose vial control limits multi-dose adoption.
- Infusion:Extended-duration presentations suit outpatient cancer center expansion and same-day discharge protocols. Japan and South Korea show fastest uptake as reimbursement shifts favor ambulatory administration; this segment climbs the fastest as centers seek operational efficiency.
- Tablet:Oral solid dosage forms remain investigational for oxaliplatin due to platinum compound bioavailability challenges. Early-phase trials in Chinese research institutions explore polymer-coated formulations for gastric cancer protocols.
- Solution:Ready-to-use liquid formulations reduce pharmacy compounding burden but impose strict 2-8°C storage requirements. Indian hospital networks with unreliable cold-chain infrastructure show limited uptake despite lower unit costs.
By volume, injection leads. By growth pace, infusion is ahead.
Application:
Protocol diversification across tumor types reshapes manufacturing batch sizing and regional registration priorities for platinum cytotoxic producers.
- Colorectal Cancer:FOLFOX and CAPOX regimens anchor oxaliplatin demand in adjuvant and metastatic settings. Patient volume concentrates in reimbursed healthcare systems of the United States, Germany, and Japan; dose-limiting neurotoxicity profiles constrain long-term therapy adherence.
- Gastric Cancer:Diffuse-type adenocarcinoma prevalence in East Asian populations drives protocol expansion beyond colorectal indications. South Korean and Japanese treatment guidelines now include oxaliplatin-doublet regimens; this application expands most quickly as incidence data supports broader adoption.
- Pancreatic Cancer:Off-protocol use in gemcitabine combinations remains limited to academic medical center trials. EMA and FDA have not granted formal indications, restricting commercial volume.
- Ovarian Cancer:Platinum-sensitive relapse settings occasionally employ oxaliplatin after carboplatin resistance, though clinical trial data remains sparse compared to colorectal and gastric applications.
Colorectal cancer commands absolute patient volume. Gastric cancer applications gain share fastest in East Asian markets.
End User:
Site-of-care migration from inpatient to ambulatory settings reconfigures distribution logistics and pricing structures across customer types.
- Hospitals:Inpatient oncology wards and day surgery units administer the majority of oxaliplatin doses under protocol supervision. German and French hospital procurement consortia now consolidate purchasing across regional networks, compressing supplier negotiation cycles.
- Clinics:Outpatient cancer centers seek extended-infusion formulations to enable same-day discharge and maximize chair utilization. United States freestanding oncology clinics represent the steepest expansion trajectory as reimbursement shifts favor site-neutral payment.
- Research Institutions:Academic medical centers drive protocol innovation for gastric and pancreatic applications. Investigator-initiated trials in Japan and South Korea generate real-world evidence supporting label expansion.
- Home Care:Subcutaneous delivery research could eventually enable administration outside clinical settings, though current intravenous requirements limit this segment to investigational protocols.
Hospitals retain volume leadership. Clinics show the fastest growth as ambulatory migration accelerates.
Delivery Mode:
Administration route determines device compatibility, nursing training requirements, and patient mobility constraints across care settings.
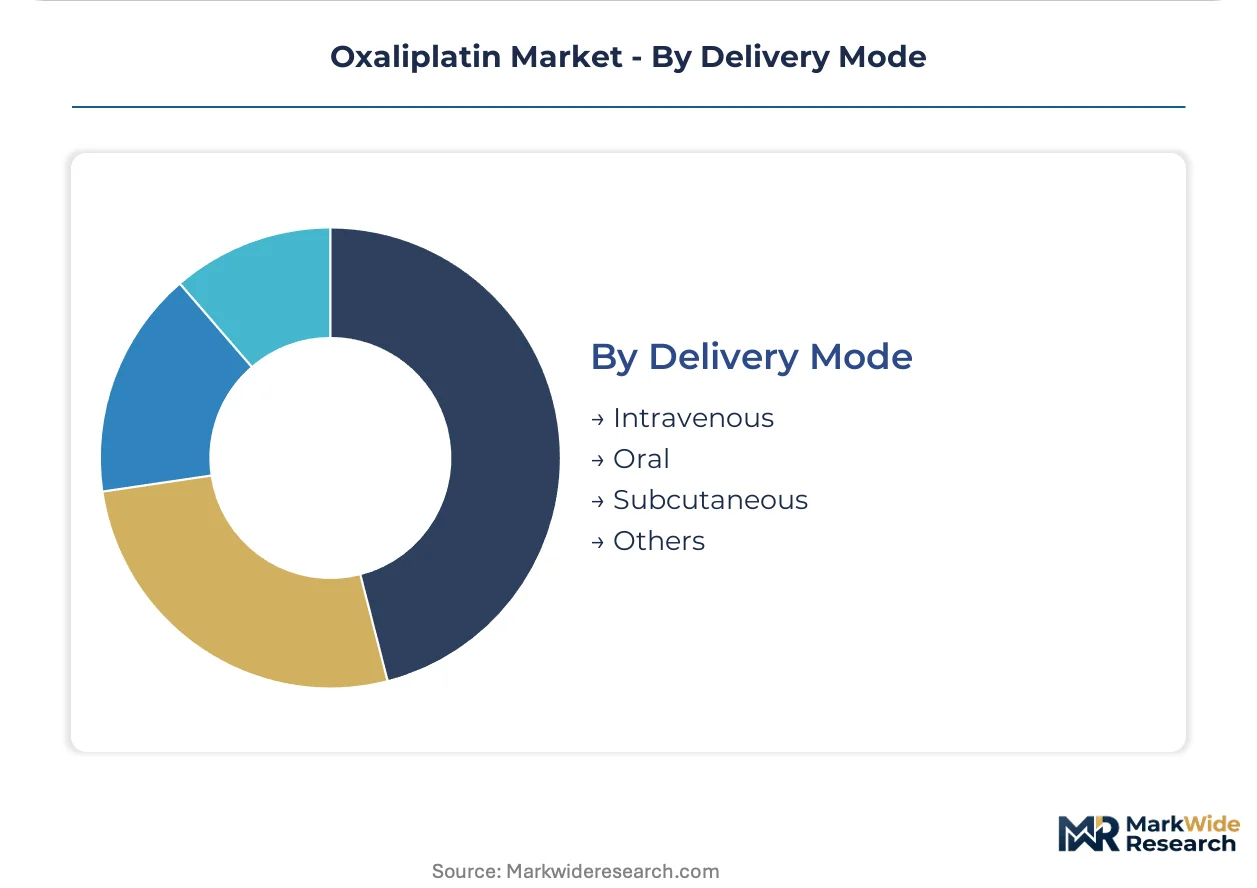
- Intravenous:Central and peripheral venous access remains standard for all approved oxaliplatin indications. Port-a-cath utilization in United States cancer centers reduces vascular complication rates and supports repeated cycle administration.
- Oral:No approved oral oxaliplatin formulations exist; polymer-encapsulation research in Chinese institutions aims to overcome platinum bioavailability barriers.
- Subcutaneous:Sustained-release depot technologies under early development could enable home administration and reduce infusion center dependency, though clinical validation remains years away.
- Others:Intraperitoneal administration for peritoneal carcinomatosis persists in select Japanese academic protocols despite limited regulatory recognition.
Intravenous delivery dominates current volume. Subcutaneous research programs target the longest-term growth potential if technical barriers resolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortia and reimbursed chemotherapy volumes concentrate demand in the United States, Germany, and Japan. These markets sustain the largest oxaliplatin treatment protocols globally.
United States
FOLFOX regimens anchor adjuvant colorectal cancer treatment at major academic medical centers. FDA bioequivalence standards for generic platinum compounds compress approval timelines while raising facility qualification costs. The Greater Boston and New York Metro clusters concentrate oncology pharmacy operations and hospital buying group headquarters.
Germany
Hospital procurement consortia now consolidate chemotherapy purchasing across regional networks, displacing individual pharmacy-level contracting. EMA good manufacturing practice harmonization streamlines cross-border facility inspections for sterile injectable producers. The Rhine-Ruhr and Bavarian hospital systems drive volume concentration through centralized oncology pharmacy operations.
Japan
Diffuse-type gastric adenocarcinoma prevalence drives protocol diversification beyond colorectal applications. PMDA regulatory pathways prioritize domestic clinical data for platinum cytotoxic approvals. The Kanto region around Tokyo anchors the largest reimbursed chemotherapy volumes, with Kansai-based academic centers advancing gastric cancer combination trials.
China
NMPA domestic preference policies accelerate local approvals for producers such as Qilu Pharmaceutical and Jiangsu Hengrui Medicine. Provincial procurement access requires joint venture structures with domestic manufacturers. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate sterile injectable production capacity and hospital network consolidation.
India
CDSCO import testing protocols delay generic entry despite lower unit cost potential for ready-to-use liquid formulations. Domestic hospital networks with unreliable cold-chain infrastructure show limited uptake of temperature-sensitive presentations. The Maharashtra and Gujarat pharmaceutical manufacturing belts concentrate sterile filling operations for export markets.
Oxaliplatin Market Competitive Environment
Channel-controlling players compete with product-specialist players across formulation and distribution vectors. The market exhibits tiered consolidation around originator heritage, vertical integration depth, and generic price aggression. Three archetypes dominate: research-origin multinationals with brand loyalty, integrated sterile injectable specialists with cost control, and emerging-market generic aggressors with volume scale. Capacity expansion and strategic partnerships constitute the dominant competitive moves as manufacturers navigate multi-jurisdiction pharmacopeial divergence.
Among research-origin multinationals, Sanofi and Pfizer occupy positions sustained by original compound heritage and hospital formulary relationships. Fresenius Kabi anchors the integrated manufacturing tier through captive supply of infusion-grade components. Teva Pharmaceutical Industries exemplifies the generic-specialist archetype competing on price across emerging markets where substitution policies accelerate volume shifts.
| Leading Market Players |
|---|
| Sanofi |
| Fresenius Kabi |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Sun Pharmaceutical Industries Ltd |
| Dr. Reddy's Laboratories Ltd. |
| Qilu Pharmaceutical Co., Ltd |
| Jiangsu Hengrui Medicine |
| Hisun Pharmaceutical |
| Others |
Value Chain & Pricing Dynamics
Platinum refining capacity clustering in South Africa and Russia positions raw material volatility as the primary margin determinant for downstream sterile injectable producers. Hospital procurement consortia in Germany and the United States exploit this concentration to extract volume-based concessions from formulation suppliers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange platinum indexation dominate long-term supply agreements between API manufacturers and finished dose producers. Three-tier pricing structure across originator brands, integrated sterile specialists, and emerging-market generics reflects certification tier and cold-chain capability differentiation. Pricing pressure stems from hospital buying group consolidation compressing negotiation cycles in the United States and Germany. Generic substitution policies in India and Brazil render emerging-market buyers most price-sensitive, while Japanese academic medical centers exhibit lowest sensitivity due to protocol loyalty and reimbursement stability.
Supply Chain Analysis
Upstream platinum sponge and potassium tetrachloroplatinate feedstock draws from South African mining operations and Russian refining complexes. Sterile filling operations hinge on isolator technology and aseptic processing equipment sourced from Germany, Switzerland, and the United States. Single-source vulnerability in platinum group metal refining exposes manufacturers to geopolitical disruption and export restriction cascades. Distribution runs through hospital procurement consortia and regional oncology pharmacy networks, with direct-to-hospital models bypassing wholesale cold-chain requirements for lyophilized presentations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs oxaliplatin competitive dynamics as EMA isolator mandates and FDA bioequivalence standards create interoperability barriers that favor scaled sterile infrastructure over boutique formulation plays.
For Market Incumbents: Harden isolator-based filling line investments ahead of EMA mandatory upgrade timelines to forestall forced market withdrawal. Deepen backward integration into platinum compound API production to offset raw material volatility exposure from South African and Russian supply concentration. Secure multi-site distribution capabilities to satisfy hospital buying group consolidation in the United States and Germany.
For New Entrants and Emerging Players: Pursue CDSCO import testing reform advocacy to unlock streamlined generic approval pathways for qualified sterile injectable producers. Target Indian hospital networks with unreliable cold-chain infrastructure through lyophilized powder formulations that bypass temperature-controlled distribution requirements. Anchor market entry through joint venture structures with domestic Chinese manufacturers to secure NMPA priority review status and provincial procurement access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sterile injectable specialists possessing isolator technology but lacking geographic diversification beyond European manufacturing footprints. Long-term viability across the projection horizon rests on regulatory compliance moats rather than patent exclusivity, favoring acquisition targets with multi-jurisdiction pharmacopeial validation capabilities. Watch EMA sterile manufacturing guideline revision timing as the inflection signal for mandatory facility upgrade capital deployment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Upgrade | EMA mandates isolator-based filling lines for all new platinum cytotoxic approvals, forcing legacy facility obsolescence. |
| Backward Integration into Platinum API | Captive supply of platinum compounds insulates margin pools from South African and Russian refining volatility. |
| Lyophilized Formulation Migration | Solid-state presentations enable direct-to-hospital distribution bypassing wholesale cold-chain infrastructure. |
| Joint Venture with Chinese Domestic Producer | NMPA domestic preference policies unlock priority review status and provincial procurement consortium access. |
| Multi-Site Distribution Network Expansion | Hospital buying group consolidation in the United States and Germany demands suppliers with regional pharmacy coverage. |
Study Parameters
A spread of perspectives from oncology pharmacy directors, sterile manufacturing operations heads, regulatory affairs leads at platinum compound producers, and hospital procurement consortium managers converged on the working assumptions. Primary field engagement combined with secondary validation from FDA bioequivalence guidance documents, EMA good manufacturing practice inspection reports, CDSCO import testing protocols, and NMPA domestic preference policy circulars. Bottom-up patient volume modeling across colorectal and gastric cancer treatment protocols triangulated against top-down manufacturer capacity disclosures.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning formulation type, administration protocol, tumor indication, and regional regulatory cluster. CAGRs derived from treatment protocol expansion rates, reimbursement policy trajectories, and manufacturing capacity addition schedules. Industry-specific forecast inputs incorporated PMDA gastric cancer guideline revision timing and EMA isolator mandate phase-in schedules.
Macroeconomic conditions sit as an overlay; deviation in platinum group metal pricing, healthcare reimbursement austerity measures, or geopolitical export restrictions would shift the trajectory. Cross-checking against hospital procurement database contract awards and GPO chemotherapy purchasing volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
Global Seasonal Affective Disorder Therapeutics Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Metformin Hydrochloride Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Antibody Therapy Market