
 Metformin HCL Drugs Market | 2026-2036
Metformin HCL Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Metformin HCL Drugs Market Insights
Hospital procurement channels is tilting toward consolidated tendering for metformin HCL, pressuring smaller distributors to cede shelf space. Lupin Pharmaceuticals leverages its Indian manufacturing base to supply regulated markets at scale. Sun Pharmaceutical Industries anchors its position through backward integration into active pharmaceutical ingredient production. Teva Pharmaceutical Industries competes on cost discipline across European and North American tender systems.
Metformin hydrochloride is a biguanide-class oral antihyperglycemic agent with the molecular formula C4H11N5·HCl, synthesized through dimethylamine and cyanoguanidine condensation followed by acidification. The compound suppresses hepatic gluconeogenesis and enhances peripheral insulin sensitivity, serving as first-line pharmacotherapy for type 2 diabetes mellitus. Extended-release tablets command attention for improved gastrointestinal tolerability and once-daily adherence profiles, while 500 mg and 1000 mg dosages dominate volume due to physician familiarity and payer preference for stepwise titration. Type 2 diabetes indication absorbs the preponderance of production capacity, though polycystic ovary syndrome represents a faster-growing off-label utilization corridor.
FDA bioequivalence requirements under 21 CFR 320 govern abbreviated new drug application approvals for generic metformin, while EMA good manufacturing practice inspections shape facility qualification across European supply chains. India's CDSCO mandates manufacturing licenses and batch release protocols that filter substandard entrants from export channels. Stakeholders must monitor evolving pharmacopeial standards for dissolution testing and impurity profiling, as regulatory stringency determines which manufacturers retain market access.
Market Dynamics
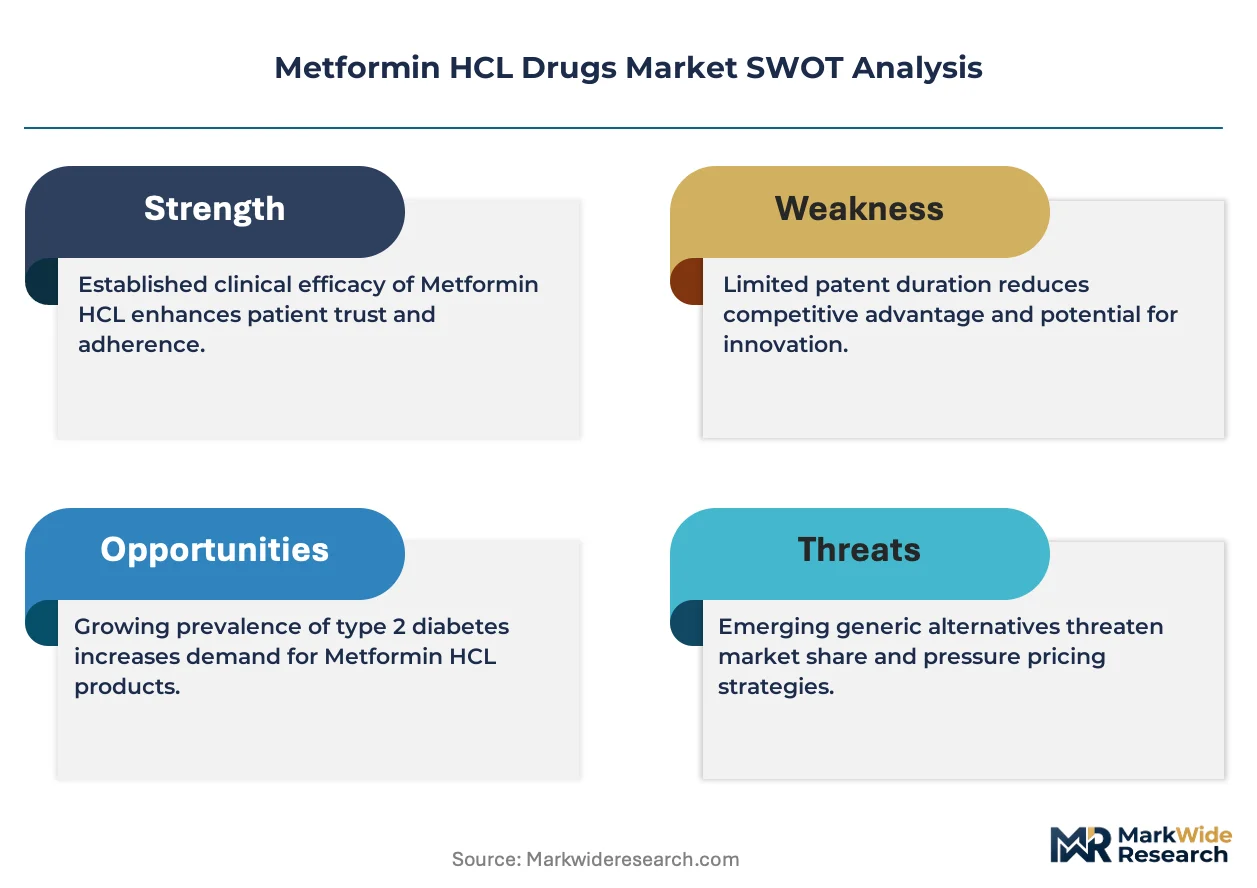
Consolidated hospital tendering across regulated markets is compressing distributor margins and forcing API-integrated manufacturers to absorb price compression through captive supply chains.
Growth Catalysts
- Extended-Release Formulation Preference:Once-daily dosing protocols improve adherence metrics for type 2 diabetes patients, expanding prescriber comfort with stepwise titration regimens.
- EMA GMP Inspection Harmonization:Standardized facility qualification across European supply chains accelerates cross-border generic approvals for compliant manufacturers.
- India API Export Scale:Dimethylamine and cyanoguanidine condensation capacity expansion lowers input costs for formulation exporters serving regulated markets.
Market Restraints
- Impurity Profiling Stringency:FDA dissolution testing thresholds under 21 CFR 320 block substandard generic entrants from abbreviated new drug application pathways.
- Single-Geography API Concentration:Dimethylamine supply chain clustering in Gujarat and Hyderabad creates vulnerability to regional logistics disruptions.
- GLP-1 Agonist Substitution:Semaglutide and tirzepatide uptake among endocrinologists threatens first-line metformin positioning for newly diagnosed patients.
Strategic Opportunities
- Polycystic Ovary Syndrome Off-Label Corridor:Gynecology practices in the United States and Germany are expanding hydrochloride prescriptions beyond diabetes indications.
- CDSCO Export License Streamlining:India's batch release protocol simplification filters non-compliant manufacturers, creating shelf space for quality-accredited exporters.
- Continuous Manufacturing Adoption:Direct compression and roller compaction technologies converge to reduce batch-to-batch variability in extended-release tablet production.
Industry Challenges
- Pharmacopeial Dissolution Method Harmonization:Divergent USP and EP testing protocols force manufacturers to maintain dual validation datasets for transatlantic shipments.
- Legacy Quality Management System Migration:Paper-based batch records at mid-scale Indian facilities require capital-intensive digitization to meet EMA inspection readiness standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metformin HCL Drugs Market |
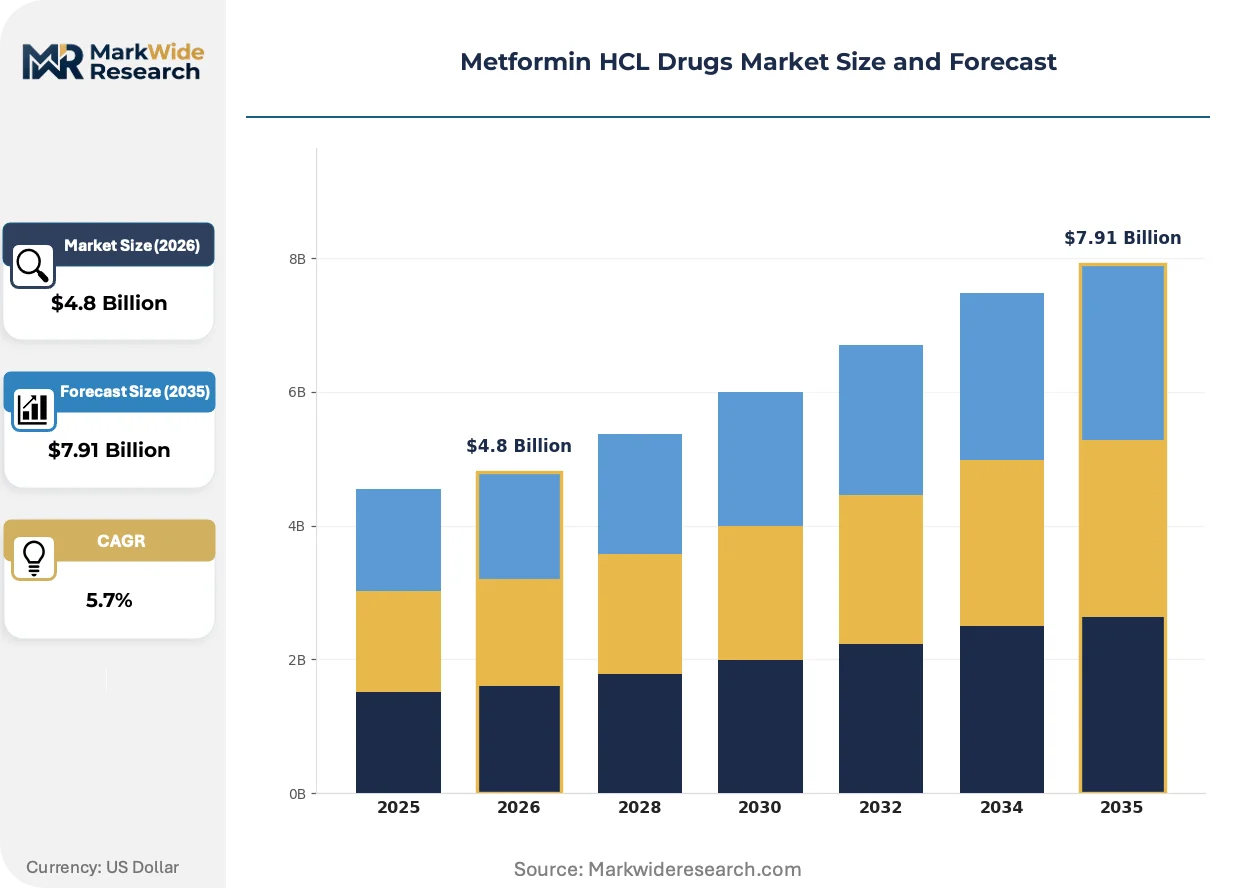
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Form: Tablet, Liquid, Extended Release, Powder Dosage: 500 mg, 850 mg, 1000 mg, 2000 mg Indication: Type 2 Diabetes, Polycystic Ovary Syndrome, Weight Management, Hyperglycemia Administration Route: Oral, Intravenous, Subcutaneous, Rectal |
| Companies Covered | Shouguang Fukang Pharmaceutical, CR Double-Crane, Lupin Pharmaceuticals, Sun Pharmaceutical Industries, Teva Pharmaceutical Industries, Aurobindo Pharma, USV, Vistin Pharma, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metformin HCL Drugs Market Trends and Innovations
Process analytical technology and real-time release testing are compressing quality assurance timelines, while regulatory data integrity mandates force legacy facility upgrades.
Continuous direct compression is virtualizing batch manufacturing for metformin hydrochloride tablets. European generics manufacturers adopting this technology achieve tighter dissolution profile control. The shift is compressing facility footprint requirements and enabling modular production lines that reconfigure across dosage strengths.
REACH authorization requirements for dimethylamine intermediates are tightening supply chain documentation obligations. ECHA substance evaluation protocols now extend to API starting materials, forcing Indian exporters to upgrade supplier qualification systems. German and French formulation facilities are absorbing compliance costs through long-term API supply contracts.
Hospital procurement consortia in Italy and Spain are consolidating annual metformin volumes into single-tender awards. Distributor networks that previously served fragmented regional health systems face disintermediation as manufacturers bid directly for multi-year framework agreements. This pattern concentrates volume with API-backward-integrated suppliers capable of absorbing payment term extension.
Metformin HCL Drugs Market Segmentation
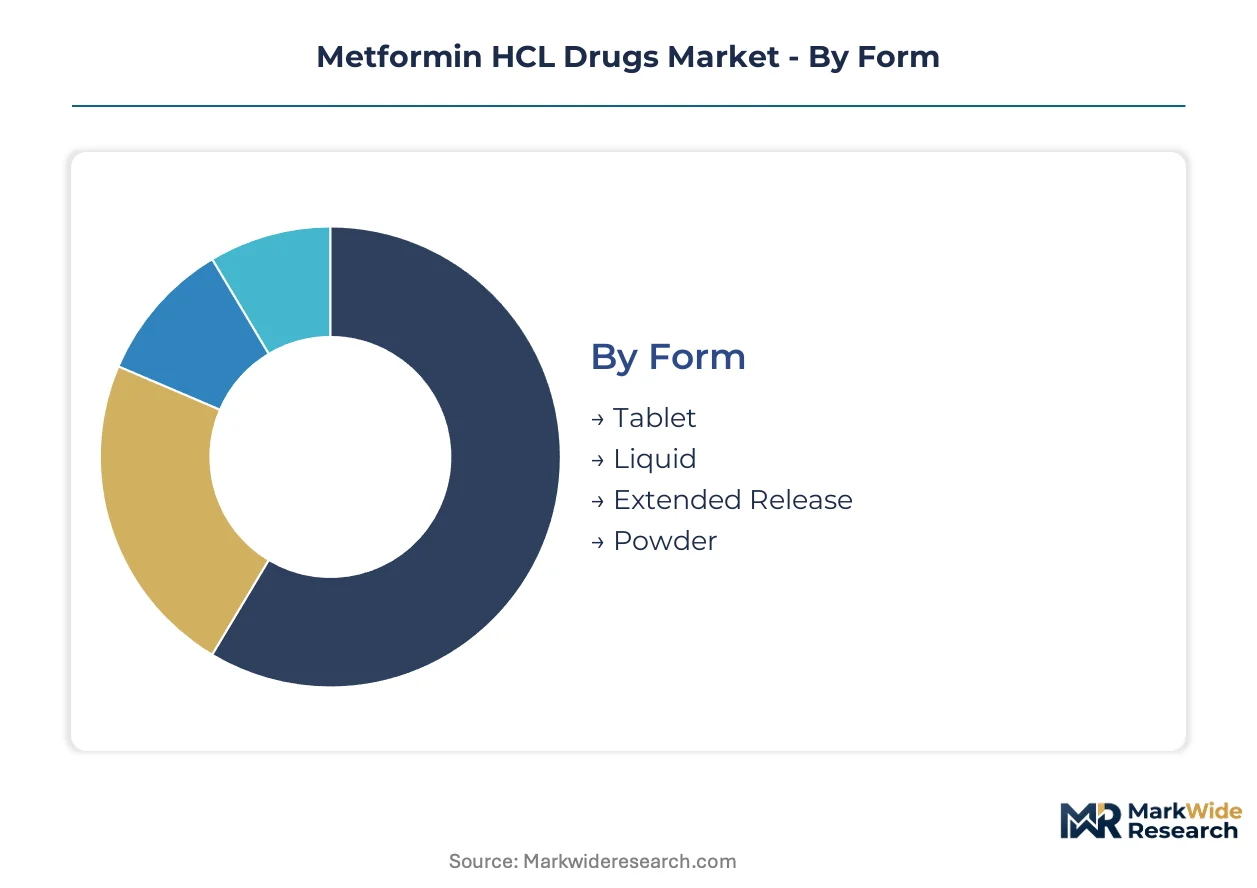
Metformin HCL formulation diversity spans immediate-release tablets, extended-release matrices, and liquid suspensions, each commanding distinct manufacturing investments and regulatory pathways. Segmentation by dosage strength, therapeutic indication, and administration route determines pricing architecture and channel access across hospital, retail, and specialty pharmacy networks.
Form:
Oral solid and liquid formats serve divergent patient populations across the use-case spectrum, from chronic maintenance to acute titration protocols.
- Extended Release:Matrix-formulation tablets employing hydroxypropyl methylcellulose or polyacrylic acid enable zero-order drug release kinetics. German hospital procurement consortia favor this format for reduced nursing burden and improved HbA1c adherence metrics in elderly populations.
- Tablet:Immediate-release compressed dosage forms dominate volume through cost-efficient direct compression manufacturing. Indian CDSCO-licensed facilities supply 500 mg and 850 mg strengths to regulated markets at scale.
- Liquid:Aqueous suspensions address pediatric and geriatric populations with dysphagia. The format requires preservative systems and unit-dose packaging that elevates per-dose cost versus solid alternatives.
- Powder:Bulk active pharmaceutical ingredient for extemporaneous compounding and clinical trial supply. Compounding pharmacies in the United States absorb volumes for customized strength preparation.
Established volume favors Tablet; emerging adoption favors Extended Release.
Dosage:
Strength stratification aligns with titration protocols and payer step-therapy requirements across cost tiers.
- 500 mg:Initiation strength for insulin-naive patients and renal impairment risk mitigation. Physician familiarity and generic substitution laws in the United States sustain volume concentration at this tier.
- 1000 mg:Maintenance strength achieving therapeutic efficacy with minimized pill burden. European tender systems prioritize this strength for consolidated hospital procurement awards.
- 850 mg:Intermediate titration step common in European prescribing guidelines. The strength occupies a narrower commercial niche between initiation and maintenance protocols.
- 2000 mg:Maximum labeled daily dose for refractory hyperglycemia. Gastrointestinal tolerability limits real-world utilization despite guideline endorsement.
Physician prescribing patterns concentrate on 500 mg and 1000 mg; 2000 mg encounters adherence barriers from tolerability constraints.
Indication:
Therapeutic application scope spans endocrinology, gynecology, and metabolic medicine, with regulatory labeling determining reimbursement access.
- Type 2 Diabetes:First-line pharmacotherapy per ADA and EASD consensus algorithms. The indication absorbs manufacturing capacity through chronic daily dosing requirements and population prevalence expansion.
- Polycystic Ovary Syndrome:Off-label utilization for insulin resistance and androgen modulation in reproductive-age women. Gynecology practices in Germany and the United States are expanding prescriptions fastest.
- Hyperglycemia:Acute and stress-induced glucose elevation management in hospitalized settings. ICU and step-down units employ intravenous formulations for perioperative glycemic control.
- Weight Management:Adjunctive therapy for metabolic syndrome and pre-diabetes populations. GLP-1 agonist competition constrains standalone metformin positioning in this corridor.
Type 2 Diabetes anchors manufacturing scale; Polycystic Ovary Syndrome represents the steepest expansion trajectory.
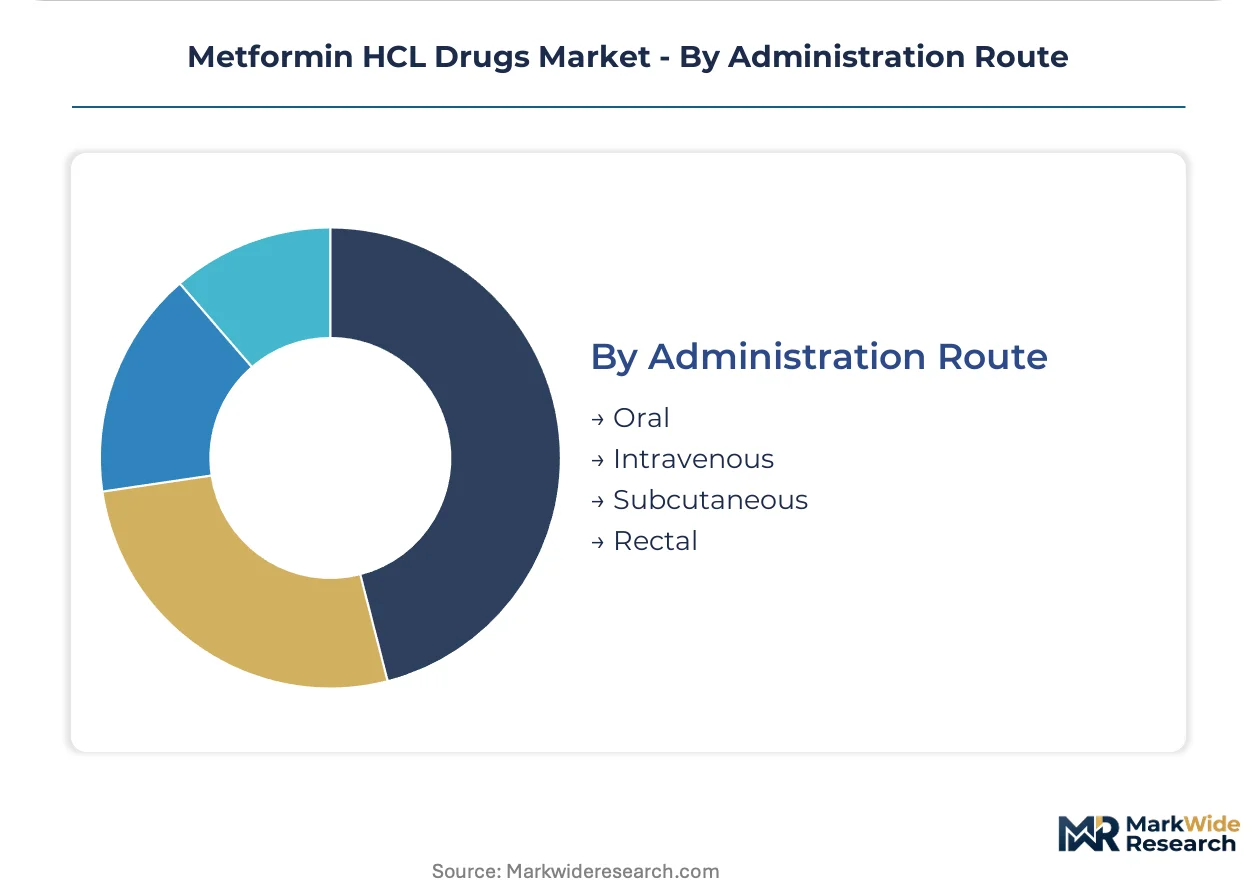
Administration Route:
Delivery modality selection reflects patient acuity, compliance capacity, and care setting infrastructure.
- Oral:Peroral absorption through intestinal epithelial transporters enables outpatient self-administration. The route dominates through convenience and decades of clinical familiarity.
- Intravenous:Parenteral formulation for perioperative and NPO-status patients requiring glycemic control. Hospital pharmacy compounding services manage preparation and stability protocols.
- Subcutaneous:Investigational and compounded delivery formats for bioavailability enhancement research. Limited commercial presence outside specialized metabolic clinics.
- Rectal:Suppository formulations for vomiting or upper GI obstruction scenarios. Niche utilization in palliative care and emergency medicine settings.
Oral administration commands manufacturing investment; Intravenous serves critical care infrastructure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany commands premium tender awards while Indian exporters absorb margin compression through captive API supply. Hospital procurement consortia in Milan and Madrid consolidate volumes into multi-year frameworks that disintermediate regional distributors. Manufacturing gravity clusters around Gujarat and Hyderabad for dimethylamine feedstock, with formulation finishing scaling across regulated markets.
United States
FDA 21 CFR 320 bioequivalence standards filter substandard generic entrants from abbreviated new drug application pathways. Medicare Part D step-therapy protocols sustain 500 mg and 1000 mg volume concentration through physician familiarity. New Jersey and North Carolina host formulation facilities supplying hospital procurement consortia across the Northeast corridor.
Germany
EMA good manufacturing practice inspections shape facility qualification standards that accelerate cross-border generic approvals for compliant manufacturers. Hospital procurement consortia in Bavaria and North Rhine-Westphalia consolidate annual metformin volumes into single-tender awards favoring extended-release matrices. Düsseldorf and Frankfurt anchor distribution networks serving centralized pharmacy operations.
India
CDSCO manufacturing licenses and batch release protocols filter non-compliant manufacturers from export channels serving regulated markets. Dimethylamine and cyanoguanidine condensation capacity expansion in Gujarat and Hyderabad lowers input costs for formulation exporters. Mumbai and Ahmedabad host backward-integrated suppliers capable of absorbing payment term extensions in European tender systems.
China
NMPA good manufacturing practice certification requirements align domestic production standards with international pharmacopeial dissolution testing protocols. Shouguang and Shandong Province concentrate active pharmaceutical ingredient synthesis for both domestic consumption and export processing. Beijing and Shanghai coordinate regulatory harmonization efforts with EMA and FDA inspection readiness programs.
Switzerland
Swissmedic manufacturing authorization protocols enforce stringent impurity profiling standards that preserve premium positioning for quality-accredited suppliers. Basel and Zurich anchor formulation science capabilities serving specialized metabolic medicine channels. The country's pharmacopeial leadership influences dissolution method harmonization debates between USP and EP testing protocols.
Metformin HCL Drugs Market Competitive Landscape
API-integrated manufacturers and pure-play formulation specialists split the market along supply chain control lines. Hospital tender consolidation favors suppliers with captive dimethylamine production capable of absorbing price compression. Three archetypes dominate: Indian backward-integrated exporters, European quality-accredited specialists, and Israeli cost-disciplined generic multinationals. Capacity expansion and regulatory compliance digitization constitute the dominant competitive moves as EMA inspection readiness standards tighten.
Among Indian backward-integrated suppliers, Lupin Pharmaceuticals and Sun Pharmaceutical Industries exemplify the archetype of API-captive exporters serving regulated markets at scale. Teva Pharmaceutical Industries occupies a position within the cost-disciplined multinational tier, competing across European and North American tender systems through manufacturing efficiency. These three anchors demonstrate how geographic clustering around Gujarat and Hyderabad combines with regulatory compliance investment to secure hospital procurement awards.
| Leading Market Players |
|---|
| Shouguang Fukang Pharmaceutical |
| CR Double-Crane |
| Lupin Pharmaceuticals |
| Sun Pharmaceutical Industries |
| Teva Pharmaceutical Industries |
| Aurobindo Pharma |
| USV |
| Vistin Pharma |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Gujarat and Hyderabad dimethylamine condensation facilities is compressing supplier margins while simultaneously enabling aggressive pricing postures for formulation exporters serving European tender systems. This utilization dynamic rewards backward-integrated manufacturers with captive API production, forcing pure-play formulators to absorb cost compression or exit hospital procurement channels.
Pricing Analysis
The customization-premium spread between standard immediate-release tablets and extended-release matrices with modified dissolution profiles separates economy-tier Indian exporters from quality-accredited European specialists. Pricing stratifies across premium, standard, and economy tiers based on EMA inspection readiness certification and volume scale commitments in multi-year framework agreements. Cost compression in the economy tier is intensifying because consolidated hospital tendering in Germany and Italy forces distributors to disintermediate or absorb payment term extensions. Generic substitution laws in the United States make retail pharmacies most price-sensitive, while hospital procurement consortia in Bavaria prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Single-geography API concentration in India and China dominates upstream exposure for dimethylamine and cyanoguanidine feedstocks. Formulation manufacturing draws from these inputs while facing tariff exposure between Asian API exporters and European finished-dose importers under evolving REACH authorization protocols. Distribution runs through hospital procurement consortia in Germany, Italy, and Spain that consolidate annual volumes into direct manufacturer awards, disintermediating regional distributor networks previously serving fragmented health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metformin HCL market is approaching a platform-economics inflection as continuous manufacturing technologies and real-time release testing protocols create interoperability standards that favor API-integrated suppliers with digitized quality management systems.
For Market Incumbents: Build regulatory moats through EMA inspection readiness digitization and USP-EP dissolution method harmonization investments. Sun Pharmaceutical Industries and Lupin Pharmaceuticals should deepen backward integration into dimethylamine production in Gujarat to absorb GLP-1 agonist substitution threats through cost discipline. Captive API supply chains and continuous direct compression adoption constitute the essential defensive lever for retaining hospital tender awards.
For New Entrants and Emerging Players: Build out polycystic ovary syndrome off-label corridors in gynecology practices across Germany and the United States, where prescriber familiarity with insulin-sensitizing therapy remains underpenetrated relative to diabetes indications. Liquid suspension formats for pediatric and geriatric dysphagia populations represent the most penetrable segment, with unit-dose packaging partnerships offering a credible go-to-market angle against incumbent solid-dose dominance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among API-backward-integrated manufacturers with CDSCO export licenses and EMA-qualified facilities serving multi-year hospital framework agreements. Long-term viability over the coming decade hinges on continuous manufacturing adoption and pharmacopeial standard-setting influence. The acquisition target archetype combines Indian API production with European formulation finishing capabilities. Watch for FDA dissolution testing threshold revisions as the critical inflection signal for quality-accredited supplier repricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Roller compaction and direct compression technologies reduce batch-to-batch variability for extended-release matrices. |
| EMA GMP Inspection Readiness | Digitized quality management systems at Indian facilities accelerate cross-border generic approval timelines. |
| API Backward Integration | Captive dimethylamine production in Gujarat lowers input costs for formulation exporters serving regulated markets. |
| Polycystic Ovary Syndrome Expansion | Gynecology practice partnerships in Germany and the United States open off-label utilization corridors beyond diabetes. |
| Pharmacopeial Harmonization Investment | Dual USP-EP dissolution validation datasets enable seamless transatlantic shipment without batch segregation. |
Research Methodology
Desk research of FDA ANDA filings, EMA inspection reports, and CDSCO manufacturing license databases preceded structured interviews with regulatory affairs leads at Indian API exporters, hospital procurement managers in German and Italian consortia, and formulary directors at European health systems. Secondary validation drew from pharmacopeial dissolution testing protocols, REACH authorization documentation, and customs trade data for dimethylamine feedstock flows. Bottom-up volume modeling triangulated against top-down therapeutic class expenditure estimates.
Assumptions held fixed across the modeling period include EMA GMP inspection stringency trajectories and ADA/EASD guideline positioning of metformin as first-line therapy. The analytical framework segmented by dosage form, therapeutic indication, administration route, and regional regulatory cluster. CAGRs derived from patient population prevalence projections, generic substitution law enforcement patterns, and hospital procurement consolidation trends. Forecast inputs incorporated GLP-1 agonist substitution elasticity and extended-release formulation preference shifts.
Practitioners should monitor FDA bioequivalence threshold revisions, EMA inspection frequency changes, and GLP-1 agonist formulary positioning for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Cough and Cold Preparations Market
Pharmaceuticals
Anti-Viral Therapeutics Market
Pharmaceuticals
Angiogenesis Inhibitors and Stimulators Market
Pharmaceuticals
Cefazedone Sodium Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Europe Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Parenteral Drugs Market
Pharmaceuticals
Novel Drug Delivery Systems in Cancer Therapy Market
Pharmaceuticals
Clozapine Market
Pharmaceuticals
Trenbolone Enanthate Market
Pharmaceuticals
Global Esketamine Market
Pharmaceuticals
Short-Acting Insulin Market