
 Global HPMC Capsules Market | 2026-2036
Global HPMC Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Global HPMC Capsules Market Foresight
Pharmaceutical polymer chemistry expertise is rotating toward plant-derived excipient platforms as gelatin supply volatility and religious dietary restrictions reshape capsule procurement. Lonza (Capsugel) leverages its integrated capsule-portfolio infrastructure to sustain leadership across multiple release-technology platforms. ACG Associated Capsules anchors South Asian supply through backward integration into HPMC raw material streams. Suheung Co. Ltd. dominates Korean export channels with specialized enteric-coating capabilities.
Hydroxypropyl methylcellulose capsules consist of cellulose ether polymers derived from purified wood pulp or cotton linter, formed through dipping-pin technology into aqueous HPMC solutions that gel upon thermal setting, yielding two-piece shells with oxygen permeability below gelatin equivalents. Their primary purpose centers on protecting hygroscopic and acid-labile actives from moisture ingress and gastric degradation. Delayed-release HPMC variants command premium positioning as biopharma pipelines expand peptide and probiotic formulations. Dietary supplement applications sustain the largest volume footprint, though veterinary nutrition channels are gaining traction as pet humanization trends intensify.
FDA dissolution standards, EMA stability guidelines, and USP-NF monographs collectively define capsule performance benchmarks that determine market access for new suppliers. Japan's PMDA enforces additional local disintegration-time specifications that filter entrants without regional testing infrastructure. Stakeholders must monitor evolving pharmacopeial harmonization between ICH regions, as divergent dissolution-method requirements threaten to fragment formulation strategies and duplicate validation costs.
Market Dynamics
Pharmacopeial harmonization pressures are compressing formulation timelines as manufacturers reconcile divergent dissolution standards across FDA, EMA, and PMDA jurisdictions.
Growth Catalysts
- Biologics moisture protection:Peptide and probiotic pipelines require oxygen-barrier shells that gelatin cannot provide, pulling HPMC into parenteral-adjacent oral delivery systems.
- Religious dietary compliance:Halal and kosher certification gaps in bovine/porcine gelatin supply chains are rotating procurement toward plant-derived alternatives in Middle Eastern and Israeli markets.
- EMA stability guidelines:Tightened ICH Q1A(R2) interpretations for hygroscopic actives are mandating HPMC qualification for new molecular entity filings in European markets.
Market Restraints
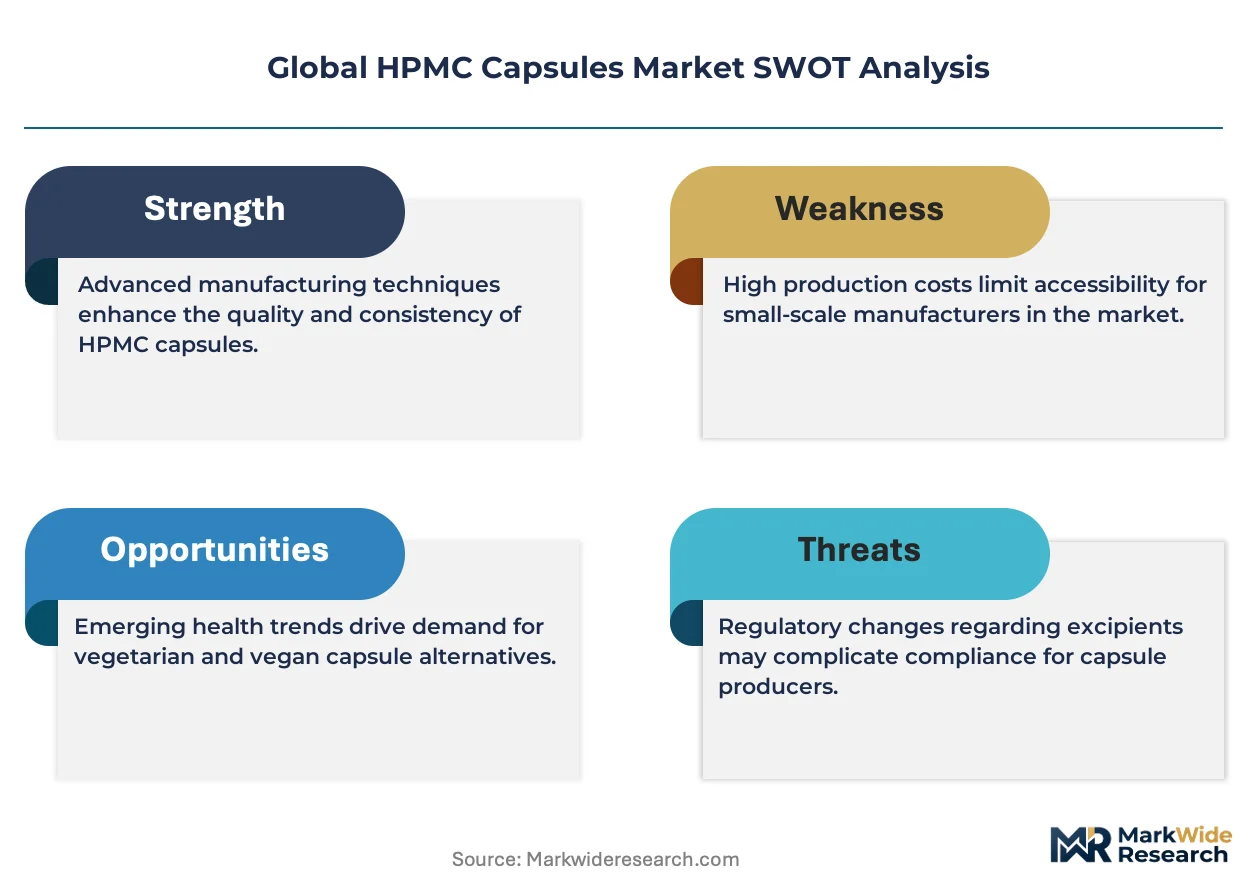
- Wood pulp input volatility:Purified cellulose ether feedstock costs fluctuate with Nordic and North American timber harvest cycles, squeezing margin structures for non-integrated manufacturers.
- Korean supply concentration:Specialized enteric-coating capabilities cluster around Suheung and limited regional competitors, creating single-source risk for delayed-release formulations.
- Gelatin price competitiveness:Bovine bone-derived alternatives retain cost advantages for non-sensitive actives, capping HPMC penetration in commoditized vitamin segments.
Strategic Opportunities
- Veterinary nutrition expansion:Pet humanization trends in the US and Western Europe are opening companion animal supplement channels that prioritize clean-label, plant-based excipient narratives.
- India contract manufacturing scale:CDMO investments in Hyderabad and Ahmedabad clusters are creating captive demand for HPMC shells serving EU and US export registrations.
- Dual carbon alignment:China's SAMR green procurement incentives and EU CSRD reporting requirements are favoring cellulose-based capsules over animal-derived alternatives in sustainability-scored tenders.
Industry Challenges
- Dissolution method validation:Reconciling USP-NF apparatus specifications with PMDA's local disintegration-time protocols demands redundant testing infrastructure for multi-regional filings.
- Pin-dipping equipment capex:Thermal gelation production lines require specialized dipping-pin arrays with 18-24 month lead times, constraining rapid capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HPMC Capsules Market |
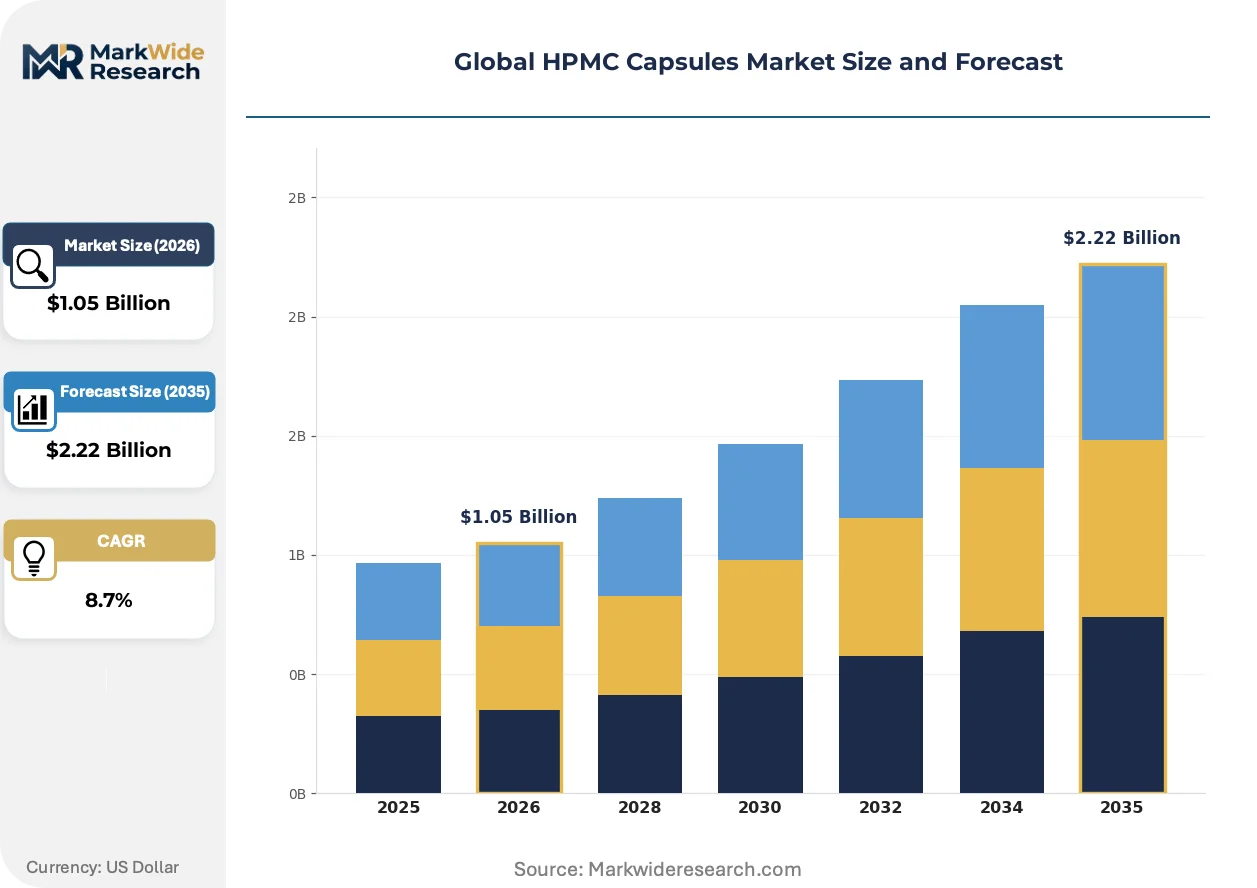
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.22 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard HPMC, Delayed Release, Enteric Coated, Gelatin-Free, Extended Release Application: Dietary Supplements, Veterinary Medicine, Veterinary Nutrition, Cosmetics, Functional Food End User: Contract Manufacturers, Nutraceutical Companies, Animal Health Providers, Cosmetic Producers, Food Manufacturers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesale Suppliers, Pharmacies |
| Companies Covered | CapsCanada Corporation, Natural Capsules Ltd., Lonza (Capsugel), Zhejiang Yuexi Capsule Co., Ltd., Sunil Healthcare, Qualicaps LLC, Suheung Co. Ltd., Shionogi Qualicaps, ACG Associated Capsules, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HPMC Capsules Market Shifts & Advancements
Formulation science is converging with materials engineering as capsule performance becomes a definitional variable in biologic stability rather than a passive containment choice.
Hypromellose acetate succinate (HPMC-AS) is decomposing the traditional enteric-coating workflow by integrating acid resistance directly into the capsule shell matrix. Biopharma formulators targeting duodenal release for peptide therapies are adopting HPMC-AS at accelerated qualification timelines. This polymer architecture is decomposing the separate coating step that previously added 15-20% to total manufacturing cost for gastric-resistant products.
REACH Annex XIV authorization requirements for residual monomers in cellulose ethers are tightening impurity thresholds for European market access. Manufacturers must demonstrate sub-ppm levels of propylene oxide and methyl chloride residues through enhanced purification protocols. CDMOs serving EMA filings are responding by qualifying dual-source HPMC raw material streams with documented supply chain transparency.
Direct-to-consumer nutraceutical brands are compressing capsule specification cycles from 24 months to 8-12 months through modular formulation platforms. These buyers now demand rapid shell customization for limited-run SKUs rather than committing to multi-year supply agreements. The US and German markets exhibit the most pronounced acceleration, where influencer-driven supplement launches prioritize speed-to-shelf over traditional pharmaceutical-grade validation depth.
Global HPMC Capsules Market Segmentation
Regulatory differentiation across FDA, EMA, and PMDA jurisdictions fragments formulation requirements by product type and application. Segmentation strategy determines qualification costs, supply chain configuration, and access to high-margin therapeutic categories.
Product Type:
EMA stability guidelines and USP-NF dissolution standards create tiered compliance burdens that reshape procurement priorities across shell variants.
- Standard HPMC:Two-piece shells formed through thermal gelation of aqueous HPMC solutions serve moisture-sensitive small molecules and generic oral solids. Demand concentrates in Indian CDMO clusters supplying EU export registrations, driven by cost-conscious procurement for non-enteric formulations.
- Delayed Release:Engineered disintegration profiles protect acid-labile actives through pH-dependent erosion mechanisms rather than separate coating steps. Biopharma peptide pipelines in the US and Germany are accelerating qualification timelines for duodenal-release applications.
- Enteric Coated:Dual-layer architecture integrates acid-resistant polymers into shell matrices for gastric bypass.
- Gelatin-Free:Purified cellulose ether construction eliminates bovine/porcine sourcing for religious dietary compliance.
- Extended Release:Modified HPMC viscosity grades enable zero-order release kinetics for chronic disease therapies.
Established volume favors Standard HPMC; emerging adoption favors Delayed Release.
Application:
Customer risk tolerance and validation depth separate pharmaceutical-grade from consumer-grade demand pools.
- Dietary Supplements:Modular formulation platforms compress specification cycles from 24 months to 8-12 months for direct-to-consumer brands. US and German influencer-driven launches prioritize speed-to-shelf over traditional validation depth.
- Veterinary Medicine:Companion animal therapeutics require batch-level traceability equivalent to human pharmaceuticals. Pet humanization trends in the US and Western Europe are rotating procurement toward plant-based excipient narratives.
- Veterinary Nutrition:Clean-label positioning drives premium positioning in functional pet supplements.
- Cosmetics:Encapsulation of sensitive actives demands oxygen-barrier properties for shelf stability.
- Functional Food:Probiotic protection requires moisture-resistant shell architecture for ambient distribution.
Volume concentrates in Dietary Supplements; margin expansion concentrates in Veterinary Medicine.
End User:
Backward integration depth and regulatory filing sophistication determine supplier relationship structures.
- Contract Manufacturers:Hyderabad and Ahmedabad CDMO clusters create captive demand for HPMC shells serving multi-regional filings. Dual-source raw material qualification is becoming mandatory for EMA stability submissions.
- Nutraceutical Companies:Rapid SKU customization requirements favor flexible supply agreements over multi-year commitments.
- Animal Health Providers:Veterinary pharmaceutical standards mirror human-grade validation for companion animal therapeutics.
- Cosmetic Producers:Shelf-life extension drives oxygen-permeability specifications for sensitive actives.
- Food Manufacturers:Probiotic viability protection requires moisture-barrier performance in ambient supply chains.
Procurement scale favors Contract Manufacturers; specification flexibility favors Nutraceutical Companies.
Distribution Channel:
Lead time compression and technical service intensity fragment channel economics across customer segments.
- Direct Sales:Technical specification support and custom shell development for pharmaceutical filings. Lonza and ACG deploy field formulation scientists to accelerate qualification timelines for delayed-release programs.
- Distributors:Inventory pooling reduces working capital burdens for mid-tier nutraceutical brands.
- Online Retail:Small-batch procurement for limited-run supplement launches and rapid market testing.
- Wholesale Suppliers:Volume aggregation for standard-grade HPMC in commoditized vitamin applications.
- Pharmacies:Compounding pharmacy channels for personalized medicine and specialized release profiles.
Technical complexity favors Direct Sales; cost efficiency favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: pharmaceutical-grade demand dominates US and German procurement, while India and China concentrate volume in dietary supplement and contract manufacturing channels. Religious dietary compliance and biologics moisture protection pull HPMC into distinct use-cases across these markets.
United States
FDA dissolution standards and biopharma peptide pipelines drive premium-grade HPMC adoption for acid-labile actives. The US market concentrates delayed-release demand through Boston-Cambridge and San Diego biotech clusters, where formulators prioritize oxygen-barrier shells for parenteral-adjacent oral delivery systems.
Germany
EMA stability guidelines and REACH Annex XIV impurity thresholds filter market access for new suppliers. The Rhine-Ruhr and Baden-Württemberg pharmaceutical corridors anchor European HPMC qualification, with CDMOs demanding dual-source raw material documentation for ICH Q1A(R2) submissions.
India
Hyderabad and Ahmedabad contract manufacturing clusters generate captive demand for standard HPMC shells serving EU and US export registrations. CDSCO filing requirements and FSSAI dietary supplement rules shape procurement, with backward integration into HPMC raw material streams reducing import dependency.
China
SAMR green procurement incentives and dual carbon alignment favor cellulose-based capsules over animal-derived alternatives in sustainability-scored tenders. Zhejiang and Jiangsu provinces concentrate capsule manufacturing capacity, though NMPA stability guidelines for hygroscopic actives remain less stringent than FDA or EMA equivalents.
Japan
PMDA enforces additional local disintegration-time specifications that filter entrants without regional testing infrastructure. The Kanto region around Tokyo hosts specialized qualification laboratories, while METI industrial policy supports domestic capsule production for pharmaceutical security.
Global HPMC Capsules Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrated in firms controlling HPMC raw material supply and multi-regional filing infrastructure. The market structure rewards backward integration into cellulose ether purification and thermal gelation production lines with 18-24 month equipment lead times. Two dominant archetypes emerge: diversified excipient conglomerates with capsule-portfolio breadth, and regional specialists with regulatory testing depth in single jurisdictions. Competitive moves center on capacity expansion in Indian CDMO corridors and technology licensing for HPMC-AS delayed-release platforms.
Within the integrated-leader tier, Lonza (Capsugel) and ACG Associated Capsules exemplify contrasting geographic anchoring—Swiss-Indian infrastructure spanning FDA, EMA, and CDSCO filings versus South Asian supply concentration with captive raw material control. Suheung Co. Ltd. occupies a specialist position, representing Korean export-channel dominance in enteric-coating capabilities. These three firms illustrate how regulatory testing depth, backward integration, and regional manufacturing scale define competitive positioning.
| Leading Market Players |
|---|
| CapsCanada Corporation |
| Natural Capsules Ltd. |
| Lonza (Capsugel) |
| Zhejiang Yuexi Capsule Co., Ltd. |
| Sunil Healthcare |
| Qualicaps LLC |
| Suheung Co. Ltd. |
| Shionogi Qualicaps |
| ACG Associated Capsules |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month lead times for thermal gelation dipping-pin arrays compress pricing power toward integrated manufacturers with captive equipment pipelines, while spot buyers absorb premiums from limited secondhand machinery availability. This temporal bottleneck concentrates margin capture in firms controlling Nordic and North American cellulose ether feedstock streams.
Pricing Analysis
Contract-based long-term offtake agreements dominate pharmaceutical-grade procurement, with spot purchasing limited to nutraceutical short-runs and market-testing SKUs. Price differentiation separates delayed-release HPMC-AS grades from standard thermal-gelation shells, with certification depth for FDA-EMA-PMDA multi-filings commanding additional premiums. Pricing pressure stems from bovine bone gelatin alternatives retaining cost advantages in commoditized vitamin segments. Contract manufacturers in Indian CDMO corridors exhibit highest price sensitivity, while Boston-Cambridge biotech clusters prioritize oxygen-barrier performance over unit economics.
Supply Chain Analysis
Just-in-time inventory strategies prevail among direct-to-consumer nutraceutical brands compressing specification cycles to 8-12 months, whereas pharmaceutical filers maintain strategic stockpiles of qualified HPMC raw material streams. Supply concentrates in India, China, and South Korea, with Nordic and North American timber regions anchoring purified cellulose ether purification. Raw material dependencies center on wood pulp harvest cycles, methyl chloride reagents, and propylene oxide derivatives. Single-source vulnerability clusters around Suheung's specialized enteric-coating capabilities. Distribution runs through direct sales channels for pharmaceutical filings and distributor pooling for mid-tier supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards firms possessing thermal gelation production infrastructure and multi-regional pharmacopeial testing depth, assets requiring 3-5 year build timelines that outpace capital deployment cycles for most entrants.
For Market Incumbents: Consolidate backward integration into HPMC raw material streams to defend margin structures against Nordic timber harvest volatility. Add thermal gelation capacity in Hyderabad and Ahmedabad CDMO corridors to capture captive demand from EU and US export registrations. Deepen field formulation scientist deployment to accelerate delayed-release qualification timelines for peptide therapy pipelines. For New Entrants and Emerging Players: Lead with modular formulation platforms targeting direct-to-consumer nutraceutical brands in US and German markets, where 8-12 month specification cycles favor agile shell customization over multi-year supply agreements. Veterinary nutrition channels offer penetrable white-space as pet humanization trends intensify clean-label procurement. Pursue HPMC-AS technology licensing rather than greenfield thermal gelation capex. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because pharmacopeial harmonization pressures and 18-24 month equipment lead times structurally limit rapid competitive entry. Target acquisition profiles emphasize firms with dual-source raw material qualification for EMA stability submissions and established PMDA regional testing infrastructure. Watch for inflection when CDSCO filing requirements tighten parity with FDA dissolution standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HPMC Raw Material Streams | Captive supply from Nordic and North American timber regions insulates margin structures against harvest cycle volatility. |
| Capacity Expansion in Indian CDMO Corridors | Hyderabad and Ahmedabad clusters generate captive demand for standard and delayed-release shells serving multi-regional filings. |
| HPMC-AS Technology Licensing | Integrated acid resistance eliminates separate coating steps, reducing manufacturing cost for gastric-resistant peptide formulations. |
| Dual-Source Raw Material Qualification | REACH Annex XIV compliance for sub-ppm residual monomers secures EMA market access against tightening impurity thresholds. |
| PMDA Regional Testing Infrastructure Investment | Local disintegration-time specification capabilities filter competitors without Japanese pharmaceutical security alignment. |
Research Methodology
The analysis maps standard HPMC, delayed-release variants, enteric-coated architectures, and HPMC-AS integrated formulations, each validated through capsule manufacturing executives, pharmaceutical formulation scientists, CDMO procurement leads, and regulatory affairs directors specializing in ICH Q1A(R2) submissions. Primary fieldwork combined with secondary validation from FDA dissolution guidance documents, EMA stability guidelines, USP-NF monographs, PMDA pharmacopeial specifications, and customs trade data for cellulose ether imports. Bottom-up capacity modeling and top-down demand segmentation were triangulated against cross-referenced sources.
Consistency checks validated volume and value outputs against external benchmarks including ACC pharmaceutical excipient reports, SEC 10-K filings from diversified excipient conglomerates, and trade association production surveys. The analytical framework modeled shell type, release technology, application grade, end-user integration depth, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical capacity expansion patterns and pipeline conversion rates for moisture-sensitive biologics. Forecast inputs incorporated peptide therapy approval trajectories and SAMR green procurement incentive adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained pharmacopeial harmonization progress or stable Nordic timber supply conditions would require recalibration. Forecasts reflect assumptions regarding CDSCO filing requirement evolution and REACH Annex XIV enforcement intensity. Revision becomes warranted when HPMC-AS adoption rates for duodenal-release formulations cross thresholds that materially displace separate coating step workflows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Oxytocic Pharmaceuticals Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Denmark Pharmaceutical Market
Pharmaceuticals
Global Angina Pectoris Drugs Market
Pharmaceuticals
Marburg Virus Disease Therapeutics Market
Pharmaceuticals
Organ Transplant Immunosuppressant Drugs Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Global 3D Printed Drugs Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Canada Pharmaceutical Market
Pharmaceuticals
Omega 3 Prescription Drugs Market