
 Biological and Chemical Indicators Market | 2026-2036
Biological and Chemical Indicators Market Size, Share, and Industry Trends Forecast 2026-2036
Biological and Chemical Indicators Market Outlook
The EU Green Deal's emphasis on reducing single-use medical waste is repositioning sterilization monitoring priorities across European healthcare procurement. STERIS leverages its installed base of sterilization equipment to bundle indicator consumables with long-term service contracts. Mesa Laboratories anchors its competitive stance through specialized biological indicator manufacturing for pharmaceutical autoclave validation.
Biological and chemical indicators are diagnostic tools that verify sterilization efficacy through microbial kill verification or chemical color-change reactions, typically employing Bacillus spores or reactive inks that undergo irreversible transformation at specified temperature-pressure thresholds. Their primary purpose is to prevent healthcare-associated infections by confirming that surgical instruments, pharmaceutical products, and medical devices achieve sterility assurance levels. Biological indicators command premium positioning in pharmaceutical process validation due to their direct microbial challenge methodology, while chemical indicators dominate high-volume hospital sterilization departments where immediate visual confirmation streamlines workflow. The integrators segment is gaining traction in automated sterilization systems that require combined time-temperature-steam saturation data.
The US FDA enforces sterilization validation requirements under 21 CFR Part 820 quality system regulations, compelling medical device manufacturers to maintain documented indicator traceability for every sterilization batch. Europe's EMA coordinates with notified bodies to enforce MDR Annex I general safety and performance requirements, which mandate periodic revalidation of sterilization processes using standardized indicator systems. Stakeholders must monitor evolving harmonization between ISO 11138 biological indicator standards and regional pharmacopeial methods to avoid compliance fragmentation in multi-jurisdiction supply chains.
Market Dynamics
The sterilization validation market is experiencing a structural pivot toward integrated monitoring systems as pharmaceutical manufacturers consolidate supplier relationships under unified quality management frameworks.
Growth Catalysts
- EU MDR traceability mandates:The Medical Device Regulation's Annex I requirements compel reusable medical equipment sterilization with documented indicator chains, expanding validation service procurement across German, French, and Italian device manufacturers.
- Pharmaceutical autoclave validation intensity:Sterility assurance level documentation for parenteral drug manufacturing now requires biological indicator deployment per production batch, embedding consumables into GMP workflows.
- Germany's sterilization services corridor:Contract sterilization providers cluster around Tuttlingen and Munich medical device production zones, creating concentrated demand for indicator supply partnerships.
Market Restraints
- Bacillus spore supply concentration:Biological indicator production depends on specialized fermentation capacity concentrated among limited contract manufacturers, exposing supply continuity risk.
- ISO 11138 harmonization friction:Divergent pharmacopeial acceptance criteria between USP, EP, and JP create regulatory fragmentation for multi-jurisdiction product registrations.
- Self-contained chemical indicator substitution:Type 5 integrating indicators with defined resistance values are displacing biological indicators in routine hospital sterilization monitoring, compressing premium segment volume.
Strategic Opportunities
- India's CDSCO medical device registration expansion:The country's notified body capacity growth for Class C and D device approvals is creating first-mover positioning for sterilization validation service bundling.
- RFID-enabled indicator integration:Converging wireless tracking with chemical color-change technology enables automated sterilization load documentation without manual recorder transcription.
- EU Green Deal waste reduction incentives:Reusable surgical instrument reprocessing mandates are redirecting hospital procurement toward validated sterilization monitoring systems with extended cycle documentation.
Industry Challenges
- Microbiology technician scarcity:Biological indicator manufacturing and quality control require specialized spore cultivation expertise that competes with broader pharmaceutical microbiology hiring pools.
- Legacy steam sterilizer integration:Automated indicator reading systems face retrofit complexity with existing hospital autoclave infrastructure lacking digital data ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological and Chemical Indicators Market |
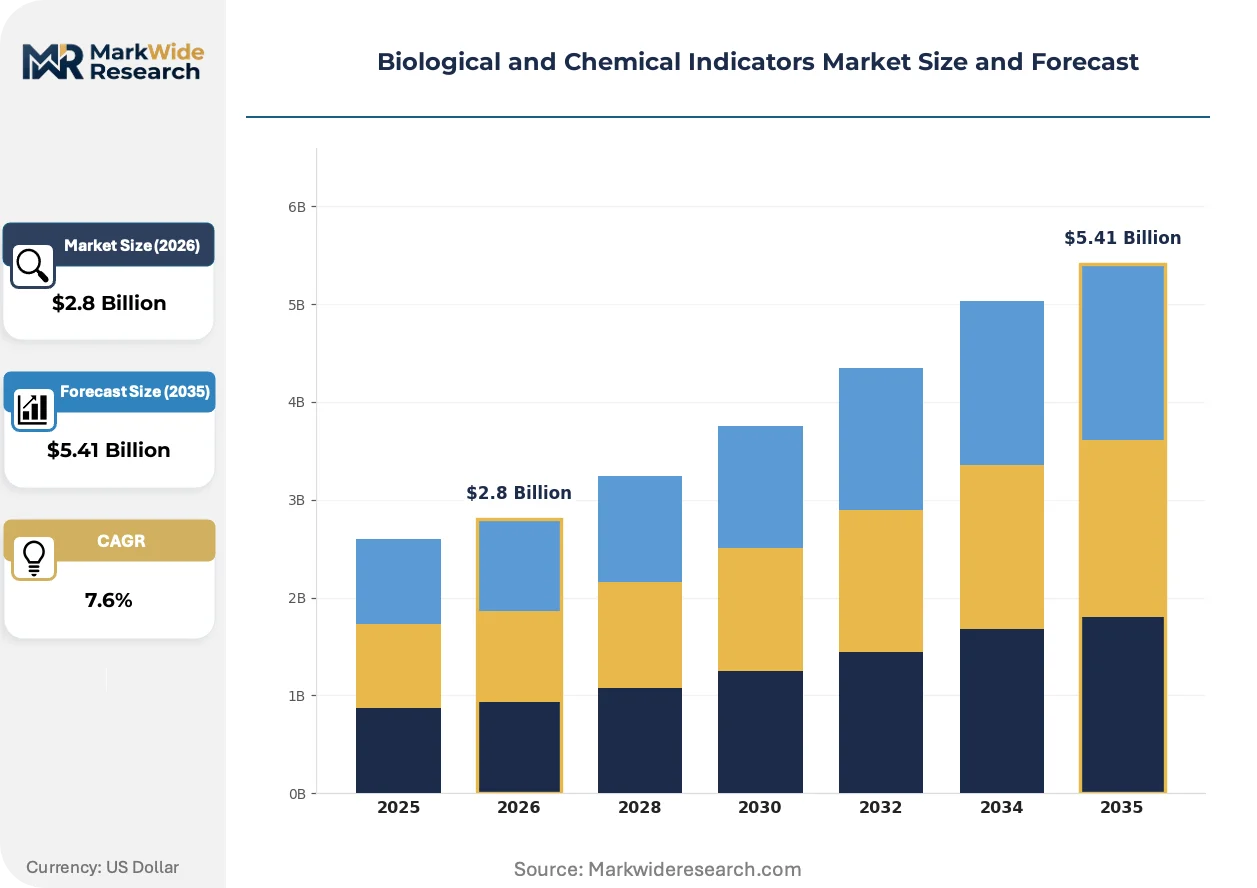
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Indicators, Chemical Indicators, Integrators, Reference Indicators Application: Sterilization, Quality Assurance, Compatibility Testing, Process Validation End User: Hospitals, Laboratories, Pharmaceutical Companies, Medical Device Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | 3M, STERIS, Mesa Laboratories, Getinge, Terragene, Propper Manufacturing, Solventum, Thermo Fisher Scientific, Cantel Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological and Chemical Indicators Market Strategic Shifts
Digital integration is reconfiguring how sterilization efficacy is documented, with automated data capture systems displacing manual logbook workflows across hospital central sterile supply departments.
Fluorogenic enzyme-based biological indicators are overtaking traditional spore-growth readout systems in pharmaceutical applications. These substrates generate measurable fluorescence upon viable spore inactivation, enabling quantitative sterility assurance level calculation rather than binary pass-fail determination. Aseptic filling line operators at parenteral manufacturing facilities are adopting this technology to compress batch release timelines from seven days to under twenty-four hours.
The FDA's 21 CFR Part 820 quality system regulation continues tightening medical device sterilization validation documentation requirements, with recent inspectional guidance emphasizing continuous process monitoring rather than periodic revalidation. Device manufacturers must now maintain statistical process control charts for every sterilization load, driving demand for indicator systems with calibrated resistance values. This enforcement pattern is most pronounced among orthopedic implant producers facing product liability exposure.
Hospital group purchasing organizations are consolidating sterilization consumable contracts into multi-year sole-source agreements with integrated equipment service providers. Independent indicator distributors are losing shelf space as STERIS and Getinge bundle chemical indicator shipments with preventive maintenance visits. This channel compression is most advanced in the United States, where IDN consolidation has reduced the number of independent purchasing decision points by over forty percent since 2019.
Biological and Chemical Indicators Market Segmentation
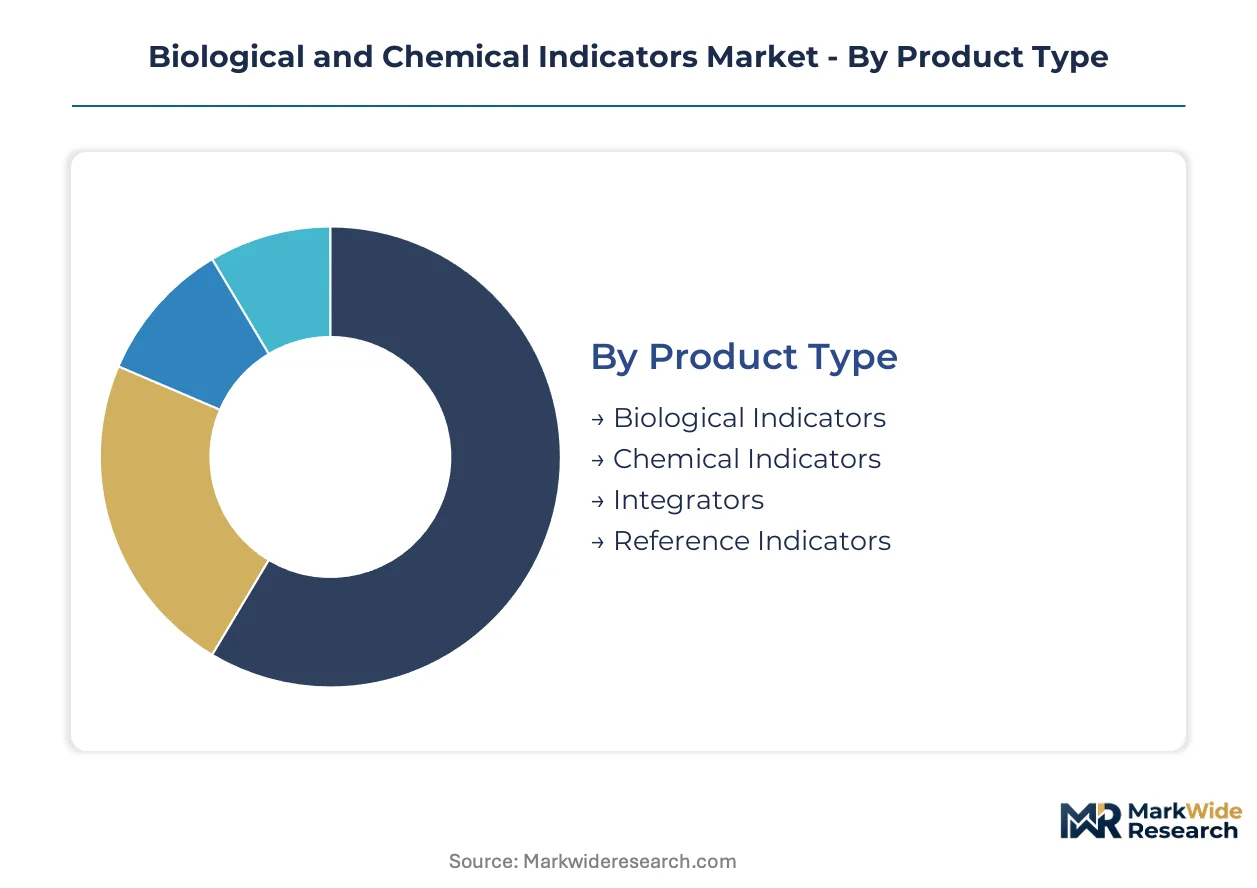
Segmentation in the biological and chemical indicators market reflects divergent technical requirements across sterilization modalities. Product specifications must align with distinct regulatory validation protocols governing pharmaceutical manufacturing versus hospital reprocessing environments.
Product Type:
Spore resistance characteristics and chemical substrate reactivity define the core specification axis across indicator categories.
- Biological Indicators:Contain standardized populations of Bacillus atrophaeus or Bacillus stearothermophilus spores on carrier substrates, providing direct microbial kill verification. Demand concentrates among German pharmaceutical autoclave validation services where EMA sterility assurance documentation mandates biological challenge per production batch.
- Chemical Indicators:Employ temperature-sensitive inks or chemical pellets that undergo irreversible color change upon steam, ethylene oxide, or dry heat exposure. Deployment dominates French and Italian hospital central sterile supply departments seeking immediate visual confirmation without incubation delays.
- Integrators:Combine time-temperature-steam saturation measurement in single devices with defined resistance values equivalent to biological indicators. Adoption is climbing fastest among automated sterilization systems in Spain and Poland where digital load documentation requirements are tightening.
- Reference Indicators:Serve as calibrated standards for indicator manufacturing quality control and laboratory proficiency testing. Procurement is concentrated among specialized biological indicator producers requiring traceable spore population verification.
Mature deployment sits with biological indicators. Newer deployment is concentrated in integrators.
Application:
Validation stringency tiers separate routine monitoring from formal regulatory submission requirements.
- Sterilization:Routine efficacy verification for steam, ethylene oxide, hydrogen peroxide plasma, and dry heat cycles. Volume concentrates in hospital sterile processing departments across Germany and France where EU MDR traceability mandates are expanding documentation intensity.
- Quality Assurance:Ongoing process monitoring to detect sterilizer performance drift before batch failure. Pharmaceutical manufacturers in Switzerland and Belgium deploy these systems under FDA 21 CFR Part 820 and EMA GMP frameworks requiring statistical process control.
- Compatibility Testing:Material-steam interaction assessment for novel medical device substrates. Medical device innovators in Ireland and the Netherlands use these protocols during product development prior to regulatory submission.
- Process Validation:Formal documented evidence that sterilization parameters achieve specified sterility assurance levels. This application commands premium pricing from contract sterilization providers in Germany's Tuttlingen corridor serving orthopedic implant manufacturers.
Established volume centers on sterilization. Steepest expansion trajectory is occurring in process validation.
End User:
Procurement sophistication and regulatory exposure shape customer segment differentiation.
- Hospitals:High-volume consumable purchasers prioritizing workflow efficiency and immediate visual readout. Consolidated purchasing through group purchasing organizations in the United States and national procurement frameworks in the United Kingdom are compressing supplier margins.
- Laboratories:Reference standard users requiring calibrated indicator lots for quality control and proficiency testing. Academic medical centers and contract research organizations in Sweden and Denmark represent concentrated demand.
- Pharmaceutical Companies:Most stringent validation requirements with batch-specific biological indicator documentation for parenteral drug manufacturing. Facilities in Germany, Switzerland, and Ireland anchor European demand under EMA coordinated oversight.
- Medical Device Manufacturers:Pre-market sterilization validation and ongoing production monitoring for implantable and reusable devices. Orthopedic and cardiovascular device producers in Germany, France, and Italy face intensifying FDA and notified body inspectional scrutiny.
Volume concentration rests with hospitals. Premium pricing power resides with pharmaceutical companies.
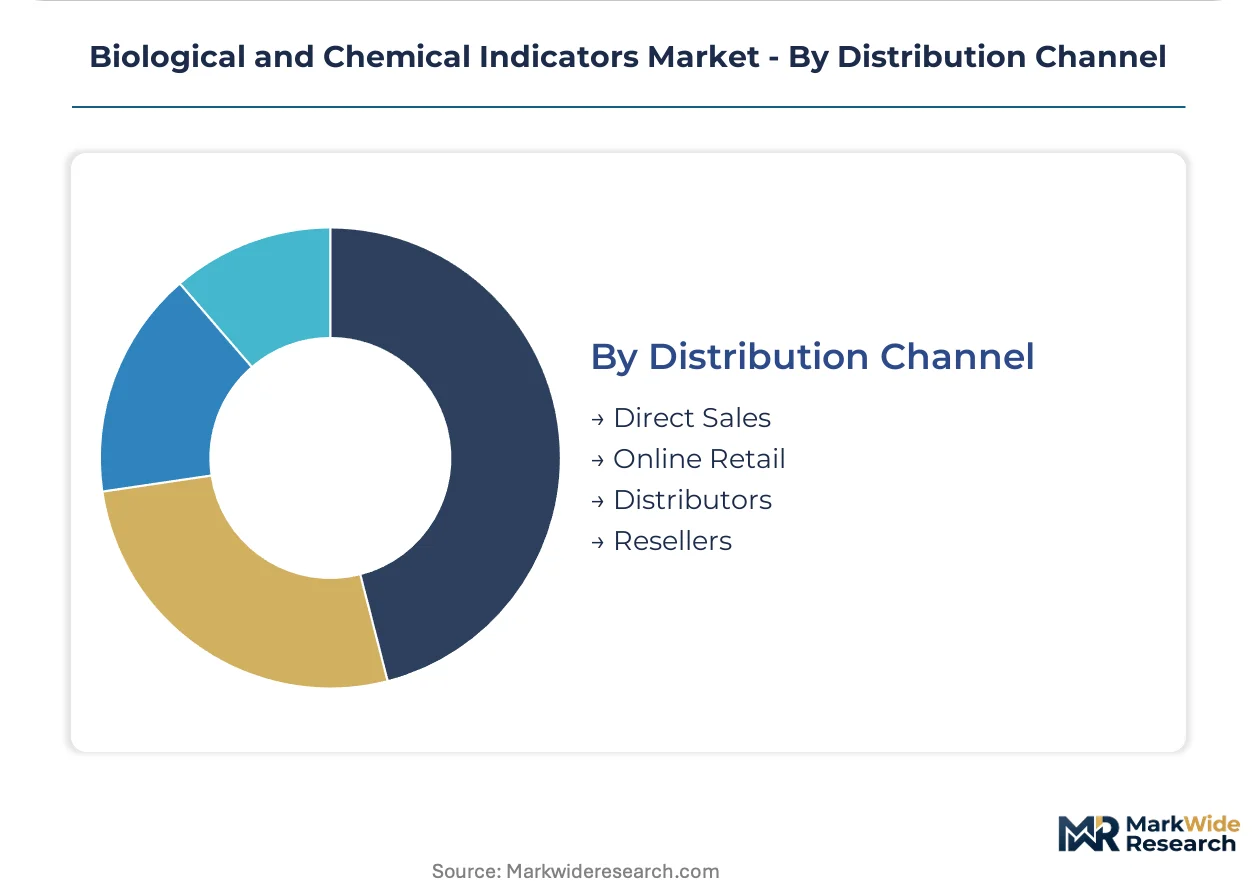
Distribution Channel:
Channel structure reflects equipment-attachment strategies versus independent consumable supply.
- Direct Sales:Manufacturer-to-end-user relationships for high-volume pharmaceutical and medical device accounts. STERIS and Getinge leverage sterilization equipment installed bases to secure multi-year indicator supply contracts.
- Online Retail:Small-lot procurement for rural hospitals and veterinary clinics seeking rapid replenishment without distributor markup. Growth is fastest in Nordic countries with mature e-procurement infrastructure.
- Distributors:Regional inventory holding and technical support for hospital sterile processing departments. Independent distributors are losing share to integrated equipment service providers bundling preventive maintenance with consumable supply.
- Resellers:Value-added repackaging and private-label sourcing for niche applications. Concentration is highest in Eastern European markets where price-sensitive procurement favors alternative supply arrangements.
Established revenue flows through direct sales. Channel shift momentum favors distributor consolidation around equipment-integrated service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of biological and chemical indicators concentrates in Germany and the United States, while consumption spreads across pharmaceutical manufacturing clusters and hospital sterilization networks in Western Europe and North America.
Germany
Tuttlingen's orthopedic implant manufacturers and Munich's medical device production zones anchor European demand for sterilization validation services. EMA coordinated oversight under MDR Annex I mandates documented indicator chains for reusable equipment. Contract sterilization providers cluster along the Neckar-Alb corridor, embedding indicator supply partnerships into multi-year service agreements.
United States
FDA 21 CFR Part 820 enforcement drives batch-specific biological indicator documentation among parenteral drug manufacturers. Hospital group purchasing organizations have consolidated sterile processing contracts, reducing independent purchasing decision points by over forty percent since 2019. Orthopedic implant producers in Warsaw, Indiana and Memphis, Tennessee face intensifying inspectional scrutiny for continuous process monitoring.
Switzerland
Swissmedic-regulated pharmaceutical facilities in Basel and Geneva deploy statistical process control systems under FDA and EMA dual compliance frameworks. Biological indicator demand concentrates among aseptic filling line operators seeking compressed batch release timelines. The country's precision manufacturing heritage supports specialized fermentation capacity for Bacillus spore production.
France
ANSM oversight of hospital central sterile supply departments prioritizes immediate visual confirmation through chemical indicator deployment. The Île-de-France region's academic medical centers drive reference standard procurement for quality control and proficiency testing. Reusable surgical instrument reprocessing mandates under EU Green Deal incentives redirect procurement toward validated monitoring systems.
India
CDSCO's expansion of notified body capacity for Class C and D device registrations creates first-mover positioning for sterilization validation service bundling. Maharashtra and Gujarat pharmaceutical manufacturing zones adopt biological indicator protocols for export-oriented parenteral drug production. Contract sterilization infrastructure in Hyderabad and Ahmedabad concentrates demand for indicator supply partnerships.
Biological and Chemical Indicators Market Competitive Environment
The competitive structure tilts toward equipment-integrated service providers with sterilization hardware installed bases. Tiered specialization separates pharmaceutical-grade biological indicator manufacturers from high-volume hospital chemical indicator suppliers. Strategic moves center on multi-year sole-source agreements bundling consumables with preventive maintenance, plus backward integration into specialized Bacillus spore fermentation capacity.
Within the equipment-integrated tier, STERIS and Getinge exemplify the service-bundling archetype that has compressed independent distributor shelf space. Mesa Laboratories occupies a position among specialized biological indicator manufacturers serving pharmaceutical autoclave validation requirements. These three anchors represent contrasting competitive positions: sterilization hardware leverage versus consumable specialization versus reference standard calibration expertise.
| Leading Market Players |
|---|
| 3M |
| STERIS |
| Mesa Laboratories |
| Getinge |
| Terragene |
| Propper Manufacturing |
| Solventum |
| Thermo Fisher Scientific |
| Cantel Medical |
| Others |
Value Chain & Pricing Dynamics
Specialized microbiology technician pools in Germany's Neckar-Alb corridor and Switzerland's Basel region anchor production cost structures, with labor-cost differentials between these fermentation-specialist clusters and routine chemical indicator manufacturing sites in Eastern Europe driving three-tier spreads across premium biological indicators, standard chemical indicators, and economy-grade alternatives.
Pricing Analysis
Margin tightening in pharmaceutical-grade biological indicators reflects Bacillus spore supply scarcity concentrated among limited contract fermentation providers. Pricing stratifies across premium, standard, and economy tiers based on ISO 11138 certification grade and volume scale, with FDA-tier validation commanding substantial premiums over routine hospital monitoring products. Cost-down pressure accelerates in chemical indicators as group purchasing organizations consolidate contracts around equipment-integrated service bundles. Hospital sterile processing departments exhibit highest price sensitivity, while pharmaceutical companies under EMA GMP mandates demonstrate lowest elasticity due to regulatory substitution barriers.
Supply Chain Analysis
Bacillus atrophaeus and Bacillus stearothermophilus spore supply rests on specialized fermentation capacity concentrated in Germany, Switzerland, and the United States, with substrate carriers and reactive ink formulations sourcing from chemical specialists in France and Italy. Raw material dependencies span pharmaceutical-grade carrier substrates, temperature-sensitive dye precursors, and calibrated reference standards. Single-source vulnerability pervades the spore cultivation tier where technician expertise scarcity limits qualified contract manufacturers. Distribution runs through direct sales relationships for pharmaceutical accounts and equipment-integrated service providers for hospital systems, with independent distributors losing share to bundled preventive maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as equipment-integrated service providers compress independent distributor margins through multi-year sole-source agreements, forcing smaller chemical indicator suppliers toward acquisition or niche specialization.
For Market Incumbents: Extend sterilization equipment installed bases into captive indicator supply through preventive maintenance contract bundling, mirroring STERIS and Getinge channel compression strategies. Deepen backward integration into Bacillus spore fermentation capacity to secure supply continuity against contract manufacturer concentration risk. Prioritize RFID-enabled indicator development to capture automated sterilization load documentation demand from hospitals facing EU MDR traceability mandates.
For New Entrants and Emerging Players: CDSCO medical device registration expansion in India opens a window for sterilization validation service bundling among Maharashtra and Gujarat pharmaceutical exporters seeking Western regulatory alignment. Target contract sterilization infrastructure in Hyderabad and Ahmedabad with biological indicator supply partnerships anchored to export-oriented parenteral manufacturing. Pursue white-label chemical indicator sourcing for price-sensitive Eastern European resellers as a volume foothold before premium segment migration.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized biological indicator manufacturers possessing ISO 11138 reference standard calibration expertise, given fluorogenic enzyme-based technology adoption accelerating pharmaceutical batch release compression. Long-term viability favors assets with dual FDA-EMA regulatory dossiers and captive fermentation capacity rather than pure-play chemical indicator distributors facing equipment-integrated channel displacement. Watch CDSCO notified body capacity buildout velocity as inflection indicator for India's contract sterilization infrastructure investment cycle.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bacillus Spore Fermentation | Secures supply continuity against contract manufacturer concentration risk in Germany and Switzerland. |
| RFID-Enabled Indicator Development | Captures EU MDR traceability automation demand from hospital sterile processing departments. |
| CDSCO Registration Service Bundling | Positions early entrants for India's Class C and D device sterilization validation market expansion. |
| Fluorogenic Enzyme Biological Indicator Launch | Compresses pharmaceutical batch release timelines from seven days to under twenty-four hours. |
| Multi-Year GPO Sole-Source Agreements | Mirrors STERIS channel compression strategy consolidating U.S. hospital sterile processing procurement. |
Study Parameters
Multi-period observation of sterilization validation protocol adoption rates anchored the trend analysis, supplemented by interviews with sterile processing department managers, pharmaceutical quality assurance directors, contract sterilization operations heads, and GPO contracts managers. Secondary validation drew from FDA 21 CFR Part 820 inspectional guidance documents, EMA MDR Annex I implementation reports, ISO 11138 standard revision records, and hospital procurement database aggregations. Bottom-up indicator volume modeling triangulated against top-down pharmaceutical and medical device production forecasts.
Input-output matrices mapped biological indicator demand to pharmaceutical autoclave validation intensity and chemical indicator consumption to hospital sterilization cycle volumes across product type, application, and end user segments. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory enforcement phase-ins and equipment replacement cycles. Forecast inputs incorporated EU MDR traceability mandate rollout schedules, CDSCO notified body capacity expansion trajectories, and group purchasing organization consolidation patterns.
Caveats apply where ISO 11138 harmonization friction between USP, EP, and JP pharmacopeial methods could materially shift multi-jurisdiction product registration economics, or where self-contained integrating indicator substitution accelerates beyond modeled displacement rates. Forecasts reflect documented assumptions about regulatory enforcement continuity and spore supply concentration stability. A small set of named triggers—Bacillus fermentation capacity expansion, RFID sterilization tracking adoption velocity, and India's notified body approval throughput—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Point of Care Infection Control Market
Infection Control
Global High Level Disinfection Services Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Intra-Amniotic Infection Treatment Market
Infection Control
Staphylococcal Infection Treatment Market
Infection Control
Medical Activated Carbon Dressing Market
Infection Control
Blood Stream Infection Testing Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Intra-Abdominal Infection Treatment Market
Infection Control
Preventable Vaccines Market
Infection Control
Infection Prevention Market
Infection Control
Virus Filtration Market
Infection Control
Steam and Hydrogen Peroxide Biological Indicators Market
Infection Control
Yeast Infection Market
Infection Control
Global Hospital Acquired Infection Control Market
Infection Control
Sterilization Market