
 Global Infection Prevention Devices Market | 2026-2036
Global Infection Prevention Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Infection Prevention Devices Market Foresight
Hospital-grade sterilization certification is reorganizing competitive dynamics in infection prevention devices. 3M leverages its materials science portfolio to dominate surgical drape and barrier material segments. STERIS sustains technology leadership through vaporized hydrogen peroxide and plasma sterilization platforms. Getinge anchors European market presence with integrated sterilization workflows for healthcare facilities.
Infection prevention devices encompass engineered products and systems designed to eliminate or suppress pathogenic microorganisms on surfaces, instruments, and in ambient environments, typically operating at sterilization assurance levels of 10^-6 SAL or employing EPA-registered disinfectant chemistries. These devices serve critical functions in interrupting nosocomial transmission chains and maintaining aseptic conditions in clinical and industrial settings. Sterilization equipment and UV-C devices capture expanding margin pools as hospitals replace legacy steam autoclaves with low-temperature alternatives. Disinfectants and barrier materials remain mature revenue bases with stable replacement demand. Antimicrobial coatings represent the fastest-growing product category as manufacturers integrate copper and silver ion technologies into high-touch medical surfaces.
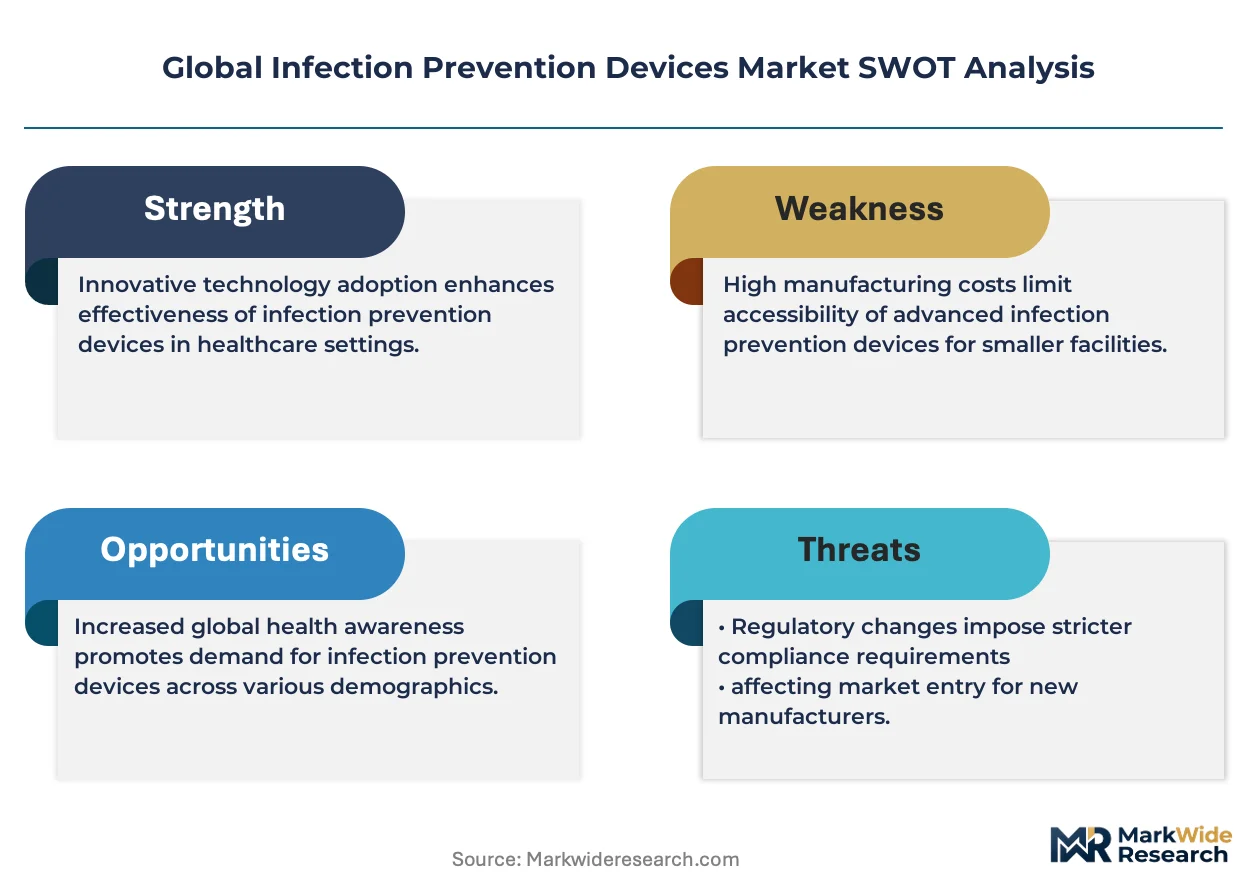
FDA sterilization validation protocols, EMA Medical Device Regulation requirements, and EPA antimicrobial pesticide registrations collectively elevate compliance costs and filter subscale competitors from commercial access. WHO infection control guidelines further shape procurement specifications in emerging markets and international development programs. Stakeholders must monitor evolving regulatory harmonization between FDA and EU MDR frameworks to anticipate testing burden shifts and timeline risks for new product introductions.
Market Dynamics
FDA and EMA sterilization validation protocols are tightening compliance thresholds, forcing manufacturers to reengineer thermal and chemical sterilization platforms while hospital procurement shifts toward automated low-temperature alternatives.
Growth Catalysts
- Hospital automation mandates:Acute care facilities in the United States are replacing steam autoclaves with vaporized hydrogen peroxide systems to reduce cycle times and instrument damage.
- EPA antimicrobial registrations:Expanded disinfectant chemistries for emerging pathogens are opening new product categories for surface decontamination devices.
- Copper ion integration:Medical device manufacturers are embedding antimicrobial alloys into high-touch surfaces, driving coating technology adoption across surgical suites.
Market Restraints
- Platinum group metal volatility:Hydrogen peroxide sterilization catalysts depend on palladium and rhodium supplies concentrated in South Africa and Russia.
- EU MDR testing burden:Extended clinical evaluation timelines for sterilization accessories are delaying product launches by 18-24 months.
- UV-C LED substitution threat:Solid-state ultraviolet sources are displacing mercury vapor lamps in ambient disinfection applications.
Strategic Opportunities
- India hospital infrastructure:Government health schemes are funding infection control equipment procurement in tier-2 and tier-3 cities with limited legacy system displacement costs.
- WHO guideline alignment:International development programs are standardizing procurement specifications around pre-qualified sterilization devices.
- Plasma-UV convergence:Hybrid sterilization systems combining low-temperature gas plasma with ultraviolet irradiation are enabling single-cycle processing of temperature-sensitive endoscopes.
Industry Challenges
- Validation engineering talent scarcity:SAL 10^-6 sterilization assurance documentation requires specialized microbiologists and process engineers in short supply across Germany and Japan.
- Legacy steam infrastructure integration:Hospital facilities built before 1990 face structural constraints retrofitting hydrogen peroxide exhaust systems and electrical load capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Infection Prevention Devices Market |
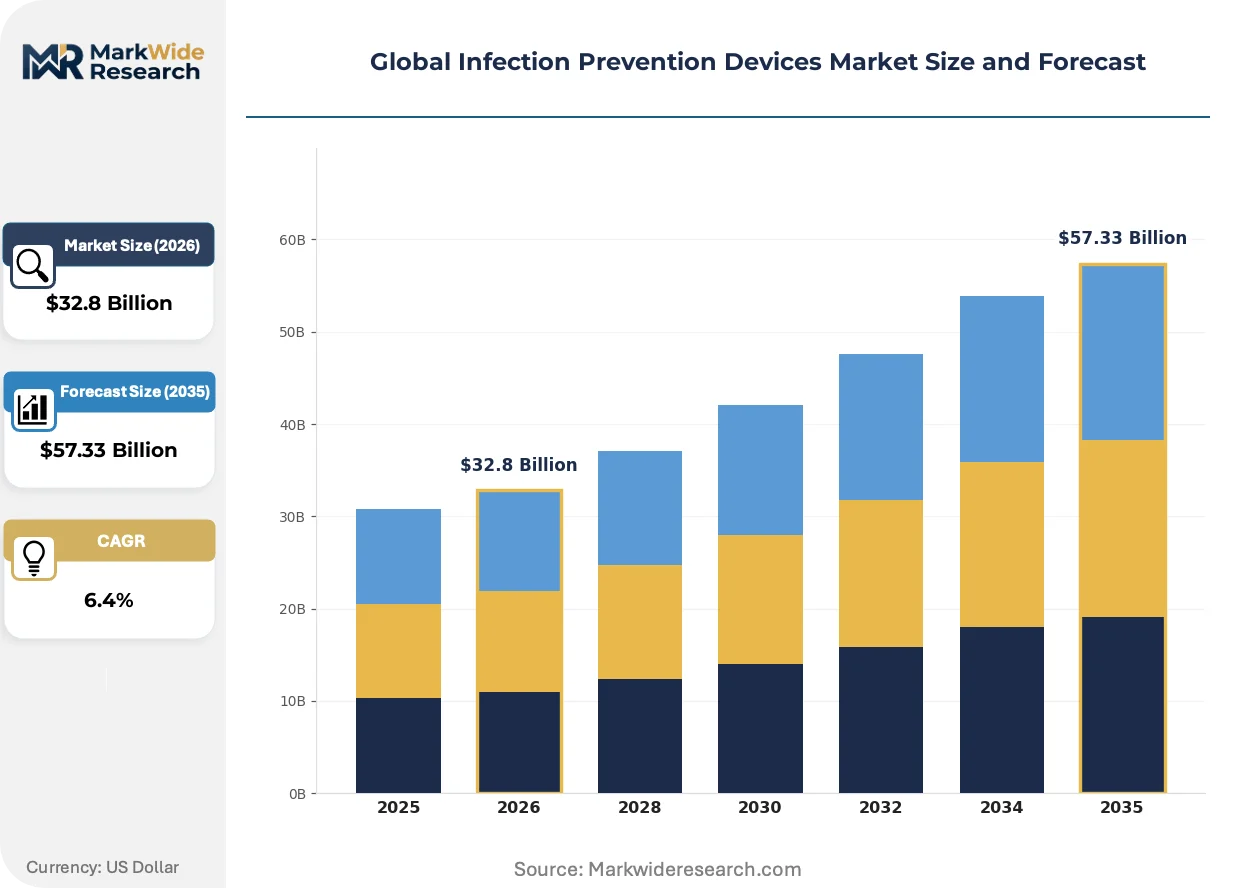
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Drapes, Sterilization Equipment, Disinfectants, Barrier Materials, Antimicrobial Coatings, UV-C Devices Technology: Electrostatic Spraying, Plasma Sterilization, Vaporized Hydrogen Peroxide, Ultraviolet Germicidal Irradiation, Automated Disinfection, Biofilm Removal Application: Hospital Infection Control, Ambulatory Care, Home Healthcare, Dental Clinics, Pharmaceutical Production, Food Processing End User: Healthcare Facilities, Diagnostic Laboratories, Long-term Care Institutions, Outpatient Centers, Veterinary Clinics, Research Institutes |
| Companies Covered | 3M, STERIS, Getinge, Advanced Sterilization Products, Cardinal Health, Ecolab, ASP, Fortive, Sotera Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Infection Prevention Devices Market Shifts & Advancements
Low-temperature sterilization chemistry is displacing thermal methods across surgical instrument reprocessing, while connected device architectures enable real-time cycle validation and predictive maintenance.
Portable UV-C disinfection systems are miniaturizing through semiconductor emitter advances, enabling point-of-care surface treatment in emergency departments and ambulatory surgery centers. Hospital infection control teams in Japan are deploying handheld units between cases. This form factor expansion is compressing equipment procurement cycles from capital budget cycles to consumable replenishment models.
EMA Medical Device Regulation Annex I requirements are elevating biocompatibility testing for sterilization packaging materials, forcing barrier film manufacturers to submit extended cytotoxicity and sensitization data. Sterile supply departments in European hospitals are now requiring ISO 11137 validation certificates for all incoming packaging. German device sterilizers are consolidating supplier bases to reduce documentation complexity.
Acute care buyers are unbundling after-sales service contracts from equipment purchases, negotiating separate agreements for preventive maintenance and validation support. This purchasing behavior is disrupting traditional distributor models that bundled service margins into capital equipment pricing. The shift is most visible in United States IDN procurement, where supply chain executives are centralizing sterilization service contracts across multi-hospital networks.
Global Infection Prevention Devices Market Segmentation
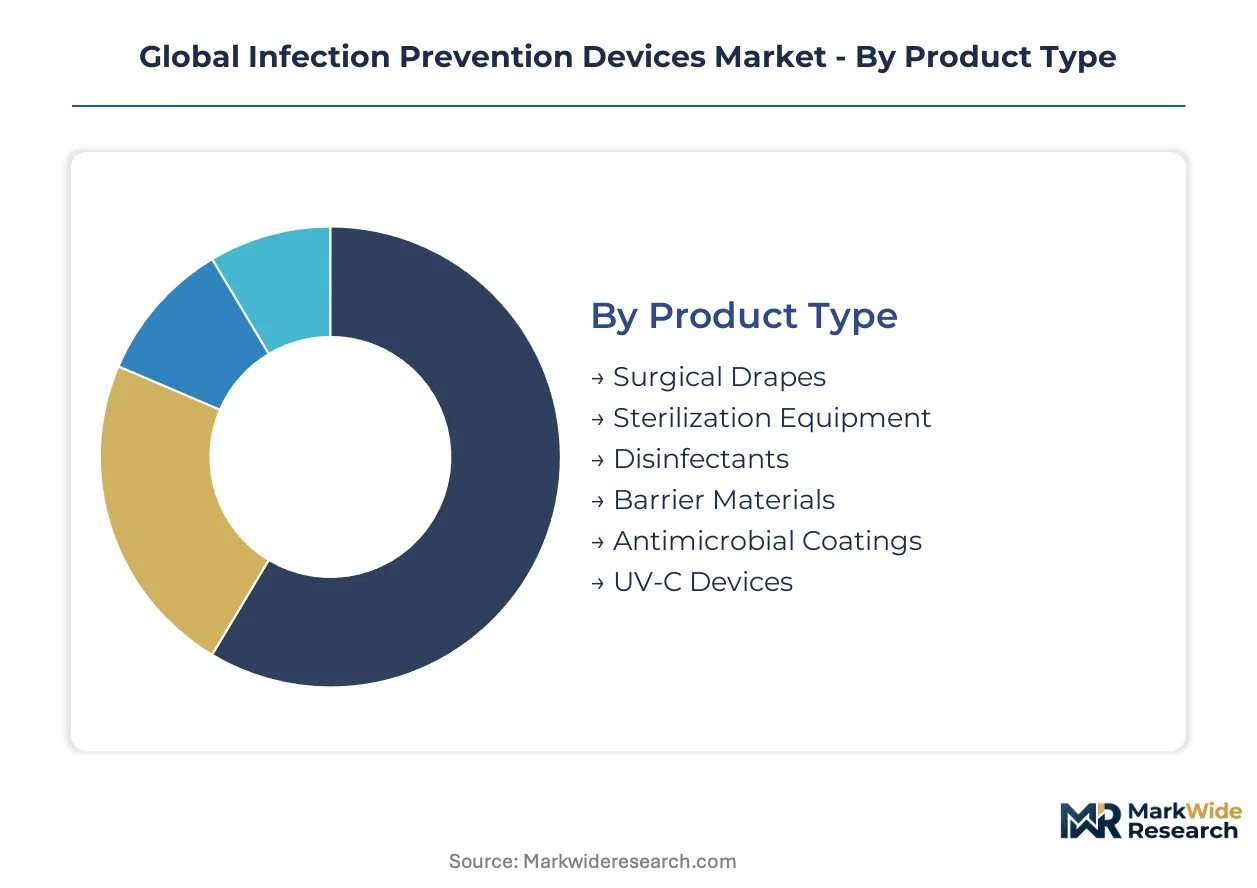
Segmentation reveals how infection prevention value migrates across product architectures, chemistry platforms, and care settings. Manufacturers must align R&D investments with where procurement budgets are concentrating and where regulatory validation burdens vary.
Product Type:
Margin pools concentrate in capital equipment with recurring consumable attachments, while commodity disposables face pricing pressure from hospital group purchasing organizations.
- Sterilization Equipment:Vaporized hydrogen peroxide and plasma-based systems command premium positioning through FDA-validated cycle assurance. United States acute care facilities are displacing legacy steam autoclaves to reduce instrument damage and turnaround times.
- Antimicrobial Coatings:Copper and silver ion technologies embed directly into high-touch medical surfaces and surgical suite fixtures. German hospital construction standards are mandating antimicrobial surface specifications for new facility builds.
- Surgical Drapes:Non-woven barrier fabrics with fluid-resistant laminations dominate standard procedure volumes.
- Disinfectants:EPA-registered chemistries for emerging pathogens span wipes, sprays, and automated dispensing systems.
- Barrier Materials:Sterile packaging films and gown fabrics face EMA biocompatibility testing expansion under EU MDR Annex I.
- UV-C Devices:Mercury vapor and solid-state emitter systems serve ambient disinfection in unoccupied spaces.
The dominant share belongs to Sterilization Equipment, while Antimicrobial Coatings is closing the gap fastest.
Technology:
Technology selection determines capital intensity, cycle throughput, and compatibility with temperature-sensitive instruments.
- Vaporized Hydrogen Peroxide:Low-temperature chemistry enables rapid sterilization of polymer and electronic instruments without thermal degradation. Japanese surgical centers are standardizing this modality for flexible endoscope reprocessing.
- Plasma Sterilization:Gas plasma systems using hydrogen peroxide or peracetic acid achieve deep penetration into lumened devices. European sterilization service providers are consolidating around integrated plasma-UV hybrid platforms.
- Automated Disinfection:Robotic systems with mapped navigation reduce human exposure to high-level disinfectants.
- Ultraviolet Germicidal Irradiation:254nm mercury and 265nm LED sources target surface and air decontamination.
- Electrostatic Spraying:Charged particle application improves disinfectant coverage on complex geometries.
- Biofilm Removal:Enzymatic and mechanical systems address recalcitrant microbial colonies on implanted devices.
Vaporized Hydrogen Peroxide holds the installed base leadership, though Plasma Sterilization is expanding most quickly in lumened device applications.
Application:
Application segmentation tracks where infection control protocols are most stringent and where capital allocation cycles differ.
- Hospital Infection Control:Central sterile supply departments and operating suites drive the highest equipment specification and validation requirements. United States integrated delivery networks are centralizing procurement across multi-hospital systems.
- Pharmaceutical Production:Aseptic manufacturing environments require ISO 14644 cleanroom classification with continuous environmental monitoring. FDA sterilization validation protocols for drug-device combinations are extending qualification timelines.
- Ambulatory Care:Same-day surgical centers prioritize compact, rapid-cycle sterilization with minimal facility infrastructure.
- Home Healthcare:Portable disinfection devices and single-use barriers serve immunocompromised patients outside institutional settings.
- Dental Clinics:Autoclave and chemical vapor sterilization for handpieces and instruments follows OSHA bloodborne pathogen standards.
- Food Processing:UV-C and chemical wash systems control Listeria and Salmonella in ready-to-eat production lines.
Hospital Infection Control commands the largest revenue pool, with Pharmaceutical Production gaining share fastest on biologics manufacturing expansion.
End User:
End user categories reflect divergent procurement sophistication, from centralized supply chain operations to fragmented individual practice purchasing.
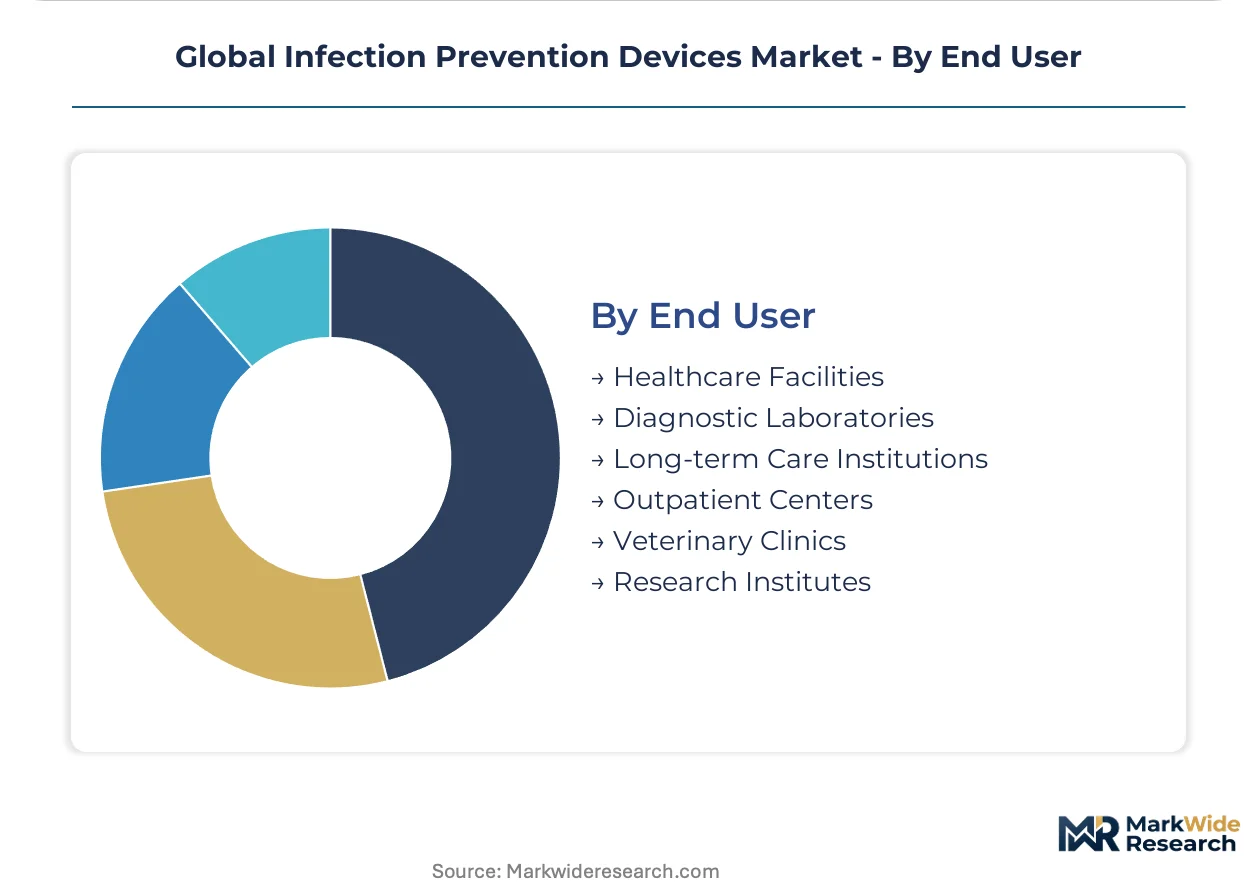
- Healthcare Facilities:Acute care hospitals with dedicated infection control committees negotiate enterprise-wide sterilization service contracts. Germany's hospital reform programs are bundling infection prevention equipment into infrastructure modernization grants.
- Long-term Care Institutions:Nursing facilities face elevated C. difficile and MRSA transmission risks requiring persistent environmental disinfection. Japan's aging population is expanding skilled nursing bed counts with associated infection control capital needs.
- Diagnostic Laboratories:Clinical and pathology labs require biosafety cabinet sterilization and waste decontamination systems.
- Outpatient Centers:Limited procedure volumes favor tabletop sterilizers and disposable barrier strategies.
- Veterinary Clinics:Companion animal surgical suites adopt human-healthcare sterilization standards for implant procedures.
- Research Institutes:BSL-2 and BSL-3 containment facilities require validated sterilization for biological waste and equipment.
Healthcare Facilities dominate absolute spending, while Long-term Care Institutions are climbing the fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device sterilization manufacturing clusters concentrate in industrial corridors with established precision engineering ecosystems and proximity to major hospital procurement networks. Germany, the United States, Japan, India, and China anchor regional supply chains through distinct regulatory and infrastructure advantages.
United States
Acute care facilities in the United States are replacing legacy steam autoclaves with vaporized hydrogen peroxide systems to reduce instrument damage and turnaround times. FDA sterilization validation protocols are tightening compliance thresholds for thermal and chemical sterilization platforms. The Boston-Cambridge corridor hosts concentrated medical device R&D operations serving IDN procurement networks.
Germany
German hospital construction standards are mandating antimicrobial surface specifications for new facility builds. EMA Medical Device Regulation Annex I requirements are elevating biocompatibility testing for sterilization packaging materials. The Baden-Württemberg industrial belt anchors precision sterilization equipment manufacturing with integrated supply chains for healthcare exports.
Japan
Japan's aging population is expanding skilled nursing bed counts with associated infection control capital needs. METI standards guide low-temperature sterilization chemistry adoption in surgical centers. The Kansai region around Osaka maintains dense clusters of endoscope reprocessing equipment manufacturers serving domestic and Asian markets.
India
Government health schemes are funding infection control equipment procurement in tier-2 and tier-3 cities with limited legacy system displacement costs. CDSCO medical device regulations are harmonizing with international sterilization assurance standards. The Maharashtra-Gujarat pharmaceutical manufacturing corridor is driving demand for aseptic processing validation equipment.
China
NMPA medical device registration pathways are extending sterilization equipment qualification timelines for imported systems. Domestic manufacturers are capturing share in UV-C disinfection device segments through cost-optimized semiconductor emitter sourcing. The Yangtze River Delta medical device production zone concentrates contract sterilization service providers.
Global Infection Prevention Devices Market Competitive Landscape
Concentration sits with diversified healthcare conglomerates and specialized sterilization technology developers. The vendor base spans three distinct tiers: integrated materials science platforms with surgical barrier portfolios, pure-play sterilization equipment specialists with validated low-temperature chemistry platforms, and regional contract manufacturers serving emerging market procurement. Dominant competitive moves include technology licensing partnerships for plasma-UV hybrid systems and backward integration into antimicrobial coating raw materials.
Among diversified healthcare technology developers, 3M, STERIS, and Getinge occupy positions across multiple sterilization and barrier product categories. 3M represents the materials science archetype with surgical drape and barrier material portfolios. STERIS exemplifies sterilization chemistry specialization through vaporized hydrogen peroxide platforms. Getinge anchors European market presence with integrated sterilization workflows for healthcare facilities.
| Leading Market Players |
|---|
| 3M |
| STERIS |
| Getinge |
| Advanced Sterilization Products |
| Cardinal Health |
| Ecolab |
| ASP |
| Fortive |
| Sotera Health |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for platinum group metal catalysts concentrate pricing power among hydrogen peroxide sterilization equipment manufacturers with captive palladium sourcing, while acute care buyers exploit equipment-consumable bundling to compress service margins.
Pricing Analysis
FDA 510(k) sterilization validation requirements dictate the pricing tier structure across vaporized hydrogen peroxide systems. Three-tier pricing structure across premium FDA-validated, standard CE-marked, and economy non-certified levels separates installed base leaders from regional challengers. Cost compression in standard-tier equipment is intensifying because hospital group purchasing organizations are unbundling after-sales contracts from capital purchases. Ambulatory surgery centers exhibit highest price sensitivity; pharmaceutical aseptic manufacturing facilities show least.
Supply Chain Analysis
Germany and Japan anchor precision sterilization equipment manufacturing with integrated supply chains for healthcare exports. Palladium and rhodium catalysts draw from South African and Russian mining concentrates; UV-C LED semiconductors source from Taiwan foundries. Single-source vulnerability in platinum group metal supply creates disruption exposure for hydrogen peroxide platform producers. Distribution runs through specialized medical device distributors with field service capabilities, though United States integrated delivery networks are consolidating direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UV-C LED substitution threatens mercury vapor lamp incumbents, forcing sterilization equipment manufacturers to defend chemistry-based platforms through validation depth and cycle assurance.
For Market Incumbents: Fortify installed base retention by embedding predictive maintenance software into vaporized hydrogen peroxide platforms, countering UV-C LED displacement with documented SAL 10^-6 assurance. Backward integration into antimicrobial coating raw materials secures margin capture as copper ion technologies penetrate surgical suite construction standards. For New Entrants and Emerging Players: Lead with portable UV-C semiconductor systems targeting Japan's emergency department point-of-care disinfection workflows, where handheld form factors bypass capital budget cycles. Tier-2 Indian cities offer white-space hospital infrastructure procurement with limited legacy steam autoclave displacement costs; partner with government health scheme administrators for pre-qualified device listings. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified healthcare conglomerates seeking to divest non-core sterilization accessories divisions under EU MDR documentation burden. Five-to-ten-year viability hinges on plasma-UV hybrid technology validation; monitor FDA submission timelines for single-cycle endoscope processing systems as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for low-temperature sterilization platforms unlocks United States acute care procurement. |
| CE Marking Pathway | MDR Annex I biocompatibility validation enables European barrier material market access. |
| Hospital System Partnership | Integrated delivery network sterilization service contracts centralize multi-facility equipment procurement. |
| Software Companion Development | Real-time cycle validation and predictive maintenance modules differentiate capital equipment offerings. |
| Reimbursement Strategy | WHO pre-qualification alignment positions devices for international development program procurement. |
Research Methodology
Cross-validation between hospital procurement database analysis and sterilization equipment manufacturer SEC filings anchors the qualitative findings. Primary interviews with central sterile supply directors, biomedical engineers, GPO contracts managers, and infection control officers combined with secondary validation from FDA 510(k) databases, EMA MDR submission records, hospital construction specification filings, and WHO pre-qualification lists. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis enable triangulation.
Sensitivity analysis across platinum group metal price volatility bands and hospital construction cycle timing informs the analytical framework. Segmentation dimensions span sterilization chemistry platform, instrument compatibility class, facility infrastructure vintage, and regional regulatory cluster. CAGRs derive from installed base replacement modeling and emerging market penetration curves. Forecast inputs incorporate FDA validation timeline distributions and EU MDR clinical evaluation period extensions.
The analysis sits within stated boundaries; outcomes outside sustained platinum group metal supply continuity and stable hospital capital allocation cycles would require recalibration. Forecasts reflect documented assumptions regarding sterilization assurance standard harmonization and emerging pathogen EPA registration expansion. Recalibration cycles align with material shifts in FDA guidance document releases and major healthcare infrastructure program announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Hospital Acquired Infections Market
Infection Control
Preventable Vaccines Market
Infection Control
Ultrasound Probe Disinfection Market
Infection Control
Hand Hygiene Market
Infection Control
Veterinary Disinfectant for Pets and Farms Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Global Prophylactic Human Vaccine Market
Infection Control
North America Hand Sanitizer Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Antimicrobial Hospital Curtains Market
Infection Control
Antiseptic Bathing Market
Infection Control
Global Hospital Disinfectant Products and Services Market
Infection Control
Virus Filtration Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Hand Sanitizer Spray Market
Infection Control
Global Viral Clearance Services Market