
 Antiseptic Bathing Market | 2026-2036
Antiseptic Bathing Market Size, Share, and Industry Trends Forecast 2026-2036
Antiseptic Bathing Market Analysis
India is rewriting antiseptic bathing supply dynamics as domestic manufacturing scales for cost-competitive exports. 3M Company leverages its adhesive and skin health portfolio to anchor hospital-grade antiseptic delivery systems. Medline Industries controls extensive North American distribution networks for preoperative bathing kits. Mölnlycke Health Care specializes in advanced wound care adjacencies that extend into surgical patient hygiene protocols.
Antiseptic bathing encompasses skin cleansing protocols using chlorhexidine gluconate, povidone-iodine, or benzalkonium chloride formulations to reduce microbial load before medical procedures, typically requiring minimum 2% CHG concentration for surgical site infection prophylaxis. Liquid antiseptics dominate hospital procurement due to established protocol familiarity and bulk dispensing compatibility, while foaming antiseptics capture faster expansion in outpatient settings where application speed and reduced drip improve compliance. Preoperative application commands the largest revenue pool as bundled payment penalties for surgical site infections intensify compliance, whereas home care emerges as the fastest-growing end user segment driven by post-discharge bathing protocols and aging-in-place trends.
FDA premarket notification requirements for antiseptic drug products shape formulation standards and clinical evidence thresholds for market entry. EPA antimicrobial pesticide regulations govern active ingredient environmental discharge profiles, while the EU Medical Device Regulation's borderline classifications influence how antiseptic-impregnated bathing devices access European markets. Stakeholders must monitor evolving antiseptic resistance surveillance data and regulatory reclassification movements that could reshape competitive moats around established active ingredients.
Market Dynamics
Hospital infection prevention bundles are compressing purchasing decisions around antiseptic bathing protocols, with bundled payment penalties for surgical site infections forcing procurement departments to standardize on preoperative skin preparation systems that demonstrate measurable microbial load reduction.
Growth Catalysts
- CMS Surgical Site Infection Penalties:US health systems face reimbursement reductions for preventable infections, accelerating compliance with antiseptic bathing protocols that demonstrate clinical efficacy.
- Chlorhexidine Gluconate Formulation Advances:Extended-release CHG formulations improve skin persistence, reducing application frequency while maintaining antimicrobial coverage through surgical procedures.
- Ambulatory Surgical Center Expansion:Outpatient procedure volume concentrates in freestanding ASCs, creating demand for rapid-application antiseptic formats that minimize preoperative preparation time.
Market Restraints
- Isopropyl Alcohol Feedstock Volatility:Petroleum-derived alcohol prices fluctuate with crude oil markets, compressing margins for povidone-iodine and CHG-alcohol combination products.
- Active Ingredient Concentration Risk:Indian and Chinese API manufacturers supply concentrated chlorhexidine base, creating geographic concentration vulnerability for North American and European formulators.
- Antiseptic Resistance Surveillance Gaps:Incomplete longitudinal data on CHG-resistant organism emergence limits evidence-based protocol updates and creates liability exposure for health systems.
Strategic Opportunities
- Home Care Post-Discharge Protocols:Aging-in-place demographics and shortened hospital stays create demand for consumer-formatted antiseptic bathing products with simplified application instructions.
- EU Medical Device Regulation Convergence:MDR borderline classifications for antiseptic-impregnated bathing cloths create pathway for premium-priced device-drug combination products in European markets.
- Telehealth-Integrated Compliance Monitoring:Remote patient monitoring platforms enable verification of home-based antiseptic bathing adherence, opening subscription revenue models for surgical preparation kits.
Industry Challenges
- Clinical Affairs Specialist Scarcity:Health systems lack personnel to design and audit antiseptic bathing compliance protocols, slowing standardized implementation across surgical service lines.
- Multisite Certification Complexity:Health system consolidations require harmonizing antiseptic protocols across acquired facilities with disparate legacy supplier contracts and formulary preferences.
- Environmental Discharge Compliance:EPA antimicrobial pesticide regulations constrain CHG-containing wastewater disposal, requiring capital investment in on-site treatment systems for high-volume bathing kit manufacturing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antiseptic Bathing Market |
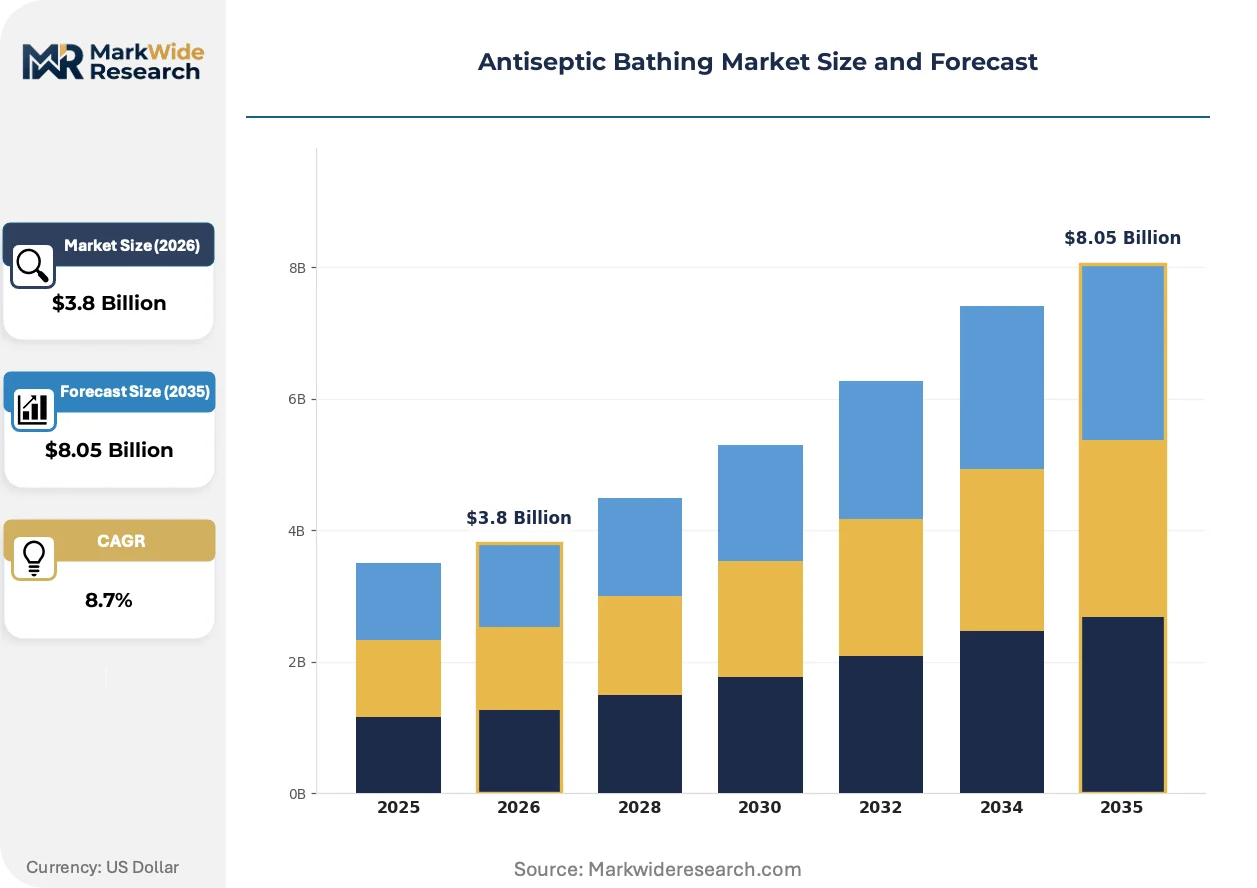
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Antiseptics, Foaming Antiseptics, Antiseptic Wipes, Foam Basins Application: Preoperative, Postoperative, Daily Hygiene, Infection Control End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Distribution Channel: Online Retail, Pharmacies, Supermarkets, Direct Sales |
| Companies Covered | 3M Company, Becton Dickinson and Company, Ecolab Inc., The Clorox Company, Medline Industries, Stryker Corporation, Mölnlycke Health Care, Reckitt Benckiser Group, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antiseptic Bathing Market Emerging Trajectories
Digital integration and formulation chemistry are converging to reshape how antiseptic bathing products demonstrate value, with connected devices and extended-release technologies replacing passive compliance models.
Smart dispensing systems with RFID-enabled compliance tracking are virtualizing audit workflows for infection prevention departments. Hospital systems in the United States deploy these units to capture timestamped bathing event data automatically. This infrastructure compresses manual documentation burden while generating defensible evidence for regulatory surveys and malpractice defense.
REACH restrictions on persistent organic pollutants are tightening formulation disclosure requirements for antiseptic active ingredients entering European markets. Manufacturers must submit expanded safety dossiers for CHG metabolites and povidone-iodine degradation products. German and French health technology assessment bodies now require environmental fate data as a condition of formulary inclusion, favoring suppliers with complete lifecycle documentation.
Buying committees are consolidating vendor relationships for preoperative preparation products, replacing fragmented purchasing across surgical, nursing, and materials management departments. Integrated delivery networks in the United States negotiate systemwide contracts for antiseptic bathing kits, displacing individual hospital autonomy. This concentration shifts negotiation leverage toward distributors with comprehensive infection prevention portfolios and away from single-product specialists.
Antiseptic Bathing Market Segmentation
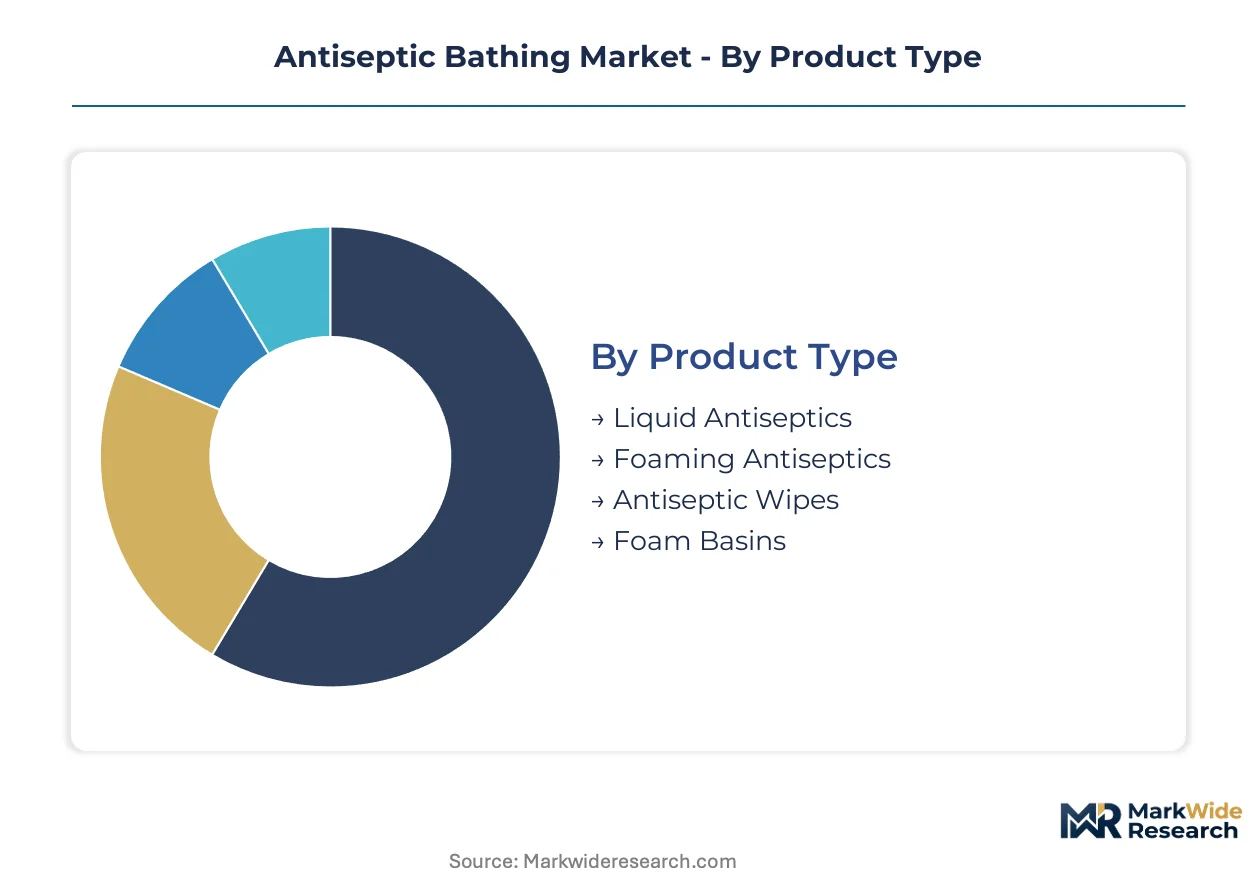
Antiseptic bathing procurement cycles vary dramatically across product formats and care settings. Understanding these velocity differences helps suppliers align inventory models with actual consumption patterns rather than aggregated demand assumptions.
Product Type:
Turnover velocity separates liquid formats with established hospital contracts from wipes and foams chasing ambulatory and retail expansion. Extended-release formulations are compressing reapplication frequency for institutional buyers.
- Liquid Antiseptics:Bulk chlorhexidine gluconate and povidone-iodine solutions in liter containers dominate surgical prep protocols requiring precise concentration control. Hospital infection prevention bundles in the United States standardize on 2% CHG liquid protocols to satisfy CMS surgical site infection penalty avoidance.
- Foaming Antiseptics:Pump-dispensed foam reduces drip and application time, capturing ambulatory surgical center procurement where patient throughput dictates equipment choices. Outpatient facilities in Texas and Florida surgical corridors specify foam for its faster skin coverage and reduced linen contamination.
- Antiseptic Wipes:Pre-saturated CHG cloths in individual packaging serve post-discharge home care protocols and emergency department rapid prep.
- Foam Basins:Impregnated basin systems for bedridden patient bathing concentrate in long-term care facilities managing pressure injury prevention alongside infection control.
Liquid antiseptics anchor the volume base while foaming antiseptics gain share at the steepest rate.
Application:
Reimbursement pressure intensity varies sharply across the application spectrum, with surgical timing constraints forcing premium pricing tolerance absent in daily hygiene maintenance contracts.
- Preoperative:Skin preparation immediately before incision commands the strictest formulation standards and highest compliance monitoring. Bundled payment penalties for surgical site infections in US health systems concentrate procurement authority around preoperative protocols with documented microbial load reduction.
- Postoperative:Wound-adjacent bathing during recovery reduces secondary infection risk, particularly for orthopedic and cardiac surgery patients with prolonged healing windows. Home care agencies in Medicare Advantage networks specify postoperative bathing kits for 30-day readmission reduction programs.
- Daily Hygiene:Routine patient bathing in long-term care applies lower-concentration antiseptic maintenance to suppress endemic resistant organisms.
- Infection Control:Outbreak response bathing with accelerated application frequency targets unit-specific containment rather than individual patient protocols.
Preoperative application commands the revenue concentration while home care postoperative protocols climb fastest as hospital stays compress.
End User:
Buying committee complexity scales with organizational size, from single-nurse home care decisions to multi-department hospital value analysis committees.
- Hospitals:Integrated delivery networks negotiate systemwide antiseptic bathing contracts spanning surgical, nursing, and infection prevention departments. Three-hospital systems in the Midwest United States recently consolidated from seven suppliers to two infection prevention portfolio vendors.
- Clinics:Physician-owned ambulatory surgery centers prioritize rapid-application formats and disposable convenience over bulk economy.
- Home Care:Post-acute agencies serving aging-in-place populations drive consumer-formatted demand with simplified instructions and telehealth-compatible compliance verification.
- Long-term Care Facilities:Nursing homes balance pressure injury prevention with infection control in bathing protocols for immobile residents.
Hospitals anchor procurement volume concentration while home care agencies expand most quickly on discharge compression trends.
Distribution Channel:
Channel selection reflects urgency requirements and formulary control intensity, with direct sales capturing institutional compliance documentation needs that retail channels cannot satisfy.
- Direct Sales:Manufacturer representatives contract with health system value analysis committees for multi-year antiseptic bathing protocol standardization. 3M and Medline field organizations maintain dedicated clinical specialists for infection prevention bundle integration.
- Pharmacies:Hospital outpatient and discharge prescription fulfillment concentrates specialty antiseptic formulations with insurance coverage verification.
- Online Retail:Consumer-directed purchasing of postoperative bathing kits bypasses institutional procurement for patient-pay home care segments.
- Supermarkets:Mass retail carries limited antiseptic soap variants without the CHG concentrations required for surgical preparation.
Direct sales channels capture the institutional revenue base while online retail climbs fastest on home care segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antiseptic bathing supply chains concentrate in North America and Western Europe, where hospital procurement standardization and regulatory stringency drive premium product demand. Manufacturing capacity expansion in South Asia is redirecting export flows toward cost-sensitive markets.
United States
CMS bundled payment penalties for surgical site infections compel health systems to standardize preoperative CHG protocols. FDA premarket notification requirements for antiseptic drug products enforce rigorous clinical evidence standards for new entrants. The Texas Medical Center in Houston anchors procurement volume for ambulatory surgical centers across the Gulf Coast surgical corridor.
Germany
Hospital infection prevention bundles in Bavaria and North Rhine-Westphalia mandate documented microbial load reduction before reimbursement approval. REACH restrictions on persistent organic pollutants require expanded safety dossiers for CHG metabolites and environmental fate data. The Frankfurt-Rhine-Main medical technology cluster hosts formulation specialists serving EU MDR borderline classification consulting for device-drug combination products.
India
Domestic API manufacturing scales for chlorhexidine base supply to North American and European formulators at cost-competitive export pricing. CDSCO manufacturing facility inspections align with FDA and EMA standards for active pharmaceutical ingredient export certification. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates contract manufacturing for antiseptic formulations targeting Middle Eastern and African markets.
United Kingdom
NHS infection prevention procurement frameworks consolidate antiseptic bathing contracts through national tender processes. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR borderline classifications for antiseptic-impregnated devices. The Greater Manchester health innovation cluster pilots smart dispensing systems with RFID-enabled compliance tracking for surgical site infection reduction.
Japan
Aging demographics and extended hospital stays for orthopedic procedures sustain demand for postoperative antiseptic bathing protocols. PMDA pharmaceutical affairs consultation procedures govern novel extended-release CHG formulation approvals. The Kansai medical device manufacturing belt around Osaka supplies pre-saturated antiseptic wipes for domestic hospital procurement and Southeast Asian export markets.
Antiseptic Bathing Market Vendor Landscape
Diversified health care conglomerates and specialized infection prevention suppliers split the market into distinct capability tiers. Consolidation pressures intensify as integrated delivery networks reduce supplier counts from seven to two infection prevention portfolio vendors. Three archetypes dominate: adhesive and skin health specialists, extensive distribution network operators, and advanced wound care adjacency extenders. Competitive moves center on multi-year value analysis committee contracts and clinical specialist field organization expansion.
Within the diversified health care tier, 3M Company leverages its adhesive and skin health portfolio to anchor hospital-grade antiseptic delivery systems. Medline Industries occupies a position as the extensive North American distribution network operator for preoperative bathing kits. Mölnlycke Health Care exemplifies the wound care adjacency extender archetype, with protocols extending into surgical patient hygiene from advanced wound care foundations.
| Leading Market Players |
|---|
| 3M Company |
| Becton Dickinson and Company |
| Ecolab Inc. |
| The Clorox Company |
| Medline Industries |
| Stryker Corporation |
| Mölnlycke Health Care |
| Reckitt Benckiser Group |
| Air Liquide |
| Others |
Supply Flow & Price Mechanics
API concentration vulnerability in Indian and Chinese chlorhexidine base manufacturing determines both the spread between premium device-drug combinations and commodity formulations and the geographic configuration of formulator supply networks. Buyers in North American and European health systems absorb cost volatility through contract tiering while domestic manufacturers in those markets invest in captive synthesis capacity to decouple from feedstock exposure.
Pricing Analysis
FDA premarket notification requirements dictate the pricing tier structure for antiseptic bathing products entering US hospital procurement. Three-tier pricing separates extended-release CHG formulations with clinical evidence packages from standard liquid protocols and economy povidone-iodine alternatives. Pricing pressure stems from CMS bundled payment penalties compressing procurement budgets for surgical site infection prevention. Ambulatory surgical centers exhibit highest price sensitivity due to throughput-driven equipment choices, while integrated delivery networks tolerate premium tiers for compliance documentation capabilities.
Supply Chain Analysis
Contract manufacturing concentration in the Hyderabad-Visakhapatnam pharmaceutical corridor and the Zhejiang chemical processing belt holds capacity for chlorhexidine base and povidone-iodine intermediate production. Active pharmaceutical ingredient supply draws from Indian API specialists and Chinese chemical intermediates producers, with formulation finishing concentrated in US Midwest and German Rhine-Ruhr industrial zones. Single-source vulnerability runs through concentrated Indian export certification for CHG base supply. Distribution runs through Medline Industries and 3M field organizations for institutional accounts, with direct-to-hospital contracts capturing compliance documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antiseptic bathing procurement is approaching a platform-economics inflection as telehealth-integrated compliance monitoring creates subscription revenue models and smart dispensing systems virtualize audit workflows. Interoperability between RFID-enabled bathing event capture and electronic health record systems will determine vendor stickiness.
For Market Incumbents: Pre-empt emerging entrant pressure in home care post-discharge protocols by acquiring telehealth platform capabilities or partnering with remote patient monitoring specialists. Defend hospital system contracts through backward integration into extended-release CHG formulation chemistry that creates switching costs. Expand clinical specialist field organizations to capture value analysis committee consolidation from seven suppliers to two infection prevention portfolio vendors.
For New Entrants and Emerging Players: Build out consumer-formatted antiseptic bathing kits with simplified application instructions targeting Medicare Advantage home care agencies managing 30-day readmission reduction programs. Penetrate the Texas and Florida ambulatory surgical center corridors with rapid-application foam formats that minimize preoperative preparation time. Pursue direct-to-consumer online retail channels bypassing institutional procurement for patient-pay segments.
For Investors and Strategic Acquirers: EU Medical Device Regulation borderline classification convergence reshapes the acquisition landscape toward device-drug combination product specialists with complete lifecycle documentation. Long-term viability rests on formulary inclusion durability across German and French health technology assessment bodies requiring environmental fate data. Target acquisition archetypes include antiseptic-impregnated bathing cloth manufacturers with MDR technical file readiness. Monitor CDSCO manufacturing facility inspection alignment with FDA standards as inflection indicator for Indian API supply reliability.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Formulation Development | Patent-protected CHG persistence technology captures premium hospital procurement tiers. |
| Smart Dispensing System Deployment | RFID-enabled compliance tracking generates defensible evidence for CMS regulatory surveys. |
| EU MDR Technical File Investment | Complete lifecycle documentation satisfies German and French health technology assessment requirements. |
| Telehealth Platform Integration | Remote adherence verification opens subscription revenue models for post-discharge bathing kits. |
| Captive API Manufacturing Buildout | In-house chlorhexidine base production decouples North American formulators from Indian supply concentration. |
Methodological Framework
Cross-validation between infection prevention department purchasing records and FDA premarket notification filings anchors the qualitative findings for this analysis. Primary interviews with hospital value analysis committee chairs, GPO contracts managers, biomedical engineers, and infection prevention specialists were combined with secondary validation from CMS Medicare cost report data, EPA antimicrobial pesticide registration databases, hospital procurement contract disclosures, and EU MDR borderline classification guidance documents. Bottom-up consumption modeling and top-down health system expenditure triangulation were applied.
Calibration against historical surgical site infection penalty implementation and antiseptic protocol adoption curves informed the projection framework. Segmentation dimensions modeled include product format, application timing, end-user facility type, and distribution channel structure across the analysis window. CAGRs were derived from elasticity-adjusted consumption trajectories and reimbursement policy phase-in schedules. Forecast inputs incorporated REACH restriction timelines for persistent organic pollutants and CDSCO inspection alignment patterns with FDA standards.
Stress conditions across API export certification disruption, CMS penalty severity adjustment, and REACH formulation disclosure expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding health system consolidation velocity and regulatory reclassification movements. Quarterly review of FDA premarket notification approval cadence and EU MDR technical file submission rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infection Control
Salivary Gland Infection Market
Infection Control
Sterilization Monitoring Market
Infection Control
Ear Infection Treatment Market
Infection Control
Community Acquired Pneumonia (CAP) Market
Infection Control
Hospital Acquired Infections Market
Infection Control
Sterilization Market
Infection Control
United States Hand Sanitizer Market
Infection Control
Hand Hygiene Products Market
Infection Control
New Zealand Healthcare Surface Disinfectant Wipes Market
Infection Control
Infection Surveillance Solutions Market
Infection Control
Medical Disinfectant Wipes Market
Infection Control
Infection Prevention Market
Infection Control
Yeast Infection Market
Infection Control
Europe Ultrasound Probe Disinfection Market
Infection Control
Infection Control Supplies Market
Infection Control
Point of Care Infection Control Market