
 Endocrine Peptides Test Market | 2026-2036
Endocrine Peptides Test Market Size, Share, and Industry Trends Forecast 2026-2036
Endocrine Peptides Test Market Foresight
Multiplexed immunoassay platforms is reshaping how endocrine peptide panels are configured for high-throughput clinical workflows. Siemens Healthineers leverages integrated analyzer systems to sustain automation leadership in hospital core laboratories. Abbott Laboratories anchors its competitive position through point-of-care connectivity that extends testing beyond centralized facilities. Roche Diagnostics dominates immunochemistry menu breadth, competing on assay standardization across decentralized networks.
Endocrine peptides test refers to analytical procedures that quantify peptide hormones—typically 3–100 amino acid residues—using antibody-based or mass spectrometric detection to assess metabolic and hormonal homeostasis. These tests serve primary commercial purpose in diagnosing insulin dysregulation, growth hormone deficiency, and neuroendocrine tumor markers through serum or plasma specimen analysis. Immunoassay technology occupies the largest installed base due to regulatory familiarity and workflow integration, while mass spectrometry segments are gaining structural traction where laboratories require simultaneous quantification of multiple peptide analogs without antibody cross-reactivity. Diabetes management application leads volume demand given population screening mandates, though cancer research segments command premium positioning through specialized reference laboratory channels.
FDA 510(k) pathways and EMA in vitro diagnostic regulations shape assay commercialization timelines and clinical claim substantiation requirements for manufacturers entering respective markets. CLIA proficiency standards and ISO 15189 accreditation frameworks govern laboratory operational eligibility, directly constraining addressable end-user expansion. Stakeholders must monitor evolving biomarker qualification criteria from both FDA and EMA as peptide signatures migrate from research utility to companion diagnostic status.
Market Dynamics
Multiplexed immunoassay platforms are compressing turnaround times for peptide hormone panels, forcing laboratories to reconfigure workflows around high-throughput automation rather than batch-processing legacy systems.
Growth Catalysts
- CLIA Proficiency Standards:United States laboratory accreditation requirements mandate quality control protocols that expand peptide testing infrastructure in hospital networks.
- Diabetes Management Protocols:Population screening mandates for insulin dysregulation drive recurring test volume through primary care channels.
- Mass Spectrometry Convergence:LC-MS/MS platforms enable simultaneous quantification of multiple peptide analogs without antibody cross-reactivity constraints.
Market Restraints
- Antibody Supply Concentration:Reagent sourcing depends on a limited supplier base concentrated in North America and Western Europe, creating procurement vulnerability.
- ISO 15189 Accreditation Burden:Laboratory operational eligibility requirements constrain addressable end-user expansion in emerging markets.
- Mass Spectrometer Capex Intensity:Instrument acquisition costs exceed immunoassay platforms by substantial multiples, limiting adoption to reference laboratories.
Strategic Opportunities
- Point-of-Care Channel Extension:Decentralized testing networks in Germany and Japan create demand for compact peptide analyzers outside hospital core laboratories.
- Companion Diagnostic Migration:FDA biomarker qualification criteria evolution positions peptide signatures for oncology therapeutic pairing.
- Neuroendocrine Tumor Markers:Specialized reference laboratory channels command premium positioning for chromogranin A and synaptophysin panels.
Industry Challenges
- Mass Spectrometry Operator Training:LC-MS/MS systems require specialized technical expertise that outpaces current laboratory workforce development pipelines.
- Assay Standardization Delays:Harmonization between immunoassay and mass spectrometry methodologies creates inter-laboratory variability disputes.
- Legacy Analyzer Integration:Hospital core laboratories face workflow friction when embedding novel peptide panels into existing Siemens and Roche instrument ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endocrine Peptides Test Market |
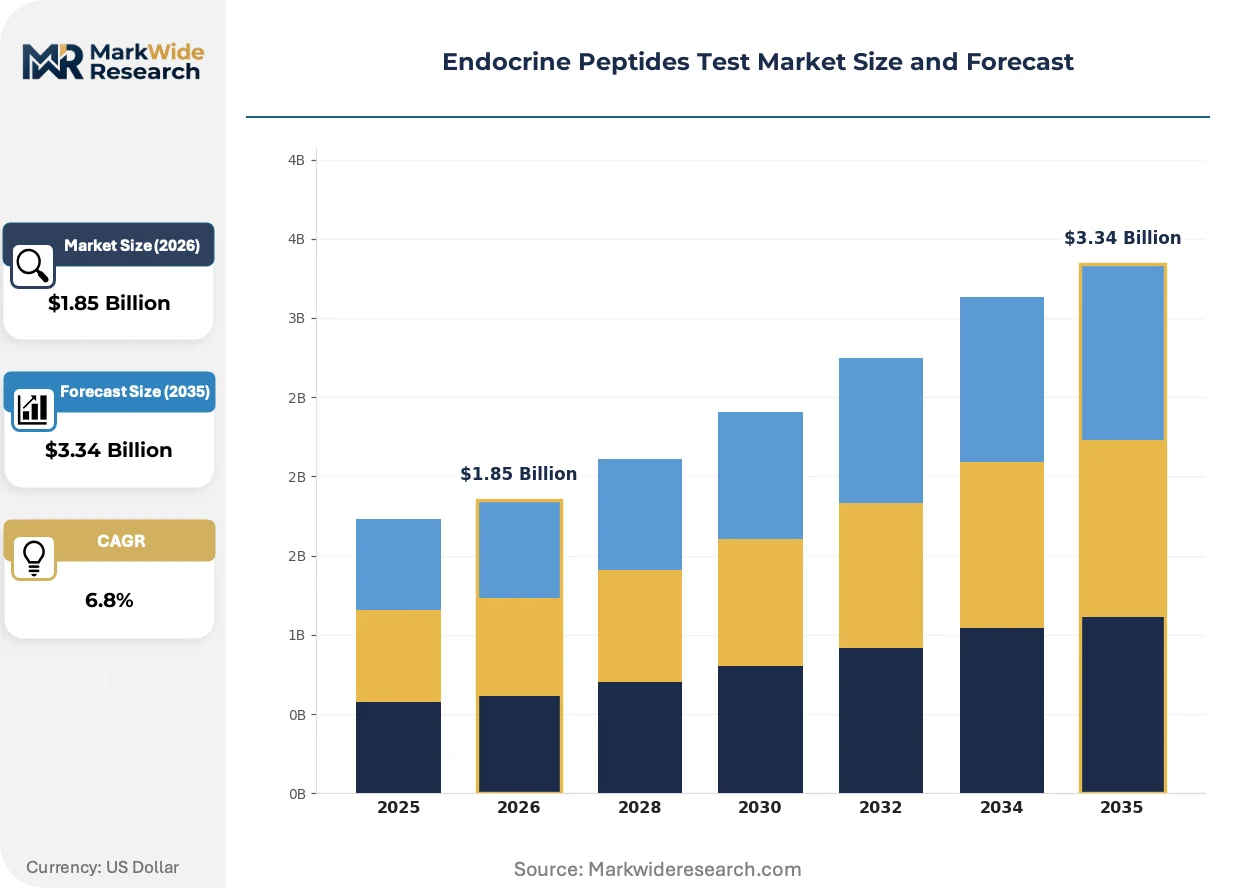
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin, Glucagon, Somatostatin, Ghrelin Technology: ELISA, Mass Spectrometry, Immunoassay, Western Blot End User: Hospitals, Clinical Laboratories, Research Institutes, Diagnostic Centers Application: Diabetes Management, Hormonal Disorder Diagnosis, Cancer Research, Metabolic Disorder Analysis |
| Companies Covered | Quest Diagnostics, Siemens Healthineers, Abbott Laboratories, bioMérieux, Agilent Technologies, Bio-Rad Laboratories, Thermo Fisher Scientific, Laboratory Corporation of America Holdings, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endocrine Peptides Test Market Shifts & Advancements
Detection methodology divergence is splitting the installed base between antibody-dependent and antibody-free quantification approaches, with each trajectory demanding distinct capital allocation and staffing models from laboratory operators.
High-resolution mass spectrometry platforms are rendering obsolete single-analyte immunoassay workflows for complex peptide panels. Reference laboratories in the United States and Germany are adopting LC-MS/MS systems at accelerated replacement cycles. This technology shift is compressing the addressable market for conventional radioimmunoassay reagents.
EMA In Vitro Diagnostic Regulation implementation is restructuring assay commercialization timelines across European markets. Manufacturers must now substantiate clinical claims through expanded performance studies before CE marking authorization. Oncology biomarker segments face the steepest compliance burden as peptide signatures advance toward companion diagnostic classification.
Consolidated procurement by hospital network purchasing organizations is displacing independent laboratory reagent sourcing. Integrated delivery networks in the United States now negotiate system-wide analyzer and consumable contracts directly with Siemens Healthineers and Abbott Laboratories. This concentration is most visible in diabetes management testing where volume commitments dictate platform standardization across multi-site deployments.
Endocrine Peptides Test Market Segmentation
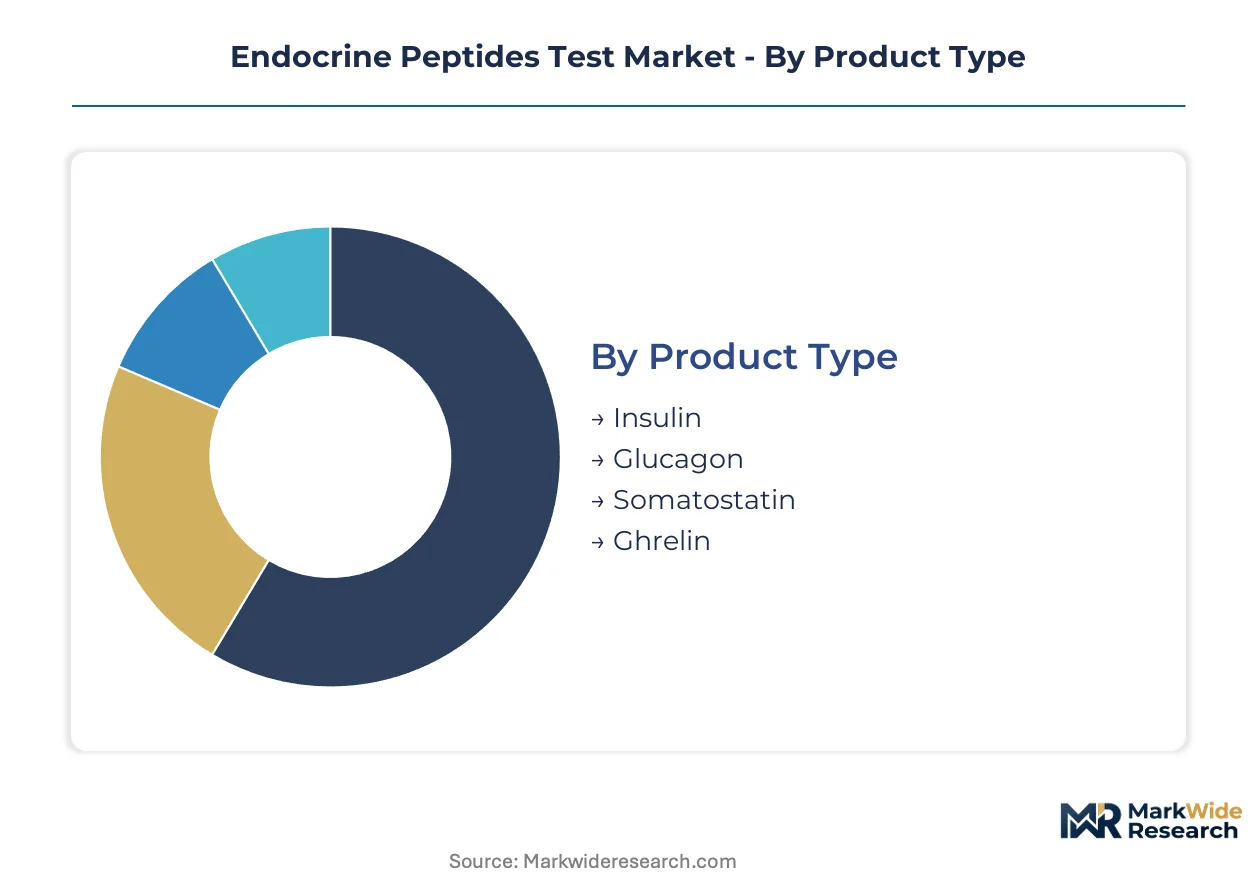
Endocrine peptide testing fragments across four structural dimensions that shape procurement patterns, regulatory pathways, and margin architecture. Product type determines reagent chemistry requirements. Technology selection drives capital deployment and workforce competency. End-user concentration governs distribution channel design. Application focus dictates reimbursement codes and clinical claim substantiation burdens.
Product Type:
Cost tier stratification across peptide hormone panels separates high-volume screening reagents from specialized research-grade materials.
- Insulin:Quantifies circulating insulin levels using antibody-based detection for glucose homeostasis assessment. Hospital laboratories in the United States process the highest screening volumes under diabetes management protocols mandated by payer networks.
- Glucagon:Measures pancreatic alpha-cell secretion to evaluate counter-regulatory response in hypoglycemic episodes. German clinical laboratories concentrate demand for glucagon panels within integrated diabetes care networks.
- Somatostatin:Detects growth hormone inhibitory peptide for neuroendocrine tumor monitoring. Research institutes in Japan deploy somatostatin assays for specialized oncology biomarker studies.
- Ghrelin:Quantifies appetite-regulating hormone for metabolic syndrome research. Academic medical centers source ghrelin reagents through limited-distribution reference laboratory channels.
Insulin commands the established base. The steepest expansion runs through somatostatin.
Technology:
Application requirements split the installed base between high-throughput automation platforms and specialized analytical instrumentation.
- Mass Spectrometry:LC-MS/MS platforms enable simultaneous quantification of multiple peptide analogs without antibody cross-reactivity constraints. Reference laboratories in Germany and the United States deploy these systems for complex metabolic panels requiring absolute specificity.
- Immunoassay:Chemiluminescent and electrochemiluminescent analyzers dominate hospital core laboratory workflows through regulatory familiarity and Siemens Healthineers ecosystem integration.
- ELISA:Enzyme-linked immunosorbent assays serve research institutes and smaller diagnostic centers with lower throughput requirements and limited capital budgets.
- Western Blot:Semi-quantitative protein detection supports academic research settings where molecular weight confirmation supplements concentration measurement.
Immunoassay anchors current infrastructure. Mass spectrometry is climbing the fastest as reference laboratories replace legacy radioimmunoassay capacity.
End User:
Customer type concentration determines pricing power, contract structure, and service attachment rates across the value chain.
- Hospitals:Integrated delivery networks negotiate system-wide analyzer contracts with volume commitments that standardize peptide testing menus across multi-site deployments.
- Clinical Laboratories:Independent and hospital-affiliated labs process routine screening panels under CLIA proficiency standards that mandate quality control infrastructure investment.
- Research Institutes:Academic medical centers and biotechnology firms procure specialized peptide assays for biomarker discovery and companion diagnostic development programs.
- Diagnostic Centers:Outpatient facilities concentrate point-of-care testing demand in Germany and Japan where decentralized networks extend access beyond hospital core laboratories.
Hospitals lock in the largest reagent commitments. Diagnostic centers are gaining share fastest through point-of-care channel extension.
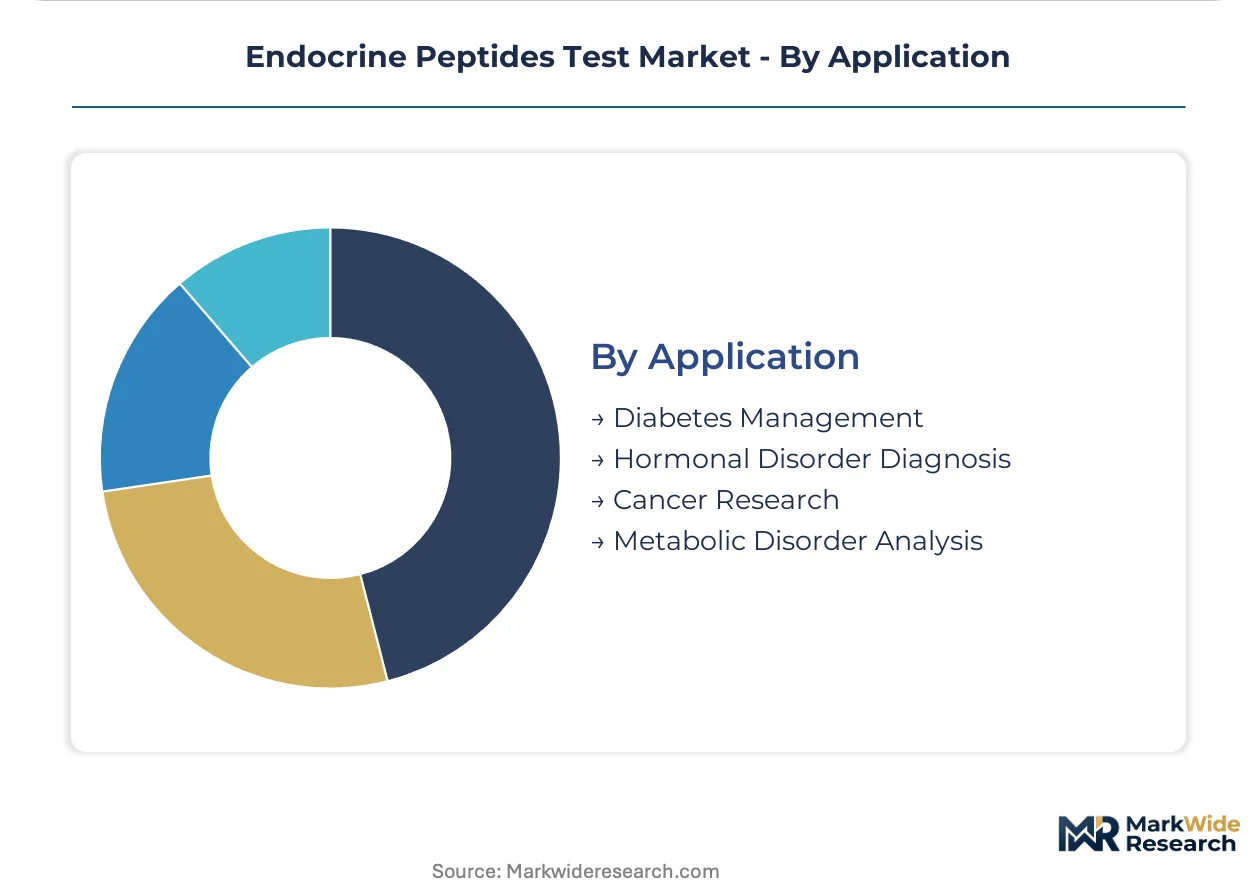
Application:
Volume distribution across clinical use cases separates recurring screening demand from premium-priced specialized testing.
- Diabetes Management:Population screening mandates for insulin dysregulation drive recurring test volume through primary care channels in the United States and Germany.
- Cancer Research:Neuroendocrine tumor marker panels command premium positioning through specialized reference laboratory channels with extended turnaround times.
- Hormonal Disorder Diagnosis:Growth hormone deficiency and thyroid dysfunction testing supports pediatric and reproductive endocrinology practices.
- Metabolic Disorder Analysis:Obesity and metabolic syndrome research programs in Japan deploy comprehensive peptide panels for longitudinal cohort studies.
Diabetes management holds the volume base. Cancer research is expanding most quickly as peptide signatures advance toward companion diagnostic classification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement offices in the United States, Germany, and Japan concentrate the highest reagent contract values, while clinical laboratories in these markets drive installed base expansion for automated peptide hormone analyzers.
United States
Integrated delivery networks in Texas and California negotiate system-wide analyzer contracts that standardize insulin testing menus across multi-site hospital deployments. FDA 510(k) clearance pathways streamline commercialization timelines for novel biomarker assays entering the market. The Boston-Cambridge corridor anchors specialized reference laboratory capacity for neuroendocrine tumor marker panels.
Germany
Decentralized diagnostic networks in Bavaria and North Rhine-Westphalia create demand for compact peptide analyzers extending beyond hospital core laboratories. EMA In Vitro Diagnostic Regulation implementation restructures assay commercialization timelines through expanded performance study requirements. The Rhine-Main cluster concentrates LC-MS/MS platform adoption for complex metabolic panels requiring absolute specificity.
Japan
Research institutes in Tokyo and Osaka deploy comprehensive peptide panels for longitudinal metabolic syndrome cohort studies. PMDA regulatory frameworks govern in vitro diagnostic authorization timelines for manufacturers entering the domestic market. The Kansai region specializes in somatostatin assay procurement for oncology biomarker development programs.
United Kingdom
NHS procurement frameworks in London and the Southeast concentrate diabetes management testing volume through primary care screening mandates. MHRA post-Brexit regulatory alignment creates transitional compliance burdens for assay manufacturers seeking UKCA marking. The Oxford-Cambridge arc hosts academic medical centers sourcing ghrelin reagents through limited-distribution reference channels.
China
Tier-three hospitals in Shanghai and Beijing expand peptide hormone testing infrastructure under chronic disease monitoring protocols. NMPA medical device registration requirements extend commercialization timelines for imported assay platforms. The Yangtze River Delta cluster attracts domestic manufacturers developing localized immunoassay reagent production capacity.
Endocrine Peptides Test Market Competitive Landscape
Channel-controlling players compete with product-specialist players across analyzer placement, reagent supply contracts, and service attachment rates. The installed base concentrates around three to five diversified diagnostics conglomerates with integrated hospital network relationships. Strategic archetypes include full-menu immunochemistry providers, mass spectrometry platform specialists, and point-of-care connectivity vendors. Dominant competitive moves encompass analyzer ecosystem lock-in through consumable bundling and reference laboratory partnerships for complex panel validation.
Among United States-based diagnostics conglomerates, Quest Diagnostics and Laboratory Corporation of America Holdings occupy positions as channel-controlling laboratory service providers. Siemens Healthineers, a German GmbH, exemplifies the full-menu immunochemistry archetype through integrated analyzer system deployment. Roche Diagnostics, a Swiss-headquartered division, represents standardization-focused competition across decentralized network configurations. These three entities anchor distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Siemens Healthineers |
| Abbott Laboratories |
| bioMérieux |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Thermo Fisher Scientific |
| Laboratory Corporation of America Holdings |
| Roche Diagnostics |
| Others |
Supply & Pricing Matrix
Overcapacity in immunoassay reagent manufacturing across North America and Western Europe is compressing margins for antibody suppliers while simultaneously expanding pricing leverage for integrated hospital networks negotiating multi-year analyzer contracts. This utilization asymmetry drives tiered procurement strategies that separate high-volume screening reagents from specialized mass spectrometry consumables.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate reagent supply agreements between hospital purchasing organizations and diagnostics manufacturers in the United States and Germany. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic panels from CLIA-waived point-of-care assays and research-grade materials. Pricing pressure stems from consolidated procurement by integrated delivery networks demanding volume discounts for diabetes management screening. Clinical laboratories exhibit highest price sensitivity due to thin margins on routine insulin testing, while reference laboratories accept premium positioning for neuroendocrine tumor marker specificity.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized bioreagent producers in the United States, Germany, and Switzerland holding monoclonal antibody production capacity. Reagent chemistry draws from fetal bovine serum, recombinant protein substrates, and synthetic peptide standards sourced through qualified supplier networks. Single-source vulnerability characterizes rare isotope-labeled internal standards for LC-MS/MS quantification. Distribution runs through direct manufacturer-to-laboratory channels for high-value analyzers, with third-party distributors handling consumable replenishment for smaller clinical sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass spectrometry platform convergence represents a high-growth disruption reshaping competitive positioning, accelerated by EMA In Vitro Diagnostic Regulation implementation demanding expanded clinical performance substantiation.
For Market Incumbents: Pre-empt displacement of legacy immunoassay revenue streams by embedding LC-MS/MS compatibility into existing analyzer ecosystems. Siemens Healthineers and Roche Diagnostics must defend installed base through consumable bundling that locks hospital networks into proprietary reagent chemistry. Backward integration into antibody production reduces exposure to North American supplier concentration. For New Entrants and Emerging Players: Establish a beachhead in point-of-care peptide testing channels in Germany and Japan where decentralized diagnostic networks extend beyond hospital core laboratories. Neuroendocrine tumor marker panels offer the most penetrable segment given premium pricing tolerance and limited incumbent specialization. Pursue reference laboratory partnerships for complex panel validation to bypass direct analyzer placement competition. For Investors and Strategic Acquirers: Capital is best deployed toward mass spectrometry platform specialists with validated LC-MS/MS workflows for multiplexed peptide quantification. Long-term viability across the analysis window hinges on regulatory navigation capabilities as biomarker qualification criteria evolve. Watch FDA biomarker qualification determinations for peptide signatures advancing toward companion diagnostic status as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| LC-MS/MS Platform Integration | Reference laboratories in Germany adopt high-resolution systems to replace legacy radioimmunoassay capacity. |
| CE Marking Pathway Expansion | EMA performance study requirements extend commercialization timelines for oncology biomarker assay manufacturers. |
| Hospital System Partnership | Integrated delivery networks in Texas negotiate system-wide insulin testing standardization across multi-site deployments. |
| Software Companion Development | Abbott Laboratories extends point-of-care connectivity to capture decentralized testing demand beyond core laboratories. |
| Reimbursement Strategy | Diabetes management protocols in the United States mandate population screening that secures recurring test volume. |
Research Methodology
Desk research of FDA 510(k) filings, EMA CE marking databases, and hospital procurement records preceded structured interviews with clinical laboratory directors, diagnostics manufacturer regulatory affairs leads, and GPO contracts managers. Primary fieldwork with biomedical engineers and point-of-care testing coordinators was cross-validated against secondary sources including CLIA proficiency survey data and ISO 15189 accreditation registries. Bottom-up reagent volume estimates were triangulated with top-down analyzer placement data across the United States, Germany, and Japan.
Assumptions held fixed include EMA In Vitro Diagnostic Regulation implementation timelines and CLIA proficiency standard continuity, while mass spectrometry adoption curves and companion diagnostic qualification pathways were modeled as sensitivity variables. Segmentation dimensions spanned product type, technology platform, end-user concentration, and application focus with regional regulatory cluster differentiation. CAGRs were derived from instrument replacement cycle analysis and reagent consumption per installed analyzer across the projection horizon. Forecast inputs incorporated diabetes screening mandate expansion and neuroendocrine tumor marker research funding trajectories.
Stress conditions across antibody supply disruption, mass spectrometer capital expenditure freeze scenarios, and EMA performance study requirement escalation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with revision triggers tied to regulatory determination shifts. Quarterly review of FDA biomarker qualification determinations and hospital network purchasing organization consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Global Multiplex Assays Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
US at-Home Testing Kits Market
Testing Services
Tuberculosis Testing Market
Testing Services
India GMP Testing Service Market
Testing Services
Global Ovulation Test Market
Testing Services
Nicotine Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Preclinical Medical Device Testing Services Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Fungal Testing Kits Market
Testing Services
Pharmaceutical Sterility Testing Market