
 Global Plant Stem Cell Market | 2026-2036
Global Plant Stem Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plant Stem Cell Market Foresight
Shortages of trained phytochemists and cell-culture technicians are redrawing competitive boundaries in botanical active ingredient production. PhytoCellTec leverages proprietary suspension culture protocols to secure supply contracts with European formulators. Mibelle Biochemistry anchors its position through backward integration into rare apple varietal sourcing in Switzerland. Oriflame Holding competes via direct-to-consumer channel control across emerging beauty markets.
Plant stem cells refer to undifferentiated meristematic cells isolated from shoot apices, root tips, or cambial layers, maintained in vitro through callus induction or suspension culture to preserve totipotency and secondary metabolite yield; these cultures generate standardized extracts for cosmetic and therapeutic applications where batch-to-batch phytochemical consistency matters. Extracts and serums command premium positioning in anti-aging formulations, while nutraceutical capsules represent the fastest-expanding application channel as ingestible beauty gains traction in Asia-Pacific markets. Skin repair applications retain mature volume bases in dermatological clinics across Western Europe.
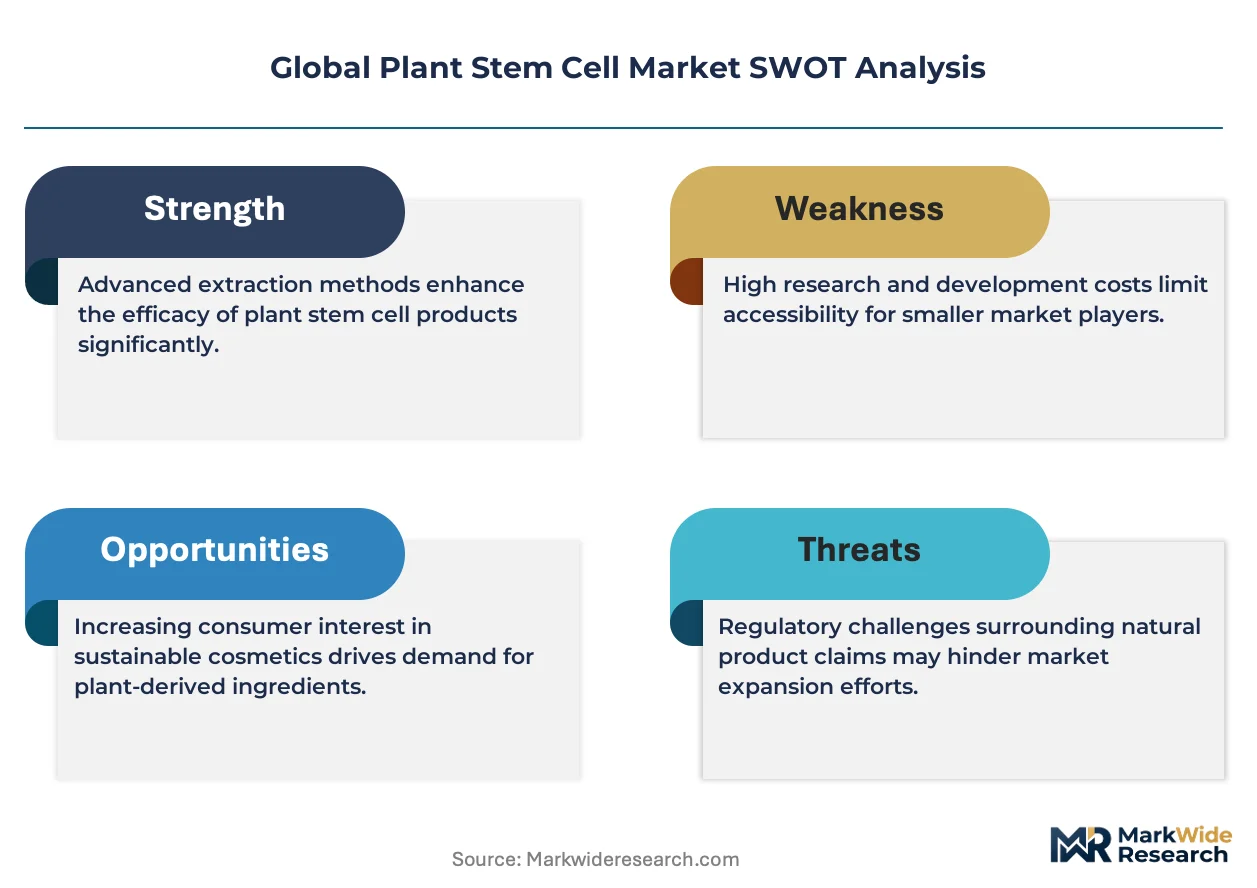
REACH registration requirements in Europe, FDA cosmetic ingredient guidance in the United States, and China's NMPA botanical-safety dossier rules collectively elevate barriers for unvalidated suppliers. EMA standards for plant-cell-derived biologics further constrain pharmaceutical-grade entrants lacking GMP-certified facilities. Stakeholders must monitor evolving substantiation requirements for stem-cell marketing claims across multiple jurisdictions.
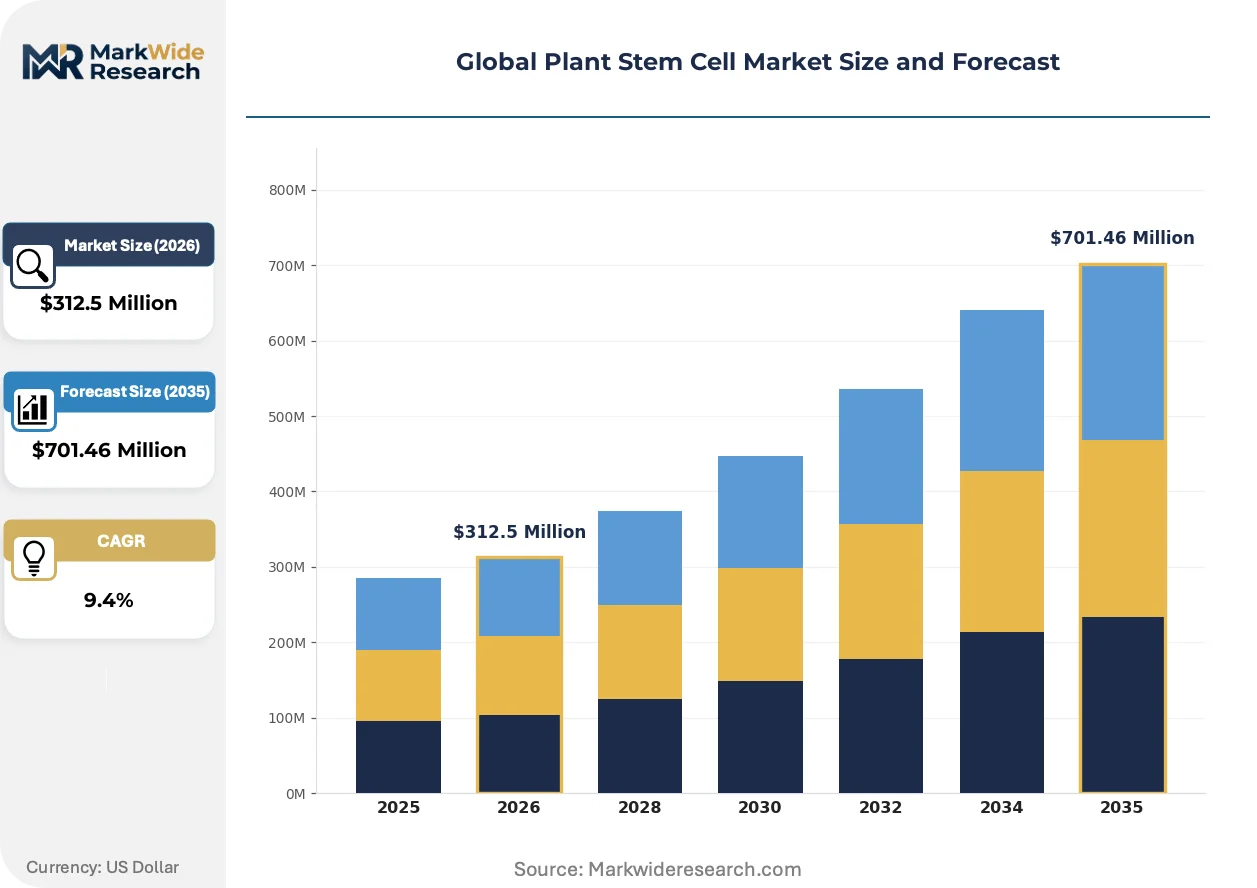
Market Dynamics
REACH dossier complexity and NMPA botanical-safety rules are forcing suppliers to consolidate around GMP-certified facilities, concentrating procurement power among European and East Asian formulators with validated supply chains.
Growth Catalysts
- Meristematic suspension culture:Standardized secondary metabolite yields enable cosmetic manufacturers to meet batch-to-batch consistency requirements for anti-aging serums without agricultural harvest volatility.
- MFDS cosmetic ingredient frameworks:South Korean regulatory clarity accelerates domestic procurement of plant-derived actives by Seoul-based beauty conglomerates seeking compliant raw material pipelines.
- Ingestible beauty demand:Nutraceutical capsules containing plant stem cell extracts gain traction among Asia-Pacific consumers pursuing skin health from within, opening volume channels beyond topical applications.
Market Restraints
- Phytochemist scarcity:Limited trained cell-culture technicians constrains production scale-up at facilities attempting to transition from research-grade to commercial-scale bioreactor operations.
- Swiss apple varietal concentration:Backward integration into rare cultivar sourcing by Mibelle Biochemistry and similar suppliers creates supply bottlenecks for competitors lacking captive orchards.
- EMA pharmaceutical-grade barriers:GMP certification requirements for plant-cell-derived biologics exclude unvalidated entrants from therapeutic applications, capping addressable market expansion.
Strategic Opportunities
- India nutraceutical penetration:FSSAI regulatory harmonization with global standards creates entry pathways for standardized plant stem cell capsules targeting domestic ingestible beauty demand.
- Bioreactor-digital twin convergence:Real-time metabolite monitoring combined with predictive modeling reduces culture failure rates and accelerates process optimization cycles.
- Dermatology clinic channels:Skin repair applications in Western European medical aesthetics practices offer premium pricing power through clinician-mediated distribution.
Industry Challenges
- Multi-jurisdiction claim substantiation:Divergent FDA cosmetic guidance, REACH marketing restrictions, and NMPA botanical dossier requirements force parallel compliance investments without harmonized standards.
- Callus-to-suspension transfer protocols:Technical variability in maintaining totipotency during scale-up generates batch failures that erode margin at commercial production volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plant Stem Cell Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Powders, Serums, Capsules, Ointments Application: Anti-aging, Skin Repair, Hair Regeneration, Cosmetics, Nutraceuticals End User: Pharmaceuticals, Personal Care, Research Institutes, Biotechnology Firms Form: Liquid, Solid, Gel, Emulsion, Spray |
| Companies Covered | Phyto Science, MyChelleDermaceuticals, Natura Therapeutics, PhytoCellTec, Renature Skin Care, Aidan Products, Oriflame Holding, Provital, Mibelle Biochemistry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plant Stem Cell Market Shifts & Advancements
Bioprocess engineering advances are compressing production timelines while regulatory convergence pressures reshape supplier qualification criteria across cosmetic and therapeutic applications.
Single-use bioreactor systems for plant cell suspension culture are miniaturizing capital requirements for mid-scale manufacturers. Contract manufacturers in Germany and Japan adopt 50-200 liter disposable vessels to serve niche cosmetic formulators without stainless-steel infrastructure investments. This technology is miniaturizing the minimum efficient scale for viable entry, fragmenting supply concentration previously held by large-cap integrated producers.
REACH registration deadlines for existing cosmetic ingredients tighten substantiation requirements for novel botanical actives. ECHA evaluation protocols now demand extensive safety data packages that extend qualification timelines by 18-24 months. European formulators respond by locking in multi-year supply contracts with pre-registered suppliers, freezing out newer entrants lacking grandfathered dossier status.
Direct-to-consumer channel expansion by beauty brands collapses traditional distributor markups for active ingredient procurement. Oriflame Holding and similar vertically integrated operators bypass wholesale intermediaries to capture margin in emerging markets. This disintermediation concentrates volume with suppliers capable of regulatory compliance documentation for finished-product marketing claims in Brazil, Saudi Arabia, and Southeast Asian jurisdictions.
Global Plant Stem Cell Market Segmentation
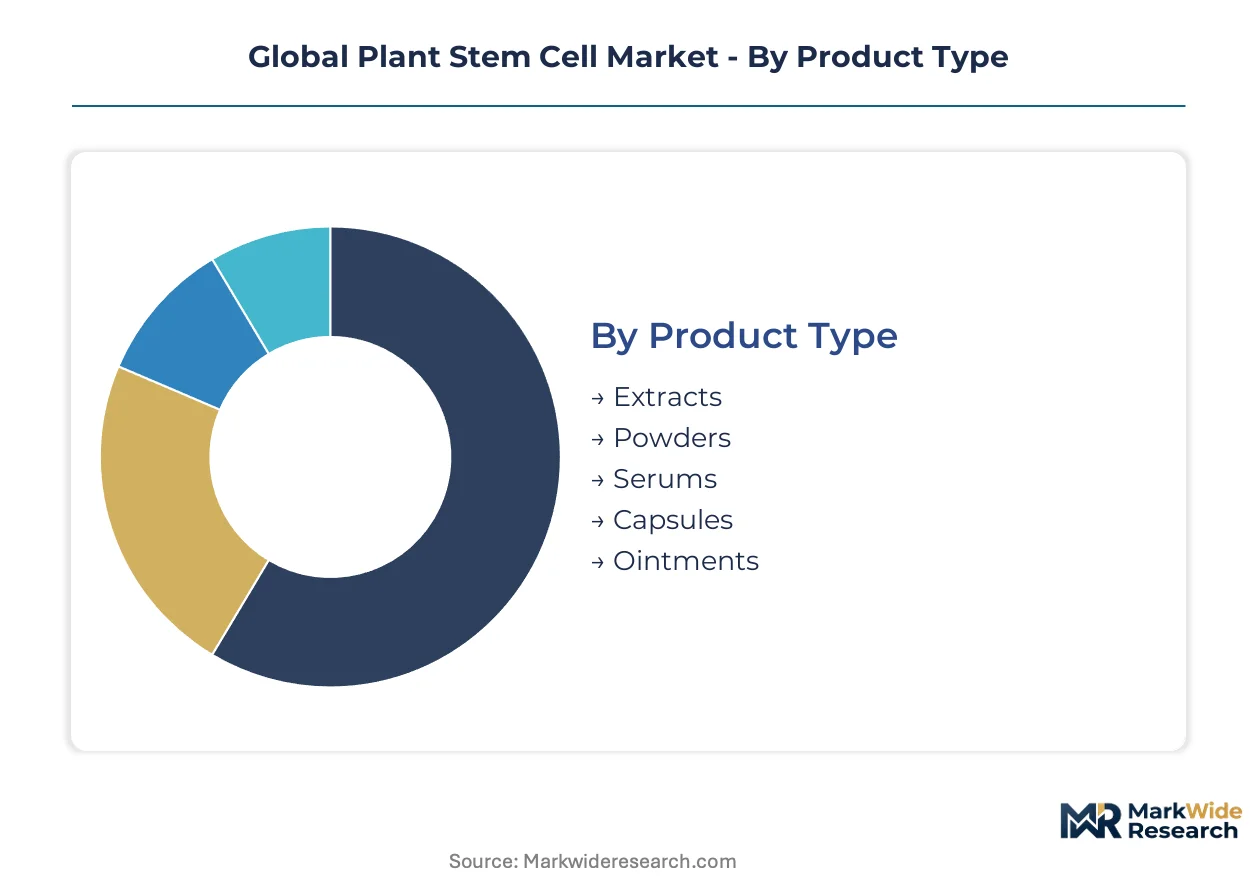
Segmentation in the plant stem cell market reflects divergent regulatory pathways across cosmetic, pharmaceutical, and nutraceutical channels. Each product category carries distinct substantiation burdens under FDA, EMA, and NMPA frameworks that determine viable commercial routes.
Product Type:
REACH dossier requirements and NMPA botanical-safety rules create tiered compliance costs that stratify supplier positioning across extract and finished-dosage formats.
- Extracts:Concentrated secondary metabolite preparations standardized for cosmetic formulators seeking batch-to-batch phytochemical consistency. Demand clusters with Seoul-based beauty conglomerates procuring compliant raw materials under MFDS frameworks.
- Serums:High-viscosity topical delivery systems incorporating stabilized meristematic cell lysates for anti-aging applications. Premium positioning in dermatological clinics across Germany and Switzerland justifies elevated pricing through clinician-mediated distribution channels.
- Powders:Lyophilized cell culture biomass for nutraceutical encapsulation.
- Capsules:Ingestible formats gaining traction in Asia-Pacific beauty-from-within segments.
- Ointments:Semi-solid preparations targeting skin repair indications in Western European medical aesthetics practices.
Extracts handle the majority of throughput; capsules are climbing the fastest on share as ingestible beauty gains regulatory clarity across Asian markets.
Application:
Customer procurement patterns split between clinician-mediated channels demanding GMP documentation and direct-to-consumer formats where marketing claim substantiation determines shelf access.
- Anti-aging:Topical formulations leveraging standardized meristematic extracts for collagen synthesis support. European formulators under REACH pressure lock in multi-year supply contracts with pre-registered suppliers, freezing out newer entrants lacking grandfathered dossier status.
- Nutraceuticals:Ingestible capsules and powders targeting skin health from within. FSSAI regulatory harmonization in India creates entry pathways for standardized plant stem cell products targeting domestic ingestible beauty demand.
- Skin Repair:Clinical-grade preparations for post-procedure dermatological care.
- Hair Regeneration:Scalp-targeted delivery systems addressing follicle stem cell signaling.
- Cosmetics:Mass-market topical products with lower substantiation thresholds than therapeutic claims.
Anti-aging commands mature volume bases; nutraceuticals represent the steepest expansion trajectory as Asia-Pacific consumers shift toward beauty-from-within consumption.
End User:
Facility certification requirements fragment addressable market access, with GMP-certified bioreactor operations serving pharmaceutical and clinical channels while research-grade facilities supply exploratory development.
- Pharmaceuticals:EMA pharmaceutical-grade barriers exclude unvalidated entrants from therapeutic applications, capping addressable market expansion for suppliers lacking certified facilities.
- Personal Care:Cosmetic manufacturers in South Korea expand procurement of plant-derived actives under clarified MFDS ingredient frameworks.
- Research Institutes:Academic and commercial R&D facilities requiring small-batch meristematic cultures for protocol development.
- Biotechnology Firms:Cell therapy developers seeking plant-derived biologics for preclinical and clinical pipeline advancement.
Personal care absorbs the largest procurement volumes; pharmaceuticals offer the highest per-unit pricing through regulatory scarcity.
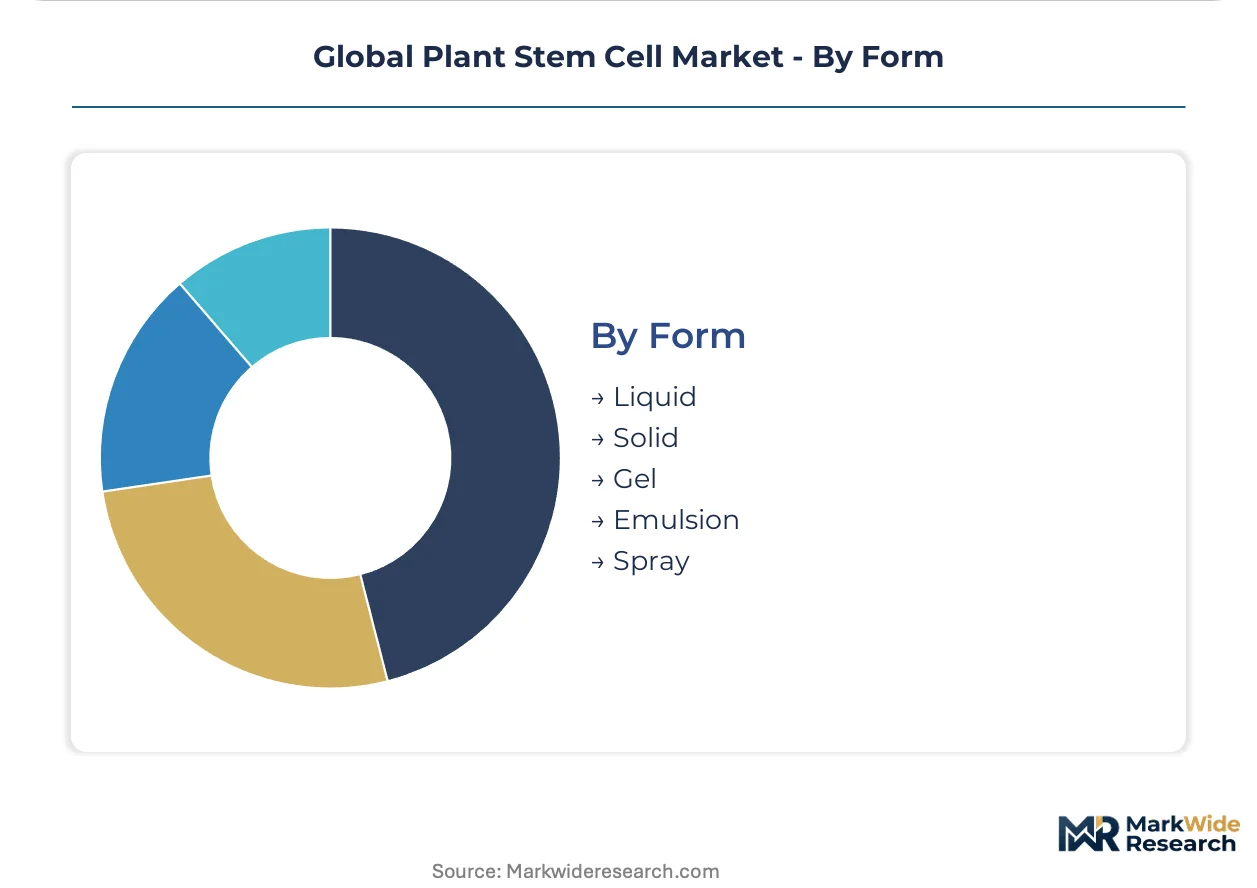
Form:
Manufacturing capital intensity varies sharply across physical states, with liquid suspension cultures demanding stainless-steel or single-use bioreactor infrastructure while solid formats enable simpler downstream processing.
- Liquid:Aqueous suspensions of meristematic cells or lysates for immediate formulation integration. Single-use bioreactor systems miniaturize capital requirements for mid-scale manufacturers in Germany and Japan.
- Gel:Viscous preparations enabling sustained-release delivery for topical applications.
- Emulsion:Oil-in-water or water-in-oil systems for enhanced dermal penetration.
- Solid:Lyophilized or spray-dried formats reducing cold-chain logistics burdens.
- Spray:Aerosolized delivery for scalp and facial mist applications.
Liquid formats dominate commercial bioreactor throughput; gels are gaining share fastest through medical aesthetics channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: East Asian markets favor ingestible formats under clarified cosmetic-ingredient frameworks, while European procurement concentrates on pre-registered topical extracts under REACH pressure, and North American demand splits between clinician-mediated dermatological channels and direct-to-consumer beauty platforms.
South Korea
Seoul-based beauty conglomerates drive procurement of plant-derived actives for anti-aging serums and capsules. MFDS cosmetic ingredient frameworks provide regulatory clarity that accelerates domestic sourcing decisions. The Seoul Capital Area anchors formulation R&D clusters where suppliers compete on batch-to-batch phytochemical consistency documentation.
Switzerland
Swiss medical aesthetics practices command premium pricing for clinical-grade skin repair preparations. Swissmedic pharmaceutical-grade standards constrain supplier qualification to GMP-certified bioreactor operations. The Lake Geneva corridor concentrates backward-integrated producers controlling rare apple varietal sourcing for standardized extract production.
Germany
German contract manufacturers adopt single-use bioreactor systems to serve mid-scale cosmetic formulators without stainless-steel infrastructure investments. ECHA REACH registration deadlines tighten substantiation requirements for novel botanical actives. The Rhine-Main and Bavarian regions host pre-registered suppliers locking in multi-year supply contracts with European formulators.
United States
FDA cosmetic ingredient guidance shapes procurement criteria for topical and ingestible formats alike. Direct-to-consumer channel expansion collapses traditional distributor markups, concentrating volume with suppliers capable of regulatory compliance documentation. California and New York Metro clusters drive demand for clinician-mediated dermatological applications and mass-market beauty-from-within capsules.
India
FSSAI regulatory harmonization with global standards creates entry pathways for standardized plant stem cell capsules targeting domestic ingestible beauty demand. Maharashtra and Karnataka host emerging nutraceutical formulation clusters. Domestic procurement concentrates on compliant raw materials for beauty-from-within positioning in urban consumer segments.
Global Plant Stem Cell Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding supply contracts through captive sourcing and GMP-certified bioreactor capacity while specialists compete on suspension-culture protocol differentiation. The structure tilts toward consolidation around validated suppliers as REACH dossier complexity and NMPA botanical-safety rules elevate barriers. Three archetypes dominate: backward-integrated producers controlling rare cultivar supply, technology licensors of proprietary culture protocols, and vertically integrated beauty brands with direct-to-consumer channel control. Competitive moves center on multi-year supply contract lock-ins with pre-registered status and bioreactor-digital twin convergence for process optimization.
Within the technology-licensor tier, PhytoCellTec represents proprietary suspension culture protocol providers securing European formulator contracts. Mibelle Biochemistry anchors the backward-integrated archetype through upstream control over rare Swiss apple varietal sourcing. Oriflame Holding exemplifies channel-integrated positioning across emerging beauty markets. These three occupy distinct competitive vectors—protocol licensing, captive supply, and distribution control—rather than competing head-to-head on identical capabilities.
| Leading Market Players |
|---|
| Phyto Science |
| MyChelleDermaceuticals |
| Natura Therapeutics |
| PhytoCellTec |
| Renature Skin Care |
| Aidan Products |
| Oriflame Holding |
| Provital |
| Mibelle Biochemistry |
| Others |
Supply & Pricing Matrix
Bioreactor capacity utilization at commercial scale anchors price floors across the plant stem cell supply base, with GMP-certified facilities in Switzerland and Germany commanding premium positioning while smaller single-use operations in Japan compete on batch flexibility. REACH dossier investments and NMPA botanical-safety compliance costs concentrate procurement power among pre-registered suppliers, compressing margins for unvalidated entrants attempting spot-market participation.
Pricing Analysis
Long-term offtake contracts dominate procurement between European formulators and GMP-certified bioreactor operators, locking in multi-year supply agreements that freeze out spot-market competitors lacking grandfathered REACH status. Price differentiation hinges on EMA certification tier and captive rare cultivar sourcing, with Swiss apple varietal controllers capturing premium positioning. Cost compression in standard-grade extracts intensifies as South Korean beauty conglomerates consolidate procurement under clarified MFDS frameworks. Research-grade facilities exhibit highest price sensitivity; clinician-mediated dermatological channels show lowest sensitivity due to reimbursement pass-through structures.
Supply Chain Analysis
Inventory lead times stretch 18-24 months for novel botanical actives awaiting ECHA evaluation protocols, forcing European formulators into advance procurement commitments. Supply concentrates in Switzerland, Germany, and South Korea, with rare apple varietal sourcing anchored in Swiss orchard networks and suspension culture capacity clustering around Lake Geneva and Seoul Capital Area biotech corridors. Raw material dependencies center on meristematic tissue stocks, specialized culture media formulations, and lyophilization equipment. Single-source vulnerability runs through captive rare cultivar controllers. Distribution runs through direct-to-consumer channel expansion by vertically integrated beauty brands, collapsing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant stem cell commercialization sits at an inflection where bioreactor-digital twin convergence is compressing process optimization cycles, while regulatory divergence between REACH, NMPA, and FDA frameworks is fragmenting viable go-to-market pathways.
For Market Incumbents: Compound GMP-certified capacity advantages through multi-year supply contract lock-ins with European and East Asian formulators facing REACH and NMPA deadline pressure. Deepen backward integration into rare cultivar sourcing to defend against Swiss apple varietal bottlenecks. Prioritize bioreactor-digital twin deployment to reduce culture failure rates and accelerate batch-to-batch consistency documentation for anti-aging serum contracts. For New Entrants and Emerging Players: MFDS fast-track certification for cosmetic ingredient frameworks offers the most penetrable entry pathway, enabling supply relationships with Seoul-based beauty conglomerates seeking compliant raw material pipelines. Target India's FSSAI-harmonized nutraceutical capsule segment where ingestible beauty demand outpaces domestic GMP-certified supply. Pursue contract manufacturing positioning using single-use bioreactor systems to serve mid-scale formulators without stainless-steel infrastructure investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated producers with captive rare cultivar supply and pre-registered REACH dossier status, as regulatory barriers compound scale advantages. Five-to-ten year viability concentrates on facilities with demonstrated batch-to-batch phytochemical consistency and clinician-mediated distribution channel access. Monitor EMA pharmaceutical-grade certification timelines as the critical inflection signal separating therapeutic-grade entrants from cosmetic-limited competitors.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Investment | EMA and Swissmedic standards unlock therapeutic-grade pricing power in dermatological channels. |
| Rare Cultivar Backward Integration | Captive Swiss apple varietal sourcing secures supply continuity for standardized extract production. |
| Bioreactor-Digital Twin Convergence | Real-time metabolite monitoring reduces culture failure rates and accelerates MFDS compliance documentation. |
| Direct-to-Consumer Channel Expansion | Oriflame-style vertical integration captures margin in Brazil, Saudi Arabia, and Southeast Asian beauty markets. |
| Multi-Year Supply Contract Lock-In | Pre-registered REACH status freezes out competitors from European formulator procurement decisions. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocess engineers, regulatory affairs directors at cosmetic formulators, GMP facility managers, and dermatology clinic procurement leads; and secondary validation through ECHA REACH registration databases, MFDS cosmetic ingredient filings, FSSAI nutraceutical approvals, and SEC disclosures from listed beauty conglomerates. Bottom-up triangulation across bioreactor capacity installations and top-down reconciliation against finished-product formulation demand anchored volume estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product format (extract, serum, capsule, powder), application channel (anti-aging topical, nutraceutical ingestible, skin repair clinical), end-user certification tier (GMP pharmaceutical, cosmetic-grade, research-grade), and geographic regulatory cluster (REACH Europe, MFDS Korea, FSSAI India, FDA United States). CAGRs derived from bioreactor capacity expansion pipelines, regulatory approval velocity, and clinician-mediated channel penetration curves. Industry-specific inputs incorporated suspension culture protocol transfer success rates and rare cultivar yield variability.
Underlying assumptions cover sustained MFDS regulatory clarity, REACH dossier grandfathering continuity, and FSSAI harmonization progress, with deviation risk concentrated in EMA pharmaceutical-grade barrier tightening and phytochemist labor scarcity constraining scale-up velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Structural Biology and Molecular Modeling Techniques Market
Biomedical Technology
Cell Separation Market
Biomedical Technology
Global Organoids Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Immunoprecipitation Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Ubiquitin Proteasome Market
Biomedical Technology
Antibody Isotyping Kit Market
Biomedical Technology
Ocular Drug Delivery Technology Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Custom Nucleic Acid Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Needle Based Biopsy Guns Market