
 Macrophage Marker Market | 2026-2036
Macrophage Marker Market Size, Share, and Industry Trends Forecast 2026-2036
Macrophage Marker Market Insights
PhD-level immunologist talent is rotating toward computational biology and single-cell analytics, tightening the specialist labor pool available for classical macrophage phenotyping workflows. Thermo Fisher Scientific leverages its channel breadth to sustain reagent availability across fragmented academic buyers. Bio-Rad Laboratories anchors its position through vertical integration into flow cytometry instrumentation and consumables. Abcam plc differentiates via recombinant antibody validation standards that address reproducibility concerns in life science research.
Macrophage markers comprise antibodies, proteins, assay kits, and reagents engineered to detect surface and intracellular antigens such as CD68, CD163, CD206, and iNOS, enabling phenotypic classification of M1/M2 polarization states in tissue and fluid samples. These tools serve primary industrial purposes in immunology research, cancer diagnostics, and inflammation studies where precise myeloid cell identification determines therapeutic strategy. Antibodies dominate current revenue owing to entrenched protocol familiarity in Western blotting and immunohistochemistry workflows, while assay kits represent the fastest-expanding category as pharmaceutical companies outsource macrophage functional assays to contract research organizations. Flow cytometry technology leads instrument-linked reagent consumption, though ELISA retains substantial share in inflammation studies requiring quantitative cytokine correlation.
FDA oversight of in vitro diagnostics and the EU IVDR framework are elevating analytical validation burdens for antibody manufacturers seeking clinical diagnostic positioning, while ISO 13485 certification has become a baseline market access requirement across OECD jurisdictions. The National Institutes of Health data sharing mandates and EMA qualification opinions on novel biomarkers are redirecting R&D investment toward multiplexed marker panels with regulatory-acceptable performance characteristics. Stakeholders must monitor evolving companion diagnostic partnerships between antibody suppliers and oncology drug developers, as these alliances increasingly determine which marker formats achieve preferred vendor status in clinical trial protocols.
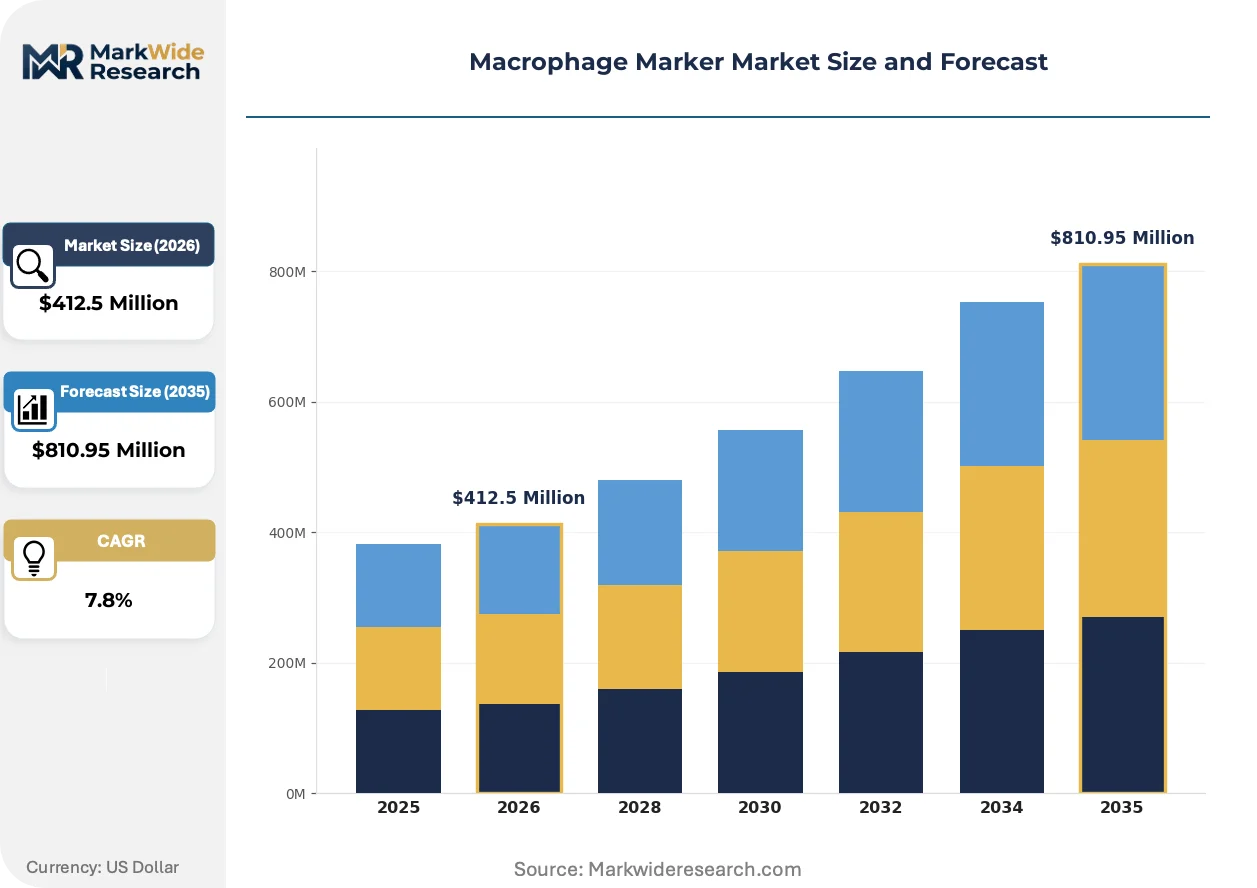
Market Dynamics
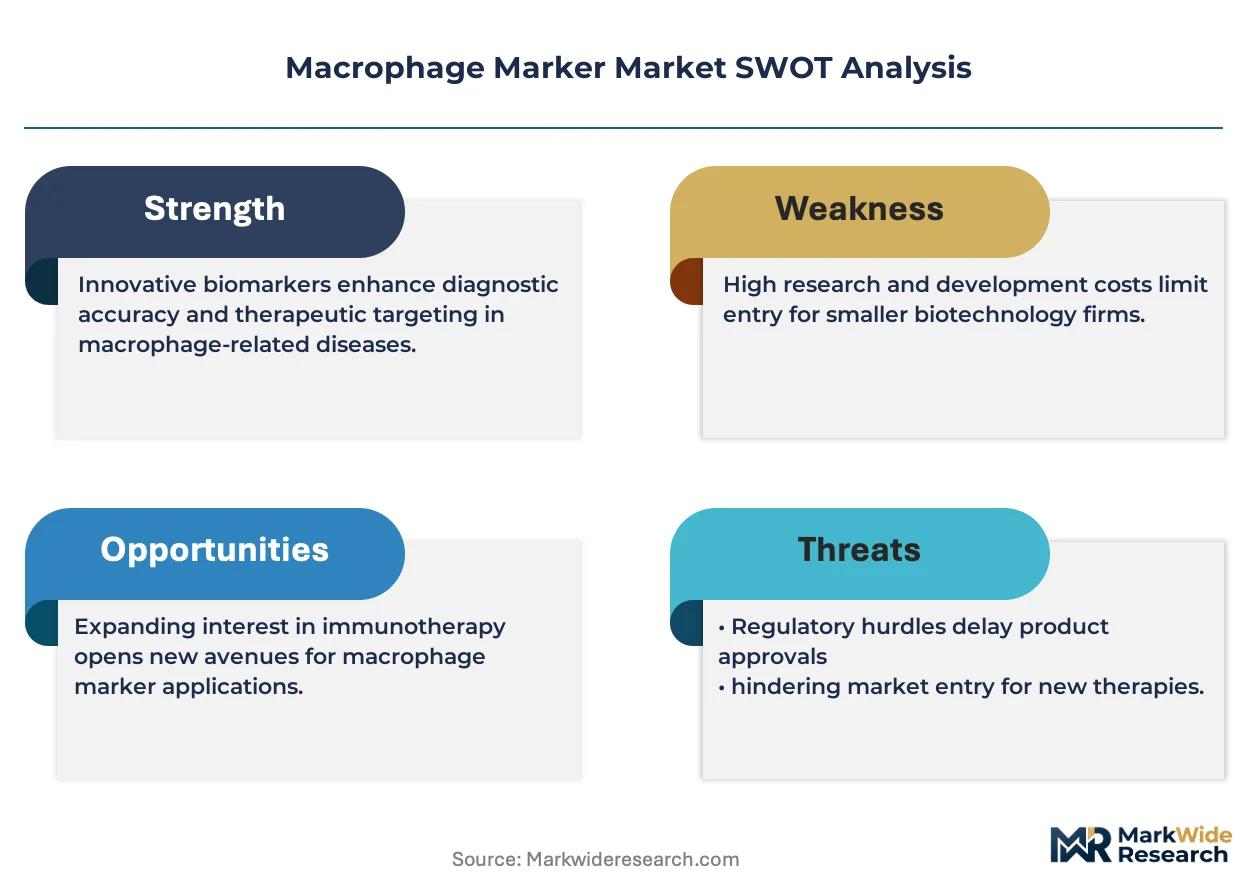
The macrophage marker market is experiencing a fundamental reconfiguration as the EU IVDR transition forces antibody suppliers to rebuild validation dossiers from the ground up, compressing margins for legacy catalog products while creating tiered competitive access based on certification readiness.
Growth Catalysts
- Companion diagnostic partnerships:Oncology drug developers now mandate validated macrophage marker panels in Phase II protocols, pulling high-affinity recombinant antibodies into clinical trial supply chains ahead of regulatory approval.
- NIH data sharing mandates:The National Institutes of Health requires open-access antibody validation data, accelerating demand for recombinant standards with batch-traceable performance characteristics in US academic consortia.
- Single-cell spatial transcriptomics:Multiplexed protein detection workflows in Boston and San Diego biotech clusters are consuming specialized CD68/CD163 antibody cocktails at volumes that justify dedicated manufacturing lines.
Market Restraints
- EU IVDR analytical validation burden:The In Vitro Diagnostic Regulation requires extended clinical evidence packages for CD marker antibodies, extending time-to-market by 18-24 months for European diagnostic positioning.
- Hybridoma cell line instability:Classical monoclonal antibody production suffers from genetic drift in murine hybridomas, forcing costly lot-to-lot revalidation that erodes gross margins on catalog products.
- Recombinant protein expression cost volatility:Chinese hamster ovary cell culture media and transfection reagent prices fluctuate with biopharma capacity utilization, squeezing input costs for premium antibody manufacturers.
Strategic Opportunities
- India CDSCO diagnostic pathway:The Central Drugs Standard Control Organization's streamlined IVD registration for research-use-only markers offers first-mover positioning in underpenetrated immuno-oncology research institutes in Bangalore and Hyderabad.
- ISO 13485-certified contract manufacturing:Third-party GMP antibody production in South Korea and Singapore enables mid-tier suppliers to access clinical diagnostic channels without captive manufacturing infrastructure.
- Machine learning-guided epitope mapping:Computational prediction of CD206 and iNOS binding sites is converging with automated phage display screening, collapsing antibody development timelines from months to weeks.
Industry Challenges
- PhD-level immunologist scarcity:Classical macrophage phenotyping expertise is migrating toward computational biology and bioinformatics, leaving contract research organizations competing for scarce FACS specialists.
- Legacy Western blot protocol entrenchment:Decades of published research using polyclonal CD68 antibodies creates switching friction toward recombinant alternatives, requiring extensive cross-validation studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macrophage Marker Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Proteins, Assay Kits, Reagents Application: Immunology Research, Cancer Diagnostics, Inflammation Studies, Cellular Biology End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Hospitals Technology: Flow Cytometry, ELISA, Western Blotting, PCR |
| Companies Covered | Thermo Fisher Scientific, Inc., Abcam plc, Bio-Rad Laboratories, Inc., BD Biosciences, Cell Signaling Technology, Inc., BioLegend, Inc., Merck KGaA, Miltenyi Biotec GmbH, Agilent Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macrophage Marker Market Trends and Innovations
Antibody validation standards, regulatory data requirements, and procurement centralization are converging to reshape competitive positioning across the macrophage marker supply base. These forces favor suppliers with captive manufacturing and documented regulatory trajectories.
Recombinant rabbit monoclonal antibodies are fragmenting the traditional hybridoma-dominated market for CD68 and CD163 detection. Pharmaceutical quality control laboratories in Germany and Switzerland are adopting these reagents at accelerated pace to satisfy EMA qualification opinion requirements for biomarker consistency. The technology is fragmenting incumbent catalog portfolios by enabling lot-to-lot reproducibility guarantees that polyclonal alternatives cannot match.
REACH chemical substance registration is extending to antibody conjugation chemistries and fluorescent dyes used in flow cytometry panels. European manufacturers must now document full toxicological profiles for Alexa Fluor and PE-Cy7 derivatives, raising formulation costs and compressing available dye portfolios. Diagnostic assay kit suppliers are responding by consolidating around pre-registered dye combinations with established safety dossiers.
Consortium-based bulk purchasing is restructuring reagent acquisition patterns among NIH-funded immunology networks. Principal investigators in Boston, San Diego, and Research Triangle Park now pool antibody procurement through centralized core facilities, displacing individual laboratory catalog orders. This concentration is most visible in high-volume M1/M2 polarization studies where standardized panel pricing outweighs brand loyalty.
Macrophage Marker Market Segmentation
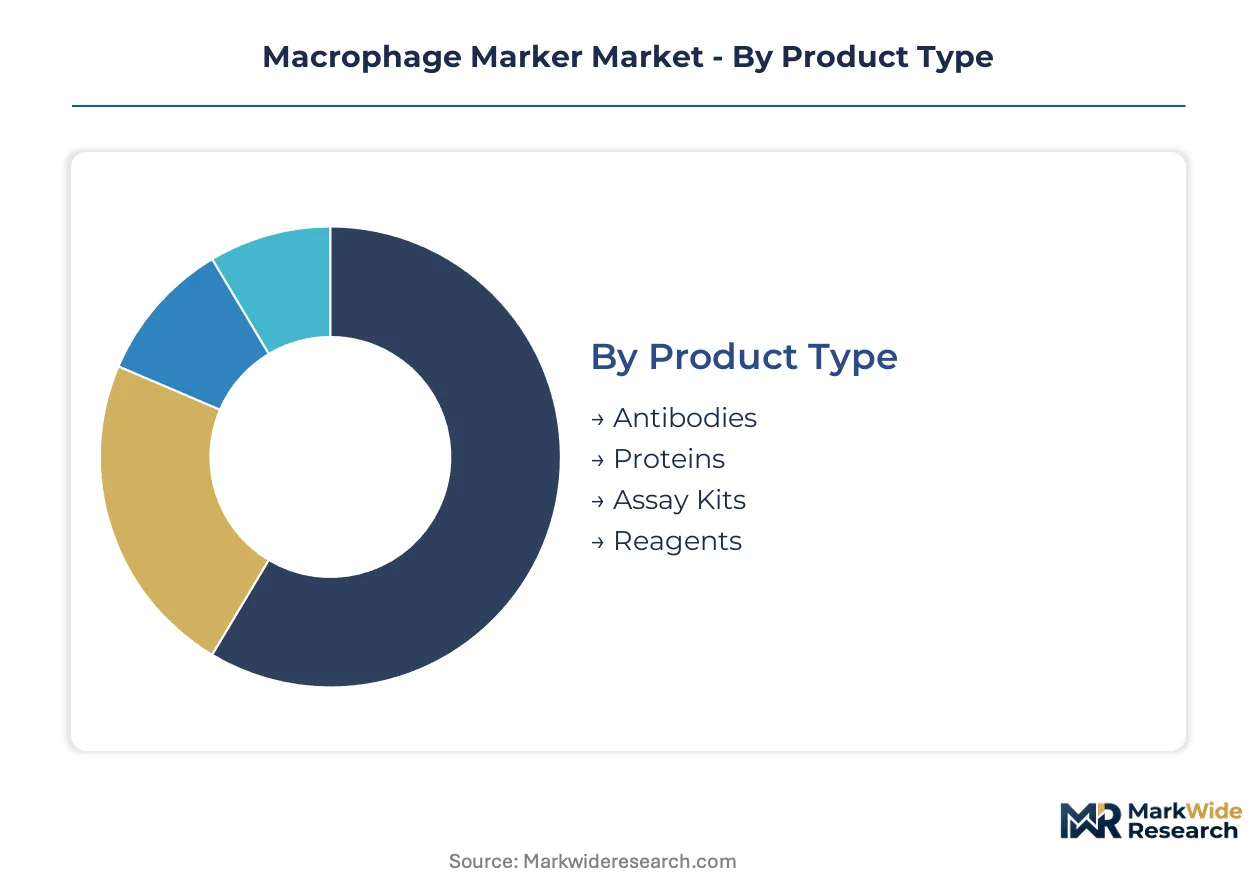
Macrophage marker procurement patterns diverge sharply across research settings, with academic consortia favoring modular antibody formats while pharmaceutical sponsors demand validated assay panels for regulatory submissions. Segmentation reveals how technology-platform choices and end-user workflows reshape supplier priorities.
Product Type:
Antibodies dominate domestic consumption in US and European academic clusters, while assay kits and reagents flow disproportionately toward export-oriented contract manufacturing hubs in Asia-Pacific.
- Antibodies:Recombinant rabbit monoclonals and classical hybridoma-derived formats detect surface antigens including CD68, CD163, and CD206. NIH-funded consortia in Boston and San Diego now mandate batch-traceable validation data, compressing demand toward recombinant alternatives with documented lot-to-lot consistency.
- Assay Kits:Pre-configured panels for M1/M2 polarization quantification integrate antibodies, detection reagents, and standardized protocols. Pharmaceutical companies outsource functional macrophage assays to CROs, driving kit volumes that justify dedicated manufacturing lines with ISO 13485 certification.
- Proteins:Recombinant cytokines and growth factors for macrophage differentiation protocols.
- Reagents:Buffers, fixation solutions, and permeabilization agents supporting downstream detection workflows.
Antibodies hold the largest share; momentum sits with assay kits.
Application:
Cost tier stratification separates premium-positioned cancer diagnostic applications from standard-grade inflammation studies and economy-tier academic research tools.
- Cancer Diagnostics:Companion diagnostic development requires GMP-grade antibody panels with EMA qualification opinion alignment and FDA 510(k) pathway documentation. Oncology drug developers in Germany and Switzerland now specify CD163/CD206 multiplex panels in Phase II protocols, pulling high-affinity reagents into clinical trial supply chains ahead of regulatory approval.
- Immunology Research:Fundamental myeloid cell biology studies employ catalog antibodies for tissue imaging and flow cytometry phenotyping. Academic core facilities consolidate procurement across principal investigator networks, displacing individual laboratory orders with standardized panel pricing.
- Inflammation Studies:Cytokine correlation workflows favor ELISA-based quantitative formats.
- Cellular Biology:General cell culture and differentiation protocols using macrophage lineage markers.
Cancer diagnostics commands premium pricing; immunology research delivers volume scale.
End User:
Customer type determines validation burden and procurement centralization, with pharmaceutical sponsors imposing stringent analytical requirements that academic buyers rarely match.
- Pharmaceutical Companies:Internal R&D and quality control laboratories specify recombinant antibodies with documented epitope mapping and stability data. FDA's evolving companion diagnostic guidance forces early partnership between antibody suppliers and oncology drug developers, locking preferred vendor status through clinical trial protocol design.
- Academic Institutions:Individual laboratories and centralized core facilities purchase catalog antibodies for Western blotting and immunohistochemistry. NIH data sharing mandates accelerate demand for open-access validation datasets, favoring suppliers with published performance characteristics.
- Contract Research Organizations:Externalized functional assay execution for pharmaceutical sponsors.
- Hospitals:Clinical pathology laboratories with diagnostic service mandates.
Pharmaceutical companies anchor revenue concentration; academic institutions expand most quickly through consortium purchasing.
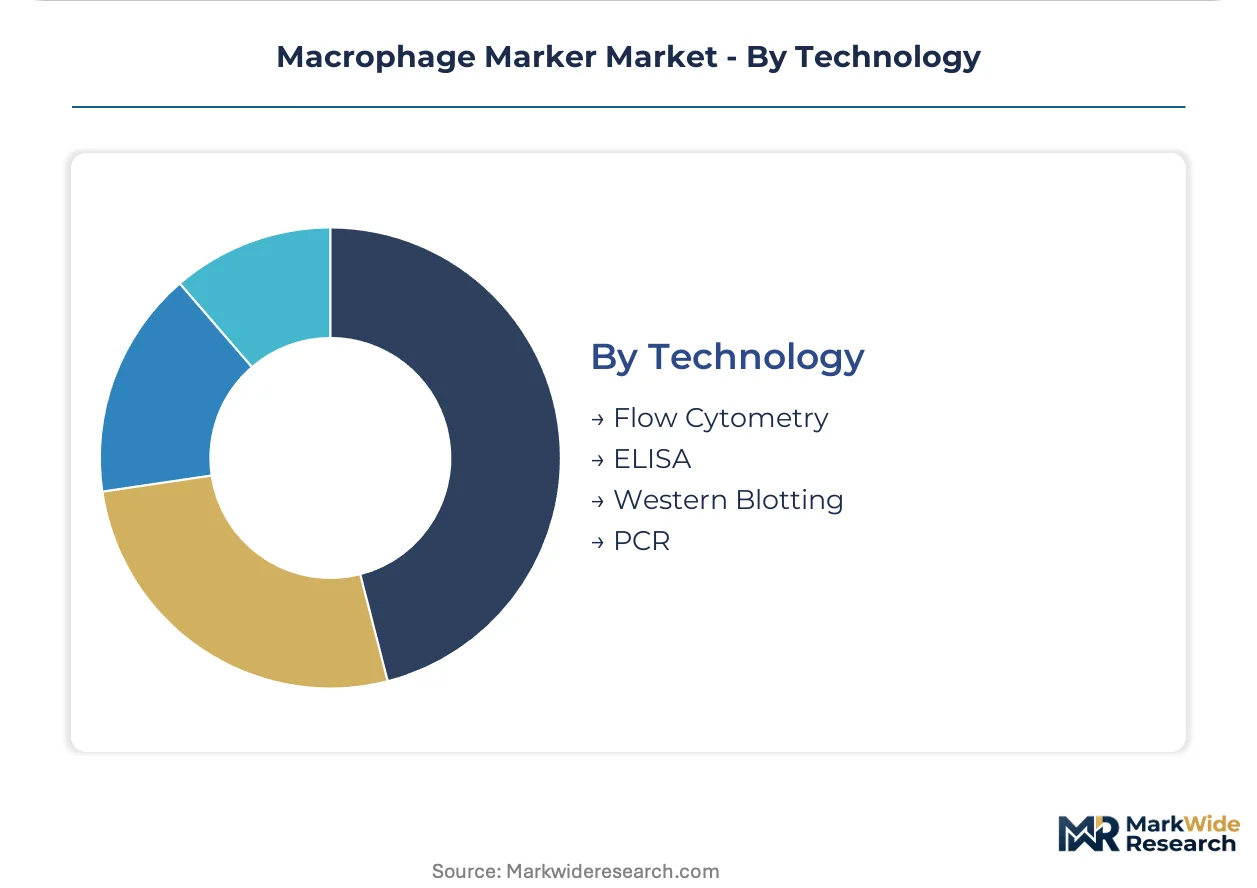
Technology:
Platform maturity stratifies the installed base, with established flow cytometry and ELISA systems facing displacement pressure from emerging spatial transcriptomics workflows.
- Flow Cytometry:Multi-parameter cell sorting and analysis consumes specialized fluorophore-conjugated antibody cocktails. Bio-Rad Laboratories and Thermo Fisher Scientific anchor instrument-linked reagent consumption through captive hardware placements in Boston and San Diego biotech clusters.
- ELISA:Quantitative cytokine detection and soluble marker measurement retains substantial share in inflammation studies requiring numerical correlation with clinical endpoints. REACH chemical registration extends to antibody conjugation chemistries, raising formulation costs for European manufacturers.
- Western Blotting:Legacy protein detection with polyclonal antibody entrenchment.
- PCR:Gene expression profiling of macrophage polarization states.
Flow cytometry leads instrument-linked consumption; ELISA maintains defensive positioning in quantitative applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates demand around flow cytometry-based phenotyping workflows, while Germany and Switzerland prioritize GMP-grade antibody validation for companion diagnostic development. Japan and China diverge toward spatial transcriptomics instrumentation and cost-efficient reagent manufacturing respectively.
United States
NIH-funded immunology consortia in Boston and San Diego drive specialized CD68/CD163 antibody cocktail consumption at volumes justifying dedicated manufacturing lines. FDA companion diagnostic guidance forces early partnership between antibody suppliers and oncology drug developers. The Research Triangle Park anchors CRO outsourcing of macrophage functional assays.
Germany
EMA qualification opinion requirements pull high-affinity recombinant antibodies into clinical trial supply chains ahead of regulatory approval. REACH chemical substance registration extends to antibody conjugation chemistries, raising formulation costs for fluorescent dye portfolios. Pharmaceutical quality control laboratories in Frankfurt and Munich adopt recombinant rabbit monoclonals at accelerated pace.
Switzerland
Swissmedic oversight of in vitro diagnostics elevates analytical validation burdens for antibody manufacturers seeking clinical diagnostic positioning. Roche and Novartis oncology pipelines mandate validated macrophage marker panels in Phase II protocols. The Basel biotech cluster concentrates demand for multiplexed CD163/CD206 detection systems.
Japan
PMDA biomarker qualification opinions redirect R&D investment toward multiplexed marker panels with regulatory-acceptable performance characteristics. METI funding for single-cell spatial transcriptomics accelerates specialized antibody consumption in Tokyo and Osaka research institutes. Domestic pharmaceutical sponsors impose stringent epitope mapping documentation requirements.
China
NMPA streamlined registration pathways for research-use-only markers enable first-mover positioning in underpenetrated immuno-oncology research institutes. Shanghai and Beijing biotech clusters expand procurement of flow cytometry-based detection systems. Cost-efficient CHO cell culture capacity supports recombinant antibody manufacturing for export markets.
Macrophage Marker Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive manufacturing and instrument-linked reagent consumption determining competitive access. Thermo Fisher Scientific and Bio-Rad Laboratories anchor the upper tier through hardware placements and consumable bundling. Mid-tier specialists differentiate via recombinant antibody validation standards and ISO 13485-certified contract manufacturing. Strategic moves concentrate on M&A for technology licensing and capacity expansion in South Korean and Singaporean GMP facilities.
Among US-based diversified life science conglomerates, Thermo Fisher Scientific Inc. exemplifies channel breadth strategies that sustain reagent availability across fragmented academic buyers. Bio-Rad Laboratories Inc. occupies a position anchored through backward integration into flow cytometry instrumentation and consumables. Abcam plc represents the recombinant validation archetype, addressing reproducibility concerns that erode demand for classical hybridoma-derived formats. These three anchors illustrate how certification readiness and documented regulatory trajectories now determine preferred vendor status in clinical trial protocols.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Abcam plc |
| Bio-Rad Laboratories, Inc. |
| BD Biosciences |
| Cell Signaling Technology, Inc. |
| BioLegend, Inc. |
| Merck KGaA |
| Miltenyi Biotec GmbH |
| Agilent Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between recombinant antibody manufacturers and NIH-funded academic consortia lock in both supply access and price visibility across multi-year procurement cycles. These contracts insulate high-volume buyers in Boston and San Diego from CHO cell culture media cost volatility while compressing spot-market opportunities for mid-tier suppliers.
Pricing Analysis
Project-based pricing for GMP-grade antibody panels dominates pharmaceutical sponsor relationships, with ISO 13485 certification tier and documented epitope mapping data serving as the primary price differentiation drivers. Cost compression in standard-grade catalog antibodies is intensifying because REACH-registered fluorescent dye portfolios constrain formulation flexibility. Academic core facilities demonstrate highest price sensitivity due to consolidated consortium purchasing, while companion diagnostic developers show lowest sensitivity given regulatory lock-in requirements.
Supply Chain Analysis
Strategic stockpiling of CHO cell culture media and transfection reagents distinguishes large-scale recombinant antibody producers from just-in-time competitors facing input cost volatility. Manufacturing concentration rests on the United States, Germany, and China, with Chinese hamster ovary cell lines, Alexa Fluor conjugation chemistries, and PE-Cy7 derivatives anchoring raw material dependencies. Single-source vulnerability in hybridoma cell line repositories poses structural risk. Distribution runs through instrument-linked consumable bundling by flow cytometry hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The macrophage marker market exhibits defensive moat characteristics rooted in regulatory entrenchment, where EMA qualification opinions and FDA companion diagnostic guidance create multi-year certification barriers that protect validated supplier relationships.
For Market Incumbents: Shield market position by accelerating ISO 13485-certified capacity expansion in South Korea and Singapore to preempt mid-tier competitors from accessing clinical diagnostic channels. Deepen backward integration into recombinant rabbit monoclonal production to offset hybridoma cell line instability threatening legacy catalog margins. For New Entrants and Emerging Players: Computational antibody design services represent an under-served layer where incumbents lack dedicated offerings, enabling entry through machine learning-guided epitope mapping subscriptions. Target India's CDSCO streamlined IVD registration pathway for research-use-only markers, leveraging Bangalore and Hyderabad immuno-oncology institutes as beachhead accounts with open-source validation data go-to-market positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among recombinant antibody suppliers with documented regulatory trajectories and captive manufacturing infrastructure. Over the projection horizon, vertically integrated specialists with EMA qualification opinion alignment present optimal acquisition profiles. Watch for FDA companion diagnostic partnership announcements as inflection indicators determining preferred vendor status in Phase II oncology protocols.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Unlocks clinical diagnostic channel access under EU IVDR and FDA oversight frameworks. |
| Recombinant Antibody Platform Migration | Addresses lot-to-lot reproducibility requirements from EMA qualification opinions. |
| Machine Learning-Guided Epitope Mapping | Collapses CD206 and iNOS antibody development timelines through computational prediction. |
| Consortium-Based Bulk Purchasing Contracts | Captures NIH-funded academic network volume through centralized core facility procurement. |
| Companion Diagnostic Partnership Formation | Locks preferred vendor status in oncology drug developer Phase II protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA qualification opinions, ClinicalTrials.gov macrophage marker protocol specifications, and NIH grant award databases. Primary interviews engaged immunology research directors at Boston and San Diego academic consortia, regulatory affairs leads at antibody suppliers, pharmaceutical quality control laboratory managers, and contract research organization procurement officers. Bottom-up reagent consumption modeling triangulates against top-down market sizing from instrument placement data and antibody catalog shipment patterns.
Segmentation dimensions modeled span product type, application, end user, and technology platform across the projection horizon. CAGRs derive from regression analysis of historical procurement volumes against NIH funding trajectories and pharmaceutical R&D outsourcing indices. Forecast inputs incorporate EU IVDR implementation timelines, companion diagnostic partnership announcement frequencies, and spatial transcriptomics instrumentation adoption curves in Tokyo and Osaka research institutes.
Underlying assumptions cover sustained NIH data sharing mandate enforcement and REACH chemical registration stability for antibody conjugation chemistries, with deviation risk concentrated in FDA companion diagnostic guidance revisions and hybridoma cell line supply disruptions. Revision becomes warranted when EU IVDR analytical validation burden timelines extend beyond current regulatory capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
America Cell Counting Market
Biomedical Technology
Automated Cell Biology Systems Market
Biomedical Technology
Drug Discovery Enzymes Market
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
Cell Analysis Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Global Biomarker Technologies Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
PD L1 Biomarker Testing Market
Biomedical Technology
Cosmid DNA Isolation Market
Biomedical Technology
Global Neuroscience Antibodies and Assays Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Cell Dissociation Market
Biomedical Technology
High-End Cellomics Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Strand Displacement Amplification (SDA) Market