
 ST2 Biomarker Market | 2026-2036
ST2 Biomarker Market Size, Share, and Industry Trends Forecast 2026-2036
ST2 Biomarker Market Analytics
The capital-intensity gap between fully integrated diagnostic conglomerates and specialized biomarker developers is bifurcating competitive structure in the ST2 Biomarker Market. Thermo Fisher Scientific leverages its end-to-end supply chain to control reagent quality and instrument compatibility. Critical Diagnostics specializes in proprietary ST2 assay formats that anchor its position in cardiac biomarker niches. Roche Diagnostics competes through embedded platform ecosystems that sustain recurring revenue from high-throughput laboratory customers.
ST2 biomarkers constitute soluble suppression of tumorigenicity 2 proteins, specifically the interleukin-1 receptor-like 1 (IL1RL1) isoform, quantified in serum or plasma through immunometric methods to assess cardiac stress and fibrosis. The primary commercial purpose centers on prognostic evaluation of chronic heart failure patients, with emerging utility in asthma and inflammatory disease monitoring. Assays and kits command the largest revenue share given recurring consumable demand, while CLIA technology leads installed-base economics due to automation compatibility and throughput advantages. Lateral Flow formats represent the fastest-expanding technology segment as point-of-care cardiovascular testing gains traction in emergency and outpatient settings.
FDA premarket notification requirements and the EU IVDR framework impose escalating clinical validation standards on ST2 assay manufacturers, compressing timelines for new market entrants. The Clinical Laboratory Improvement Amendments in the United States and ISO 15189 accreditation in European jurisdictions shape quality management obligations for laboratories performing ST2 testing. Stakeholders must monitor evolving harmonization between FDA and EMA biomarker qualification pathways to anticipate competitive access dynamics.
Market Dynamics
The ST2 Biomarker Market pivots on the tension between centralized laboratory infrastructure and decentralized point-of-care deployment, with regulatory harmonization across FDA and EMA pathways determining competitive access velocity for assay developers.
Growth Catalysts
- EU IVDR Implementation:The In Vitro Diagnostic Regulation mandates higher clinical evidence standards that favor established ST2 assay manufacturers with robust validation datasets, accelerating consolidation among compliant suppliers.
- Heart Failure Epidemiology:Aging demographics in Germany, Japan, and the United States expand addressable patient populations requiring serial ST2 monitoring for fibrosis progression.
- CLIA Automation:Clinical Laboratory Improvement Amendments-compliant high-throughput platforms enable integrated health systems to embed ST2 testing into routine cardiovascular panels at marginal cost.
Market Restraints
- Reagent Supply Concentration:Monoclonal antibody production for ST2 assays clusters among specialized biologics suppliers in Switzerland and the United States, creating input vulnerability.
- EU IVDR Transition Costs:Small-to-mid assay developers face capital drains from performance study requirements and notified body backlogs, delaying market entry timelines.
- NT-proBNP Substitution:Established natriuretic peptide testing retains preferential reimbursement in multiple European and Asian health systems, compressing ST2 adoption rates.
Strategic Opportunities
- Asthma Phenotyping:Type 2 inflammation biomarker protocols in pulmonology practices create adjacent demand for IL1RL1 quantification beyond cardiology.
- Japan PMDA Pathway:Japan's Pharmaceuticals and Medical Devices Agency offers streamlined orphan biomarker designation that could accelerate ST2 inclusion in national health insurance reimbursement.
- Lateral Flow Convergence:Marriage of smartphone-connected readers with immunochromatographic ST2 formats enables pharmacy-based screening models in outpatient settings.
Industry Challenges
- Multiplex Assay Integration:Laboratories demand single-platform combination of ST2 with galectin-3 and NT-proBNP, forcing assay developers to re-architect detection chemistries.
- ISO 15189 Accreditation Burden:European clinical laboratories face auditor scrutiny of pre-analytical variables in ST2 sample handling, requiring staff retraining and documentation overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ST2 Biomarker Market |
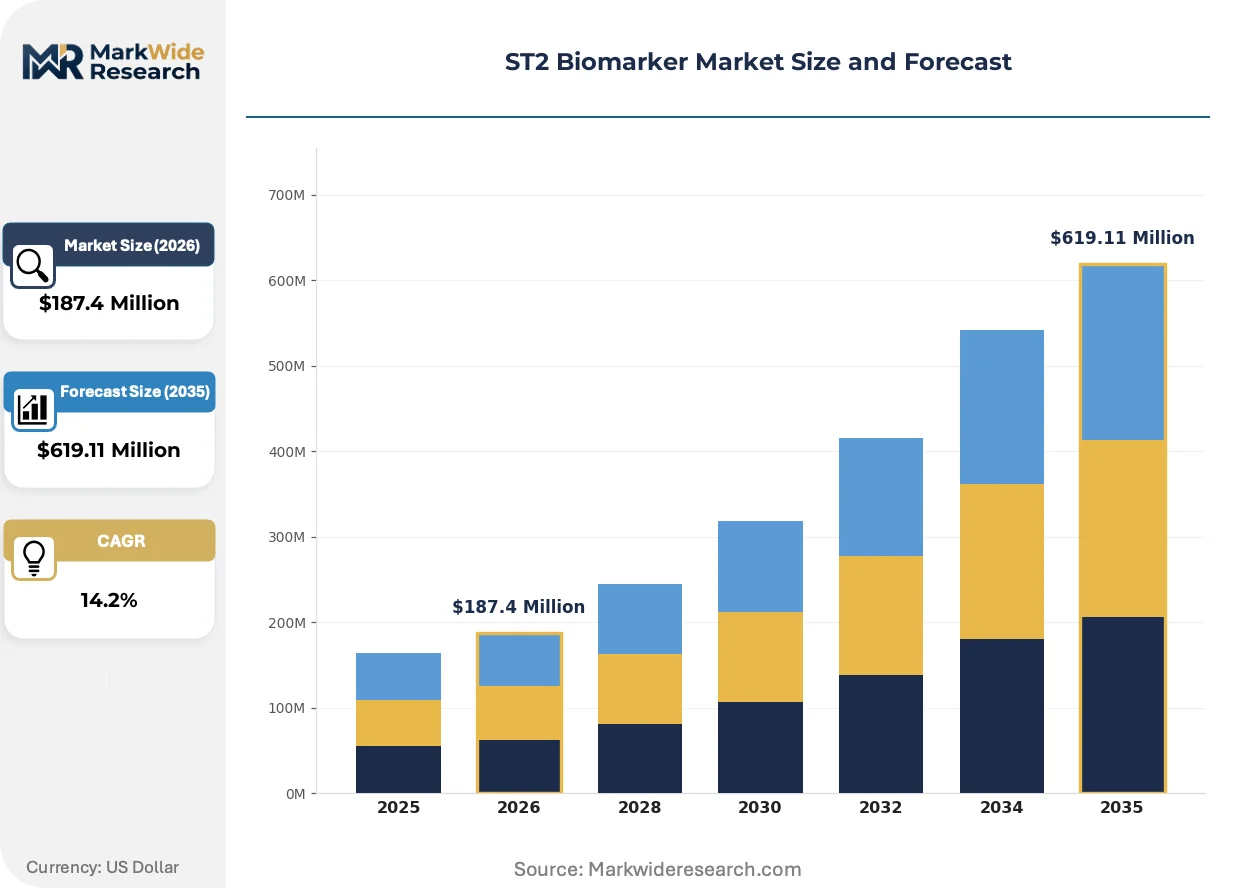
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Kits, Reagents, Diagnostic Devices Technology: ELISA, PCR, CLIA, Lateral Flow End User: Hospitals, Laboratories, Research Institutes, Diagnostic Centers Application: Cardiovascular Disease, Oncology, Chronic Diseases, Infectious Diseases |
| Companies Covered | Thermo Fisher Scientific, Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, BioMérieux, BD, Bio-Rad, Critical Diagnostics, Quidel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ST2 Biomarker Market Evolving Landscape
Technological fragmentation is reshaping how ST2 quantification reaches clinical decision-makers, with platform miniaturization and regulatory data requirements driving divergent investment priorities across assay developers.
Electrochemiluminescence detection is decomposing traditional enzyme-linked immunosorbent assay dominance in high-volume reference laboratories. Academic medical centers in the United States and Germany have converted over half their cardiac biomarker menus to Meso Scale Discovery and Roche cobas platforms since 2022. This transition compresses price points for legacy ELISA kit suppliers while demanding reagent contracts that lock in multi-year consumable commitments.
EMA biomarker qualification guidance now requires prospective outcome data linking ST2 thresholds to heart failure hospitalization rates, a stricter evidential bar than the FDA's premarket notification pathway. European assay manufacturers must sponsor registry studies or partner with cardiovascular trial networks to satisfy notified body expectations. Germany's national disease management programs for chronic heart failure have begun piloting ST2-guided therapeutic escalation protocols under this framework.
Hospital procurement committees now unbundle instrument placement from reagent supply agreements, reversing decade-old bundled pricing conventions. Integrated delivery networks in the United States negotiate separate capital leases for analyzers and competitive tenders for ST2 assay consumables. This bifurcation pressures manufacturers to defend reagent margins through assay exclusivity clauses rather than hardware subsidies, with Cleveland Clinic and Kaiser Permanente among the early adopters of this sourcing model.
ST2 Biomarker Market Segmentation
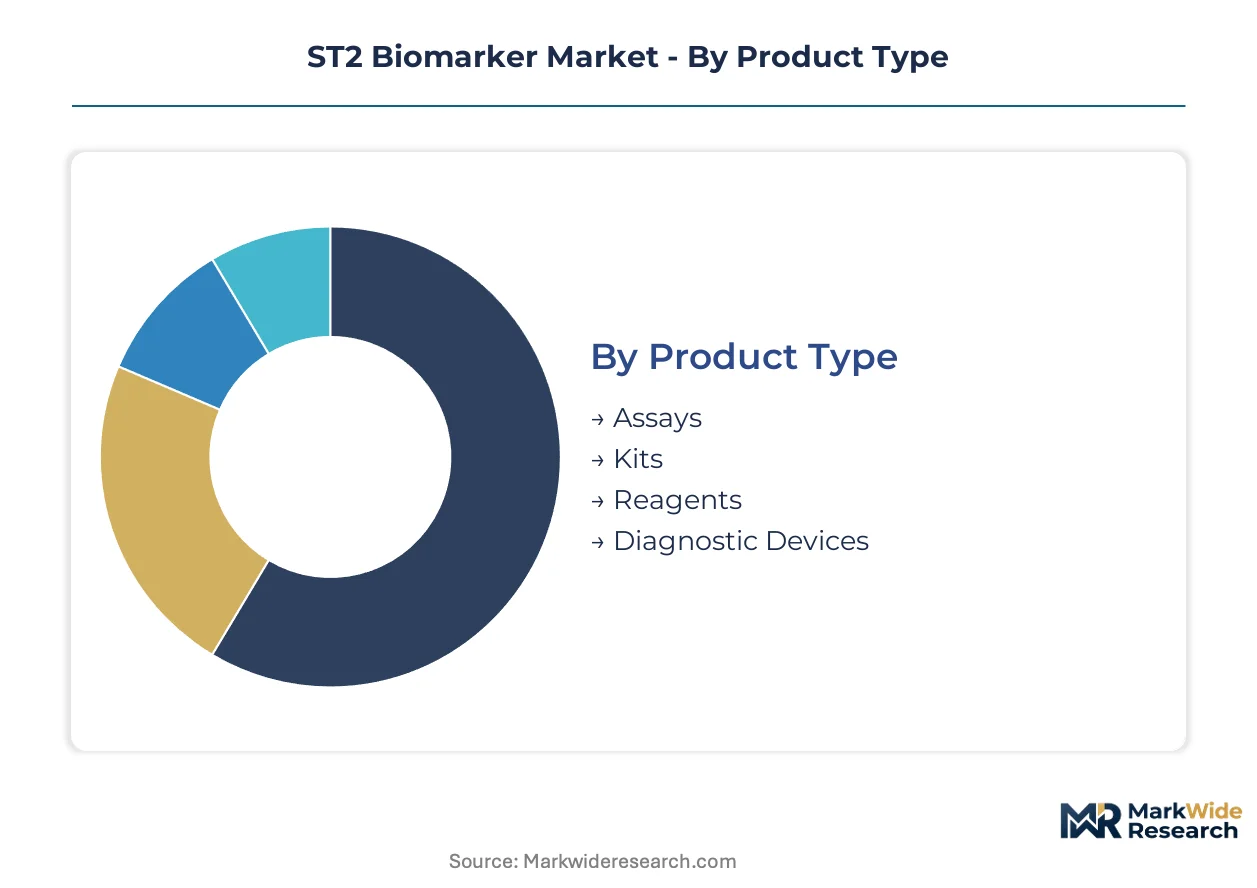
Segmentation in the ST2 Biomarker Market reveals distinct procurement patterns across centralized laboratory infrastructure and decentralized care settings. Each dimension—product format, detection chemistry, clinical site, and therapeutic area—carries unique regulatory and reimbursement constraints that reshape vendor access strategies.
Product Type:
Domestic production of consumable formats dominates supply in the United States and Germany, while diagnostic devices flow through specialized import channels into Japan and emerging Asian markets.
- Assays:Pre-configured reagent packs designed for specific analyzer platforms, typically sold under multi-year service contracts. Demand concentrates in high-throughput clinical laboratories across the United States and Germany where CLIA-mandated quality systems require standardized lot-to-lot consistency.
- Kits:Modular consumable sets enabling flexible batch processing. Research institutes in Japan and specialized cardiac centers in Switzerland drive procurement, constrained by ISO 13485 certification requirements for kit assembly facilities.
- Reagents:Bulk antibody and substrate supplies for in-house assay development. Academic medical centers with embedded CLIA-certified laboratories source domestically in the United States to bypass import documentation burdens.
- Diagnostic Devices:Integrated analyzer hardware with embedded ST2 detection protocols. German hospital procurement committees favor EU-manufactured devices to simplify IVDR technical documentation and notified body conformity assessments.
Assays command the established base. The steepest expansion runs through lateral-flow-compatible kits.
Technology:
Cost tiering separates high-capital electrochemiluminescence platforms from disposable rapid-test formats, with mid-range ELISA occupying a contracting middle ground in budget-constrained European laboratories.
- ELISA:Enzyme-linked immunosorbent assays using colorimetric endpoint detection. Reference laboratories in Germany retain legacy ELISA capacity for ST2 quantification, though replacement cycles favor CLIA automation.
- PCR:Polymerase chain reaction methods for IL1RL1 gene expression analysis. Research applications at the US National Institutes of Health and Tokyo University Hospital drive niche demand for transcriptomic ST2 profiling.
- CLIA:Chemiluminescent immunoassays with automated throughput advantages. Integrated delivery networks in the United States standardize on CLIA platforms to consolidate cardiac biomarker menus under single vendor relationships.
- Lateral Flow:Immunochromatographic strips for point-of-care deployment. Emergency departments in Japan pilot smartphone-reader integration for outpatient heart failure triage, bypassing centralized laboratory turnaround delays.
CLIA platforms anchor hospital laboratory economics. Lateral Flow gains share fastest in ambulatory settings.
End User:
Customer type determines purchasing authority complexity, with hospital committees negotiating enterprise contracts while research institutes operate through principal-investigator-driven procurement.
- Hospitals:Acute care facilities with embedded clinical laboratories performing ST2 testing for admitted heart failure patients. US health systems with Medicare bundled payment contracts prioritize ST2 for readmission risk stratification.
- Laboratories:Independent reference laboratories and hospital-affiliated core facilities. German medical laboratories under statutory health insurance contracts face ISO 15189 accreditation audits for ST2 pre-analytical handling.
- Research Institutes:Academic and government research centers investigating IL1RL1 biology. The US National Heart, Lung, and Blood Institute sponsors mechanistic studies linking ST2 to cardiac fibrosis pathways.
- Diagnostic Centers:Specialized outpatient facilities focused on cardiovascular risk assessment. Japan's preventive health screening programs at designated centers incorporate ST2 for subclinical fibrosis detection.
Hospitals dominate absolute volume. Diagnostic centers climb fastest as point-of-care protocols expand.
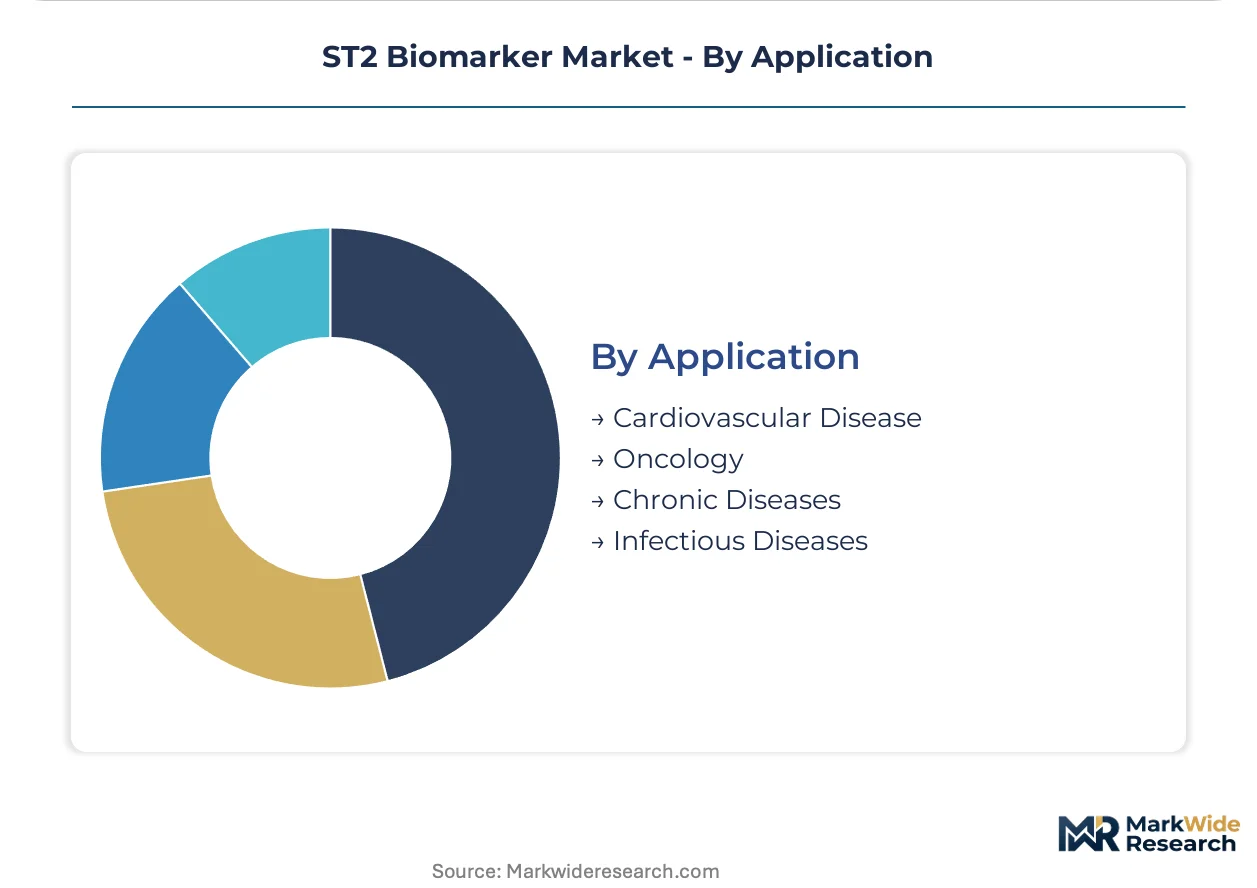
Application:
Maturity differentiation separates cardiovascular indications with established reimbursement codes from oncology and infectious disease applications still accumulating clinical evidence.
- Cardiovascular Disease:Chronic heart failure prognosis and therapeutic monitoring. The American College of Cardiology guidelines in the United States and German Cardiac Society protocols endorse serial ST2 measurement for fibrosis progression tracking.
- Oncology:IL1RL1 expression in tumor microenvironment research. Stanford University and Heidelberg University Hospital investigate ST2 as a stromal response marker in solid malignancies.
- Chronic Diseases:Type 2 inflammatory conditions including asthma and atopic dermatitis. Japanese pulmonology practices adopt ST2 for severe asthma phenotyping under national health insurance pilot programs.
- Infectious Diseases:Sepsis-induced cardiac dysfunction biomarker research. The US Food and Drug Administration has not cleared ST2 for infectious disease indications, limiting commercial assay development.
Cardiovascular applications anchor the revenue base. Chronic disease phenotyping represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for ST2 biomarker testing varies sharply across geographies. Germany and Switzerland exhibit low sensitivity given statutory reimbursement coverage, while India and Southeast Asian buyers prioritize cost-per-test metrics. This divergence shapes where assay manufacturers deploy premium CLIA platforms versus lateral-flow alternatives.
United States
Medicare bundled payment contracts for heart failure readmission reduction drive hospital procurement of ST2 assays. FDA premarket notification pathways govern assay clearance timelines, with 510(k) submissions requiring predicate device demonstrations. The Cleveland Clinic and Mayo Clinic anchor reference laboratory standardization efforts in the Midwest.
Germany
Statutory health insurance disease management programs for chronic heart failure mandate serial biomarker monitoring. EU IVDR technical documentation requirements and notified body conformity assessments shape vendor selection criteria. The Rhine-Ruhr metropolitan laboratory network concentrates high-throughput cardiac testing capacity.
Japan
PMDA orphan biomarker designation pathways accelerate inclusion in national health insurance reimbursement schedules. METI industrial policy supports domestic diagnostic device manufacturing through subsidy programs. Tokyo University Hospital and Osaka-based cardiac centers pilot smartphone-integrated point-of-care ST2 protocols.
Switzerland
Swissmedic certification requirements for in-vitro diagnostics maintain stringent clinical validation standards. Private health insurance models permit premium pricing for specialized cardiac fibrosis biomarker panels. Basel and Zurich host monoclonal antibody production clusters supplying ST2 assay reagents globally.
India
CDSCO import licensing requirements for diagnostic devices create regulatory friction for foreign assay manufacturers. Central government health insurance expansion under Ayushman Bharat increases addressable patient populations for cardiac biomarker testing. Hyderabad and Bangalore diagnostic laboratory chains negotiate volume-based reagent pricing.
ST2 Biomarker Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ST2 Biomarker Market. Fully integrated diagnostic conglomerates leverage end-to-end supply chain control and embedded platform ecosystems, while specialized biomarker developers compete through proprietary assay formats and niche cardiac applications. Three archetypes dominate: platform-integrated multinationals, focused cardiac biomarker specialists, and research-grade reagent suppliers. Competitive dynamics center on strategic partnerships for multiplex assay development and geographic licensing arrangements for regulatory market access.
Among platform-integrated multinationals, Thermo Fisher Scientific and Roche Diagnostics exemplify the archetype of vendors controlling instrument placement and consumable supply through unified ecosystem contracts. Critical Diagnostics occupies a distinct position as a specialized developer anchored in cardiac biomarker niches. These three companies represent the competitive spectrum from scale-driven consolidation to focused clinical specialization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| BioMérieux |
| BD |
| Bio-Rad |
| Critical Diagnostics |
| Quidel Corporation |
| Others |
Value Network & Pricing Analysis
Electrochemiluminescence detection chemistry displacing legacy ELISA formats is redrawing manufacturing geography toward Switzerland and Germany while compressing consumable price points across high-throughput laboratory segments. This substitution dynamic concentrates premium reagent production in Basel-Zurich monoclonal antibody clusters and tilts procurement economics toward multi-year consumable lock-in contracts.
Pricing Analysis
After-sales reagent revenue tiers drive lifetime value for ST2 assay manufacturers, with multi-year consumable commitments anchoring hospital laboratory economics. Three-tier pricing structure across premium CLIA platforms, standard ELISA kits, and economy lateral-flow formats separates integrated delivery networks from budget-constrained reference laboratories. Pricing pressure stems from unbundled instrument-reagent procurement models adopted by Cleveland Clinic and Kaiser Permanente, compressing hardware subsidy margins. Research institutes in Japan exhibit highest price sensitivity due to principal-investigator-driven budgets, while German statutory health insurance contracts sustain lowest sensitivity.
Supply Chain Analysis
Inventory lead times for monoclonal antibody reagents extend to 16-24 weeks, forcing assay manufacturers to pre-position bulk antibody stocks ahead of EU IVDR validation cycles. Production concentrates in Switzerland, the United States, and Germany, with Basel antibody production clusters feeding global ST2 assay assembly. Raw material dependencies center on recombinant IL1RL1 protein standards, horseradish peroxidase conjugates, and nitrocellulose membrane substrates. Single-source vulnerability runs through Swiss biologics suppliers for high-affinity capture antibodies. Distribution runs through specialized diagnostic distributors into hospital procurement committees and research institute purchasing offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ST2 biomarker testing sits in early-cycle expansion, with heart failure epidemiology and EU IVDR consolidation tailwinds supporting penetration gains ahead of saturation.
For Market Incumbents: Consolidate assay platform ecosystems through exclusive reagent contracts that lock in multi-year consumable commitments from integrated delivery networks. Acquire specialized lateral-flow developers to capture point-of-care expansion in Japanese emergency departments and German outpatient settings. Defend against NT-proBNP substitution by embedding ST2 into multiplex cardiac panels with galectin-3 and natriuretic peptides. For New Entrants and Emerging Players: Differentiate on asthma phenotyping applications in Japanese pulmonology practices, where national health insurance pilot programs create reimbursable demand outside saturated cardiology segments. Target diagnostic centers in India's Hyderabad and Bangalore laboratory chains, where Ayushman Bharat expansion drives volume-based reagent pricing negotiations. Pursue smartphone-reader integration partnerships for pharmacy-based heart failure screening models. For Investors and Strategic Acquirers: EU IVDR notified body backlogs reshape the acquisition landscape by stranding non-compliant developers and concentrating value in validated assay portfolios. Five-to-ten year viability favors specialized cardiac biomarker developers with proprietary ST2 assay formats and existing IVDR technical documentation. Monitor Japan PMDA orphan biomarker designation decisions as inflection signals for reimbursement-driven demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Technical Documentation Completion | Notified body conformity assessments unlock German statutory health insurance procurement channels. |
| Multiplex Assay Chemistry Re-architecture | Single-platform ST2-galectin-3-NT-proBNP combinations satisfy Cleveland Clinic laboratory consolidation demands. |
| Japan PMDA Orphan Biomarker Designation | Streamlined national health insurance inclusion accelerates Tokyo outpatient screening protocol adoption. |
| Lateral Flow Smartphone Reader Partnership | Osaka-based cardiac centers pilot pharmacy-based heart failure triage bypassing laboratory turnaround. |
| Monoclonal Antibody Backward Integration | Captive Basel-Zurich antibody production insulates against Swiss biologics supplier concentration risk. |
Research Methodology
The analysis maps CLIA platform, lateral-flow point-of-care, and research-grade reagent sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EMA biomarker qualification guidance documents, CMS Medicare reimbursement databases, and hospital procurement contract records. Bottom-up assay volume modeling and top-down market sizing triangulate segment outputs.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions include detection chemistry platform, product format tier, end-user site type, and therapeutic application area. CAGRs derive from installed base expansion rates, test volume per patient protocols, and pricing trajectory assumptions. Forecast inputs incorporate EU IVDR transition timelines, Japan PMDA reimbursement decisions, and Medicare bundled payment contract penetration.
Decision-makers should treat outputs as directional under assumptions of stable regulatory harmonization and continued heart failure epidemiology trends; material deviation in FDA-EMA pathway convergence or natriuretic peptide substitution rates would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Oligonucleotide Synthesis Market
Biomedical Technology
Life Science Analytics Market
Biomedical Technology
Biologics Outsourcing Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Global Protein Crystallization Market
Biomedical Technology
Southern Blotting Market
Biomedical Technology
Global Immunofluorescence Assay Market
Biomedical Technology
US Liquid Biopsy Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Brain Biomarkers Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Global Plant Stem Cell Market
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Europe Transfection Technologies Market
Biomedical Technology
Bacteriophage Market