
 Ligases Enzyme Market | 2026-2036
Ligases Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Ligases Enzyme Market Analysis
Pharmaceutical companies are expanding their share of ligase enzyme procurement as gene therapy pipelines multiply. Thermo Fisher Scientific Inc. dominates commercial supply chains through vertical integration into raw material sourcing and finished enzyme distribution. New England Biolabs anchors specialist demand with deep catalogs of high-fidelity ligase variants for cloning workflows. Novozymes A/S leverages fermentation scale to compete on cost for industrial biochemistry applications.
Ligases are a class of enzymes that catalyze the formation of phosphodiester bonds between adjacent nucleotides, typically requiring ATP or NAD+ as cofactors and operating optimally at pH ranges of 7.6–8.0 in magnesium-dependent reaction buffers. Their primary commercial purpose is to join DNA fragments in molecular biology workflows, enabling plasmid construction, next-generation sequencing library preparation, and CRISPR-mediated genome editing. Recombinant ligase variants now lead product type demand because engineered thermostability and reduced blunt-end bias command premium positioning in high-throughput sequencing pipelines. CRISPR technology applications represent the fastest-expanding segment as diagnostic developers and therapeutic manufacturers adopt ligase-dependent repair pathways for precise genomic modifications.
FDA oversight of gene therapy manufacturing and EMA's ATMP quality guidelines shape enzyme validation requirements, compelling suppliers to document host-cell protein clearance and lot-to-lot consistency. ISO 13485 certification and GMP compliance for diagnostic-grade ligases are becoming baseline requirements for market access in regulated jurisdictions. Stakeholders must monitor how evolving gene editing patent landscapes and emerging national biosecurity frameworks for synthetic biology reagents reshape supply chain sourcing decisions.
Market Dynamics
CRISPR-mediated genome editing workflows are compressing development timelines for gene therapies, forcing enzyme suppliers to validate thermostable ligase variants under accelerated FDA and EMA purity protocols. This technological inflection is redistributing procurement power toward pharmaceutical manufacturers with captive diagnostic divisions.
Growth Catalysts
- FDA Gene Therapy Guidance:The FDA's tightened host-cell protein clearance mandates for ATMP manufacturing are disqualifying non-recombinant ligase sources from commercial pipelines.
- NGS Library Prep Automation:High-throughput sequencing platforms in Boston and San Diego biotech clusters are standardizing on engineered high-fidelity ligases for blunt-end ligation workflows.
- Biosecurity Framework Expansion:National synthetic biology screening protocols in the United States and Germany are creating certified-supplier preference tiers that favor documented recombinant production.
Market Restraints
- Fermentation Input Volatility:Magnesium cofactor and ATP precursor costs fluctuate with industrial chemical supply chains concentrated in Chinese bulk manufacturing.
- Specialist Supplier Concentration:High-fidelity variant development resides with a narrow base of US and Danish enzyme engineering houses, creating single-source vulnerability for GMP-grade lots.
- Thermostability Trade-offs:Engineered ligases with enhanced thermal tolerance exhibit elevated blunt-end bias that degrades cloning fidelity in certain insert-size ranges.
Strategic Opportunities
- India CDMO Expansion:Contract development organizations in Hyderabad and Bengaluru are building ligase production capacity to serve domestic gene therapy startups under CDSCO's emerging ATMP pathway.
- Diagnostic-Grade Certification:ISO 13485-compliant ligase kits for CRISPR-based infectious disease assays open procurement channels separate from research-grade supply.
- AI-Directed Enzyme Engineering:Machine learning platforms for protein structure prediction are converging with high-throughput screening to accelerate variant optimization cycles.
Industry Challenges
- GMP Lot Release Timelines:FDA and EMA validation documentation for host-cell protein clearance extends production schedules by 8-14 weeks for new recombinant strains.
- CRISPR Patent Thickets:Licensing complexity around Cas9 and base-editing platforms creates uncertainty for ligase-dependent repair pathway suppliers in therapeutic applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ligases Enzyme Market |
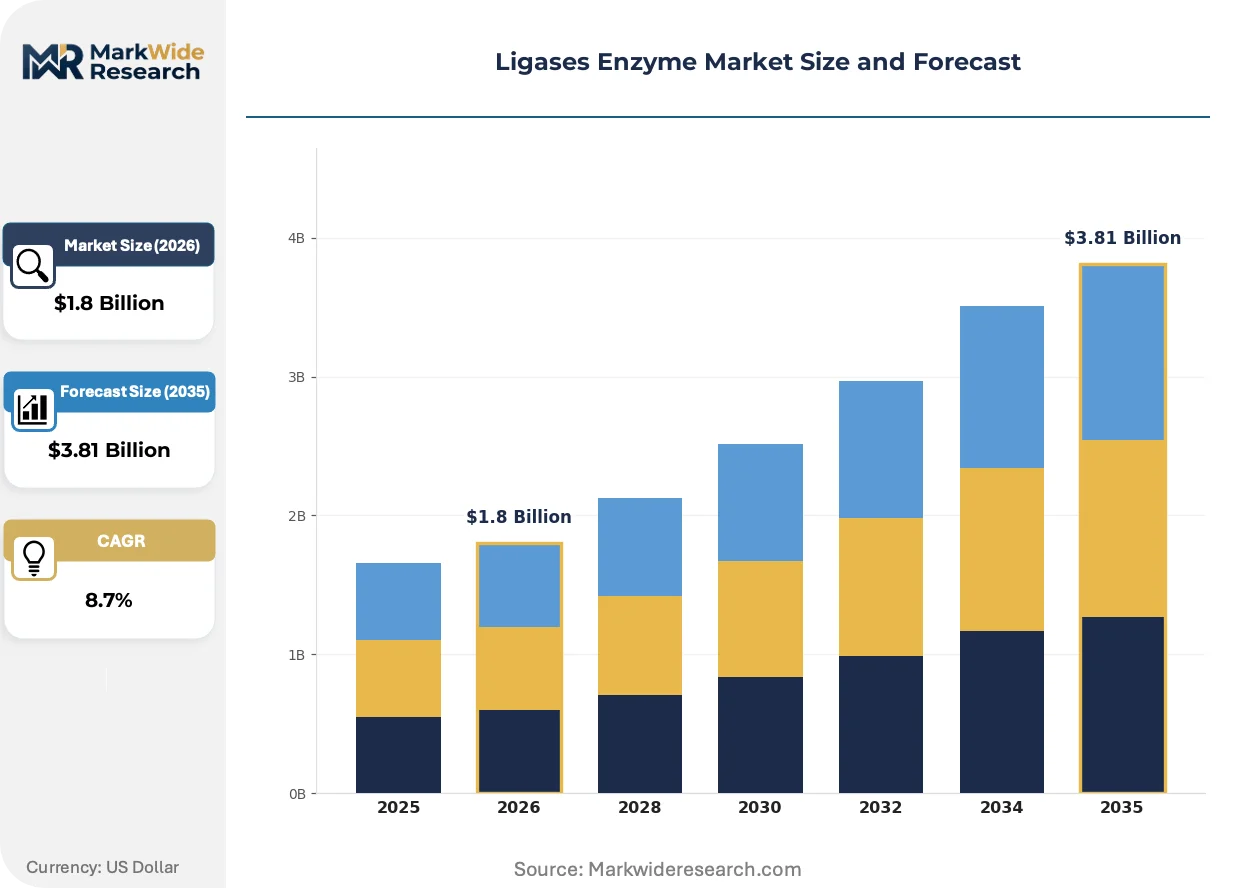
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant, Native, Synthetic, Others Application: Molecular Biology, Genetic Engineering, Biochemistry, Diagnostics End User: Pharmaceutical Companies, Research Laboratories, Academic Institutions, Biotech Firms Technology: RT-PCR, Gene Cloning, Sequencing, CRISPR |
| Companies Covered | Thermo Fisher Scientific Inc., New England Biolabs, Novozymes A/S, Merck KGaA, Agilent Technologies Inc., QIAGEN, Takara Bio Inc., ArcticZymes Technologies, Codexis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ligases Enzyme Market Emerging Trajectories
Enzyme engineering and regulatory certification are converging to reshape competitive positioning in ligase supply. Thermostability optimization, GMP-grade documentation automation, and procurement channel specialization define the current innovation frontier.
Engineered thermostable ligase variants are absorbing demand from wild-type enzymes in next-generation sequencing pipelines. Diagnostic manufacturers in the United States are adopting these variants at compressed validation cycles. The technology is absorbing margin pressure from commoditized research-grade supply by commanding premium positioning in automated liquid-handling workflows.
EMA's ATMP quality guidelines and the FDA's updated gene therapy chemistry, manufacturing, and controls framework are tightening documentation requirements for enzyme suppliers. Manufacturers must now demonstrate lot-to-lot consistency in host-cell protein profiles and magnesium-dependent activity specifications. European and US therapeutic developers are responding by consolidating procurement around suppliers with pre-validated GMP master files.
Buying patterns among pharmaceutical end-users are fragmenting across research-grade, diagnostic-grade, and GMP-tier supply channels. Large molecule developers are unbundling after-sales technical support from enzyme procurement, sourcing validation consulting separately through specialized CDMOs. This disintermediation is most pronounced in the United States, where Boston and San Diego biotech clusters maintain dedicated sourcing teams for enzyme qualification.
Ligases Enzyme Market Segmentation
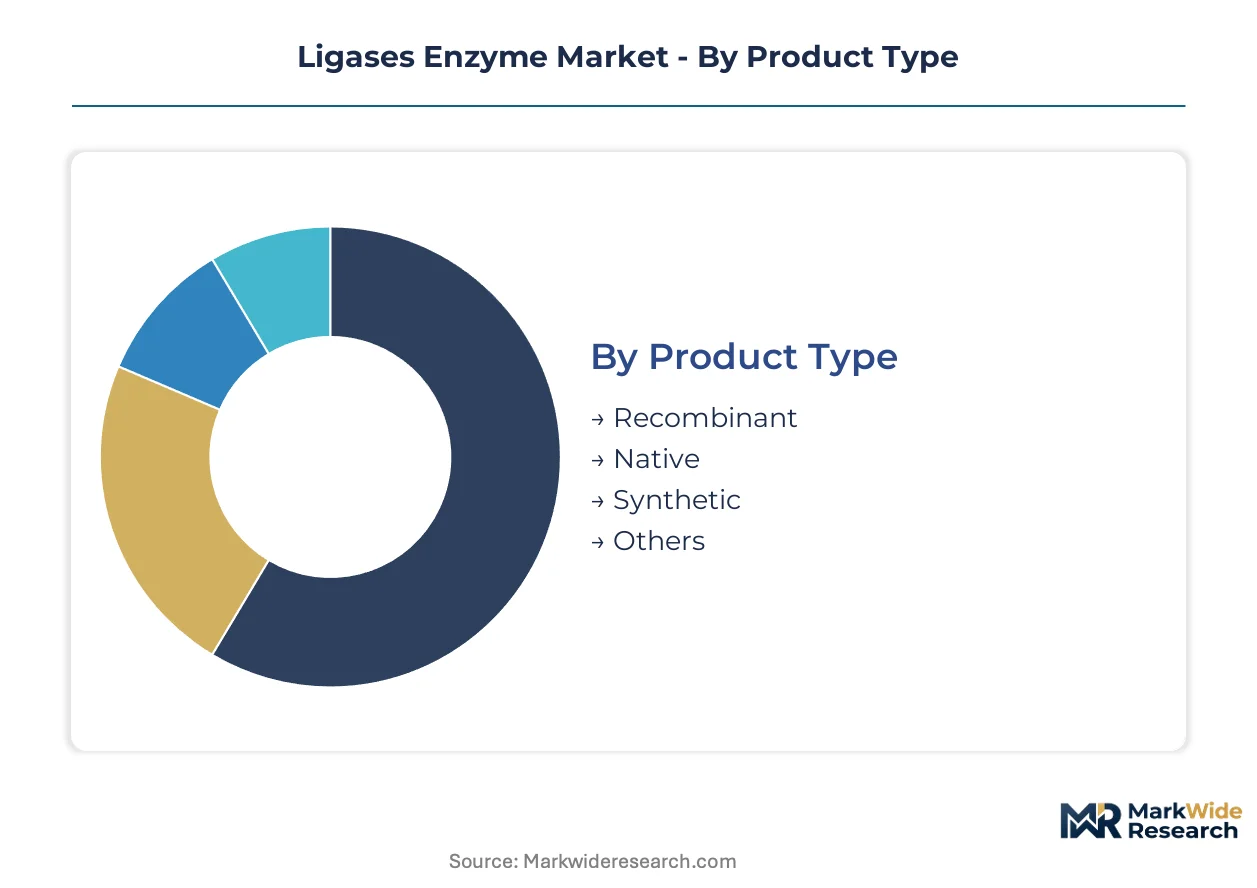
Enzyme procurement patterns fragment sharply across certification tiers and workflow integration depth. Buyers sort ligase supply by regulatory grade, thermal performance specifications, and automation compatibility rather than crude product categories alone.
Product Type:
Standardization dominates at the research-grade tier while recombinant variants command premium positioning through documented host-cell clearance.
- Recombinant:Engineered variants with thermostability modifications and reduced blunt-end bias absorb procurement from pharmaceutical manufacturers under FDA gene therapy mandates. Boston and San Diego biotech clusters standardize on these enzymes for automated NGS library preparation workflows.
- Native:Wild-type ligases purified from bacteriophage T4 retain cost advantages in academic settings with manual cloning protocols. Procurement volumes are compressing as EMA ATMP guidelines disqualify non-recombinant sources from commercial therapeutic pipelines.
- Synthetic:Chemically synthesized peptide ligases serve specialized applications requiring non-immunogenic cofactor profiles.
- Others:Hybrid enzyme formulations and fusion protein constructs address niche workflow integration requirements.
Leading the category by volume: Recombinant. Growing fastest: Synthetic.
Application:
Workflow automation intensity separates high-margin diagnostic-grade demand from commoditized research consumption.
- Molecular Biology:Cloning and plasmid construction workflows consume standardized T4 DNA ligase at scale. Academic laboratories in Germany and the United States drive procurement through bulk purchasing consortia.
- Genetic Engineering:CRISPR-mediated repair pathways require high-fidelity variants with validated blunt-end ligation efficiency. Gene therapy developers in Boston and Hyderabad are consolidating supply around GMP-certified recombinant sources.
- Biochemistry:Industrial protein engineering applications leverage cost-optimized native enzymes for non-therapeutic modifications.
- Diagnostics:ISO 13485-certified ligase kits for infectious disease assays open procurement channels with compressed validation cycles separate from research supply.
Genetic Engineering commands the steepest expansion trajectory. Molecular Biology retains the largest installed base.
End User:
Regulatory sophistication and captive diagnostic capabilities determine pricing tolerance across buyer categories.
- Pharmaceutical Companies:Integrated gene therapy developers with in-house sequencing divisions are unbundling technical support from enzyme procurement. FDA and EMA compliance documentation now precedes price negotiation in vendor selection.
- Research Laboratories:Core facilities at US academic medical centers standardize on engineered thermostable variants for high-throughput service operations.
- Academic Institutions:Individual investigator grants sustain demand for economy-grade native enzymes with manual protocol compatibility.
- Biotech Firms:Venture-backed startups in Bengaluru and San Diego prioritize diagnostic-grade certification for dual-use research and clinical assay development.
Pharmaceutical Companies dominate procurement value. Biotech Firms are climbing the fastest.
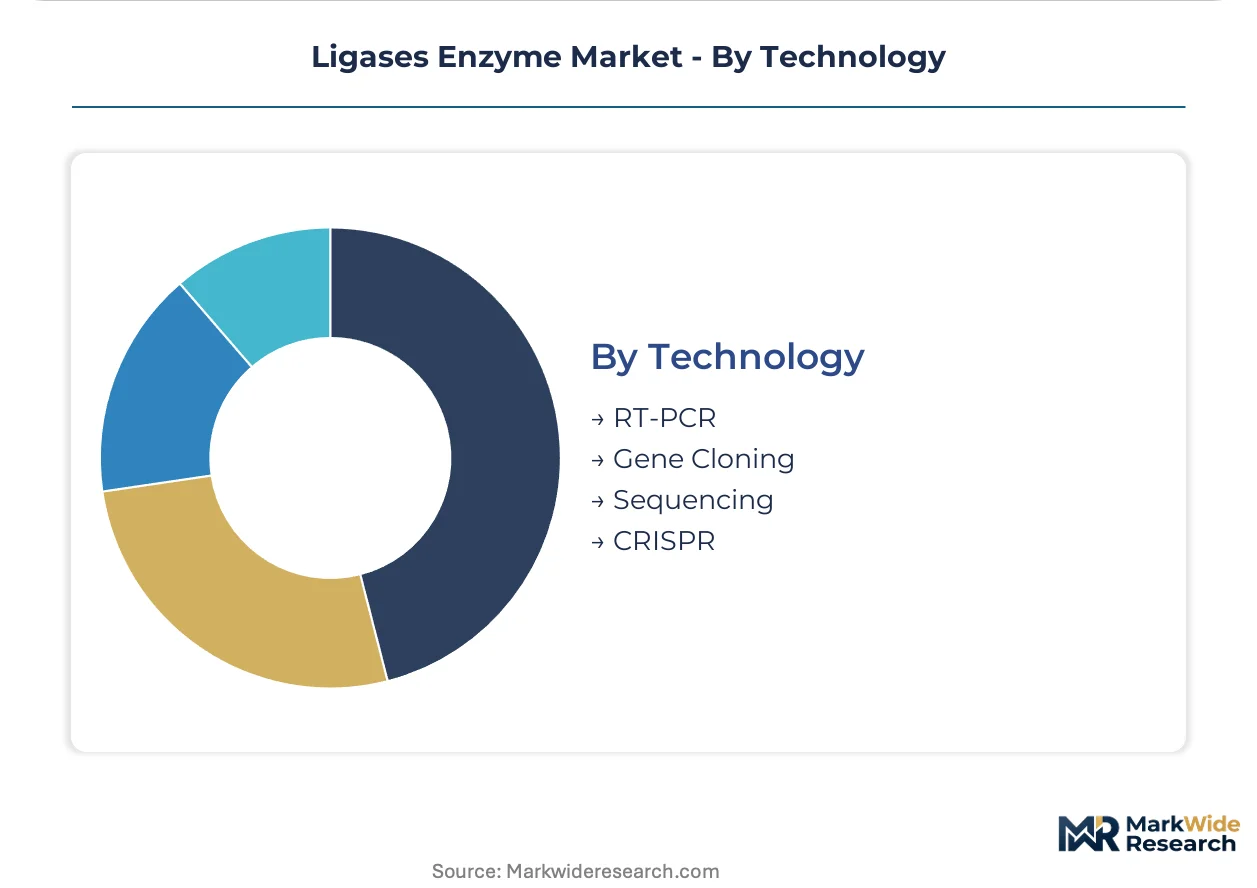
Technology:
Patent licensing complexity and platform automation maturity reshape enzyme specification requirements.
- CRISPR:Base-editing and prime-editing workflows demand ligases with validated compatibility for precise genomic modification repair pathways. Therapeutic developers face uncertainty from overlapping Cas9 patent estates.
- Sequencing:Next-generation library preparation automation requires thermostable variants with consistent performance in magnesium-dependent buffers across thermal cycling conditions.
- Gene Cloning:Traditional restriction-ligation workflows persist in academic settings with established manual protocols.
- RT-PCR:Reverse transcription quantitative PCR applications integrate ligase-dependent detection chemistries for pathogen identification.
Sequencing anchors current procurement volumes. CRISPR exhibits the most rapid adoption acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Denmark and the United States, while consumption tilts toward gene therapy clusters in North America and emerging biotech hubs in India. This geographic split shapes supply chain configurations and regulatory compliance requirements across procurement networks.
United States
FDA gene therapy guidance drives demand for GMP-certified recombinant ligases among Boston and San Diego biotech clusters. The agency's host-cell protein clearance mandates disqualify non-recombinant sources from commercial pipelines. Massachusetts and California research institutions standardize on engineered thermostable variants for automated NGS workflows.
Germany
EMA's ATMP quality guidelines compel therapeutic developers to document lot-to-lot consistency in enzyme specifications. Heidelberg and Munich biotech firms consolidate procurement around suppliers with pre-validated GMP master files. The country's national pharmaceutical regulator enforces stringent validation documentation for gene therapy manufacturing inputs.
India
CDSCO's emerging ATMP pathway stimulates contract development organization investment in Hyderabad and Bengaluru. Domestic gene therapy startups source recombinant ligases for clinical assay development. The central government's PLI scheme for biotechnology supports fermentation capacity expansion for industrial enzyme production.
Denmark
Novozymes A/S anchors global supply through large-scale fermentation infrastructure serving industrial biochemistry applications. Danish enzyme engineering houses develop high-fidelity variants for pharmaceutical manufacturers. Copenhagen's biotech ecosystem specializes in cost-optimized native enzymes for non-therapeutic protein modifications.
Japan
PMDA oversight of regenerative medicine products shapes enzyme validation requirements for domestic gene therapy developers. Tokyo and Osaka pharmaceutical firms adopt ISO 13485-certified ligase kits for diagnostic applications. METI funding for synthetic biology research accelerates procurement of engineered variants for CRISPR-mediated repair pathways.
Ligases Enzyme Market Vendor Landscape
Top-tier vendors anchor GMP-grade supply chains, while mid-tier specialists compete on research-grade customization and regional CDMO partnerships. The vendor base stratifies across three certification tiers: diagnostic-grade ISO 13485 holders, research-grade catalog suppliers, and industrial-scale fermentation operators. Two strategic archetypes dominate: vertically integrated life science conglomerates with captive raw material sourcing, and focused enzyme engineering houses with deep variant catalogs. Capacity expansion in Indian CDMOs and backward integration into magnesium cofactor supply represent the primary competitive moves reshaping procurement economics.
Within the premium-tier certification segment, Thermo Fisher Scientific Inc. and New England Biolabs occupy positions as archetypal representatives of scale-driven and specialist strategies respectively. Novozymes A/S exemplifies the industrial fermentation archetype competing on cost for bulk biochemistry applications. These three companies collectively illustrate how geographic origin—American, American, and Danish—correlates with distinct competitive positioning around regulatory sophistication, catalog depth, and manufacturing scale.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| New England Biolabs |
| Novozymes A/S |
| Merck KGaA |
| Agilent Technologies Inc. |
| QIAGEN |
| Takara Bio Inc. |
| ArcticZymes Technologies |
| Codexis Inc. |
| Others |
Supply Flow & Price Mechanics
Backward integration into magnesium cofactor sourcing anchors pricing power for ligase manufacturers serving GMP-grade therapeutic markets. This upstream control over ATP precursor and magnesium supply buffers margin compression from fermentation input volatility while locking in supply security for FDA-validated production runs.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery schedules for GMP-grade recombinant ligases. Pricing stratifies across diagnostic-grade ISO 13485 certification, research-grade catalog supply, and industrial-scale native enzyme tiers. Cost compression in research-grade segments is intensifying because academic consortia consolidate bulk purchasing power. Biotech startups in Boston and San Diego exhibit lowest price sensitivity due to compressed gene therapy development timelines.
Supply Chain Analysis
Returns and lot rejection flows concentrate in the GMP validation stage where host-cell protein clearance failures trigger 8-14 week remake cycles. Production gravity centers on Denmark, the United States, and emerging capacity in India. Fermentation inputs draw from Chinese bulk chemical manufacturing for magnesium and ATP precursors. Single-source vulnerability persists for high-fidelity variant engineering concentrated in US and Danish specialist houses. Distribution runs through direct pharmaceutical procurement channels and specialized life science distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP-grade fermentation capacity constraints prop pricing premiums as FDA and EMA validation timelines stretch supplier lead times. This supply bottleneck favors incumbents with pre-validated master files and captive production assets.
For Market Incumbents: To counter emerging CDMO competition from Indian contract manufacturers, prioritize ISO 13485 certification automation and backward integration into magnesium cofactor supply. Lock in multi-year offtake agreements with Boston and San Diego gene therapy developers to secure volume commitments ahead of capacity expansions. For New Entrants and Emerging Players: The mid-tier price gap between premium GMP-grade and economy research-grade ligases offers white-space entry for diagnostic-grade specialists. Target Hyderabad and Bengaluru biotech startups seeking dual-use research and clinical assay enzymes. Lead with compressed validation cycles and regional technical support unbundled from product pricing. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to vertically integrated life science conglomerates seeking GMP enzyme capabilities. Five-to-ten year viability favors specialists with pre-validated FDA master files and thermostable variant IP. Monitor CDSCO ATMP pathway acceleration in India as inflection signal for regional supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Master File Expansion | Pre-validated documentation accelerates FDA gene therapy product approvals. |
| Thermostable Variant Development | Engineered enzymes capture NGS automation demand from Boston sequencing clusters. |
| Indian CDMO Partnership | Hyderabad fermentation capacity serves domestic gene therapy startups under CDSCO pathway. |
| Diagnostic-Grade Certification | ISO 13485 compliance opens infectious disease assay procurement channels. |
| AI-Directed Enzyme Engineering | Machine learning platforms compress variant optimization cycles for CRISPR applications. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with gene therapy development executives, regulatory affairs leads at enzyme suppliers, GMP quality officers, and diagnostic assay developers combined with FDA guidance documents, EMA ATMP submissions, and CDSCO pathway notifications. Bottom-up procurement volume estimates triangulated against top-down fermentation capacity assessments across Denmark, the United States, and India.
Data-stream reconciliation across shipment records, import manifests, and supplier revenue disclosures validated segment-level estimates. Modeled dimensions span product type, application workflow, end-user regulatory sophistication, and geographic certification cluster. CAGRs derived from slope analysis of annual procurement growth rates adjusted for pipeline conversion probabilities. CRISPR patent landscape evolution and biosecurity framework implementation tracked as scenario variables.
Inputs from FDA and EMA regulatory databases were available through the study window; gaps in CDSCO emerging pathway enforcement timelines introduce uncertainty bands for Indian market projections. Forecasts reflect assumptions about gene therapy pipeline maturation and GMP capacity expansion schedules. Practitioners should monitor ATMP guideline harmonization progress and synthetic biology export control expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Nucleic Acid Aptamers Market
Biomedical Technology
North America Exosome Research Products Market
Biomedical Technology
Global Glycobiology Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Rat and Mouse Model Market
Biomedical Technology
Global Cell Based Assays Market
Biomedical Technology
E2 Antibody Market
Biomedical Technology
Antibody Library Technology Market
Biomedical Technology
Vaccine Technology Market
Biomedical Technology
Global Protein Crystallization and Crystallography Market
Biomedical Technology
Global Protein Characterization and Quantification Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
DNA Synthesis Market
Biomedical Technology
Global Tissue Microarray Market
Biomedical Technology
DNA Forensics Market
Biomedical Technology
Middle East and Africa Exosome Research Products Market