
 Colon Hydrotherapy Units Market | 2026-2036
Colon Hydrotherapy Units Market Size, Share, and Industry Trends Forecast 2026-2036
Colon Hydrotherapy Units Market Outlook
Equipment leasing and pay-per-use arrangements are rewriting capital deployment patterns for colon hydrotherapy unit procurement, lowering barriers for mid-sized wellness operators. Dotolo Research Corporation leverages its longstanding manufacturing scale to sustain dominant positions in gravity-based system supply. Herrmann Apparatebau anchors European demand through precision engineering traditions and localized regulatory compliance capabilities. Zhengzhou Gold Elite Industry competes aggressively on production cost structures while extending distribution networks across Asia-Pacific markets.
Colon hydrotherapy units are closed or open-system medical devices designed to introduce temperature-controlled, filtered water into the colon for cleansing procedures, typically operating at pressures between 0.5 and 2.0 psi with integrated waste evacuation and odor-control subsystems. Their primary commercial purpose centers on supporting digestive wellness protocols, pre-operative bowel preparation, and complementary therapy programs administered under licensed practitioner supervision. Closed system configurations command premium positioning due to enhanced patient comfort controls and automated pressure regulation, while open system variants occupy value-oriented segments in high-volume spa environments. Electronic units integrating ultrasonic technology lead innovation pipelines, though gravity-based technology sustains cost-sensitive clinic procurement patterns across developing markets.
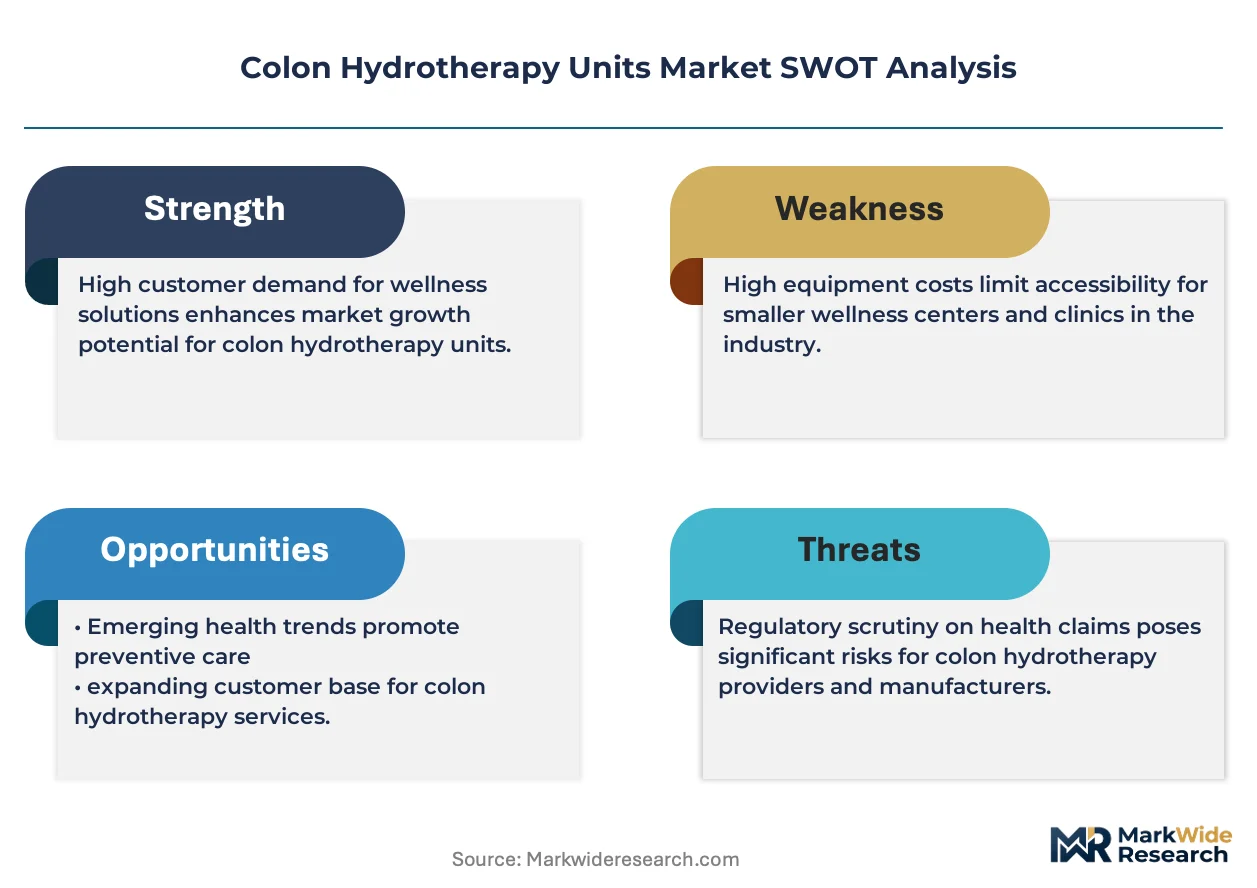
FDA 510(k) clearance requirements and EU MDR technical documentation obligations shape device commercialization timelines and compliance expenditures for manufacturers targeting Western markets. Health Canada and Australia's TGA impose parallel quality system standards that filter market access for firms lacking established regulatory affairs infrastructure. ISO 13485 certification functions as a baseline qualification for original equipment manufacturers seeking multi-jurisdictional distribution partnerships. Stakeholders must monitor evolving state-level scope-of-practice regulations governing non-physician operator certification, as jurisdictional fragmentation directly influences addressable market boundaries and service model legality.
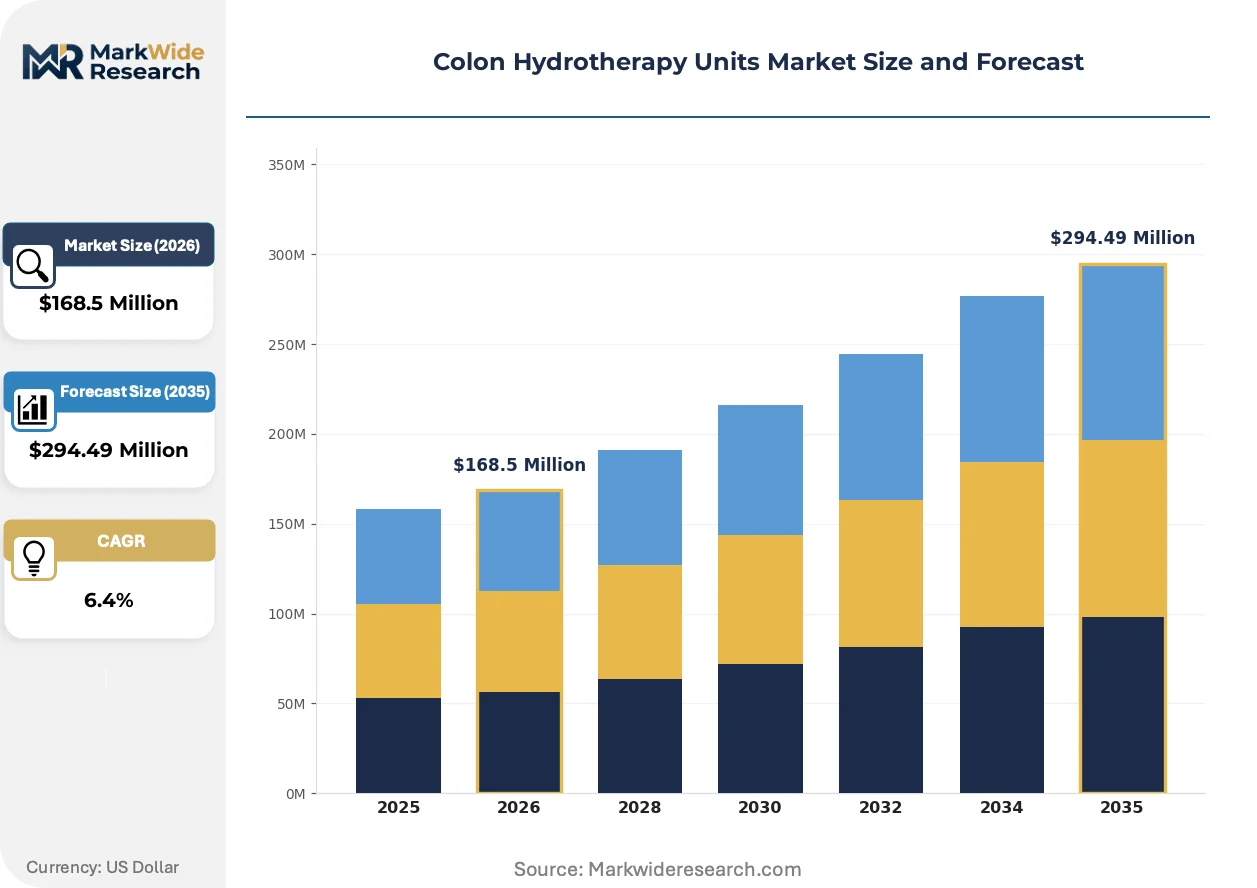
Market Dynamics
Equipment leasing structures are compressing capital barriers for mid-sized wellness operators, while FDA 510(k) and EU MDR compliance timelines are elongating product commercialization cycles for manufacturers targeting Western markets.
Growth Catalysts
- Preventive wellness protocols:Spa and clinical operators in Germany and Australia are integrating hydrotherapy into digestive health maintenance programs, expanding addressable service volumes beyond traditional medical indications.
- EU MDR harmonization:Unified technical documentation requirements across European member states are reducing multi-jurisdictional registration fragmentation, enabling faster cross-border distribution for certified manufacturers.
- Ultrasonic integration:Electronic units incorporating ultrasonic technology are displacing gravity-based systems in premium clinic segments, commanding higher per-procedure reimbursement rates.
Market Restraints
- Stainless steel input volatility:Medical-grade 316L stainless steel price fluctuations are compressing margin structures for precision-engineered closed-system manufacturers.
- Operator certification fragmentation:State-level scope-of-practice variations across the United States create jurisdictional complexity that limits standardized service model deployment.
- Substitute colonoscopy prep:Oral polyethylene glycol solutions for surgical bowel preparation retain cost and convenience advantages in hospital settings.
Strategic Opportunities
- Underpenetrated Canadian market:Health Canada device licensing pathways, while rigorous, remain less congested than FDA queues, offering first-mover positioning for compliant entrants.
- Home-use regulatory tailwind:Australia's TGA is evaluating expanded device classifications for supervised home-based hydrotherapy, potentially unlocking direct-to-consumer channels.
- Pay-per-use channel innovation:Equipment-as-a-service models are displacing outright purchase arrangements, lowering customer acquisition costs for emerging wellness chains.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for multi-jurisdictional market access require 12-18 month implementation cycles that delay revenue recognition.
- Integration complexity with electronic health records:Closed-system units generating procedure data face interoperability friction with legacy clinic management platforms.
- Specialized technician training gaps:Certified hydrotherapist programs remain concentrated in urban wellness hubs, constraining service expansion into secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colon Hydrotherapy Units Market |
| Market Size in 2026 | $168.5 Million |
| Market Size in 2035 | $294.49 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed System, Open System, Electronic Units, Manual Units Technology: Ultrasonic Technology, Hydrostatic Technology, Gravity-Based Technology, Pressure-Controlled Technology End User: Clinics, Wellness Centers, Home Care, Health Spas Capacity: 1-2 Patients, 3-5 Patients, 6-10 Patients, Others |
| Companies Covered | Colonic Network, TRANSCOM, Prime Pacific Health Innovations, iCLear, Cerajivan Healthtech, Herrmann Apparatebau, Dotolo Research Corporation, Zhengzhou Gold Elite Industry, Lifestream Purification Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colon Hydrotherapy Units Market Strategic Shifts
Digital control architectures are displacing mechanical pressure regulation in next-generation units, while regulatory documentation automation is compressing compliance overhead for multi-market entrants.
Closed-system colon hydrotherapy units are digitizing pressure regulation through sensor-integrated feedback loops that maintain 0.5-2.0 psi ranges with precision unattainable through gravity-based mechanisms. Premium wellness centers in California and Bavaria are prioritizing these configurations for patient comfort differentiation. The technology is digitizing procedural documentation, enabling automated compliance logging that reduces manual record-keeping labor.
EU MDR technical documentation obligations are mandating clinical evidence packages that exceed legacy Medical Device Directive requirements, particularly for Class IIa devices with patient-contact components. Manufacturers are restructuring regulatory affairs teams to accommodate notified body review timelines extending 18-24 months. Closed-system configurations with automated waste evacuation subsystems face the most stringent biocompatibility testing burdens.
Wellness operators are unbundling after-sales service contracts from equipment procurement, instead sourcing maintenance through third-party biomedical technicians. This pattern is displacing manufacturer-captive service agreements that historically captured recurring revenue streams. The shift is most visible in United States metropolitan markets where independent service organizations have achieved critical density.
Colon Hydrotherapy Units Market Segmentation
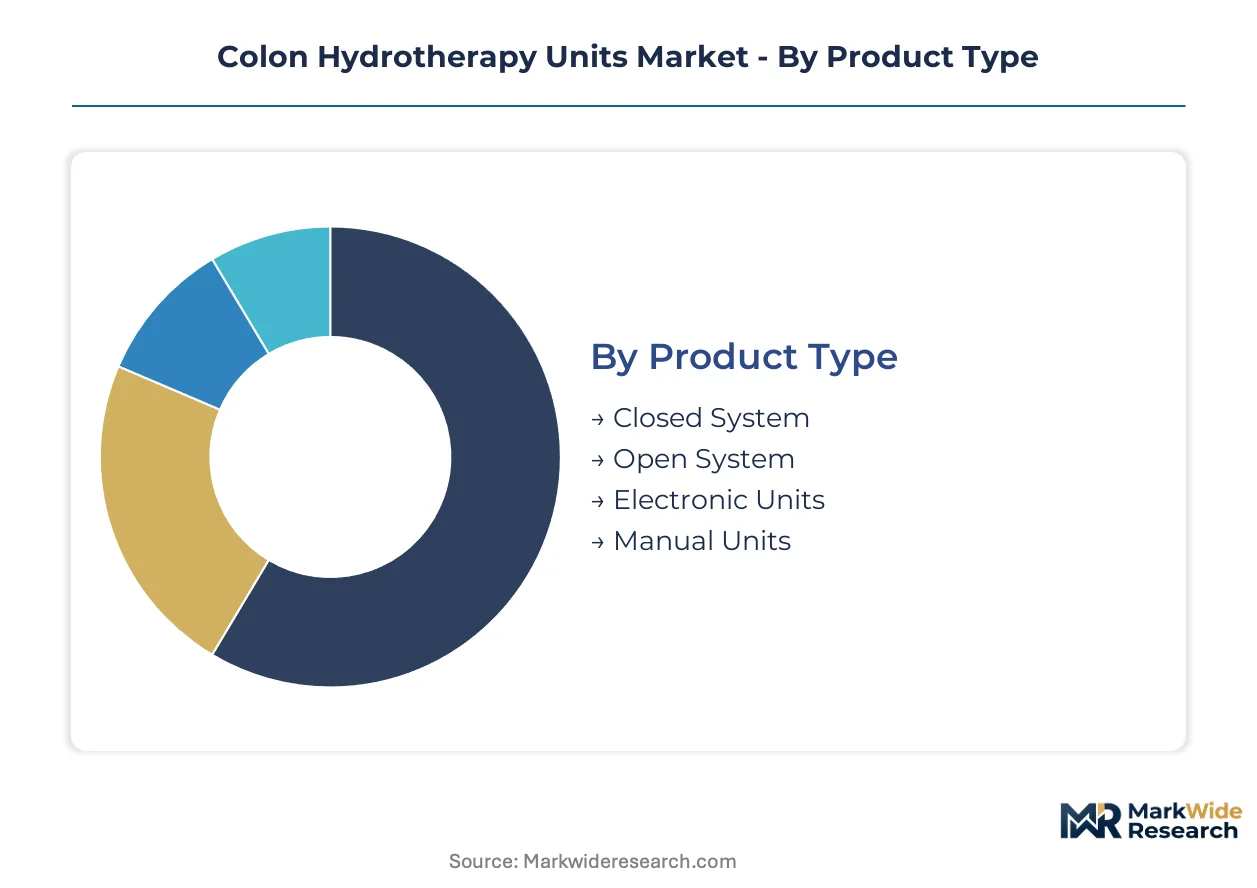
Segmentation in colon hydrotherapy units reveals how clinical requirements diverge from wellness aesthetics and how regulatory pathways fragment across use environments. Manufacturers configure pressure systems, waste handling, and operator interfaces differently for each channel, creating distinct margin structures and compliance burdens.
Product Type:
Cost tier differentiation separates premium closed configurations from value-oriented open alternatives, with automation levels driving procurement decisions across end-use settings.
- Closed System:Sealed pressure-regulated architectures with automated waste evacuation and odor containment subsystems. Premium wellness centers in California and Bavaria prioritize these units for patient comfort differentiation and liability risk reduction. FDA 510(k) clearance requirements extend commercialization timelines but lock in reimbursement advantages.
- Open System:Gravity-fed designs with simplified mechanical construction and lower per-unit capital requirements. High-volume spa operators in Florida and Texas favor these configurations for throughput economics where practitioner supervision remains constant.
- Electronic Units:Sensor-integrated platforms with digital pressure feedback and automated procedural logging. Germany's clinical procurement channels show concentrated demand for documentation capabilities supporting quality audits.
- Manual Units:Hand-operated pressure control without electronic components, serving cost-sensitive clinic segments in developing markets where maintenance infrastructure is limited.
Closed systems command the established base. The steepest expansion runs through electronic units integrating ultrasonic capabilities.
Technology:
Application requirements dictate technology selection, with clinical precision demands pulling toward electronic feedback systems while spa volume economics sustain gravity-based alternatives.
- Ultrasonic Technology:High-frequency acoustic integration enabling tissue-level diagnostic feedback during hydrotherapy procedures. Australia's TGA is evaluating expanded indications for these platforms in supervised home settings.
- Hydrostatic Technology:Fluid column pressure management with calibrated height differentials. German precision engineering traditions anchor European manufacturing concentration for these systems.
- Gravity-Based Technology:Passive pressure generation through elevated water reservoir positioning. These units sustain dominant share in India's emerging wellness infrastructure where capital constraints limit electronic system adoption.
- Pressure-Controlled Technology:Active servo-mechanisms maintaining 0.5-2.0 psi ranges with real-time adjustment. United States metropolitan clinics prioritize these configurations for liability documentation and patient safety protocols.
Gravity-based technology holds volume leadership. Pressure-controlled systems are climbing the fastest as regulatory documentation requirements tighten.
End User:
Customer type determines regulatory pathway complexity, with clinical settings demanding full medical device certification while spa environments navigate lighter oversight frameworks.
- Clinics:Licensed medical facilities requiring FDA 510(k) or EU MDR Class IIa compliance with full quality system documentation. Pre-operative bowel preparation applications in United States hospital outpatient departments sustain procurement concentration.
- Wellness Centers:Preventive health facilities integrating hydrotherapy into digestive maintenance protocols. Germany's statutory wellness program reimbursements are expanding addressable service volumes beyond traditional medical indications.
- Home Care:Supervised residential use with emerging regulatory frameworks. Australia's TGA home-use classification evaluation could unlock direct-to-consumer distribution channels.
- Health Spas:Aesthetic-focused operators prioritizing patient experience and throughput. California's luxury wellness corridor shows concentrated demand for closed-system configurations with premium finishing.
Clinics anchor current revenue concentration. Wellness centers are gaining share fastest as preventive health protocols expand reimbursement eligibility.
Capacity:
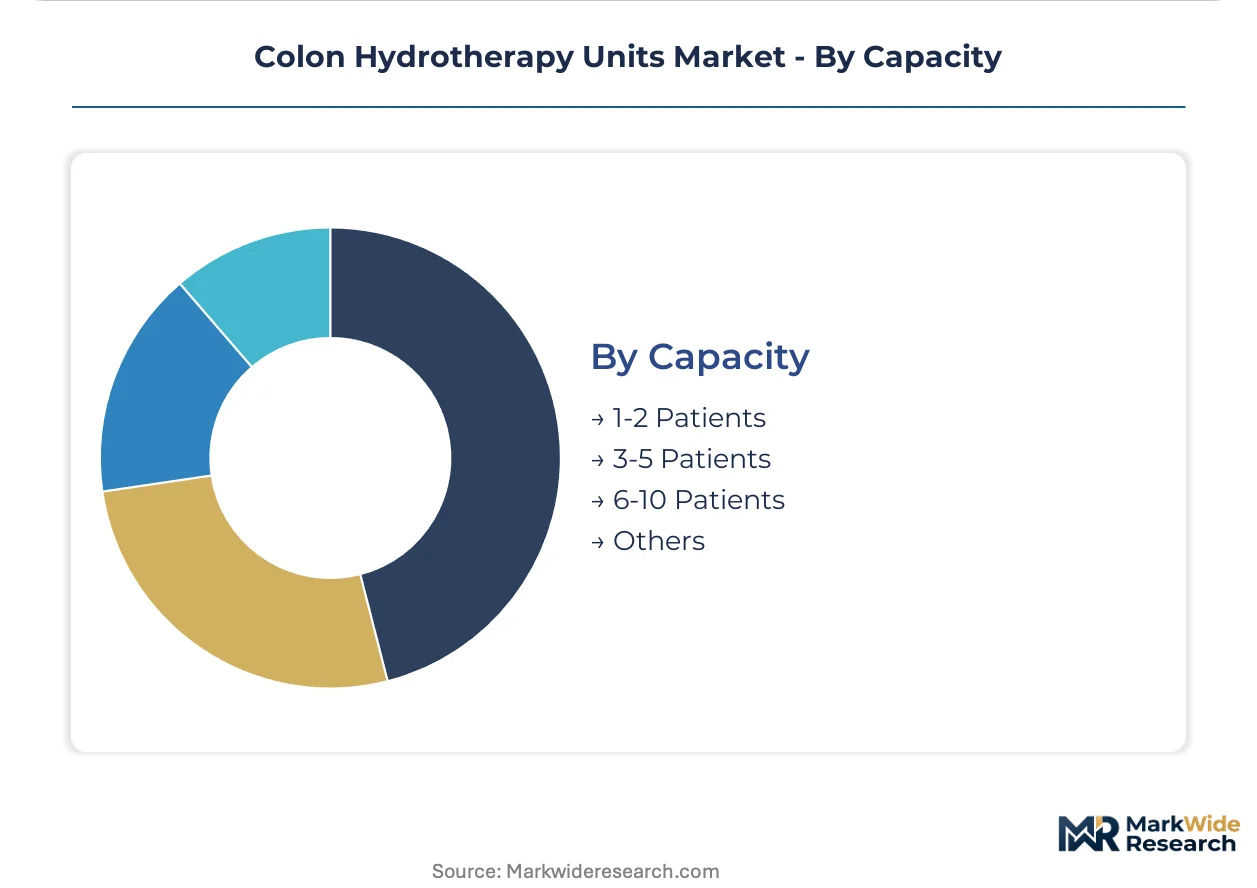
Volume scale aligns with operational model economics, with multi-station configurations serving high-throughput environments while single-patient units match boutique service positioning.
- 1-2 Patients:Compact footprints for independent practitioners and mobile service operators. Australia's rural wellness outreach programs favor these configurations for transportability.
- 3-5 Patients:Mid-scale installations matching franchise wellness chain requirements. United States metropolitan rollouts by emerging regional brands concentrate procurement here.
- 6-10 Patients:High-volume installations for destination wellness resorts and hospital outpatient centers. Germany's integrated health spa chains (Kurorte) sustain demand for these configurations.
- Others:Custom installations and specialized mobile units serving event-based or institutional contract services.
3-5 patient configurations dominate current installations. 6-10 patient systems are expanding most quickly as wellness chains consolidate operational footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory wellness program reimbursements for preventive digestive health protocols are expanding service eligibility beyond traditional medical indications, while Australia's TGA evaluates home-use device classifications that could unlock direct-to-consumer distribution channels.
United States
California's luxury wellness corridor and Florida's high-volume spa operators drive divergent procurement patterns, with closed-system configurations dominating premium positioning. FDA 510(k) clearance requirements extend commercialization timelines but lock in reimbursement advantages for compliant manufacturers. Metropolitan clusters in Los Angeles and Miami sustain concentrated demand for electronic units with automated documentation capabilities.
Germany
Precision engineering traditions in Bavaria anchor European manufacturing concentration for hydrostatic technology systems. The EU MDR's unified technical documentation requirements reduce multi-jurisdictional registration fragmentation, enabling faster cross-border distribution for certified manufacturers. Integrated health spa chains in Baden-Württemberg sustain procurement of 6-10 patient capacity installations.
Australia
Rural wellness outreach programs favor compact 1-2 patient configurations for transportability across dispersed populations. The TGA's evaluation of expanded device classifications for supervised home-based hydrotherapy signals potential regulatory tailwinds for direct-to-consumer channels. Sydney and Melbourne metropolitan markets concentrate demand for premium closed-system units.
Canada
Health Canada device licensing pathways remain less congested than FDA queues, offering first-mover positioning for compliant entrants targeting underpenetrated provincial markets. Ontario's emerging wellness chains are adopting equipment-as-a-service procurement models that displace outright purchase arrangements. Vancouver's preventive health operators integrate hydrotherapy into digestive maintenance protocols.
India
Capital constraints in emerging wellness infrastructure sustain dominant share for gravity-based technology systems. The country's national medical device regulator imposes quality system standards that filter market access for firms lacking established regulatory affairs infrastructure. Maharashtra's urban wellness hubs show early adoption of electronic units among premium clinic operators.
Colon Hydrotherapy Units Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans legacy manufacturers with captive distribution networks and emerging entrants leveraging third-party service organizations. Three archetypes dominate: precision-engineering specialists with multi-jurisdictional compliance capabilities, cost-optimized fabricators serving developing markets, and integrated wellness solution providers bundling equipment with training protocols. Competitive moves concentrate on geographic expansion through regulatory certification stacking and portfolio diversification into adjacent hydrotherapy modalities.
Among North American-established operators, Dotolo Research Corporation occupies a position representing scale-driven manufacturing heritage, while Herrmann Apparatebau exemplifies European precision-engineering specialization. Zhengzhou Gold Elite Industry represents cost-optimized production archetypes extending distribution across Asia-Pacific markets. These three anchors illustrate how geographic origin and organizational structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Colonic Network |
| TRANSCOM |
| Prime Pacific Health Innovations |
| iCLear |
| Cerajivan Healthtech |
| Herrmann Apparatebau |
| Dotolo Research Corporation |
| Zhengzhou Gold Elite Industry |
| Lifestream Purification Systems |
| Others |
Value Chain & Pricing Dynamics
Freight corridors connecting Bavarian precision-engineering clusters to North American wellness operators transmit stainless steel cost volatility into downstream price spreads, while FDA-grade certification requirements lock premium tiers away from gravity-fed alternatives serving cost-sensitive spa chains.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE-MDR tier) creates the primary spread between premium closed-system configurations and value-oriented open alternatives. Three-tier pricing structure across premium electronic, standard hydrostatic, and economy gravity-based levels stratifies procurement budgets across clinic and spa archetypes. Pricing pressure stems from medical-grade 316L stainless steel input fluctuations compressing margin structures for precision-engineered manufacturers. Wellness chains in high-volume Florida markets exhibit acute price sensitivity, while German integrated health spa operators absorb premium positioning for liability documentation advantages.
Supply Chain Analysis
Export-control restrictions on precision sensor components limit flows from German engineering hubs to emerging Asia-Pacific assemblers, concentrating advanced electronic unit production in EU and North American facilities. Manufacturing gravity centers on Germany, the United States, and China, with Bavarian workshops feeding hydrostatic technology specialization and Zhengzhou fabricators anchoring cost-optimized gravity system output. Component sourcing draws from medical-grade stainless steel suppliers, ultrasonic sensor foundries, and FDA-compliant polymer molding operations. Single-source vulnerability concentrates in precision pressure-regulation subassemblies. Distribution runs through manufacturer-direct channels for large clinic networks, with independent biomedical service organizations displacing captive after-sales agreements in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colon hydrotherapy unit penetration sits at early-cycle expansion, with Australia's TGA home-use classification evaluation poised to unlock direct-to-consumer channels that could reshape addressable market boundaries.
For Market Incumbents: Pre-empt emerging ultrasonic-technology entrants by accelerating backward integration into sensor-component supply, while hardening regulatory affairs infrastructure against EU MDR documentation burdens that elongate commercialization timelines for challengers. Dotolo Research Corporation's manufacturing scale and Herrmann Apparatebau's precision-engineering heritage illustrate how captive quality-system capabilities defend positioning against cost-optimized fabricators. For New Entrants and Emerging Players: Establish a beachhead in Canada's underpenetrated provincial markets where Health Canada licensing queues remain less congested than FDA pathways, leveraging equipment-as-a-service procurement models to displace outright purchase arrangements among Ontario's emerging wellness chains. Target supervised home-use segments in Australia ahead of TGA classification expansion, partnering with independent biomedical service organizations to bypass manufacturer-captive distribution. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device parents with undermonetized hydrotherapy divisions lacking dedicated regulatory affairs infrastructure. Long-term viability hinges on portfolio positioning toward electronic documentation-capable platforms as reimbursement documentation requirements tighten across Western markets. Watch Australia's TGA home-use ruling as the signal for direct-to-consumer channel viability and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Stacking | Accelerates cross-border distribution across German, French, and Benelux wellness markets. |
| Ultrasonic Technology Integration | Commands premium positioning in California and Bavaria clinic procurement channels. |
| Equipment-as-a-Service Launch | Compresses customer acquisition costs for mid-sized United States wellness operators. |
| Third-Party Service Partnership | Displaces manufacturer-captive agreements through independent biomedical technician networks. |
| Home-Use Regulatory Pathway | Unlocks direct-to-consumer distribution pending Australia's TGA classification expansion. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hydrotherapy clinic directors, wellness center procurement managers, biomedical equipment service technicians, and regulatory affairs specialists at device manufacturers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, Health Canada device licensing records, and Australia's TGA classification evaluations. Bottom-up installation counts across metropolitan wellness clusters were triangulated against top-down manufacturer shipment data.
Calibration against historical adoption curves in adjacent preventive health modalities informed projection frameworks across the analysis window. Segmentation dimensions modeled include system architecture (closed/open/electronic/manual), technology type (ultrasonic/hydrostatic/gravity/pressure-controlled), end-use environment (clinic/wellness center/home/spa), and capacity configuration. CAGRs were derived from procedure volume elasticities and equipment replacement cycles, with inputs from stainless steel price indices and reimbursement policy trajectories.
Sensitivities concentrate around TGA home-use classification timing, EU MDR audit queue congestion, and state-level scope-of-practice regulatory shifts in the United States. Forecasts reflect documented assumptions regarding wellness operator capital deployment preferences and certification-driven procurement segmentation. Material shifts in Australia's residential-use regulatory framework or FDA enforcement posture on 510(k) documentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Thoracic Drainage Devices Market
Medical Devices
Europe Surgical Visualization Products Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
Global Casting Devices Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
India Minimally Invasive Surgery Devices Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Cosmetic Implants Market