
 Global Endotracheal Tubes Market | 2026-2036
Global Endotracheal Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endotracheal Tubes Market Foresight
Hospital procurement of airway management devices is hardening as health systems prioritize disposable intubation supplies over reusable alternatives. Medtronic leverages its critical care portfolio breadth to anchor North American supply contracts for cuffed and reinforced tubes. Teleflex Incorporated competes through specialized anesthesia and emergency product lines that sustain European hospital loyalty. Smiths Medical differentiates via pediatric and neonatal tube engineering that occupies premium clinical segments.
Endotracheal tubes are polymer-based medical devices inserted through the mouth or nose into the trachea to maintain patent airways, typically manufactured from polyvinyl chloride or silicone in diameters ranging from 2.0 mm to 10.0 mm depending on patient age and anatomy. Their primary purpose is to enable mechanical ventilation, protect against aspiration, and secure controlled breathing during surgery or critical illness. Cuffed tubes dominate adult operative settings where positive pressure ventilation demands airway sealing, while silicone variants represent the fastest-growing material category due to biocompatibility and extended intubation tolerance in intensive care. Pediatric and neonatal tubes command specialized manufacturing precision and corresponding margin pools as regulatory scrutiny intensifies for low-birth-weight applications.
FDA 510(k) pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for tube manufacturers across North America and Europe. ISO 5361 standards for tracheal tubes and ISO 10993 biocompatibility testing establish baseline safety benchmarks that WHO procurement frameworks reference for emerging market tenders. Stakeholders must monitor evolving EPA and ECHA restrictions on plasticizer chemistries in medical polymers, as phthalate substitution mandates could accelerate material cost structures and supplier qualification burdens.
Market Dynamics
Hospital procurement consolidation across Germany, the United States, and Japan is compressing supplier margins and favoring manufacturers with integrated critical care portfolios capable of meeting volume-scale tender requirements.
Growth Catalysts
- Surgical volume expansion:Aging demographics in Germany and Japan are elevating operative procedures requiring postoperative ventilation, driving cuffed tube utilization in tertiary acute care networks.
- EU MDR compliance acceleration:Technical documentation mandates for silicone-based variants are forcing quality upgrades that favor established manufacturers with regulatory infrastructure.
- Biocompatibility premium:Extended ICU intubation protocols are electrifying demand for silicone alternatives that reduce tracheal injury rates during prolonged mechanical ventilation.
Market Restraints
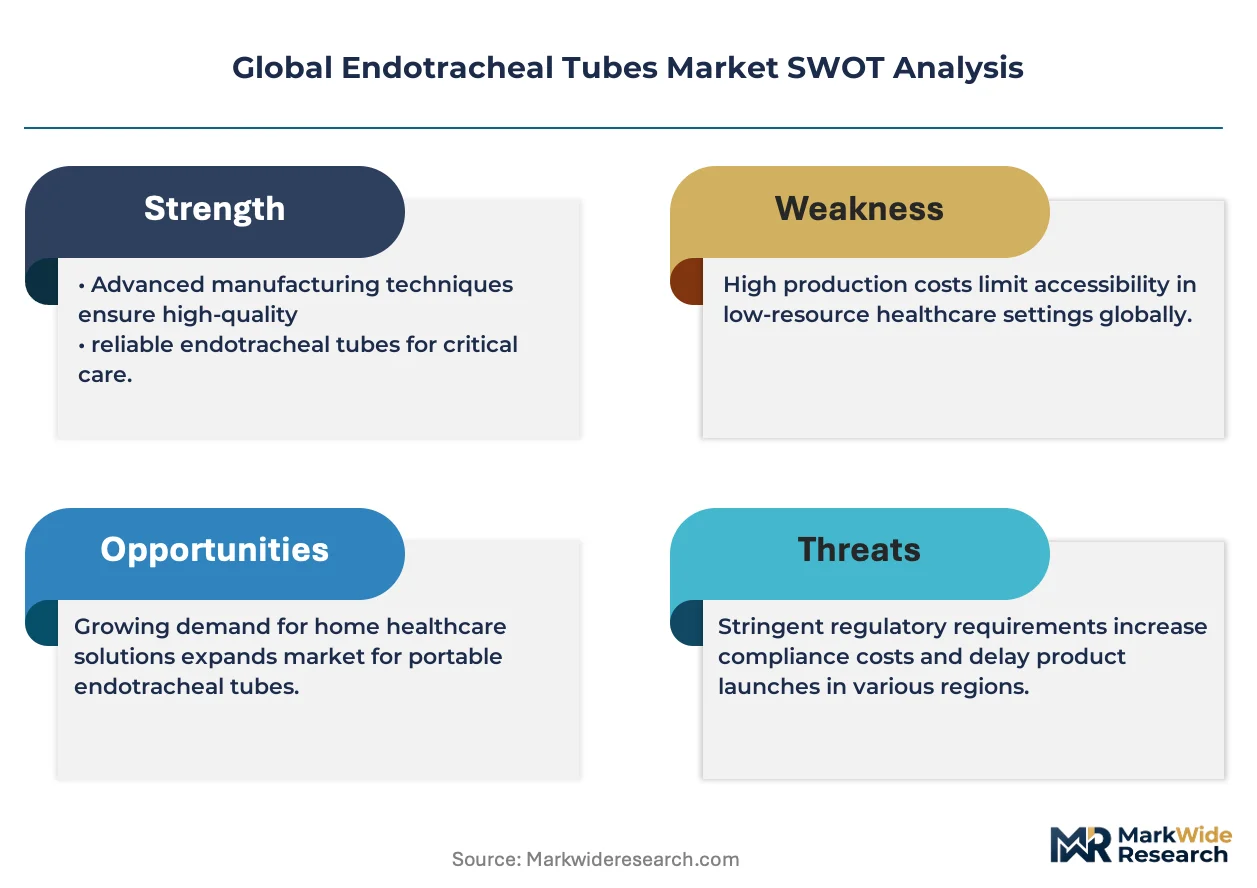
- Polymer input cost volatility:Medical-grade polyvinyl chloride and silicone feedstock prices fluctuate with petrochemical indices, squeezing margin stability for mid-tier manufacturers.
- Supply concentration risk:Critical raw material suppliers cluster in East Asian chemical manufacturing hubs, exposing European and North American tube producers to logistics disruption.
- Phthalate substitution mandates:EPA and ECHA restrictions on plasticizer chemistries are accelerating reformulation costs and supplier requalification timelines for legacy PVC formulations.
Strategic Opportunities
- Neonatal precision engineering:Low-birth-weight applications command specialized manufacturing capabilities and corresponding margin pools as regulatory scrutiny intensifies for pediatric segments.
- WHO procurement framework alignment:ISO 5361 and ISO 10993 certification alignment opens emerging market tenders where national health systems prioritize pre-qualified suppliers.
- Integrated airway management bundles:Convergence of tube, stylet, and suction catheter technologies enables comprehensive contract positioning against fragmented component competitors.
Industry Challenges
- Regulatory talent scarcity:FDA 510(k) pathway expertise and EU MDR technical file preparation require specialized regulatory affairs professionals in short supply across medical device sectors.
- Validation timeline compression:Biocompatibility testing protocols and sterilization validation cycles extend product launch windows, delaying revenue recognition for pipeline innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endotracheal Tubes Market |
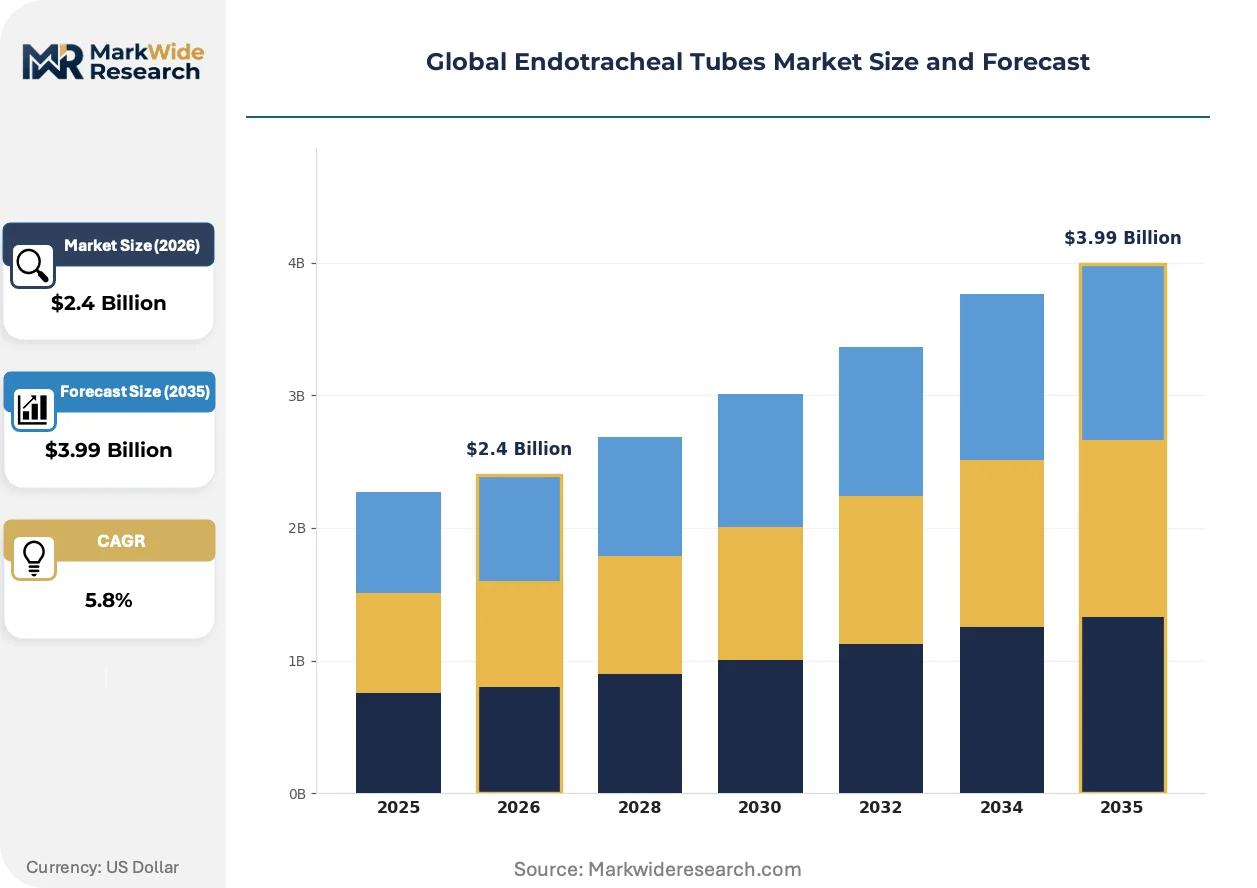
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cuffed Tubes, Uncuffed Tubes, Reinforced Tubes, Pediatric Tubes, Neonatal Tubes Material: Polyvinyl Chloride, Silicone, Rubber, Polyurethane, Latex-Free Application: General Anesthesia, Critical Care Management, Emergency Response, Airway Protection, Respiratory Therapy End User: Operating Theaters, Intensive Care Units, Emergency Medical Services, Diagnostic Centers |
| Companies Covered | Medtronic, Teleflex Incorporated, ICU Medical, Ambu A/S, Smiths Medical, ConvaTec, Intersurgical Ltd, Well Lead Medical Co., Ltd., Fuji Systems Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endotracheal Tubes Market Shifts & Advancements
Material science advances and regulatory harmonization pressures are reshaping competitive positioning in airway management, with differentiation increasingly anchored in clinical outcome documentation rather than commodity manufacturing scale.
Silicone endotracheal tube formulations are electrifying market segmentation through superior biocompatibility profiles that enable extended intubation tolerance. Intensive care units in German university hospitals and Japanese tertiary centers are adopting these variants for ventilation courses exceeding seventy-two hours. This material transition is compressing PVC dominance in premium clinical segments while elevating manufacturing complexity barriers for new entrants.
EU MDR technical documentation requirements are extending conformity assessment timelines and amplifying notified body bottlenecks for tube manufacturers. Device classification elevation for certain cuffed variants is forcing clinical evidence generation that smaller competitors cannot resource. German and French manufacturers with established quality management systems are capturing market access advantages as regulatory friction intensifies.
Hospital procurement consolidation is compressing supplier bases and favoring integrated airway management portfolios over single-product vendors. Acute care networks in the United States are consolidating intubation supply contracts under fewer preferred vendor relationships. This concentration is visible most acutely in multi-hospital systems across Texas and California, where standardization committees prioritize supply chain simplification over product variety.
Global Endotracheal Tubes Market Segmentation
Endotracheal tube specifications dictate clinical performance across ventilation scenarios, with material composition and cuff design determining airway sealing capability and tracheal injury risk. Procurement decisions in German university hospitals and Japanese tertiary centers increasingly weight biocompatibility metrics against unit cost, fragmenting demand across performance tiers.
Product Type:
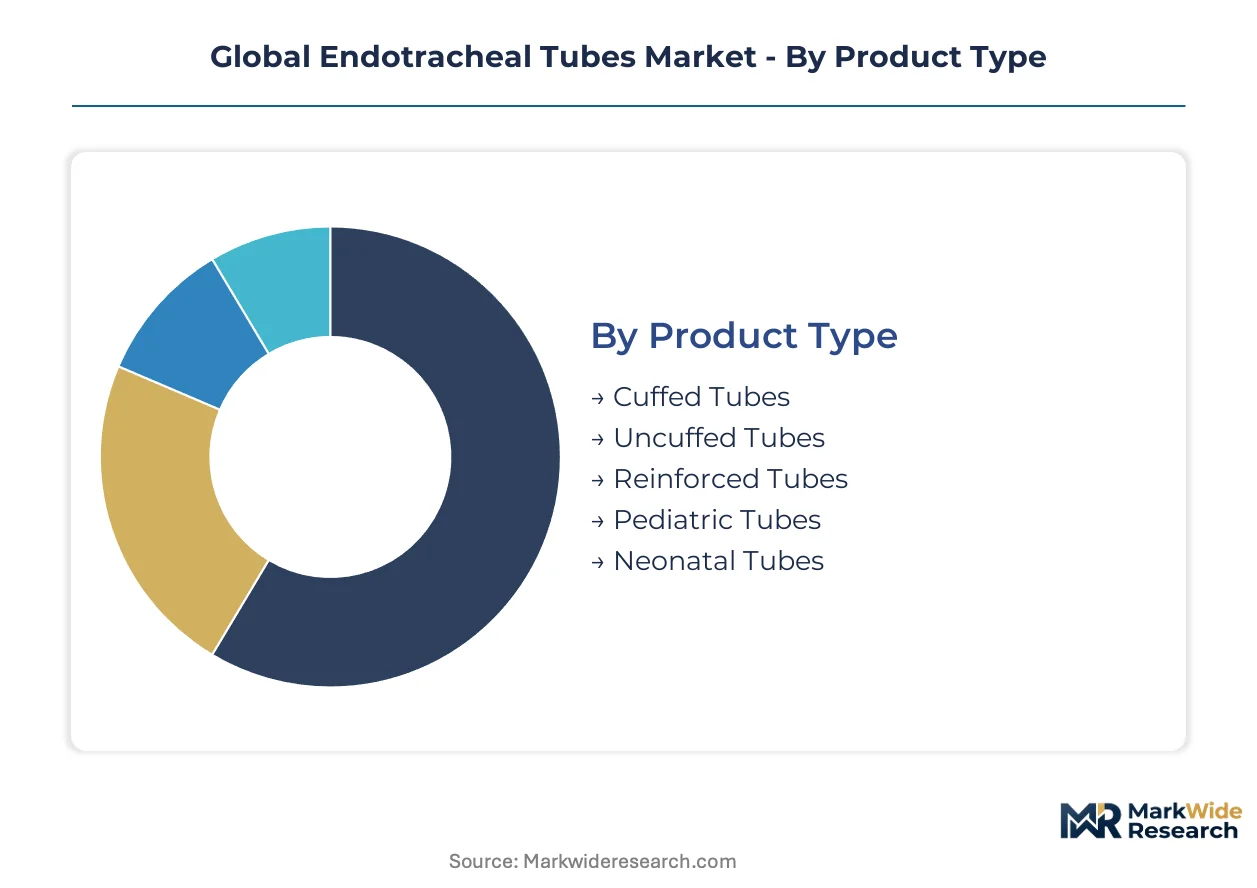
Tube architecture defines functional suitability for patient age, ventilation mode, and intubation duration, with cuff mechanisms and reinforcement layers commanding manufacturing precision premiums.
- Cuffed Tubes:Inflatable cuff mechanisms seal the trachea during positive pressure ventilation, preventing aspiration and enabling controlled breathing circuit management. Demand concentrates in United States operating theaters where laparoscopic and bariatric procedures require sustained airway isolation. FDA 510(k) clearance pathways for cuff pressure monitoring features extend development timelines for safety-enhanced variants.
- Reinforced Tubes:Spiral-wound metal or nylon reinforcement prevents kinking during head and neck positioning changes, sustaining patent lumens in prolonged neurosurgical cases. German anesthesia departments specify these for prone-position spinal operations exceeding four hours. Premium pricing reflects specialized extrusion and coil-embedding manufacturing complexity.
- Uncuffed Tubes:Straight polymer construction without inflatable seals suits short-duration procedures and patients with intact airway reflexes. Diagnostic centers in Japan deploy these for brief bronchoscopic interventions.
- Pediatric Tubes:Diameter-scaled variants from 3.0 mm to 6.0 mm address anatomical constraints in children aged one to twelve years. ISO 5361 dimensional tolerances tighten as tube diameter decreases.
- Neonatal Tubes:Ultra-fine 2.0 mm to 2.5 mm diameters serve low-birth-weight infants requiring mechanical ventilation. PMDA scrutiny of tracheal stenosis incidence rates intensifies post-market surveillance obligations.
Cuffed tubes lead on scale across adult operative settings; reinforced tubes lead on momentum as extended surgical durations proliferate in aging populations.
Material:
Polymer selection governs biocompatibility profiles, sterilization tolerance, and extended intubation safety, with phthalate substitution mandates accelerating formulation transitions.
- Silicone:Platinum-cured elastomer formulations deliver superior tissue tolerance and reduced biofilm adhesion during ventilation courses exceeding seventy-two hours. Japanese ICU protocols specify silicone for anticipated prolonged intubation, displacing PVC in premium clinical segments. ECHA restrictions on plasticizer chemistries amplify silicone adoption in European acute care networks.
- Polyvinyl Chloride:Plasticized PVC dominates disposable tube manufacturing through cost efficiency and established extrusion infrastructure. United States hospital purchasing coalitions negotiate volume contracts favoring PVC for routine operative cases under four hours.
- Polyurethane:Thermoplastic elastomer variants combine thin-wall design with high tensile strength, enabling larger internal diameters at equivalent outer dimensions. Specialized applications in difficult airway management drive niche demand.
- Rubber:Natural and synthetic rubber formulations persist in emerging market procurement where lowest-unit-cost tenders predominate.
- Latex-Free:Synthetic polymer alternatives eliminate Type I hypersensitivity risks in sensitized patient populations. Regulatory labeling requirements in Germany mandate latex-free claims for hospital supply contracts.
Polyvinyl chloride leads on scale through manufacturing cost advantages; silicone leads on momentum as extended ICU protocols expand across Germany and Japan.
Application:
Clinical use case determines performance requirements for airway sealing, aspiration protection, and ventilation control, with emergency scenarios demanding rapid-deployment designs.
- General Anesthesia:Elective operative ventilation requires reliable cuff seals and resistance to biting compression. Operating theaters in the United States standardize on cuffed PVC tubes for routine surgical cases.
- Critical Care Management:Prolonged mechanical ventilation in ICU settings prioritizes tracheal mucosal preservation and biofilm resistance. Silicone variants gain preference in German university hospital networks.
- Emergency Response:Pre-hospital intubation demands stylet-compatible designs and rapid visualization features. Emergency medical services in Japan specify reinforced tubes for trauma airway management.
- Airway Protection:Aspiration risk mitigation in neurologically compromised patients drives cuffed tube utilization with subglottic suction capabilities.
- Respiratory Therapy:Weaning protocols and non-invasive ventilation bridges employ specialized tube designs with speaking valve compatibility.
General anesthesia leads on scale through surgical volume concentration; critical care management leads on momentum as ICU bed expansion proceeds in aging economies.
End User:
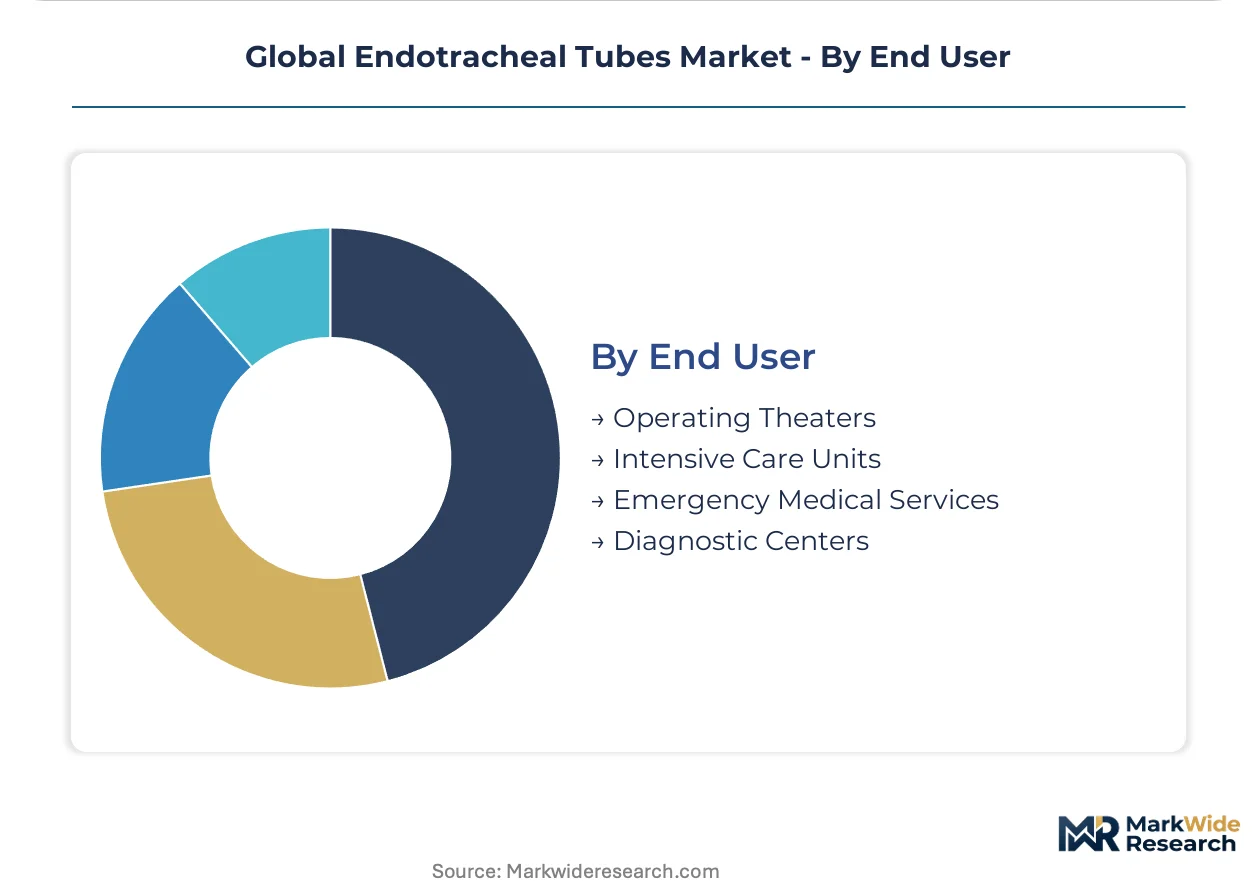
Facility type dictates procurement scale, product mix, and compliance requirements, with integrated health systems consolidating vendor relationships across care settings.
- Intensive Care Units:Extended ventilation protocols and weaning complexity drive demand for biocompatible materials and pressure monitoring integration. Japanese tertiary centers specify silicone variants for anticipated intubation beyond seventy-two hours.
- Operating Theaters:High-throughput surgical environments prioritize supply chain reliability and standardized sizing across anesthesia workstations. United States multi-hospital systems consolidate tube contracts under preferred vendor arrangements.
- Emergency Medical Services:Pre-hospital airway management requires compact packaging and rapid deployment features. German emergency physician-staffed ambulance systems specify reinforced tubes for difficult field intubations.
- Diagnostic Centers:Brief procedural sedation drives demand for uncuffed tubes and cost-optimized disposable supplies. Bronchoscopy suites in Japan utilize single-use airway devices for infection control compliance.
Operating theaters lead on scale through surgical procedure volume; intensive care units lead on momentum as prolonged ventilation incidence rises with population aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as silicone formulation expertise migrates toward jurisdictions with compressed compliance timelines. Germany and Japan absorb premium production capacity while contract manufacturers in China capture PVC tube volume for emerging market tenders.
United States
Hospital purchasing coalitions in Texas and California consolidate intubation supply contracts under preferred vendor arrangements. FDA 510(k) pathways for cuff pressure monitoring features extend development timelines for safety-enhanced variants. Greater Boston anchors critical care device innovation clusters where academic medical centers pilot extended intubation protocols.
Germany
University hospitals in Bavaria specify silicone variants for ventilation courses exceeding seventy-two hours. EU MDR technical documentation mandates force quality upgrades that favor established manufacturers with regulatory infrastructure. The Rhine-Ruhr medical technology corridor concentrates notified body relationships and sterilization validation capacity.
Japan
Tertiary centers in Tokyo and Osaka adopt silicone tubes for anticipated prolonged intubation, displacing PVC in premium clinical segments. PMDA scrutiny of tracheal stenosis incidence rates intensifies post-market surveillance obligations for neonatal applications. The Kansai region hosts precision extrusion specialists serving domestic ICU networks.
China
Domestic manufacturers capture WHO procurement tenders through ISO 5361 certification alignment. The country's national medical device regulator accelerates review timelines for emergency airway management devices. Yangtze River Delta chemical hubs supply medical-grade polymer feedstock to regional tube fabricators.
Global Endotracheal Tubes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated critical care portfolios commanding hospital procurement consolidation in North America and Europe. The vendor base concentrates around three strategic archetypes: diversified medtech conglomerates with anesthesia workstation integration, pure-play airway management specialists with pediatric engineering depth, and Asian contract manufacturers with PVC extrusion scale. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with emergency medical services distributors.
Within the diversified medtech tier, Medtronic and Teleflex Incorporated exemplify portfolio breadth strategies that anchor multi-hospital system contracts. Among European specialists, Ambu A/S occupies a position representing single-use airway device innovation. Chinese fabricators including Well Lead Medical Co., Ltd. exemplify cost-optimized manufacturing archetypes serving emerging market volume tenders.
| Leading Market Players |
|---|
| Medtronic |
| Teleflex Incorporated |
| ICU Medical |
| Ambu A/S |
| Smiths Medical |
| ConvaTec |
| Intersurgical Ltd |
| Well Lead Medical Co., Ltd. |
| Fuji Systems Corp |
| Others |
Supply & Pricing Matrix
Medical-grade silicone feedstock indices cascade through three pricing tiers as polymer cost volatility compresses margins for mid-tier fabricators while amplifying premium capture for integrated manufacturers serving German and Japanese ICU networks.
Pricing Analysis
Distributor margins of 15-25 percent separate hospital GPO contracts from direct OEM supply agreements in North American acute care networks. Three-tier pricing structure across premium silicone, standard PVC, and economy rubber variants reflects ISO 10993 certification grades and extended intubation tolerance claims. Cost compression in standard PVC segments intensifies as Chinese contract manufacturers capture WHO tender volume. Emergency medical services purchasing coalitions exhibit highest price sensitivity; German university hospital procurement committees demonstrate lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital systems mandate qualified suppliers in both East Asian chemical hubs and European compounding facilities. Raw material flows draw from China, Germany, and Japan for silicone monomers, medical-grade PVC resins, and platinum catalyst systems. Single-source vulnerability concentrates in East Asian specialty chemical production where 70 percent of medical-grade silicone feedstock originates. Distribution runs through regional medical device distributors with cold-chain capabilities for sterile finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Endotracheal Tubes Market represents a late-cycle quality story as ICU protocols in aging economies displace commodity PVC with biocompatible silicone specifications for ventilation courses exceeding seventy-two hours.
For Market Incumbents: Deploy backward integration into medical-grade polymer compounding to defend margin position against emerging Chinese contract manufacturers capturing WHO tender volume. Prioritize notified body relationship expansion in Germany to compress EU MDR conformity assessment timelines for silicone-based variants. Consolidate hospital GPO contracts across Texas and California multi-hospital systems before procurement standardization committees finalize preferred vendor lists.
For New Entrants and Emerging Players: Enter via neonatal precision engineering where ISO 5361 dimensional tolerance requirements and PMDA post-market surveillance obligations deter commodity competition. Target Japanese tertiary centers in Osaka and Tokyo with silicone tube offerings for anticipated prolonged intubation protocols. Pursue emergency medical services distributor partnerships in Germany where physician-staffed ambulance systems specify reinforced tube designs for difficult field intubations.
For Investors and Strategic Acquirers: Asymmetric upside sits with European specialists possessing established quality management systems and notified body relationships as regulatory friction intensifies. Five-to-ten year viability favors acquisition targets with silicone formulation expertise and pediatric engineering capabilities rather than PVC commodity fabricators. Monitor PMDA tracheal stenosis surveillance data for neonatal applications as inflection indicator for regulatory scrutiny intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Pathway | Accelerated conformity assessment captures German hospital procurement consolidation before notified body bottlenecks intensify. |
| Silicone Formulation Backward Integration | In-house polymer compounding secures margin stability against petrochemical index volatility in medical-grade feedstock markets. |
| Neonatal Engineering Capability Buildout | Specialized 2.0-2.5 mm diameter manufacturing accesses premium margin pools as PMDA scrutiny elevates compliance barriers. |
| WHO Procurement Framework Alignment | ISO 5361 certification opens emerging market tenders where national health systems prioritize pre-qualified supplier status. |
| Integrated Airway Management Bundling | Converged tube-stylet-suction catheter contracts displace fragmented component vendors in United States GPO negotiations. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region triangulated against secondary validation. Interviews with critical care physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with FDA 510(k) filings, EU MDR technical documentation databases, Japanese PMDA submission records, and WHO procurement tender archives. Bottom-up demand modeling across ICU bed expansion projections and top-down supply validation through medical device trade flows established analytical anchors.
Granularity-level modeling operated at product type, material composition, application setting, and end-user facility tier across the projection horizon. CAGRs derived from surgical volume demographics, ICU intubation incidence rates, and material substitution elasticity in extended ventilation protocols. Industry-specific inputs incorporated phthalate substitution mandate timelines from EPA and ECHA, silicone biocompatibility adoption curves in German university hospitals, and neonatal tube regulatory surveillance intensity from PMDA post-market data.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-time polymer feedstock pricing introduce uncertainty bands around margin compression scenarios. Deviation in EU MDR notified body capacity or PMDA regulatory enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
US Pulse Oximeters Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
Eye Massage Device Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
India Biopsy Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Global Enteral Feeding Tubes Market
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Microcirculation Microscope Market