
 Military Computers Market | 2026-2036
Military Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Military Computers Market Analysis
Market Context
Edge computing architectures is fragmenting traditional centralized military data processing into distributed node-based systems across tactical formations. BAE Systems leverages its UK defense heritage to anchor naval combat management programs with hardened embedded processors. Raytheon Technologies Corporation sustains dominance in airborne radar computing through captive semiconductor sourcing and radiation-hardened design expertise. Elbit Systems competes aggressively in wearable soldier systems, extending its Israeli defense relationships into NATO procurement channels.
Technical Definition and Segment Structure
Military computers are purpose-built electronic systems engineered to operate across temperature extremes from minus 40 to plus 85 degrees Celsius, with shock resistance exceeding 40g and electromagnetic interference shielding compliant with MIL-STD-461 specifications, designed to process tactical data in contested electromagnetic environments where commercial hardware fails. Rugged laptops and embedded systems together occupy the largest revenue pool, though tablets are gaining traction in dismounted soldier programs where weight reduction directly impacts mission endurance. Surveillance applications command premium pricing due to real-time video analytics requirements, while communications-oriented platforms benefit from software-defined radio convergence that merges multiple waveform processing onto single computing chassis.
Regulatory Environment
The US Department of Defense mandates MIL-STD-810H environmental testing and NSA-approved encryption through its Commercial Solutions for Classified program, while European procurement increasingly references NATO STANAG interoperability standards and the EU Permanent Structured Cooperation framework for joint capability development. China's NMPA and military-civil fusion directives compel domestic substitution of foreign processors in critical systems, reshaping supplier qualification pathways. Stakeholders must monitor evolving export control classifications under the Wassenaar Arrangement and emerging quantum-resistant cryptography mandates that will force hardware refresh cycles regardless of platform age.
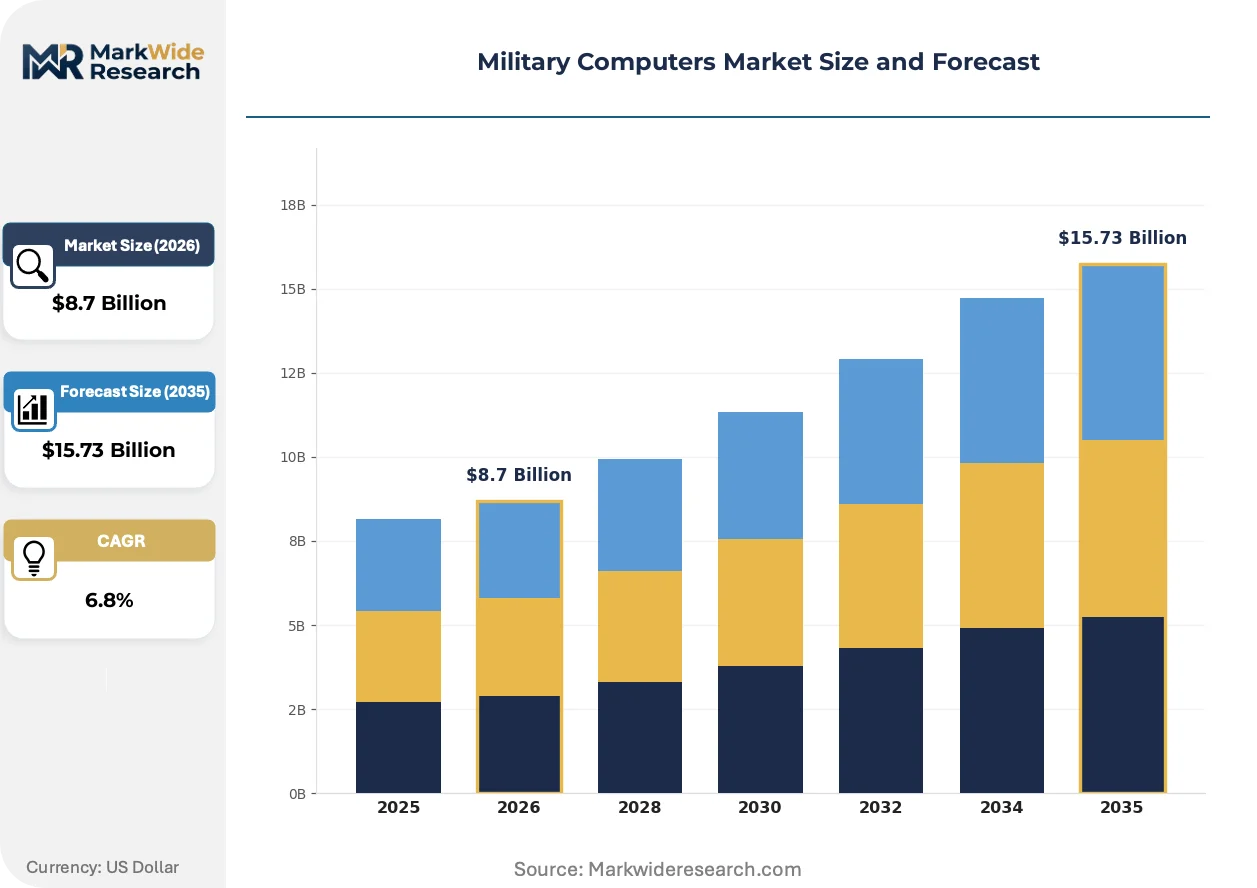
Market Dynamics
Network-centric warfare doctrine is compressing procurement cycles for edge-deployable computing, as defense ministries abandon centralized data architectures in favor of distributed tactical nodes that demand hardened processors with sub-100-millisecond latency thresholds.
Growth Catalysts
- MIL-STD-810H mandates:The US Department of Defense's environmental testing requirements force platform upgrades across legacy vehicle fleets, creating replacement demand for shock-resistant computing chassis in ground combat systems.
- Airborne mission computers:Fighter modernization programs in Germany and Japan prioritize integrated avionics suites that merge sensor fusion with real-time targeting algorithms.
- China's military-civil fusion:Domestic processor substitution policies under NMPA directives accelerate indigenization of critical command-and-control systems, reshaping supplier qualification pathways for foreign component vendors.
Market Restraints
- Rare earth supply concentration:Neodymium and gallium nitride sourcing dependence on Chinese refining capacity creates input cost volatility for radiation-hardened semiconductor fabrication.
- ITAR classification friction:US State Department export controls on encryption modules delay NATO interoperability certification for cross-border joint operations.
- Silicon carbide substrate scarcity:Limited 150mm wafer production for wide-bandgap power electronics constrains thermal management performance in next-generation radar computing.
Strategic Opportunities
- Dismounted soldier wearables:Australian Defence Force trials of helmet-integrated augmented reality displays create demand for sub-500-gram processing units with all-day battery endurance.
- Quantum-resistant cryptography:NSA's Commercial Solutions for Classified program mandates post-quantum algorithm migration, forcing hardware refresh cycles regardless of platform operational age.
- Software-defined radio convergence:Multi-waveform processing on single computing chassis enables platform consolidation across naval, airborne, and ground vehicle segments.
Industry Challenges
- VHDL and FPGA talent scarcity:Radiation-hardened design expertise concentrates among aging engineer cohorts, constraining workforce expansion for custom ASIC development.
- MIL-STD-461 recertification timelines:Electromagnetic interference testing for modified commercial-off-the-shelf components extends procurement cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Computers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rugged Laptops, Embedded Systems, Workstations, Tablets Application: Surveillance, Navigation, Data Analysis, Communications End User: Defense Forces, Government Agencies, Aerospace Contractors, Security Firms Technology: AI Integration, Cloud Computing, Connectivity Solutions, Encryption Methods |
| Companies Covered | Raytheon Technologies Corporation, Elbit Systems, BAE Systems, Panasonic Corporation, Getac Technology Corp., Curtiss-Wright Corporation, Northrop Grumman Corporation, Kontron AG, General Dynamics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Computers Market Emerging Trajectories
Software-defined architectures are dissolving hardware-software boundaries in tactical systems, enabling capability upgrades through firmware rather than physical replacement. This shift compresses obsolescence cycles and redirects R&D investment toward modular open standards.
Containerized mission applications are virtualizing legacy stovepiped functions—radar processing, electronic warfare, and communications—onto common computing infrastructure. Naval combat management system integrators in the UK and France are adopting this approach aggressively. The technology is virtualizing traditional single-purpose hardware stacks, collapsing multiple proprietary chassis into unified processing pools that reduce shipboard footprint and thermal load.
EU AI Act risk classification frameworks are extending to autonomous targeting systems, triggering design-phase compliance documentation for machine learning inference at the tactical edge. Defense contractors must now maintain algorithmic audit trails and human-in-the-loop validation protocols. Airborne platforms with predictive maintenance modules face the steepest compliance burden, with manufacturers restructuring development workflows to embed explainability requirements from initial architecture.
Performance-based logistics contracts are displacing traditional spares-and-maintenance procurement in NATO member states. Danish and Dutch defense ministries now specify availability guarantees rather than component quantities, transferring operational risk to prime contractors. This restructuring concentrates aftermarket revenue with system integrators possessing predictive analytics capabilities, marginalizing component suppliers lacking fleet-wide data access.
Military Computers Market Segmentation
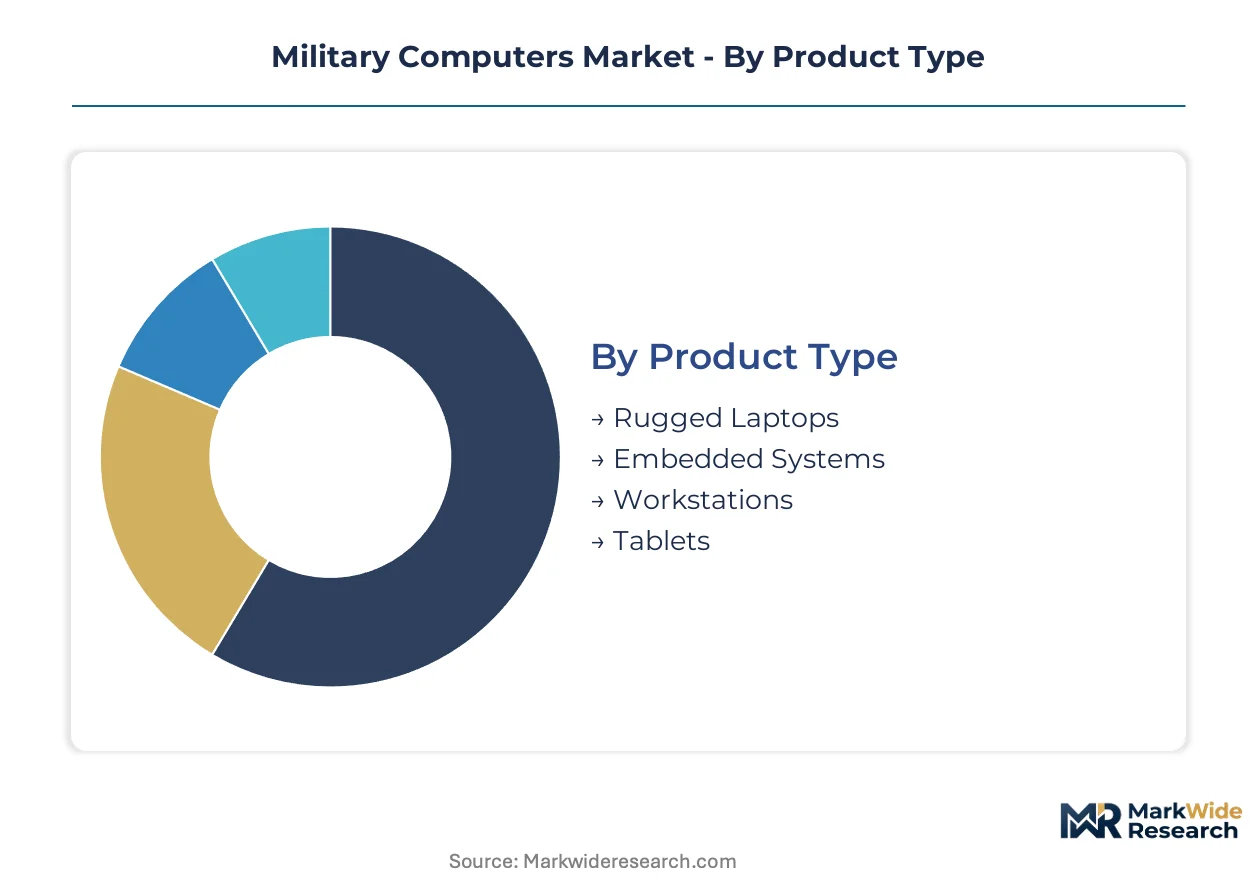
Military computing procurement splits across hardware form factors, operational functions, and integration complexity. Segment boundaries blur as software-defined architectures enable single platforms to serve multiple mission profiles.
Product Type:
Form factor selection hinges on environmental exposure severity and mobility requirements across deployment scenarios.
- Rugged Laptops:Clamshell designs with MIL-STD-810H certification withstand 40g shock loads and temperature swings from minus 40 to plus 85 degrees Celsius. German and Japanese ground vehicle modernization programs drive replacement cycles for chassis-mounted units with sealed port configurations.
- Embedded Systems:Fanless architectures with conduction cooling dominate naval combat management installations where salt spray and continuous vibration degrade conventional hardware. Royal Navy Type 26 frigate programs specify these for distributed processing nodes.
- Workstations:High-throughput units with multiple PCIe slots support radar signal processing and intelligence fusion in fixed command centers.
- Tablets:Sub-500-gram form factors with sunlight-readable displays gain traction in Australian and British dismounted soldier trials.
Rugged laptops command the established base. The steepest expansion runs through embedded systems.
Application:
Functional specialization reflects doctrinal emphasis on network-centric warfare and real-time decision compression.
- Surveillance:Real-time video analytics pipelines with GPU acceleration process multi-spectral sensor feeds for target identification. These platforms carry premium pricing due to inference latency requirements under 100 milliseconds in contested electromagnetic environments.
- Communications:Software-defined radio convergence merges multiple waveform processing onto single computing chassis, collapsing legacy stovepiped hardware stacks. French and Italian naval programs prioritize these for cross-platform interoperability.
- Navigation:INS/GPS fusion processors with anti-jam algorithms support denied-environment positioning for precision strike missions.
- Data Analysis:Edge-deployable inference engines enable predictive maintenance and logistics optimization without cloud connectivity.
Communications applications anchor current procurement volume. Surveillance platforms are climbing the fastest as autonomous targeting systems proliferate.
End User:
Customer type determines specification rigor, certification pathways, and contract structure complexity.
- Defense Forces:National military procurement offices in the United States, China, and Germany specify hardened platforms with NSA-approved encryption or domestic equivalents. These buyers mandate MIL-STD-461 electromagnetic interference shielding and impose 18-24 month recertification timelines for modified commercial components.
- Aerospace Contractors:Prime integrators like BAE Systems and Raytheon Technologies source captive semiconductor supply chains for radiation-hardened airborne mission computers. Their demand concentrates in fighter modernization programs with integrated avionics suites.
- Government Agencies:Intelligence community buyers prioritize compartmentalized processing with cross-domain guard capabilities.
- Security Firms:Private sector contractors operate under lighter environmental specifications, adopting modified rugged commercial hardware for perimeter monitoring and convoy protection.
Defense forces dominate absolute spending. Aerospace contractors are gaining share fastest as performance-based logistics contracts concentrate aftermarket revenue with system integrators.
Technology:
Technical architecture choices determine upgrade pathways and obsolescence risk across multi-decade platform lifecycles.
- AI Integration:Machine learning inference at the tactical edge triggers EU AI Act compliance documentation for autonomous targeting systems. Danish and Dutch predictive maintenance modules face steep audit trail requirements with human-in-the-loop validation protocols.
- Encryption Methods:NSA's Commercial Solutions for Classified program mandates post-quantum algorithm migration, forcing hardware refresh cycles regardless of platform operational age. This creates replacement demand independent of physical wear.
- Cloud Computing:Containerized mission applications virtualize legacy functions onto common infrastructure, reducing shipboard footprint and thermal load in UK and French naval programs.
- Connectivity Solutions:Multi-domain mesh networking processors enable distributed tactical nodes with sub-100-millisecond latency thresholds.
Encryption methods anchor compliance-driven procurement. AI integration is expanding most quickly as explainability requirements restructure development workflows from initial architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in the United States, China, and Germany concentrate procurement authority for hardened computing platforms. National security doctrines and indigenization policies reshape supplier qualification pathways across these buyer archetypes.
United States
The Department of Defense drives demand through fighter modernization and naval combat management programs. NSA's Commercial Solutions for Classified program mandates post-quantum encryption migration, forcing hardware refresh cycles. Defense contractors cluster around Washington D.C., Boston, and Southern California for proximity to Pentagon procurement offices and captive semiconductor foundries.
China
Military-civil fusion directives accelerate domestic processor substitution in command-and-control systems. NMPA regulations compel foreign component vendors to requalify through joint venture structures. Industrial concentration spans Beijing-Tianjin-Hebei for avionics and the Yangtze River Delta for naval systems integration.
Germany
The Bundeswehr prioritizes integrated avionics suites for Eurofighter and naval frigate programs. EU Permanent Structured Cooperation frameworks coordinate joint capability development with France and the Netherlands. Bavaria and Baden-Württemberg host system integrators supplying NATO STANAG-compliant platforms.
Japan
Air Self-Defense Force fighter modernization drives procurement of sensor-fusion computing with real-time targeting algorithms. METI oversees technology transfer restrictions on wide-bandgap semiconductors. Industrial activity concentrates in the Nagoya aerospace cluster and Kanto defense electronics corridor.
Australia
The Australian Defence Force trials helmet-integrated augmented reality displays for dismounted soldier programs. TGA-equivalent defense procurement regulations emphasize interoperability with Five Eyes partners. Activity clusters in Canberra for policy coordination and South Australia for systems integration.
Military Computers Market Vendor Landscape
Channel-controlling players compete with product-specialist players across procurement tiers. The vendor base organizes around three strategic archetypes: captive semiconductor system integrators, rugged hardware fabricators, and software-defined architecture specialists. Consolidation pressure intensifies as performance-based logistics contracts concentrate aftermarket revenue with fleet-wide data holders. Prime contractors pursue backward integration into radiation-hardened chip design while specialist vendors seek NATO interoperability certification to bypass ITAR friction.
Within the captive semiconductor tier, Raytheon Technologies Corporation and Northrop Grumman Corporation exemplify system integrators sustaining dominance through in-house sourcing and radiation-hardened design expertise. BAE Systems occupies a position anchored by UK defense heritage and naval combat management programs. Elbit Systems represents the wearable systems specialist archetype, extending Israeli defense relationships into NATO procurement channels.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Elbit Systems |
| BAE Systems |
| Panasonic Corporation |
| Getac Technology Corp. |
| Curtiss-Wright Corporation |
| Northrop Grumman Corporation |
| Kontron AG |
| General Dynamics Corporation |
| Others |
Supply Flow & Price Mechanics
The Trans-Pacific freight corridor's rate volatility feeds directly into landed cost spreads for radiation-hardened semiconductors, amplifying price differentiation between captive-sourced and merchant-supplied computing chassis while compressing margins for vendors lacking upstream control over gallium nitride substrate procurement.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate long-term supply agreements for radiation-hardened processors. Three-tier pricing structure across radiation-hardened, ruggedized commercial, and modified COTS levels separates platforms by MIL-STD-810H certification depth and NSA encryption approval status. Pricing pressure stems from Chinese refining concentration in neodymium and gallium nitride feedstocks. Defense forces exhibit lowest price sensitivity due to mission-critical specifications, while security firms face acute margin compression on commercial-derivative hardware.
Supply Chain Analysis
Contract manufacturing concentrates with TSMC for advanced node fabrication, GlobalFoundries for radiation-hardened processes, and BAE Systems' captive UK facilities for naval combat management systems. Raw material dependencies center on silicon carbide wafers from Cree/Wolfspeed, rare earth concentrates from Chinese refiners, and specialty substrates from Japanese suppliers. Single-source vulnerability in 150mm silicon carbide production constrains thermal management performance for next-generation radar computing. Distribution runs through prime contractor integration channels rather than direct procurement by defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military computing is approaching a platform-economics inflection as NATO STANAG interoperability standards and the EU AI Act force modular open architectures, collapsing proprietary hardware stacks into fungible processing pools where ecosystem control displaces component-level differentiation.
For Market Incumbents: Build switching-cost moats through performance-based logistics contracts that embed predictive analytics and fleet-wide data access. Deepen backward integration into radiation-hardened ASIC design to offset VHDL talent scarcity. Consolidate aftermarket revenue by acquiring containerized mission application specialists before NATO interoperability certification opens prime contractor channels to modular competitors. For New Entrants and Emerging Players: Pursue Australian and British dismounted soldier wearables as the most penetrable segment, where sub-500-gram processing requirements and helmet-integrated AR trials have yet to harden around incumbent supply relationships. Target software-defined radio convergence for naval platforms through NATO STANAG compliance as a go-to-market angle that bypasses ITAR friction. For Investors and Strategic Acquirers: FPGA design houses with radiation-hardened expertise and aging engineer cohorts represent the priority acquisition archetype for capability capture. Long-term viability hinges on quantum-resistant cryptography refresh cycles and AI Act compliance tooling. Watch NSA post-quantum algorithm migration timelines as the inflection signal forcing hardware replacement regardless of platform operational age.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Foundry Investment | In-house radiation-hardened production insulates Raytheon and Northrop Grumman from rare earth supply volatility. |
| Containerized Mission Application Development | Virtualizing radar and EW functions onto common infrastructure reduces Royal Navy Type 26 frigate footprint. |
| Post-Quantum Cryptography Hardware Refresh | NSA Commercial Solutions for Classified mandates force replacement demand independent of physical wear. |
| Performance-Based Logistics Contracting | Danish and Dutch availability guarantees transfer operational risk to primes with predictive analytics capabilities. |
| NATO STANAG Interoperability Certification | EU Permanent Structured Cooperation frameworks open joint capability development to qualified non-traditional vendors. |
Methodological Framework
The analysis maps rugged laptops, embedded systems, tablets, and workstations, each validated through program managers at defense procurement offices, radiation-hardened design engineers at prime contractors, electromagnetic interference testing lab directors, and semiconductor substrate procurement leads. Primary interview findings triangulate against MIL-STD-810H certification databases, Wassenaar Arrangement export control classifications, NSA Commercial Solutions for Classified approved product listings, and EU Permanent Structured Cooperation joint capability development announcements. Bottom-up unit demand modeling reconciles with top-down defense budget allocation analysis.
Assumptions hold fixed current NATO STANAG interoperability requirements and Wassenaar encryption control classifications while varying Chinese military-civil fusion enforcement intensity and rare earth supply disruption scenarios across the analysis window. Segmentation dimensions include form factor, application function, end-user procurement tier, and technology architecture choice. CAGRs derive from defense ministry budget trajectory analysis and platform replacement cycle modeling, with specific inputs from fighter modernization program timelines and naval combat management system refresh schedules.
Sensitivities concentrate around Chinese NMPA domestic substitution enforcement, NSA quantum-resistant cryptography mandate acceleration, and silicon carbide substrate supply expansion. Forecasts reflect these assumptions and acknowledge revision risk from regulatory classification shifts or rare earth logistics disruption. Quarterly review of defense procurement office RFP releases, foundry capacity expansion announcements, and STANAG standard update notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense Cybersecurity
Military Cybersecurity Market
Defense Cybersecurity
Global Counter IED Market
Defense Cybersecurity
Asia-Pacific Cyber Weapons Market
Defense Cybersecurity
Aviation Cyber Security Market
Defense Cybersecurity
Global Handheld Counter IED Market
Defense Cybersecurity
Automotive Cybersecurity Service Market
Defense Cybersecurity
Military Sensors Cybersecurity Solutions Market
Defense Cybersecurity
Vehicle Cybersecurity Market
Defense Cybersecurity
Global C4I Systems Market
Defense Cybersecurity
Europe Automotive Cybersecurity Market
Defense Cybersecurity
High Energy Lasers Market
Defense Cybersecurity
Europe Cyber Weapons Market
Defense Cybersecurity
Mine and IED Detection System Market
Defense Cybersecurity
Global Defense Tactical Radio Market
Defense Cybersecurity
Anti-Drone Defense System Market
Defense Cybersecurity
Cyber Weapons Market