
 Waste-Derived Pyrolysis Oil Market | 2026-2036
Waste-Derived Pyrolysis Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Waste-Derived Pyrolysis Oil Market Analytics
Cement manufacturing is expanding its offtake of waste-derived pyrolysis oil as kiln operators seek alternative fuels to displace petroleum coke and coal. Plastic Energy leverages continuous pyrolysis technology leadership to anchor long-term supply contracts with European cement producers. Ensyn Corporation sustains geographic dominance in North American biocrude markets through dedicated R&D on woody biomass feedstocks. Quantafuel ASA specializes in chemical recycling integration, positioning its operations to compete for polymer-grade output streams from mixed plastic waste.
Waste-derived pyrolysis oil is a thermally decomposed liquid hydrocarbon produced from organic refuse at temperatures between 350°C and 700°C in oxygen-starved conditions, yielding a viscous, energy-dense fluid with heating values comparable to heavy fuel oil. Its primary commercial purpose is to substitute fossil-derived fuels in industrial combustion and to serve as a secondary feedstock for chemical synthesis. Plastic waste dominates current feedstock supply chains due to established collection infrastructure and higher oil yields per tonne processed. Continuous pyrolysis technology leads on throughput efficiency and operational uptime, while catalytic variants command margin premiums for producing lighter, more refinery-compatible fractions. Fuel production applications absorb the largest volume share, though chemical feedstock pathways are gaining traction as petrochemical buyers seek mass-balance-certified circular inputs.
The EPA's renewable fuel standard pathways and the EU's REACH registration requirements for recovered substances are shaping product quality specifications and market access conditions for waste-derived pyrolysis oil producers. Germany's KBA and France's environmental agency enforce end-of-waste criteria that determine whether pyrolysis oil qualifies as product or remains regulated as waste, directly affecting cross-border trade eligibility. India's BIS is developing standards for pyrolysis-derived fuels from tire waste, opening a compliance pathway for exports to South Asian industrial buyers. Stakeholders must monitor how evolving mass-balance certification rules from ISO and national regulators will determine premium access to chemical industry offtake contracts.
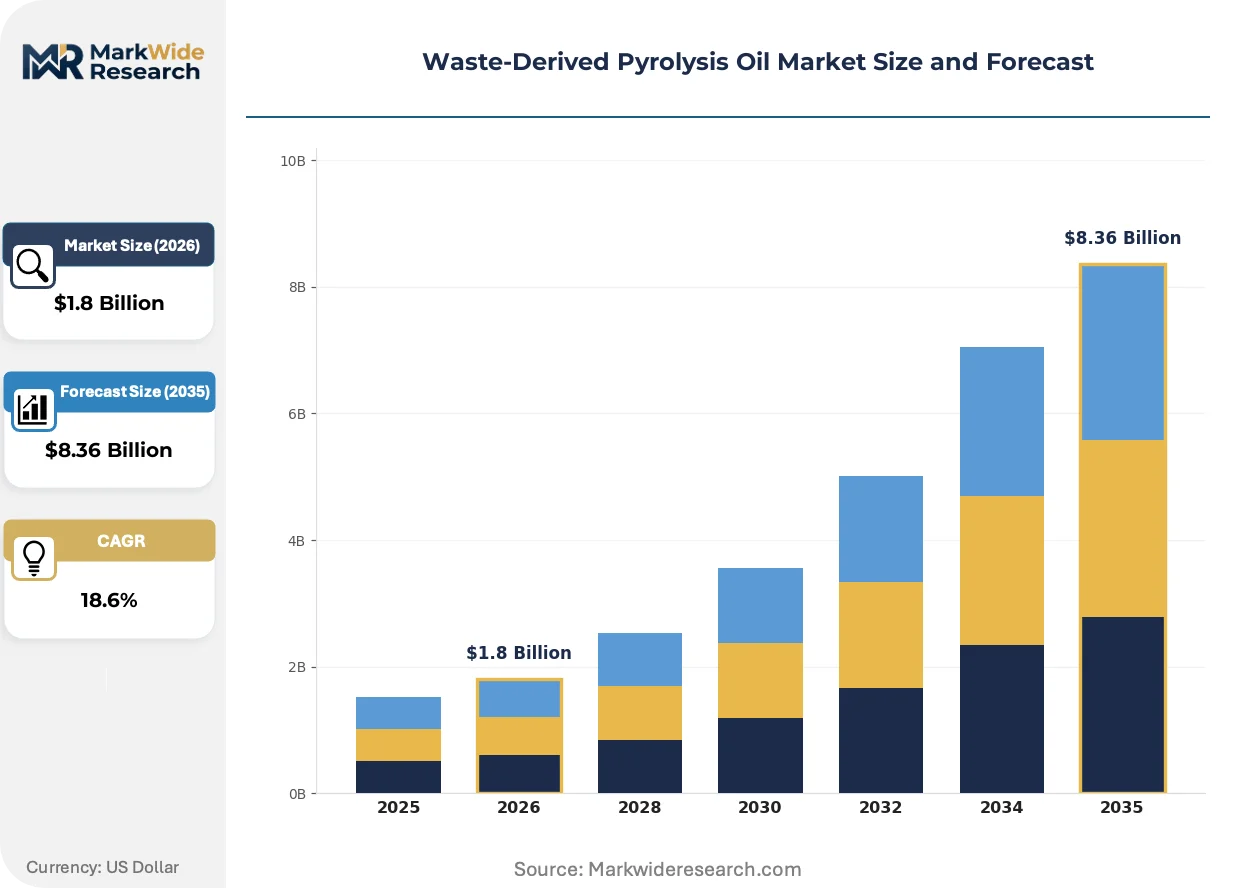
Market Dynamics
Cement kiln operators and marine shipping lines are driving structural demand for waste-derived pyrolysis oil as a drop-in fuel substitute, while EU Green Deal waste-to-energy mandates and California's LCFS program tighten feedstock traceability requirements across supply chains.
Growth Catalysts
- EU Green Deal Mandates:Waste-to-energy targets under the European Commission's framework are compelling cement producers to displace petroleum coke with certified pyrolysis oil feedstocks.
- Marine Fuel Substitution:International Maritime Organization decarbonization rules are accelerating bunker fuel trials using pyrolysis-derived heavy fuel oil equivalents in European and Asian ports.
- Chemical Park Infrastructure:Industrial clustering near Germany's integrated chemical parks enables direct pipeline offtake, reducing logistics costs for pyrolysis oil producers.
Market Restraints
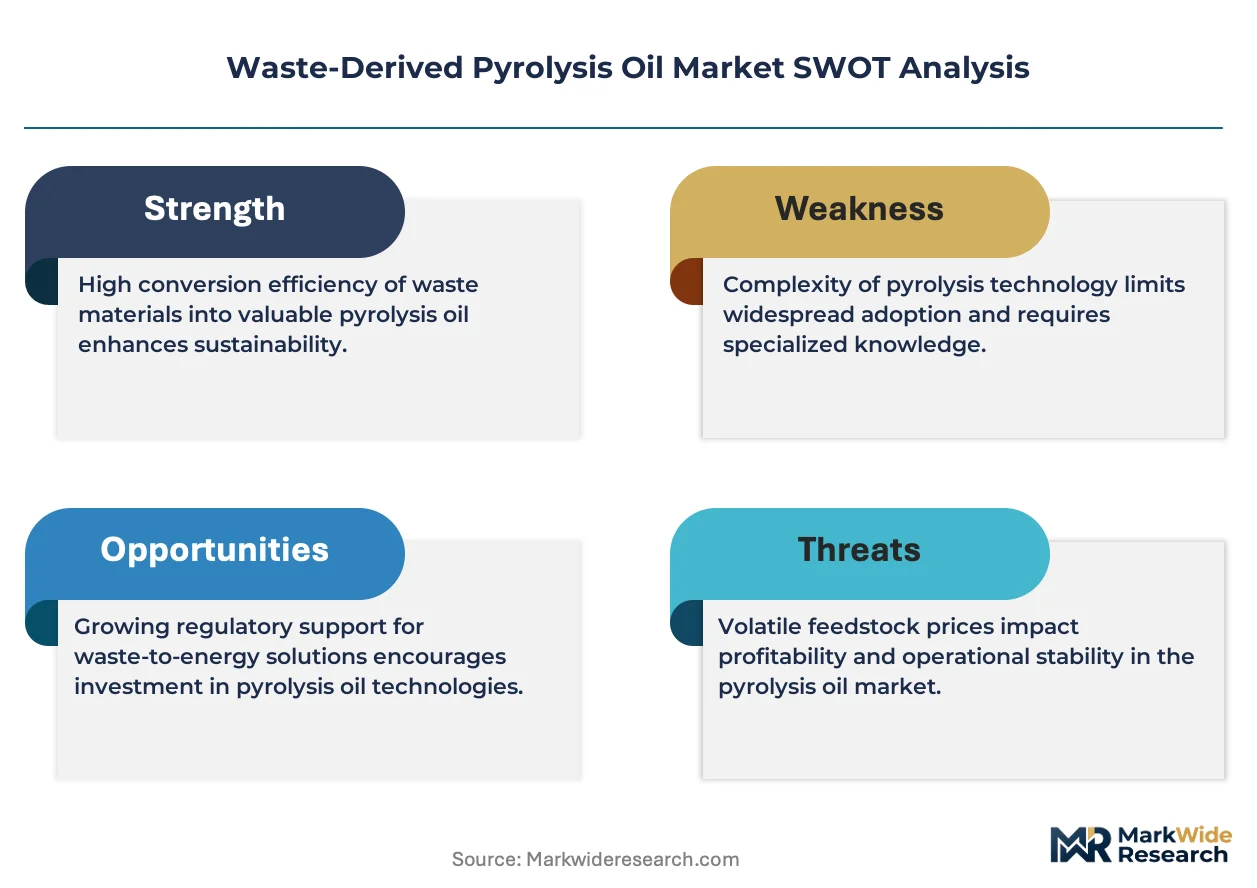
- Feedstock Quality Volatility:Mixed plastic waste streams exhibit variable contamination levels that degrade pyrolysis oil yields and require pre-treatment capex.
- End-of-Waste Regulatory Friction:Germany's KBA and France's environmental agency apply divergent criteria for product qualification, fragmenting cross-border trade eligibility.
- Natural Gas Price Arbitrage:Periodically low European natural gas prices compress the economic case for pyrolysis oil in industrial heat applications.
Strategic Opportunities
- Tire Waste-to-Fuel Pathways:India's BIS standards development for pyrolysis-derived fuels from tire waste opens compliance routes for South Asian industrial offtake.
- Catalytic Upgrading Convergence:Integration of continuous pyrolysis with hydroprocessing catalysts is enabling polymer-grade output streams from previously fuel-limited feedstocks.
- Mass-Balance Certification Premiums:Early alignment with evolving ISO mass-balance rules positions producers for chemical industry contracts commanding price premiums over fuel markets.
Industry Challenges
- Pyrolysis Engineer Talent Scarcity:The specialized skill set spanning thermal chemistry, reactor design, and feedstock characterization remains concentrated among a limited pool of practitioners.
- REACH Registration Timelines:EU chemical registration requirements for recovered substances impose multi-year compliance windows that delay market entry for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste-Derived Pyrolysis Oil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Plastic Waste, Biomass, Tires, Agricultural Residues Technology: Batch Pyrolysis, Continuous Pyrolysis, Catalytic Pyrolysis, Microwave Pyrolysis Application: Fuel Production, Chemical Feedstocks, Carbon Black, Asphalts End User: Energy Sector, Manufacturing, Transportation, Chemical Industry |
| Companies Covered | Agilyx Corporation, Plastic Energy, Ensyn Corporation, Enerkem Inc., Fortum Oyj, Nexus Circular, Brightmark LLC, Quantafuel ASA, Twence, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste-Derived Pyrolysis Oil Market Evolving Landscape
Technology convergence and regulatory precision are compressing the gap between waste-derived pyrolysis oil and refinery-grade feedstock specifications, reshaping competitive positioning across fuel and chemical pathways.
Continuous catalytic pyrolysis systems are unifying thermal decomposition with in-situ cracking to produce lighter, more aromatic fractions without secondary upgrading. European petrochemical buyers are piloting these streams for mass-balance-certified circular polymer production. This unification is collapsing the traditional separation between fuel-only and chemical-grade pyrolysis oil markets.
California's LCFS program and the EU's Renewable Energy Directive are tightening lifecycle carbon intensity thresholds for alternative fuels. Industrial combustion buyers must now document feedstock provenance and processing emissions to claim credits. Cement manufacturers in Germany and marine operators in Rotterdam are responding by mandating third-party certification for all pyrolysis oil supply contracts.
Long-term offtake contracting is displacing spot market purchasing among cement and shipping buyers seeking supply security. Aggregators and integrated chemical park operators are capturing margin by bundling feedstock sourcing, upgrading, and certification services. This shift is most visible in Germany's Rhine-Ruhr industrial corridor, where dedicated pipeline infrastructure enables decade-long supply agreements.
Waste-Derived Pyrolysis Oil Market Segmentation
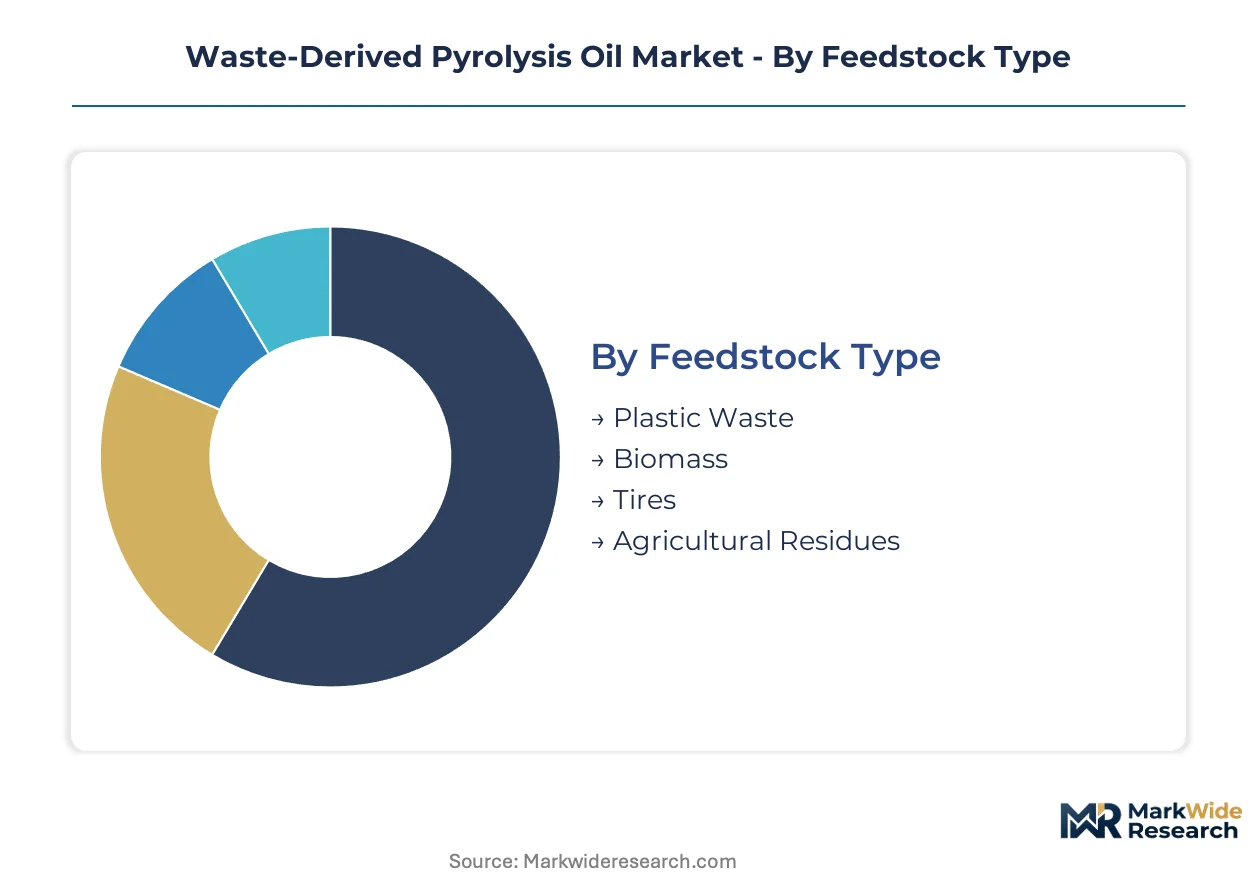
Waste-derived pyrolysis oil segments diverge sharply by feedstock chemistry, reactor economics, and offtake specifications. Producers must align technology selection with end-use certification requirements to capture premium pricing tiers.
Feedstock Type:
Volume production concentrates on plastic waste streams, while premium margins attach to specialized tire and biomass pathways.
- Plastic Waste:Polyethylene and polypropylene-rich municipal streams deliver oil yields exceeding 80% by mass with consistent calorific value. Cement manufacturers in Germany's Rhine-Ruhr corridor anchor procurement through decade-long supply agreements tied to EU Green Deal compliance.
- Biomass:Woody residues and agricultural lignocellulose produce oxygenated biocrude requiring hydrotreating before refinery integration. North American industrial heat buyers sustain demand despite natural gas price volatility compressing regional arbitrage.
- Tires:Steel-belted passenger and truck tire crumb yields sulfur-heavy pyrolysis oil alongside recovered carbon black. India's BIS standards development is unlocking South Asian industrial boiler markets previously closed to waste-derived fuels.
- Agricultural Residues:Rice husks, straw, and bagasse present seasonal collection challenges that fragment supply security for continuous reactor operations.
Mature deployment sits with plastic waste. Newer deployment is concentrated in tire-derived pathways.
Technology:
Throughput efficiency separates continuous systems from batch alternatives, while catalytic variants command upgrading premiums for chemical-grade output.
- Batch Pyrolysis:Intermittent reactor loading suits distributed, small-scale operations with variable feedstock availability. Rural processing facilities in India and Southeast Asia rely on this configuration for agricultural residue conversion.
- Continuous Pyrolysis:Automated feed systems achieve operational uptimes exceeding 90% with thermal efficiencies above 75%. European cement producers mandate continuous technology certification for long-term offtake contracts.
- Catalytic Pyrolysis:In-situ zeolite cracking produces lighter aromatic fractions directly compatible with petrochemical steam crackers. Mass-balance certification premiums for circular polymer production concentrate demand in Germany's integrated chemical parks.
- Microwave Pyrolysis:Dielectric heating enables rapid temperature ramping with reduced energy intensity, though capital costs limit commercial scale-up.
Commercial maturity clusters with continuous systems. Steepest expansion trajectory is attached to catalytic upgrading integration.
Application:
Fuel markets absorb volume, while chemical feedstock pathways capture margin premiums contingent on mass-balance certification.
- Fuel Production:Heavy fuel oil substitutes serve cement kilns and marine bunkers with minimal processing beyond filtration and stabilization. Rotterdam port authorities are piloting IMO-compliant bunker blends from tire-derived pyrolysis oil.
- Chemical Feedstocks:Hydrotreated pyrolysis oil yields naphtha-range fractions for circular polymer production. Petrochemical buyers in Germany and the Netherlands require third-party mass-balance verification for premium contract pricing.
- Carbon Black:Recovered solid product from tire pyrolysis displaces virgin furnace black in rubber compounding and pigment applications.
- Asphalts:Pyrolysis oil modifiers enhance binder performance in road construction, though specification standardization remains fragmented across national markets.
Established offtake dominates fuel applications. Emerging deployment is concentrating in chemical feedstock certification pathways.
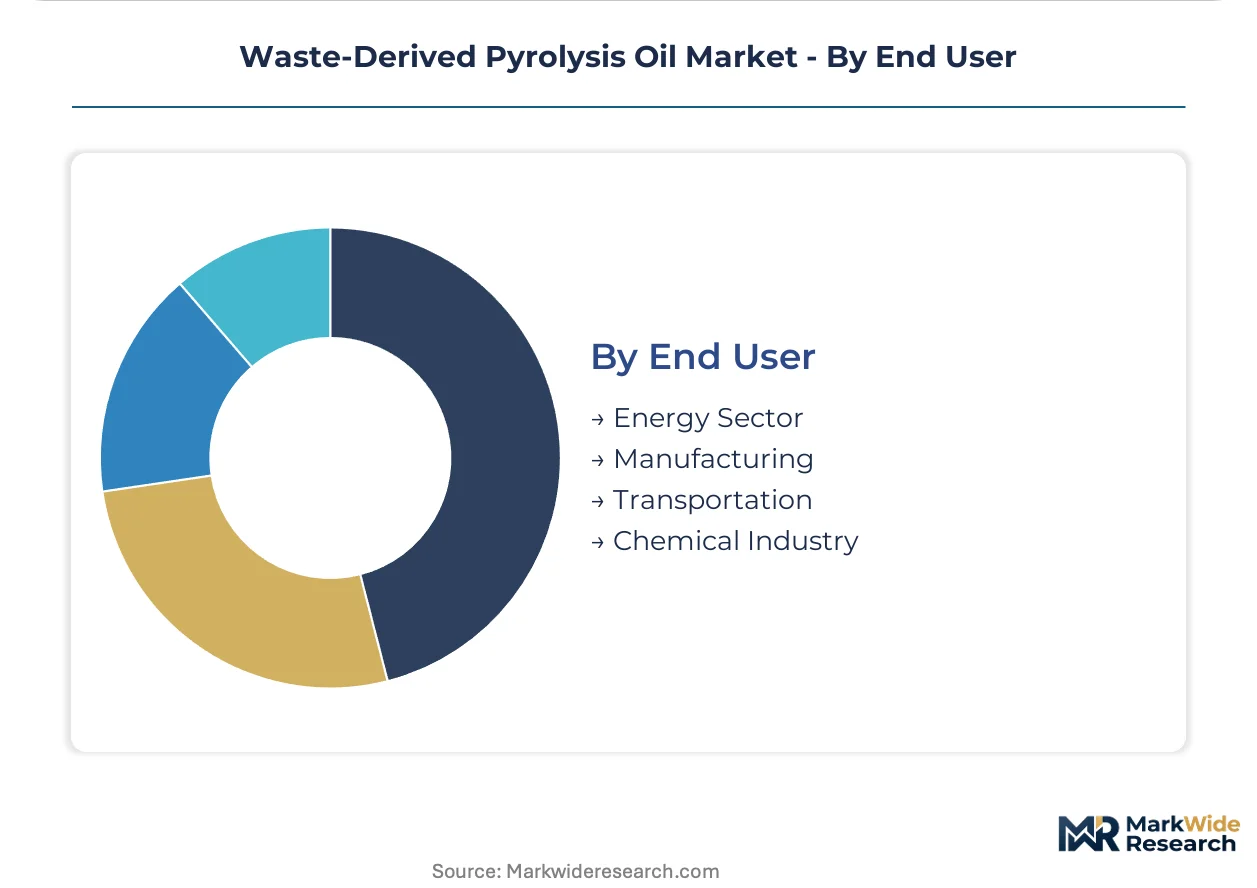
End User:
Industrial combustion buyers drive baseline demand, while chemical sector procurement is conditioning on traceability infrastructure.
- Energy Sector:Power generators and district heating operators utilize pyrolysis oil for seasonal peak load coverage. German municipal utilities are trialing tire-derived fuels in combined heat plants.
- Manufacturing:Cement and steel producers displace petroleum coke and natural gas in high-temperature process heat. Heidelberg Materials and similar operators are embedding pyrolysis oil into EU ETS compliance strategies.
- Transportation:Marine shipping lines in European and Asian ports are conducting IMO 2030-aligned bunker trials with pyrolysis-derived heavy fuel equivalents.
- Chemical Industry:Polymer producers seek mass-balance-certified circular feedstocks for brand-owner sustainability commitments. BASF and INEOS have established qualification programs for pyrolysis-derived naphtha.
Procurement scale concentrates with manufacturing. Contract sophistication is advancing fastest in chemical industry offtake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States while consumption demand clusters near Rotterdam's marine bunkering hub and India's industrial boiler corridors. This geographic mismatch creates arbitrage opportunities for integrated traders with certification capabilities.
Germany
Cement manufacturers in the Rhine-Ruhr corridor anchor European demand through decade-long supply agreements tied to EU Green Deal compliance. The KBA enforces end-of-waste criteria that determine cross-border trade eligibility for pyrolysis oil shipments. Industrial clustering near Ludwigshafen and Leverkusen enables direct pipeline offtake into BASF's chemical park infrastructure.
United States
California's LCFS program drives bunker fuel trials at Long Beach and Oakland ports as marine operators seek IMO-aligned decarbonization pathways. The EPA's renewable fuel standard pathways shape product quality specifications for domestic producers. Ensyn Corporation sustains geographic dominance through dedicated R&D operations anchored in woody biomass feedstock corridors.
India
Industrial boiler operators in Gujarat and Maharashtra represent emerging demand as tire-derived pyrolysis oil penetrates cement and steel manufacturing heat applications. The BIS is developing standards for pyrolysis-derived fuels from tire waste, opening compliance routes for South Asian industrial buyers. Mumbai-Pune industrial belt aggregators are bundling feedstock sourcing with upgrading services to capture margin.
Netherlands
Rotterdam port authorities pilot IMO-compliant bunker blends from tire-derived pyrolysis oil as marine shipping lines accelerate decarbonization commitments. The EU's Renewable Energy Directive tightens lifecycle carbon intensity thresholds for alternative fuel certification. Integrated chemical park operators near the port capture value by consolidating feedstock traceability documentation for export shipments.
France
Cement producers in the Hauts-de-France region displace petroleum coke with certified pyrolysis oil feedstocks under national waste-to-energy transition mandates. The country's environmental agency applies divergent end-of-waste criteria compared to German regulators, fragmenting cross-border trade eligibility for producers. Dunkirk industrial cluster operators are investing in pre-treatment capacity to manage feedstock quality volatility from mixed plastic waste streams.
Waste-Derived Pyrolysis Oil Market Competitive Landscape
Top-tier vendors anchor integrated chemical park infrastructure, while mid-tier specialists concentrate on single-feedstock verticals and regional offtake relationships. The vendor base organizes around three archetypes: continuous pyrolysis technology licensors, catalytic upgrading integrators, and feedstock aggregators with certification capabilities. Strategic moves concentrate on long-term offtake contracting and mass-balance certification alignment to capture chemical industry premium pricing.
Within the technology-licensor tier, Plastic Energy and Ensyn Corporation exemplify divergent geographic and feedstock specializations. Quantafuel ASA occupies a position bridging chemical recycling integration with polymer-grade output stream development. These three entities represent the competitive spectrum spanning continuous pyrolysis deployment, woody biomass biocrude production, and mixed plastic waste chemical recycling pathways.
| Leading Market Players |
|---|
| Agilyx Corporation |
| Plastic Energy |
| Ensyn Corporation |
| Enerkem Inc. |
| Fortum Oyj |
| Nexus Circular |
| Brightmark LLC |
| Quantafuel ASA |
| Twence |
| Others |
Value Network & Pricing Analysis
Feedstock contamination variability from mixed plastic waste streams propagates through pyrolysis reactor economics into three distinct pricing tiers: mass-balance-certified chemical-grade output commands premiums from BASF and INEOS, continuous-process fuel grades serve Heidelberg Materials under long-term offtake, and batch-process economy grades compete in spot markets near Rotterdam and Mumbai.
Pricing Analysis
Cost-down pressure on economy-tier pyrolysis oil accelerates because India's BIS standards development is attracting new tire-waste processors into price-competitive industrial boiler supply. Pricing stratifies across premium chemical-grade with ISO mass-balance certification, standard continuous-process fuel grades, and economy batch-process outputs. Certification investment requirements widen spreads between tiers. Cement manufacturers in Germany's Rhine-Ruhr corridor show least price sensitivity due to EU ETS compliance value, while Indian steel producers exhibit highest sensitivity to delivered fuel costs.
Supply Chain Analysis
Pyrolysis engineer scarcity in Germany and the Netherlands constrains reactor commissioning timelines and inflates specialized labor premiums across European project deployments. Supply concentrates in Germany, the United States, and India, with feedstock sourcing drawing from municipal plastic collection systems, tire crumb processors, and woody biomass corridors. Single-source vulnerability sits with catalyst suppliers for zeolite cracking systems. Distribution runs through integrated chemical park pipelines in Ludwigshafen and Leverkusen, with maritime bulk shipments serving Rotterdam bunkering hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around producers with captive certification capabilities and long-term offtake infrastructure, as REACH registration timelines and end-of-waste regulatory fragmentation force sub-scale operators into distressed exit.
For Market Incumbents: Deploy backward integration into feedstock aggregation to secure contamination-controlled supply streams. Cement kiln operators in Germany are consolidating procurement around decade-long supply agreements, squeezing spot-market intermediaries. Invest in continuous catalytic pyrolysis capacity near chemical park infrastructure to capture polymer-grade margin premiums from petrochemical buyers. For New Entrants and Emerging Players: California's LCFS program opens a window for tire-derived pyrolysis oil suppliers to anchor marine bunker fuel trials at Long Beach and Oakland ports. Target India's industrial boiler corridors in Gujarat and Maharashtra where BIS standards development is creating first-mover compliance advantages. Partner with Mumbai-Pune aggregators bundling feedstock sourcing with upgrading services to bypass capital-intensive reactor ownership. For Investors and Strategic Acquirers: Long-term offtake contract announcements from Heidelberg Materials or similar cement operators is the leading indicator that certification-capable production assets are achieving bankable revenue visibility. Focus acquisition screening on continuous pyrolysis technology licensors with existing EU REACH registrations and mass-balance certification alignment. Watch for KBA end-of-waste criteria harmonization with French regulators as the signal for cross-border trade friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Aggregation | Captive supply of contamination-controlled plastic waste secures reactor yield consistency for chemical-grade output. |
| Continuous Catalytic Pyrolysis Capacity Expansion | In-situ zeolite cracking enables direct naphtha-range fractions for BASF circular polymer production. |
| Mass-Balance Certification Program Alignment | ISO-compliant traceability documentation unlocks premium chemical industry contracts above fuel market pricing. |
| Long-Term Offtake Agreement Structuring | Decade-long supply contracts with Heidelberg Materials reduce revenue volatility and secure project finance. |
| Joint Venture with Chemical Park Operators | Pipeline offtake into Ludwigshafen infrastructure eliminates logistics costs and enables real-time quality feedback. |
Research Methodology
Trade databases, EU customs records, and EPA renewable fuel standard filings formed the secondary backbone for feedstock flow and production capacity mapping. Primary interviews with pyrolysis plant managers, procurement leads at cement manufacturers, chemical park infrastructure operators, and tire crumb processors validated secondary estimates and informed technology deployment timelines. Bottom-up capacity aggregation across named facilities triangulated against top-down demand estimates from cement kiln fuel substitution rates and marine bunker trial volumes.
Historical trendline analysis tracked reactor deployment announcements, offtake contract disclosures, and regulatory standard development milestones across the projection horizon. Segmentation modeling incorporated feedstock chemistry, reactor technology configuration, application pathway, and end-user industry dimensions. CAGRs were derived from fitted trend extrapolation adjusted for policy implementation schedules and infrastructure buildout constraints. Forecast inputs included EU Green Deal waste-to-energy mandate compliance deadlines and IMO marine fuel carbon intensity threshold phase-ins.
Caveats apply where feedstock quality volatility, natural gas price arbitrage, or end-of-waste regulatory divergence could materially shift the outlook. Forecasts reflect assumptions regarding certification standard adoption rates and chemical industry mass-balance verification uptake. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
North America LNG Bunkering Market
Fuels
Wood Pellet Market
Fuels
Global Butane Gas Cartridges Market
Fuels
China Coal Market
Fuels
Smart Gas Solutions Market
Fuels
India Petrol Station Market
Fuels
Global Fuel Ethanol Market
Fuels
Saudi Arabia Fuel Station Market
Fuels
Europe Gas Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Coal Briquette Box Market
Fuels
Gas Pooling Mechanism Market
Fuels
Biobutanol Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Gasoline Market
Fuels
Mobile Gas Pumping System Market