
 Fuel Analyzer Market | 2026-2036
Fuel Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Analyzer Market Foresight
Refinery equipment manufacturers in Germany is rebalancing capacity toward emission-compliant analyzer systems. Siemens AG leverages its automation portfolio to anchor large-scale refinery installations across Europe. ABB Ltd. competes through integrated digital platforms that combine fuel analysis with distributed control systems. HORIBA Ltd. specializes in precision optical engines for sulfur and particulate measurement, sustaining its position in marine fuel certification.
A fuel analyzer is an instrument that quantifies chemical and physical properties of hydrocarbon fuels, including cetane index, sulfur content, viscosity, and distillation characteristics, using optical, electrochemical, or thermal detection principles to ensure compliance with combustion performance and environmental standards. Portable analyzers dominate field inspection workflows for shipboard and pipeline applications where laboratory access is impractical, while online analyzers command premium positioning by enabling continuous process feedback in refinery fuel blending operations. Infrared spectroscopy leads technology adoption due to its non-destructive speed and multi-parameter detection capability, whereas electrochemical sensors gain share in handheld units for sulfur-specific screening at lower price points.
The EPA enforces Tier 3 sulfur standards that compel U.S. refiners to deploy continuous monitoring infrastructure, while the EU Green Deal and F-Gas Regulation push European operators toward analyzers with reduced calibration gas consumption. China's MEE implements national VI fuel standards that mandate stricter benzene and olefin controls, accelerating analyzer replacement cycles at Sinopec and PetroChina facilities. Stakeholders must weigh the trade-off between capital-intensive online systems and scalable portable deployments as regulatory stringency diverges across jurisdictions.
Market Dynamics
The fuel analyzer market is experiencing structural pressure from real-time blending automation, as refineries abandon periodic lab sampling in favor of continuous in-line measurement systems that integrate directly with distributed control architectures.
Growth Catalysts
- IMO 2020 Sulfur Caps:Marine fuel suppliers across Singapore, Rotterdam, and Houston now require portable sulfur verification at bunkering points, expanding field-deployable analyzer demand.
- China's National VI Standards:The MEE mandate for benzene and olefin limits at Sinopec and PetroChina facilities is forcing wholesale replacement of legacy offline testing infrastructure.
- Infrared Spectroscopy Maturation:Non-destructive multi-parameter detection is compressing testing cycles from hours to minutes in European refinery quality control laboratories.
Market Restraints
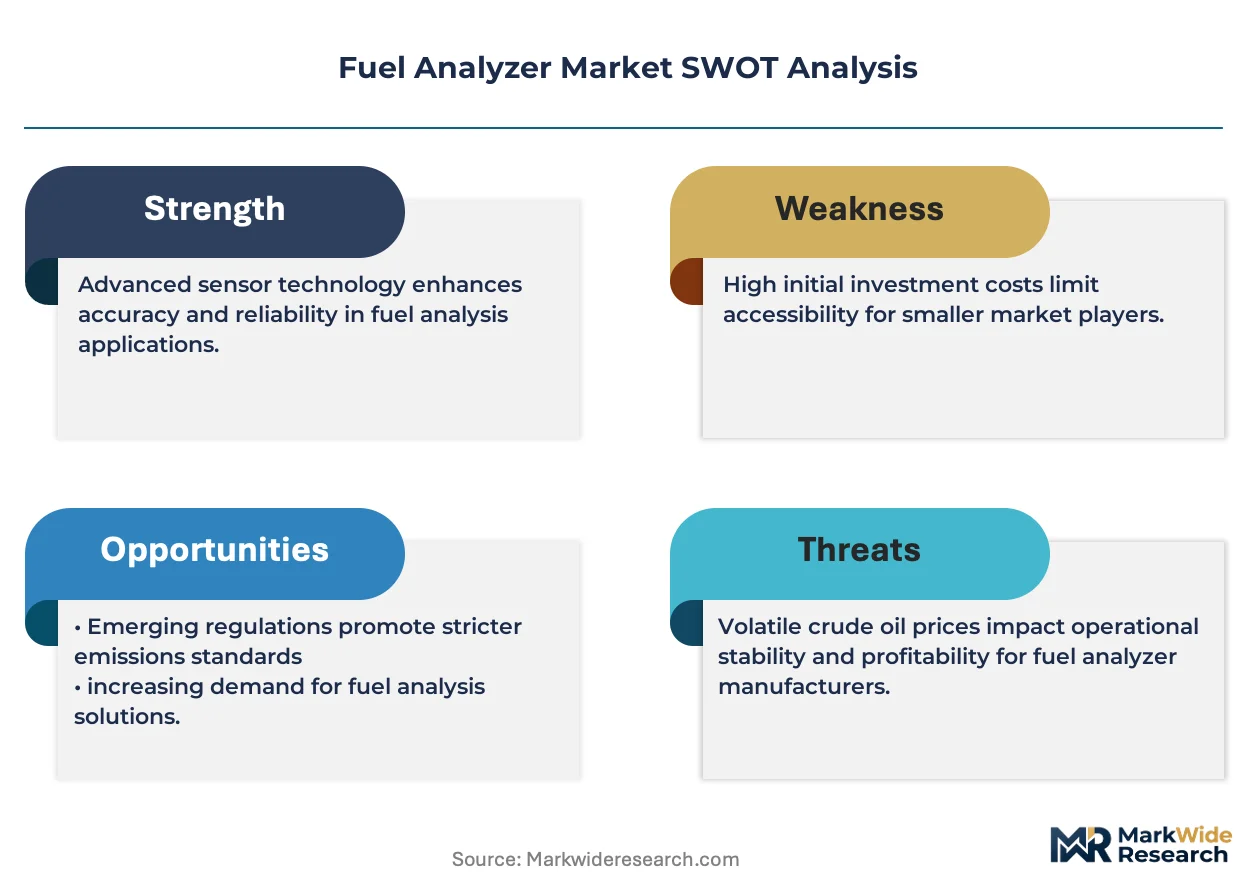
- Calibration Gas Dependency:Electrochemical sensor accuracy requires certified reference gases whose supply concentrates in German and Japanese specialty chemical producers, creating input cost volatility.
- Online System Capex Burden:Continuous monitoring installations demand $2-5 million per refinery stream, freezing out mid-sized independent processors in India and Brazil.
- Technical Skill Scarcity:Interpretation of spectroscopic data patterns requires analytical chemists whose training pipelines have narrowed across North American technical institutes.
Strategic Opportunities
- India's Refinery Expansion:Reliance Industries and Indian Oil Corporation are greenfielding capacity at Jamnagar and Paradip without legacy analyzer infrastructure, enabling direct-to-digital deployment.
- Electrochemical-Optical Hybrid Architectures:Convergence of low-cost sulfur-specific sensors with broadband infrared engines is opening price-accessible tiers for pipeline monitoring applications.
- EU F-Gas Regulation:Reduced calibration gas consumption mandates are creating preference for laser-based analyzers that eliminate consumable-dependent electrochemical cells.
Industry Challenges
- Integration Complexity:Retrofitting online analyzers into 1980s-era distributed control systems at US Gulf Coast refineries requires custom protocol bridges that extend commissioning timelines.
- Certification Bottlenecks:Marine fuel certification under ISO 8754 demands inter-laboratory validation cycles that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Analyzer Market |
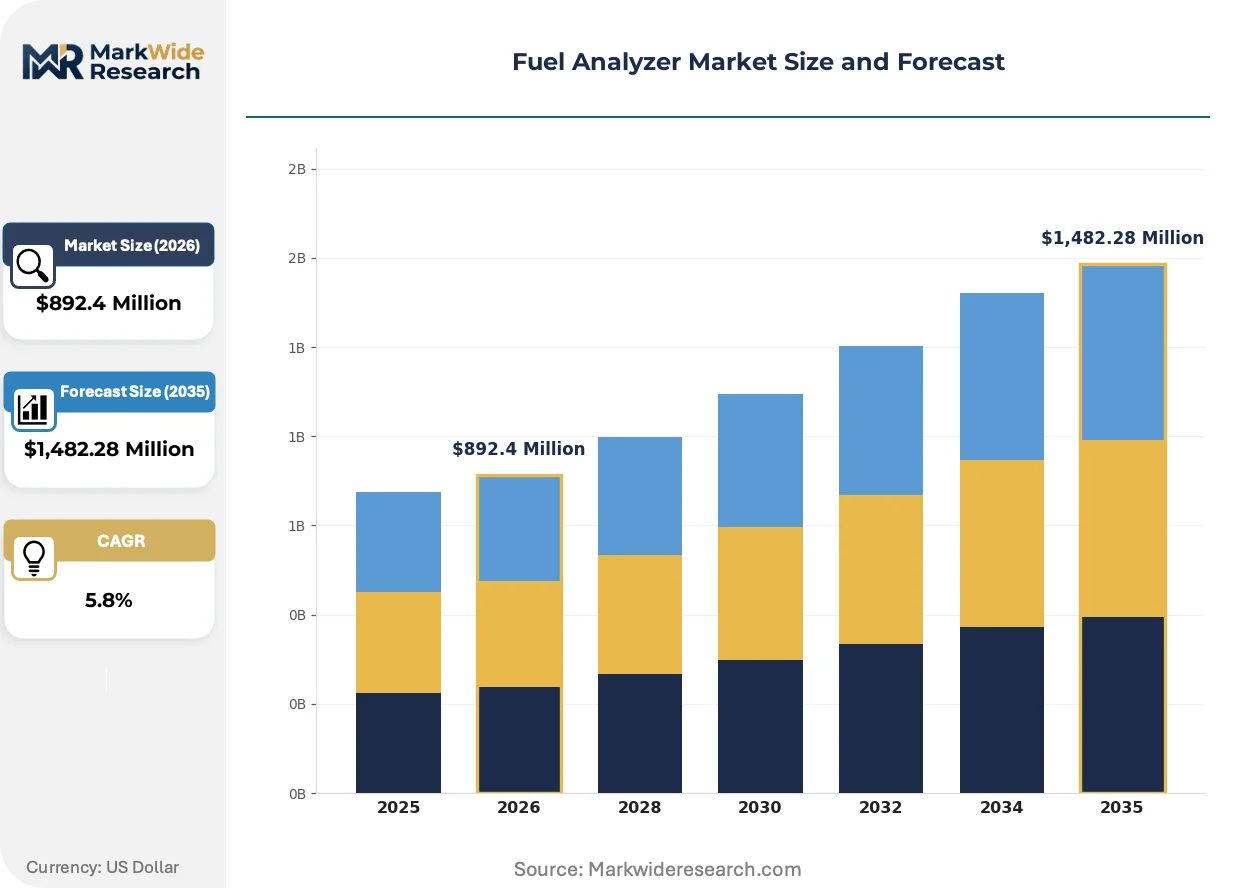
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,482.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Online Analyzers, Laboratory Analyzers, Handheld Analyzers, Fixed Analyzers Technology: Infrared Spectroscopy, Ultrasonic Testing, Chromatography, Electrochemical Sensors, Thermal Conductivity Application: Quality Control, Process Monitoring, Emission Testing, Fuel Blending, Contamination Detection End User: Petroleum Refineries, Shipbuilding, Power Plants, Chemical Processing, Aviation Fuel Providers |
| Companies Covered | Emerson Electric Co., Siemens AG, Thermo Fisher Scientific Inc., PAC LP, General Electric Company, AMETEK Inc., ABB Ltd., eralytics GmbH, HORIBA Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Analyzer Market Shifts & Advancements
Analyzer architecture is pivoting from standalone instruments to embedded sensor networks, with data streams feeding directly into refinery optimization algorithms rather than human-readable reports.
Machine learning-based spectral interpretation is automating pattern recognition in diesel cetane index determination. Major European refiners are deploying these systems at blending headers to close control loops within 30-second cycles. The technology is automating the elimination of intermediate laboratory verification steps that previously added 4-6 hours to batch release.
The EPA's Tier 3 sulfur enforcement protocol now mandates continuous emissions monitoring system correlation for all gasoline batch certifications. US refiners must maintain redundant analyzer channels with automatic failover to avoid regulatory shutdowns. Small-batch specialty fuel producers in Texas and California are responding by outsourcing verification to third-party testing consortia.
Refinery procurement teams are unbundling analyzer hardware from long-term service contracts that previously bundled calibration, consumables, and software updates. Independent service providers in the Netherlands and Singapore now compete for maintenance contracts on ABB, Siemens, and Yokogawa installations. This shift is most visible among Asian independent refiners seeking to reduce total cost of ownership by 15-25 percent through competitive tendering of service components.
Fuel Analyzer Market Segmentation
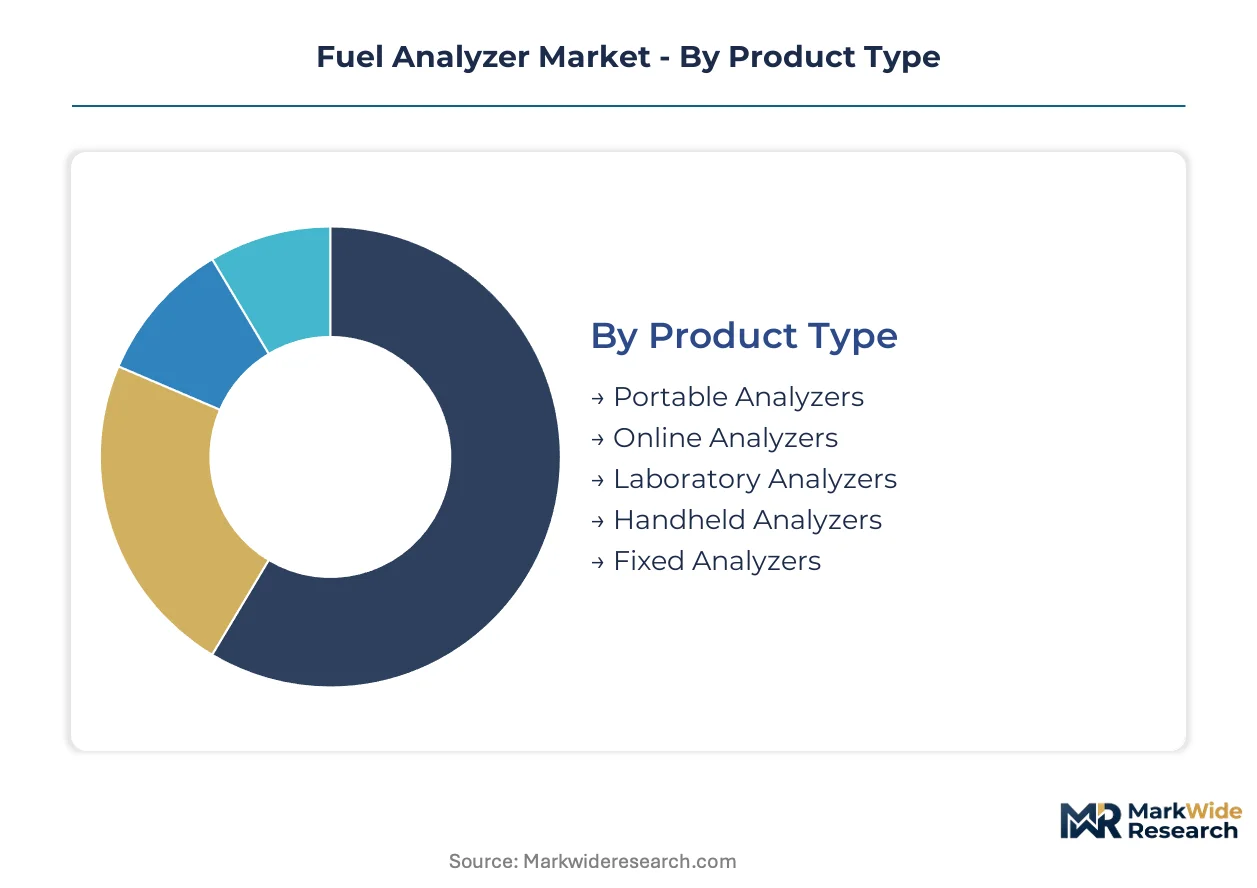
Refinery procurement teams segment fuel analyzers by deployment mode, detection principle, and integration depth. Each axis reveals divergent cost structures and technical requirements that shape vendor selection and lifecycle economics.
Product Type:
Capital intensity and mobility requirements drive the buyer calculus across installation categories.
- Portable Analyzers:Self-contained units with battery power and ruggedized enclosures enable field verification at bunkering terminals and pipeline inspection points. Singapore and Rotterdam marine fuel suppliers deploy these for IMO 2020 sulfur compliance checks where laboratory access is impractical.
- Online Analyzers:Continuous in-line systems integrate directly with refinery distributed control architectures to enable real-time fuel blending optimization. Sinopec and PetroChina facilities in China are replacing legacy infrastructure with these systems under National VI standards.
- Laboratory Analyzers:Bench-top instruments deliver reference-grade precision for certification and dispute resolution at central testing facilities.
- Handheld Analyzers:Single-parameter screening devices offer lower price points for sulfur-specific field testing.
- Fixed Analyzers:Permanent installations at blending headers and tank farm outlets provide dedicated monitoring without mobility requirements.
Online analyzers lead on scale; portable analyzers lead on momentum.
Technology:
Detection speed and parameter breadth determine technology selection for specific compliance workflows.
- Infrared Spectroscopy:Non-destructive multi-parameter detection compresses testing cycles from hours to minutes through broadband spectral analysis. European refinery quality control laboratories favor this technology for cetane index and distillation characteristic determination.
- Electrochemical Sensors:Sulfur-specific cells operate at lower price points for handheld screening applications. Calibration gas dependency creates supply chain concentration risk tied to German and Japanese specialty chemical producers.
- Ultrasonic Testing:Velocity-based measurement enables viscosity and density determination without consumable reagents.
- Chromatography:Separation-based analysis delivers reference-grade precision for benzene and olefin quantification under China's MEE mandates.
- Thermal Conductivity:Simple thermal detection principles support binary mixture analysis in legacy installations.
Infrared spectroscopy dominates installed base; electrochemical sensors are gaining share fastest in handheld tiers.
Application:
Regulatory enforcement intensity and process economics shape deployment priorities across use cases.
- Quality Control:Batch certification and release testing ensures compliance with sulfur caps, cetane minimums, and distillation specifications before product enters distribution.
- Process Monitoring:Continuous measurement at blending headers enables closed-loop control that reduces giveaway and reprocessing costs.
- Emission Testing:Verification of fuel properties against EPA Tier 3 and EU F-Gas Regulation requirements for combustion performance and environmental impact.
- Fuel Blending:Real-time optimization of component ratios to meet specification at minimum cost.
- Contamination Detection:Identification of off-specification material ingress during storage and transfer operations.
Quality control commands the largest installed base; process monitoring shows the steepest expansion trajectory as refineries automate blending operations.
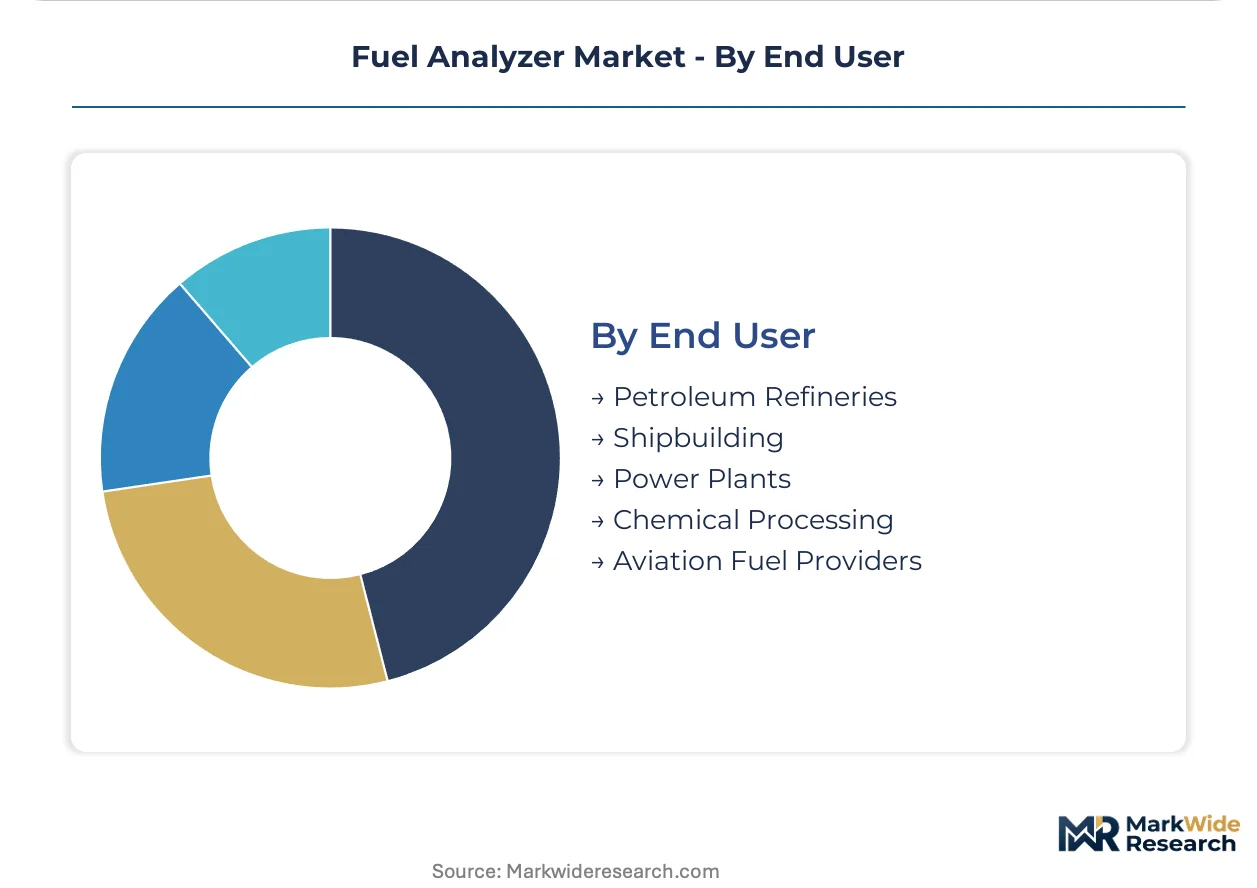
End User:
Regulatory exposure and batch scale create divergent requirements for analyzer precision and throughput.
- Petroleum Refineries:Integrated processing facilities with continuous production streams require online analyzers at multiple unit outlets. India's Reliance Industries and Indian Oil Corporation are greenfielding capacity at Jamnagar and Paradip without legacy infrastructure.
- Shipbuilding:Vessel construction and repair yards verify fuel system compatibility and bunkering infrastructure performance.
- Power Plants:Combustion turbine and diesel generator operators monitor fuel quality to prevent injector fouling and efficiency degradation.
- Chemical Processing:Petrochemical crackers and reformers analyze feedstock composition for yield optimization.
- Aviation Fuel Providers:Jet fuel suppliers maintain stringent particulate and water contamination controls under aviation authority protocols.
Petroleum refineries anchor demand volume; aviation fuel providers maintain the tightest specification tolerances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery operators are relocating analyzer procurement decisions toward jurisdictions where compliance costs and infrastructure modernization cycles create procurement windows. The cost-of-compliance gap between mature and emerging refinery bases is redistributing vendor attention and service capacity.
United States
The EPA's Tier 3 sulfur enforcement protocol mandates continuous emissions monitoring system correlation for gasoline batch certifications. Gulf Coast refineries in Texas and Louisiana are retrofitting online analyzers into 1980s-era distributed control systems, requiring custom protocol bridges that extend commissioning timelines. Small-batch specialty fuel producers in California are outsourcing verification to third-party testing consortia to avoid redundant analyzer capital expenditure.
Germany
Refinery equipment manufacturers are rebalancing capacity toward emission-compliant analyzer systems under EU F-Gas Regulation mandates for reduced calibration gas consumption. Siemens AG leverages its automation portfolio to anchor large-scale refinery installations across the Rhine-Ruhr industrial corridor. Independent service providers in the Netherlands now compete for maintenance contracts on German-engineered installations as procurement teams unbundle hardware from long-term service agreements.
China
The MEE implements national VI fuel standards that mandate stricter benzene and olefin controls, accelerating analyzer replacement cycles at Sinopec and PetroChina facilities. Yangtze River Delta refineries are replacing legacy offline testing infrastructure with online analyzers that enable real-time fuel blending optimization. Qingdao and Ningbo port clusters concentrate demand for portable sulfur verification units serving marine fuel bunkering operations.
India
Reliance Industries and Indian Oil Corporation are greenfielding capacity at Jamnagar and Paradip without legacy analyzer infrastructure, enabling direct-to-digital deployment of integrated measurement systems. The country's refinery expansion bypasses the retrofit complexity facing mature markets. Gujarat and Odisha coastal zones are emerging as procurement hotspots where vendors can install native digital architectures rather than protocol-constrained upgrades.
South Korea
Ulsan and Yeosu industrial complexes concentrate demand for online analyzers that monitor fuel blending in real time, supporting the country's position as a major marine fuel supplier to Singapore and Rotterdam markets. Domestic refiners are deploying infrared spectroscopy systems to compress testing cycles from hours to minutes in quality control laboratories. The Busan bunkering hub requires portable sulfur verification units to comply with IMO 2020 sulfur caps at point of delivery.
Fuel Analyzer Market Competitive Landscape
German and Swiss automation conglomerates anchor one tier; Japanese precision instrument specialists hold another. The market structure consolidates around diversified industrial technology groups with refinery automation heritage and dedicated analytical instrument houses with optical measurement expertise. Three archetypes dominate: integrated automation platform providers, precision optical engine specialists, and analytical instrument conglomerates with life science diversification. Competitive moves center on unbundling service contracts from hardware sales and geographic expansion into Asian greenfield refinery projects.
Within the integrated automation tier, Siemens AG and ABB Ltd. exemplify platform providers that combine fuel analysis with distributed control system architectures. HORIBA Ltd. occupies a position among precision optical specialists focused on sulfur and particulate measurement engines. These three names represent the competitive anchors around which procurement decisions organize, with Emerson Electric Co. and Thermo Fisher Scientific Inc. sitting within adjacent technology conglomerate archetypes that span broader industrial and scientific measurement portfolios.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| Thermo Fisher Scientific Inc. |
| PAC LP |
| General Electric Company |
| AMETEK Inc. |
| ABB Ltd. |
| eralytics GmbH |
| HORIBA Ltd. |
| Others |
Supply & Pricing Matrix
Infrared spectroscopy maturation simultaneously compresses testing-cycle economics and concentrates optical-engine sourcing among German and Japanese precision manufacturers. This technology transition elevates capital efficiency for end-users while tightening supplier leverage over critical photonic components.
Pricing Analysis
Distributor margins on portable analyzers compress as direct-to-refinery sales channels expand. Pricing stratifies across premium online systems, standard laboratory units, and economy handheld tiers based on integration depth and certification grade. Cost compression in the handheld segment intensifies as electrochemical sensor commoditization accelerates. Mid-sized independent refiners in India and Brazil exhibit highest price sensitivity; integrated majors in China and South Korea prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty chemical producers of certified calibration gases for electrochemical sensors. Optical-engine manufacturing draws from Germany, Japan, and the United States, while final assembly concentrates in China and South Korea. Tariff exposure on precision photonic components creates input cost volatility. Distribution runs through refinery automation integrators and independent service providers competing for maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuel analyzer market functions as a geographic-arbitrage play where India's greenfield refinery expansion offers vendor margin relief versus the retrofit complexity and regulatory compliance costs burdening US Gulf Coast facilities.
For Market Incumbents: Extend service unbundling strategies to Asian independent refiners seeking 15-25 percent total cost of ownership reductions. Anchor large-scale installations through automation platform integration while defending against emerging optical-engine specialists by deepening backward integration into calibration gas supply. Prioritize certification investment for ISO 8754 marine fuel validation to close 8-14 month inter-laboratory validation gaps. For New Entrants and Emerging Players: Begin with portable sulfur verification units for Singapore and Rotterdam bunkering terminals where IMO 2020 compliance creates immediate demand without legacy infrastructure competition. Target India's Jamnagar and Paradip greenfield sites for direct-to-digital online analyzer deployment. Pursue go-to-market partnerships with Netherlands and Singapore independent service providers already competing for maintenance contract tendering. For Investors and Strategic Acquirers: Valuations sit cheapest among electrochemical-optical hybrid architecture developers serving pipeline monitoring applications. Long-term viability hinges on regulatory stringency divergence across jurisdictions sustaining replacement-cycle demand. Watch for EU F-Gas Regulation enforcement intensity as the signal indicating laser-based analyzer preference shifts that eliminate consumable-dependent cell technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calibration Gas Supply | Mitigates input cost volatility tied to German and Japanese specialty chemical concentration. |
| Service Contract Unbundling | Enables competitive tendering that reduces total cost of ownership for Asian independent refiners. |
| Electrochemical-Optical Hybrid Development | Opens price-accessible tiers for pipeline monitoring applications between portable and online systems. |
| Laser-Based Analyzer Certification | Addresses EU F-Gas Regulation mandates eliminating consumable-dependent electrochemical cells. |
| Greenfield Direct-to-Digital Deployment | Bypasses retrofit protocol complexity facing 1980s-era distributed control system integrations. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with refinery automation directors, analyzer procurement leads at integrated oil companies, independent service provider executives, and optical-engine R&D specialists. Secondary validation draws from EPA enforcement protocols, EU F-Gas Regulation filings, MEE national standard announcements, customs trade data for photonic component flows, and SEC disclosures from automation conglomerates. Bottom-up unit deployment tracking triangulates against top-down refinery capital expenditure analysis.
Rate-of-change decomposition across the projection horizon models technology substitution effects, regulatory enforcement intensity variations, and refinery modernization cycle phasing. Segmentation dimensions include deployment mode, detection principle, application workflow, and regional regulatory cluster. CAGRs derive from installed-base replacement velocity and greenfield penetration curves calibrated against historical analyzer procurement patterns at Sinopec, PetroChina, Reliance Industries, and Indian Oil Corporation facilities.
Caveats apply where IMO sulfur cap enforcement consistency, EU calibration gas consumption mandate timing, or China National VI standard implementation pace could materially shift the outlook. Forecasts reflect assumptions about refinery automation investment priorities and spectroscopic data interpretation skill availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Global Gas Treatment Market
Fuels
Middle-East and Africa Bunker Fuel Market
Fuels
Aboveground Fuel Storage Market
Fuels
Asia-Pacific Coal Market
Fuels
City Gas Distribution Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Collapsible Fuel Tank Market
Fuels
Brazil Bunker Fuel Market
Fuels
Solid Fuel Tablet Market
Fuels
Global Wood Gas Generator Market
Fuels
Global Methane Hydrate Market
Fuels
Hydrogen Tube Trailer Market
Fuels
Liquefied Helium Tanks Market
Fuels
Italy Chemical Logistics Market
Fuels
Brazil LNG Market
Fuels
North America Aviation Fuel Market