
 Anemometer Market | 2026-2036
Anemometer Market Size, Share, and Industry Trends Forecast 2026-2036
Anemometer Market Analysis
IEC 61400-12-1 Class A compliance is redrawing competitive thresholds for wind resource assessment equipment. Vaisala leverages its calibration laboratory network to sustain premium positioning in offshore wind contracts. Gill Instruments anchors its presence in marine meteorology through salt-spray-resistant ultrasonic designs. NRG Systems competes aggressively on price in the utility-scale wind farm segment while maintaining its Cold Weather package specialization.
An anemometer measures air velocity through mechanical rotation, thermal dissipation, acoustic time-of-flight, or differential pressure principles, with ultrasonic variants achieving accuracy within 0.1 m/s and operating ranges from 0 to 75 m/s. Cup anemometers dominate installed base volumes in legacy wind farms but face replacement cycles as ultrasonic technology displaces mechanical wear-prone designs. HVAC applications represent a concentrated margin pool for handheld and vane instruments where Testo SE & Co. KGaA and OMEGA Engineering hold established channel positions. Pressure-based anemometers retain niche demand in wind tunnel testing for aerospace research despite slower growth trajectories.
The EU Green Deal and IEC standards shape product roadmaps for European manufacturers while China's GB standards and dual carbon goals accelerate domestic ultrasonic anemometer production. The US FAA and NHTSA maintain separate certification tracks for meteorological versus transportation safety applications, fragmenting compliance pathways. Stakeholders must monitor evolving IEC revision timelines and heating technology specifications as cold-climate wind expansion redefines performance benchmarks.
Market Dynamics
Ultrasonic time-of-flight technology is displacing mechanical cup designs across offshore wind turbine control systems, compressing replacement cycles and tightening certification requirements under evolving IEC standards.
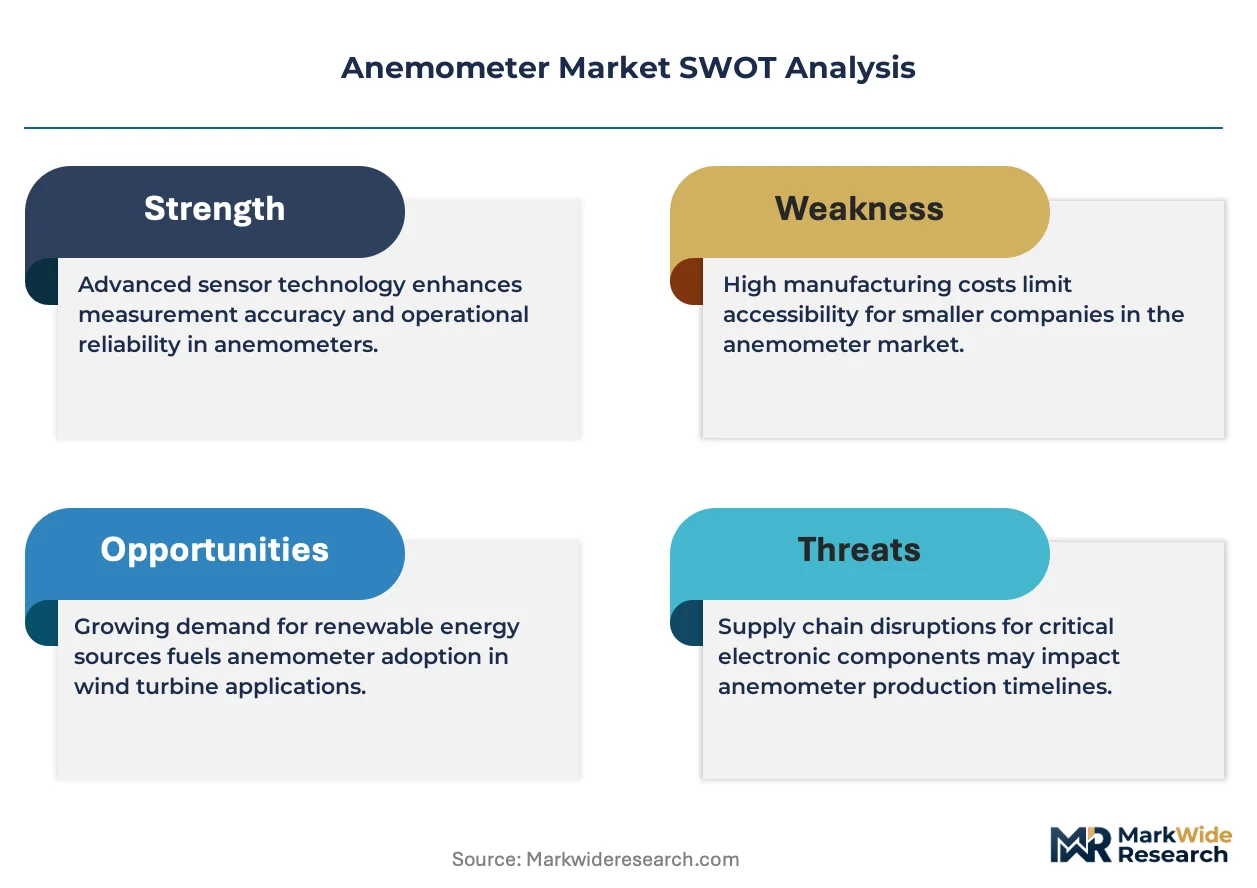
Growth Catalysts
- EU Green Deal renewable targets:Offshore wind farm developers in Germany and Denmark are scaling procurement of heated ultrasonic units for North Sea installations.
- IEC 61400-12-1 Class A compliance:Certification requirements for wind resource assessment equipment are tightening competitive thresholds and filtering substandard suppliers.
- Dual carbon goals:China's GB standards are accelerating domestic ultrasonic anemometer production for utility-scale wind farm deployment.
Market Restraints
- Heated ultrasonic component costs:Cold-climate specifications require specialized heating elements and salt-spray-resistant housings that inflate unit economics.
- Calibration laboratory concentration:Premium positioning depends on accredited metrology infrastructure concentrated in Northern Europe and select US facilities.
- Mechanical cup anemometer installed base:Legacy wind farms face extended replacement timelines due to capital rationing and operational inertia.
Strategic Opportunities
- Cold-climate wind expansion:Heated ultrasonic variants for Baltic Sea and Great Lakes offshore zones represent underpenetrated demand pockets.
- HVAC building automation:Integration with BACnet and Modbus protocols creates white space for vane and handheld instruments in commercial real estate.
- Drone-mounted meteorological sensors:Convergence of ultrasonic time-of-flight with unmanned aerial platforms enables mobile wind profiling for construction and agriculture.
Industry Challenges
- IEC revision timeline uncertainty:Pending updates to heating technology specifications delay product roadmaps and R&D allocation decisions.
- Meteorological instrumentation talent scarcity:Specialized firmware engineers for acoustic signal processing command premium compensation in tight labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anemometer Market |
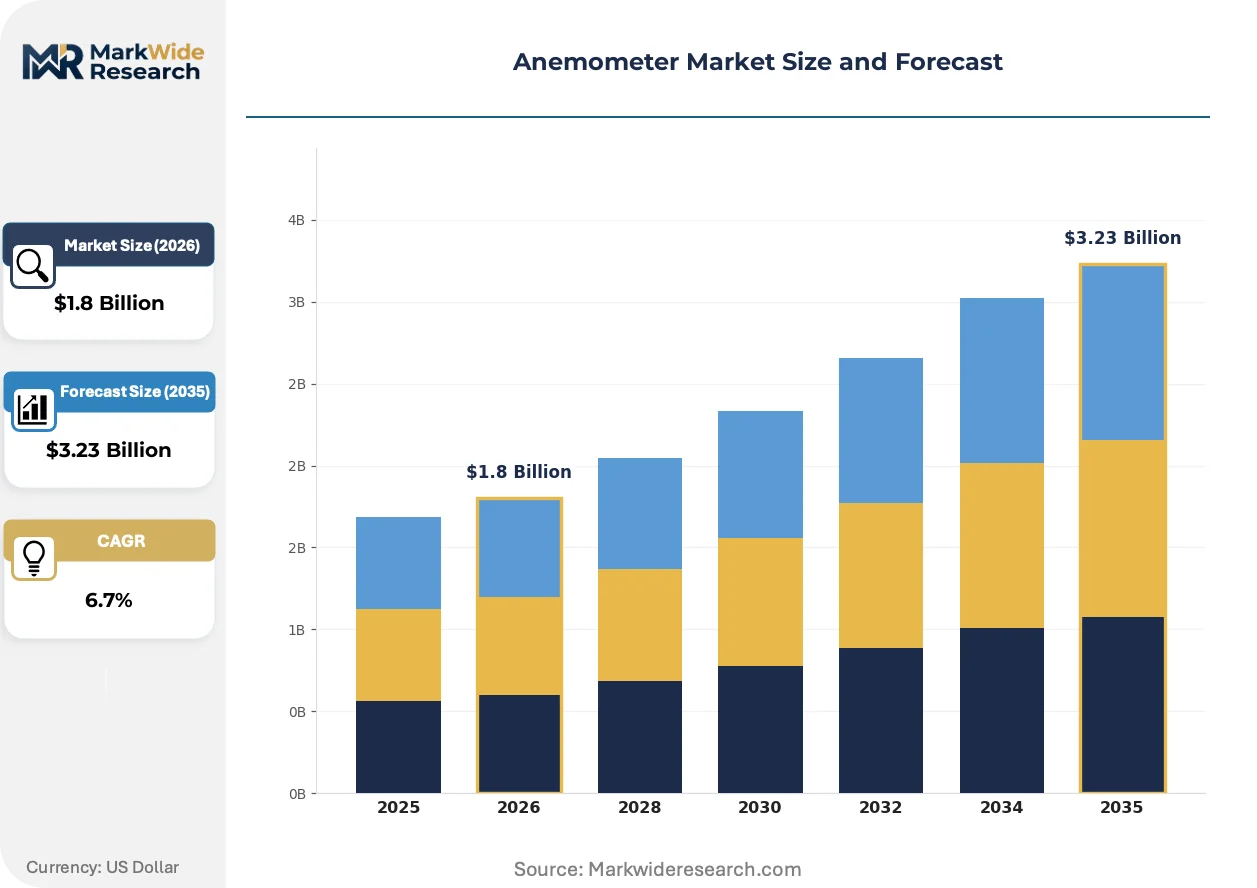
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Digital, Cup, Vane End User: Agriculture, Meteorology, Marine, Industrial Technology: Hot Wire, Ultrasonic, Mechanical, Pressure Application: Weather Monitoring, HVAC, Wind Tunnel Testing, Research |
| Companies Covered | Vaisala, Gill Instruments, Thies Clima, Campbell Scientific, OMEGA Engineering, Testo SE & Co. KGaA, NRG Systems, R. M. Young Company, FT Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anemometer Market Emerging Trajectories
Active reshaping in the anemometer market centers on acoustic sensing sophistication, regulatory harmonization pressures, and procurement consolidation among offshore wind developers.
Heated ultrasonic anemometers with integrated ice detection algorithms are displacing mechanical cup designs in turbine nacelle applications. Offshore wind farm operators in Germany and the UK are specifying these units for all new North Sea installations. This displacement is compressing the addressable market for legacy cup manufacturers and elevating calibration service margins.
REACH and RoHS substance restrictions are tightening material specifications for marine-grade housings and electronic components. European manufacturers are reformulating potting compounds and connector materials to maintain salt-spray resistance without restricted substances. The F-Gas Regulation is additionally pressuring thermal anemometer architectures that rely on controlled refrigerants for calibration references.
Consolidated procurement through offshore wind farm EPC contractors is compressing vendor negotiation cycles and unbundling after-sales service contracts. Developers in Denmark and the Netherlands are mandating decade-long calibration service agreements as contract conditions. This behavioral shift is favoring suppliers with captive metrology infrastructure over component specialists.
Anemometer Market Segmentation
Technology choice in anemometers dictates certification pathways, replacement cycles, and margin structures across offshore wind, aerospace, and building automation verticals. Segmentation reveals where IEC compliance costs concentrate and which product architectures face displacement pressure from ultrasonic time-of-flight designs.
Product Type:
IEC 61400-12-1 Class A certification requirements split the product landscape between precision-grade instruments for turbine control and lower-specification units for general meteorological monitoring.
- Handheld:Portable battery-powered units with integrated data logging target field technicians and agricultural consultants. Demand clusters in Germany and Denmark for wind farm commissioning teams requiring rapid on-site validation of turbine sensor arrays against IEC standards.
- Digital:Microprocessor-based instruments with SDI-12 and RS-485 outputs dominate utility-scale wind resource assessment. Offshore developers in the North Sea specify these for mast-mounted installations where signal integrity across 100-meter heights is non-negotiable.
- Cup:Mechanical rotational designs with three-cup assemblies face accelerated replacement timelines as ultrasonic variants displace wear-prone legacy installations. Salt-spray degradation in Baltic Sea environments compresses service intervals below manufacturer specifications.
- Vane:Combined wind speed and direction sensors with potentiometer or optical encoders serve building automation and marine meteorology. BACnet protocol integration creates specification pull from commercial real estate energy management systems in urban clusters.
Digital instruments handle the majority of throughput in offshore wind procurement; handheld units are expanding most quickly in drone-mounted and portable commissioning applications.
End User:
Customer procurement behavior varies sharply between regulated infrastructure operators and price-sensitive commercial buyers.
- Agriculture:Frost protection and irrigation scheduling drive demand for cost-optimized cup and vane designs. Vineyard operators in France and Germany deploy wireless sensor networks with anemometer nodes for microclimate monitoring.
- Meteorology:National weather services and research institutions mandate traceable calibration chains under WMO guidelines. The German Weather Service operates one of Europe's largest accredited wind tunnel facilities for instrument verification.
- Marine:Salt-spray-resistant ultrasonic anemometers with integrated heating elements command premium positioning for offshore platform and vessel applications. North Sea oil and gas decommissioning is redirecting procurement budgets toward floating wind infrastructure.
- Industrial:Process safety and emissions monitoring applications span chemical plants, refineries, and mining operations. OSHA ventilation requirements in US manufacturing facilities sustain demand for intrinsically certified thermal anemometers.
Meteorology captures the highest calibration service attach rates; marine is climbing the fastest on contract value as decade-long service agreements become standard.
Technology:
Measurement principle selection determines accuracy specifications, maintenance burden, and regulatory acceptance across application verticals.
- Hot Wire:Thermal dissipation sensors using electrically heated filaments achieve response times under 50 milliseconds for turbulence research. Wind tunnel facilities at German aerospace centers specify these for boundary layer studies where frequency resolution exceeds ultrasonic capabilities.
- Ultrasonic:Time-of-flight arrays with no moving parts achieve accuracy within 0.1 m/s across 0-75 m/s ranges. Heated variants with ice detection algorithms are displacing mechanical designs in all new North Sea offshore wind installations.
- Mechanical:Cup and propeller rotation sensors with magnetic or optical pickup dominate legacy installed bases. Capital rationing at older European wind farms extends replacement timelines despite performance degradation.
- Pressure:Differential pressure tubes and Pitot-static configurations retain niche demand in aerospace wind tunnel testing and aircraft systems. Slower growth reflects limited displacement of established installations.
Ultrasonic technology commands the dominant share of new procurement value; hot wire holds the steepest expansion trajectory in research and turbulence measurement segments.
Application:
Use case requirements fragment the market between continuous monitoring infrastructure and episodic measurement scenarios.
- Weather Monitoring:Permanent meteorological station networks require IEC-compliant instruments with remote diagnostics and heated enclosures. Germany's North Sea offshore zones mandate these specifications for all new wind farm meteorological masts.
- HVAC:Building automation integration via BACnet and Modbus protocols creates specification pull for vane and handheld instruments. Commercial real estate developers in Denmark prioritize energy optimization through demand-controlled ventilation systems.
- Wind Tunnel Testing:Aerospace and automotive research facilities combine pressure-based, hot wire, and laser Doppler systems for multi-scale flow characterization. German automotive OEMs operate specialized climatic wind tunnels for thermal management validation.
- Research:Academic and government laboratory procurement emphasizes calibration traceability and open data formats. EU-funded climate research programs in the Netherlands specify instruments with full uncertainty documentation.
Weather Monitoring absorbs the largest equipment procurement volumes; HVAC is gaining share fastest through smart building retrofit cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Northern European metrology infrastructure and North American aerospace testing corridors, with demand fragmentation across offshore wind zones and building automation clusters.
Germany
North Sea and Baltic Sea offshore wind zones drive heated ultrasonic procurement for turbine nacelle installations. The EU Green Deal's renewable targets tighten IEC 61400-12-1 certification timelines for equipment deployed in German waters. Hamburg anchors calibration service demand through its concentration of marine meteorology contractors serving floating wind projects.
United States
FAA meteorological standards and NHTSA transportation safety mandates fragment compliance pathways for dual-use instruments. The Inflation Reduction Act's clean energy provisions accelerate utility-scale wind farm development in the Great Lakes corridor. Pacific Northwest aerospace clusters sustain demand for pressure-based anemometers in wind tunnel testing facilities.
China
Dual carbon goals and GB standards accelerate domestic ultrasonic anemometer production for utility-scale wind deployment. MIIT regulations on meteorological instrumentation tighten quality certification for equipment used in national weather monitoring networks. Yangtze River Delta manufacturing clusters concentrate heated variant assembly for cold-climate export markets.
United Kingdom
North Sea oil and gas decommissioning redirects procurement budgets toward floating wind infrastructure requiring salt-spray-resistant designs. REACH and RoHS substance restrictions reformulate marine-grade housing specifications for North Sea installations. Scottish offshore zones mandate decade-long calibration service agreements as standard contract conditions.
Denmark
Offshore wind farm EPC contractors consolidate procurement cycles and unbundle after-sales service contracts. EU Green Deal renewable targets accelerate replacement of mechanical cup anemometers in legacy installations. Copenhagen-area energy management specialists drive BACnet protocol integration for commercial real estate applications.
Anemometer Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where precision-grade suppliers and volume manufacturers occupy distinct competitive spaces. Premium positioning depends on captive metrology infrastructure and accredited calibration laboratory networks. Three archetypes dominate: precision instrument specialists with calibration assets, volume manufacturers competing on unit economics, and marine-environment specialists with salt-spray-resistant designs. Competitive moves center on strategic partnerships for protocol integration and geographic expansion into cold-climate wind zones.
Among Northern European precision instrument specialists, Vaisala and Thies Clima exemplify the calibration-dependent archetype, while Gill Instruments occupies a position within marine-environment specialization. These three represent distinct competitive vectors: metrology infrastructure ownership, marine-grade engineering heritage, and offshore wind certification expertise.
| Leading Market Players |
|---|
| Vaisala |
| Gill Instruments |
| Thies Clima |
| Campbell Scientific |
| OMEGA Engineering |
| Testo SE & Co. KGaA |
| NRG Systems |
| R. M. Young Company |
| FT Technologies |
| Others |
Supply Flow & Price Mechanics
Heated ultrasonic component substitution for mechanical cup assemblies redraws manufacturing geography toward Yangtze River Delta assembly clusters while compressing margin structures for legacy suppliers tethered to Baltic Sea calibration dependencies.
Pricing Analysis
IEC 61400-12-1 Class A compliance dictates the pricing tier structure across precision-grade, standard, and economy levels for wind resource assessment equipment. Certification grade and captive metrology infrastructure anchor price differentiation between Northern European specialists and volume manufacturers. Cost compression in the mechanical cup segment intensifies as ultrasonic variants displace wear-prone legacy installations. Offshore wind farm EPC contractors demonstrate lowest price sensitivity due to decade-long calibration service bundling requirements.
Supply Chain Analysis
Germany and Denmark anchor precision instrument assembly and accredited calibration laboratory networks for IEC-compliant equipment. China feeds from domestic MEMS sensor foundries and heated housing component suppliers serving cold-climate export specifications. Single-source vulnerability concentrates in Nordic metrology infrastructure for traceable wind tunnel verification. Distribution runs through offshore wind farm EPC contractors consolidating procurement cycles and unbundling after-sales service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as ultrasonic time-of-flight architectures displace mechanical cup designs across turbine nacelle applications.
For Market Incumbents: Consolidate calibration service attach rates through captive metrology infrastructure investments in Baltic Sea zones. Deepen backward integration into heated housing component production to offset salt-spray-resistant material cost inflation from REACH and RoHS reformulation requirements. For New Entrants and Emerging Players: Anchor in drone-mounted meteorological sensor integration for construction and agricultural wind profiling applications. BACnet protocol compatibility for commercial real estate HVAC automation represents the most penetrable white space with established channel positions held by Testo SE & Co. KGaA and OMEGA Engineering. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors precision instrument specialists with captive laboratory networks. Long-term viability across the projection horizon rests on IEC revision timeline navigation and cold-climate specification expansion. Monitor pending updates to heating technology specifications as the critical inflection signal for R&D allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | Accredited metrology infrastructure in Hamburg anchors service contract capture for floating wind projects. |
| Heated Ultrasonic Product Line Extension | Ice detection algorithm integration addresses Baltic Sea and Great Lakes cold-climate procurement specifications. |
| Protocol Integration Partnership | BACnet and Modbus compatibility unlocks commercial real estate energy management system specifications. |
| Salt-Spray-Resistant Housing Reformulation | REACH and RoHS compliance maintains marine-grade positioning without restricted potting compounds. |
| Decade-Long Service Agreement Structuring | Unbundled after-sales contracts align with Danish and Dutch EPC contractor procurement consolidation patterns. |
Methodological Framework
Operator-level perspectives from offshore wind farm developers, turbine nacelle engineers, calibration laboratory technicians, and marine meteorology contractors anchored the qualitative base. Primary interview data combined with secondary validation from IEC standard revision documentation, EU Green Deal implementation reports, F-Gas Regulation filings, and customs trade records for meteorological instrumentation. Bottom-up equipment procurement tracking and top-down renewable energy capacity deployment models provided triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against alternative IEC revision timeline scenarios and cold-climate wind zone expansion patterns. Segmentation dimensions modeled include technology type, certification grade tier, end-use vertical, application scenario, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression rates and ultrasonic penetration trajectories in offshore versus onshore installations. Industry-specific inputs incorporated heating element cost curves and salt-spray-resistant housing material availability constraints.
Underlying assumptions cover IEC 61400-12-1 Class A certification stability and EU Green Deal renewable target continuity, with deviation risk concentrated in pending heating technology specification updates and REACH substance restriction expansions. Recalibration cycles align with material shifts in IEC revision timelines and offshore wind farm procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Asia-Pacific Bulk Acoustic Wave Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
North America Acoustic Sensors Market