
 Anti-Collision Sensor Market | 2026-2036
Anti-Collision Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Collision Sensor Market Analysis
Photonics and radar engineering talent scarcity is reorganizing supplier geography across the anti-collision sensor value chain. Robert Bosch GmbH sustains broad manufacturing scale across European and Asian module facilities. Infineon Technologies AG specializes in silicon germanium and gallium nitride chipsets for 77 GHz automotive radar front ends. NXP Semiconductors N.V. dominates secure vehicle networking architectures that bind sensor arrays to central compute domains.
Anti-collision sensors are electromechanical or photonic detection devices that emit structured energy pulses—radio waves, ultrasonic pressure waves, or coherent light—and measure time-of-flight returns to calculate object distance, velocity, and trajectory with sub-meter precision. Their primary commercial purpose is to enable real-time hazard identification and automated braking or steering intervention in mobile platforms. Radar modules retain the largest installed base among product types, while LiDAR captures the fastest expansion as solid-state designs reduce unit costs for automotive integration. Fusion technology leads technology segmentation by revenue, though machine learning inference layers represent the emerging margin pool as software-defined perception replaces fixed-threshold detection.
NHTSA mandates automatic emergency braking on all new US passenger vehicles, while UNECE R152 and R79 regulations in Europe enforce pedestrian and cyclist detection thresholds that reshape sensor minimum specifications. The EU AI Act adds conformity requirements for machine learning components in safety-critical automotive systems, tightening market access for non-compliant module suppliers. Stakeholders must track how regulatory divergence between US FMVSS updates and European type-approval frameworks affects platform engineering costs and regional sourcing decisions.
Market Dynamics
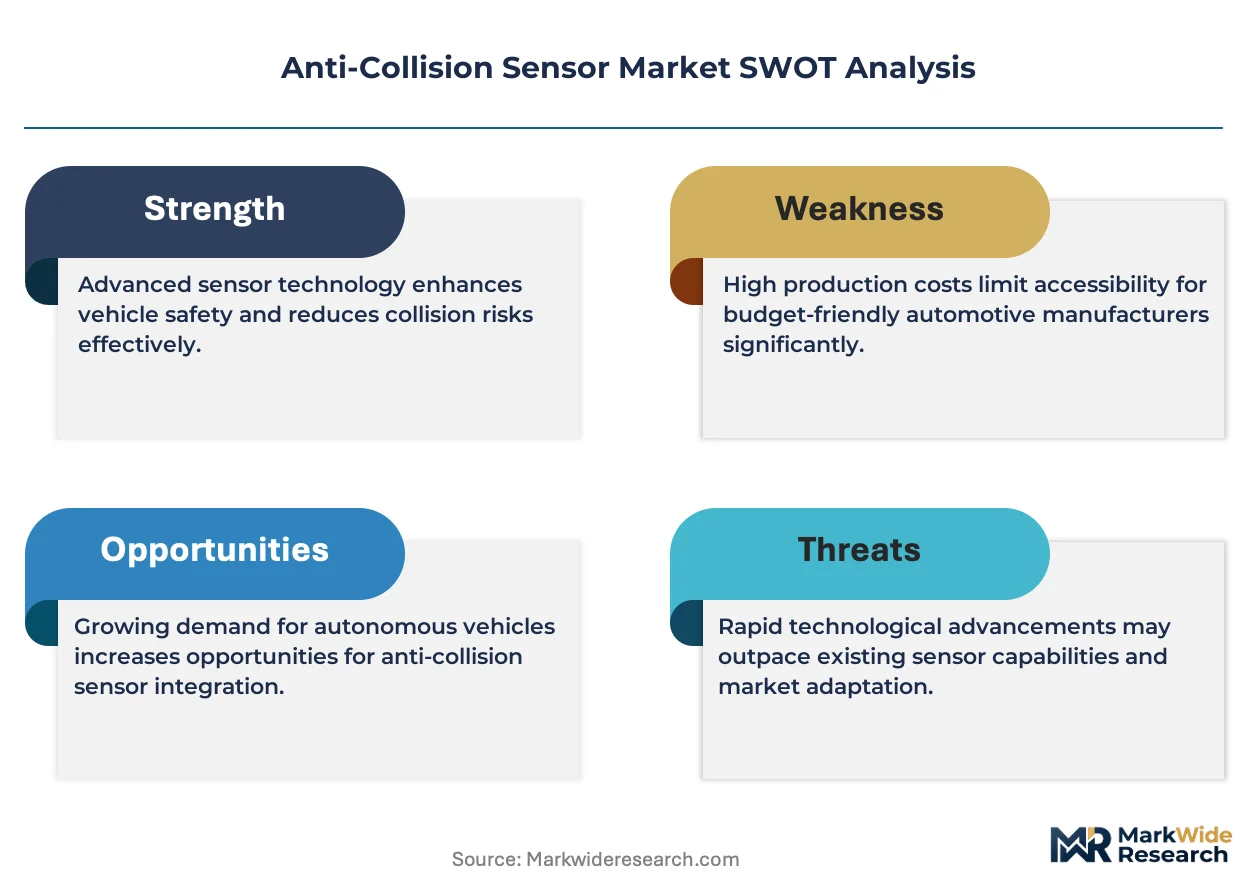
Multi-sensor fusion architectures are compressing module supplier margins while elevating software-layer valuations across the anti-collision sensor value chain. Tier-1 integrators now capture perception-stack revenue that hardware vendors previously monopolized.
Growth Catalysts
- NHTSA AEB Mandate:Automatic emergency braking requirements for all US passenger vehicles force OEM procurement of radar-LiDAR fusion suites, expanding addressable hardware volume.
- Silicon Photonics:Solid-state LiDAR designs using optical phased arrays slash per-unit manufacturing costs, enabling mid-market vehicle segment penetration.
- Germany:Stuttgart and Munich engineering clusters concentrate radar algorithm development talent, accelerating homologation cycles for European OEM platforms.
Market Restraints
- Gallium Nitride Wafer Supply:77 GHz radar front-end production depends on constrained GaN-on-SiC substrate capacity concentrated among three Asian foundries.
- UNECE R79 Compliance Friction:Steering regulation updates impose redundant sensor validation protocols that extend type-approval timelines by 8-14 months for non-EU module suppliers.
- Ultrasonic Substitution Ceiling:Parking-assist applications resist radar migration due to sub-$15 ultrasonic module pricing in economy vehicle segments.
Strategic Opportunities
- India:PLI scheme incentives for automotive electronics manufacturing attract radar module assembly investments serving domestic OEM export programs.
- Agricultural Autonomy:Combine harvester and tractor OEMs in the US Midwest adopt 4D imaging radar for collision avoidance in GPS-guided field operations.
- EU AI Act Conformity:Machine learning perception stacks certified under safety-critical automotive frameworks command premium positioning in European platform bids.
Industry Challenges
- Photonics Packaging Expertise:Solid-state LiDAR volume manufacturing requires precision optical alignment skills scarce outside Germany, Japan, and California engineering corridors.
- Functional Safety Certification:ISO 26262 ASIL-D validation for sensor fusion controllers demands 18-24 month development cycles that compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Collision Sensor Market |
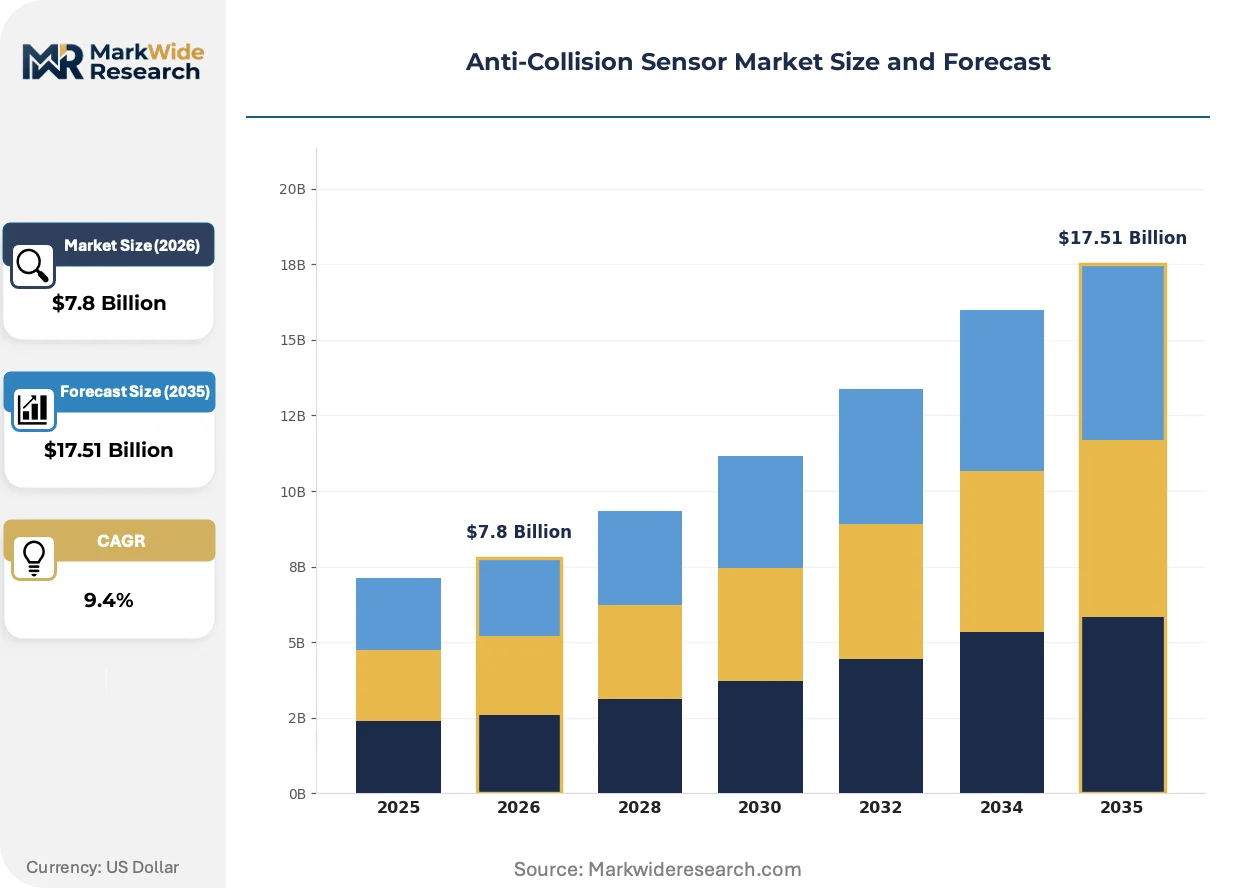
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LiDAR, Ultrasonic Sensors, Radar, Cameras End User: Aerospace, Automotive OEMs, Manufacturing Facilities, Construction Technology: Active Sensing, Passive Sensing, Fusion Technology, Machine Learning Application: Collision Avoidance, Autonomous Vehicles, Robotics, Security Systems |
| Companies Covered | Valeo S.A., Aptiv plc, Robert Bosch GmbH, Infineon Technologies AG, Autoliv, Inc., Continental AG, ZF Friedrichshafen AG, NXP Semiconductors N.V., Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Collision Sensor Market Emerging Trajectories
Sensor fusion architectures are collapsing the historical boundary between hardware module supply and software perception licensing. Tier-1 suppliers now compete on inference latency rather than detection range specifications alone.
Frequency-modulated continuous-wave radar is bifurcating the market between legacy time-of-flight architectures and coherent detection designs. Premium OEM platforms in Germany and Japan adopt 4D imaging radar for elevation mapping and object classification. This technology compression forces mid-tier suppliers to abandon 24 GHz legacy product lines entirely.
EU AI Act conformity requirements are reshaping machine learning component sourcing for safety-critical automotive systems. The regulation mandates documented training data provenance and model interpretability that exclude black-box perception algorithms from European type approval. LiDAR point-cloud processing stacks face the steepest compliance retrofit costs.
Fleet procurement of standardized ADAS sensor suites is displacing bespoke OEM development programs. Rental and logistics operators in the United States now specify interchangeable radar-LiDAR modules across multi-brand vehicle pools. This specification consolidation favors suppliers with cross-platform calibration tools and remote diagnostic capabilities.
Anti-Collision Sensor Market Segmentation
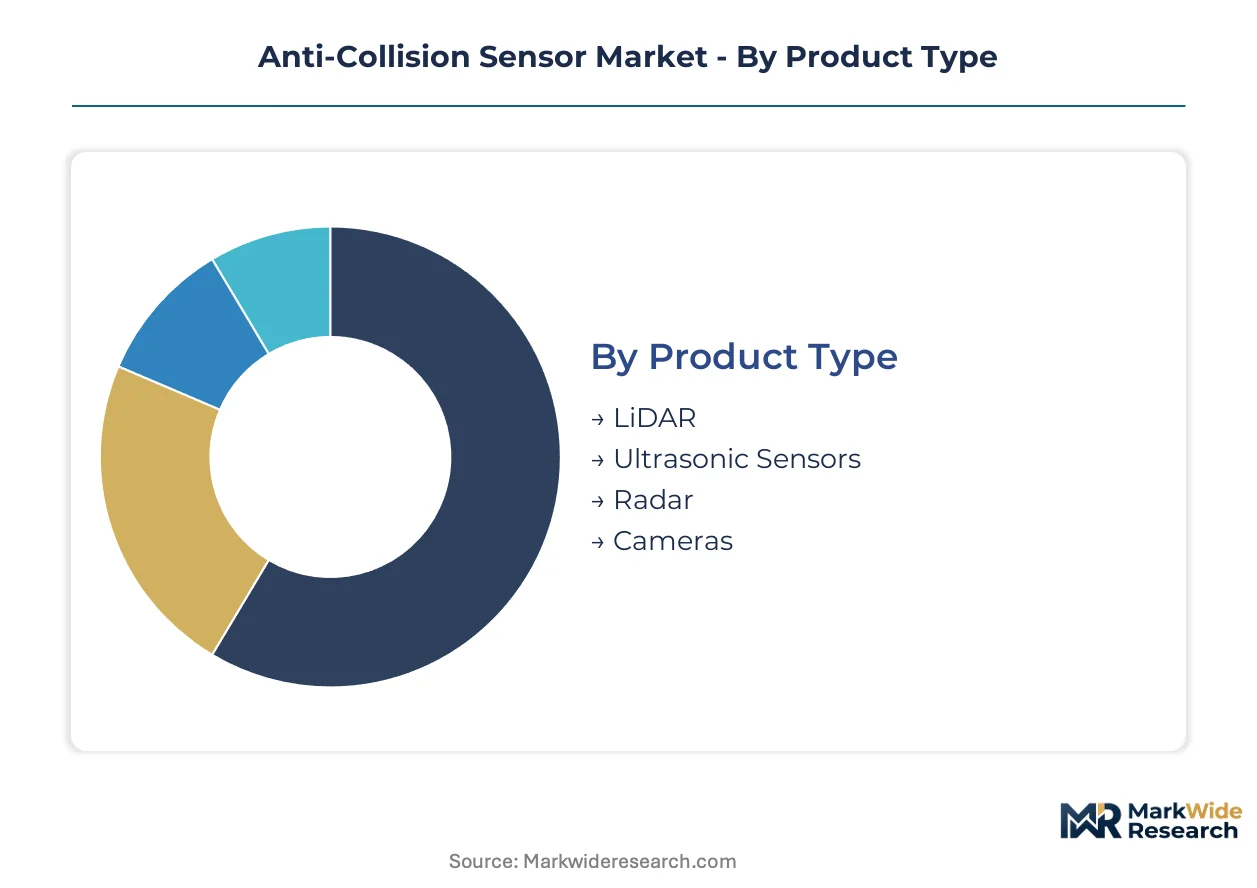
Anti-collision sensor procurement patterns diverge sharply across hardware modalities, end-use platforms, and computational architectures. Understanding where margin pools concentrate within each dimension enables suppliers to prioritize R&D investment and platform positioning.
Product Type:
Margin pools concentrate in solid-state LiDAR and 4D imaging radar where semiconductor integration reduces bill-of-materials costs while preserving premium pricing.
- LiDAR:Solid-state optical phased arrays replace mechanical scanning assemblies with silicon photonics. German and Japanese OEMs specify these units for Level 3 highway pilot systems, though GaN driver chip shortages constrain volume scaling.
- Radar:Frequency-modulated continuous-wave architectures now dominate 77 GHz front-end design. Stuttgart engineering clusters supply algorithm IP that distinguishes radar modules on object classification accuracy rather than range alone.
- Ultrasonic Sensors:Piezoelectric transducer arrays serve parking-assist functions in economy vehicle segments where sub-fifteen-dollar module pricing resists radar substitution.
- Cameras:CMOS image sensors with HDR processing enable traffic sign recognition and lane-keeping assistance on cost-sensitive ADAS platforms.
The dominant share belongs to Radar, while LiDAR is closing the gap fastest.
End User:
Application complexity determines sensor specification tiers, with aerospace and automotive OEMs driving divergent validation protocols.
- Automotive OEMs:Multi-sensor fusion suites integrate radar, LiDAR, and camera feeds into central compute domains. NHTSA AEB mandates force procurement across all US passenger vehicle classes, compressing hardware margins while elevating software-layer valuations.
- Aerospace:Radar altimeters and terrain awareness systems require DO-178C software certification and extended temperature operating ranges. FAA certification timelines stretch 24-36 months, filtering supplier participation to established avionics houses.
- Manufacturing Facilities:Warehouse AGVs deploy 2D LiDAR for pedestrian detection in shared human-robot workspaces. ISO 3691-4 safety standards mandate redundant sensing architectures.
- Construction:Excavator and crane OEMs specify ruggedized ultrasonic and radar modules for blind-spot monitoring in dusty, high-vibration environments.
Automotive OEMs command the largest procurement volumes, though Aerospace sustains the highest unit margins.
Technology:
Computational intensity separates hardware-centric detection from software-defined perception stacks.
- Fusion Technology:Multi-sensor data aggregation combines time-synchronized inputs from radar, LiDAR, and cameras into unified environmental models. EU AI Act conformity requirements now govern machine learning components within these stacks.
- Machine Learning:Neural network inference engines process raw sensor feeds for object classification and trajectory prediction. Training data provenance documentation requirements under European type-approval frameworks exclude black-box algorithms.
- Active Sensing:Energy-emitting modalities including radar and LiDAR calculate time-of-flight returns for direct distance measurement.
- Passive Sensing:Camera-based detection relies on ambient illumination, constraining performance in low-light conditions without supplemental active illumination.
Fusion Technology generates the dominant revenue share, while Machine Learning claims the steepest expansion trajectory.
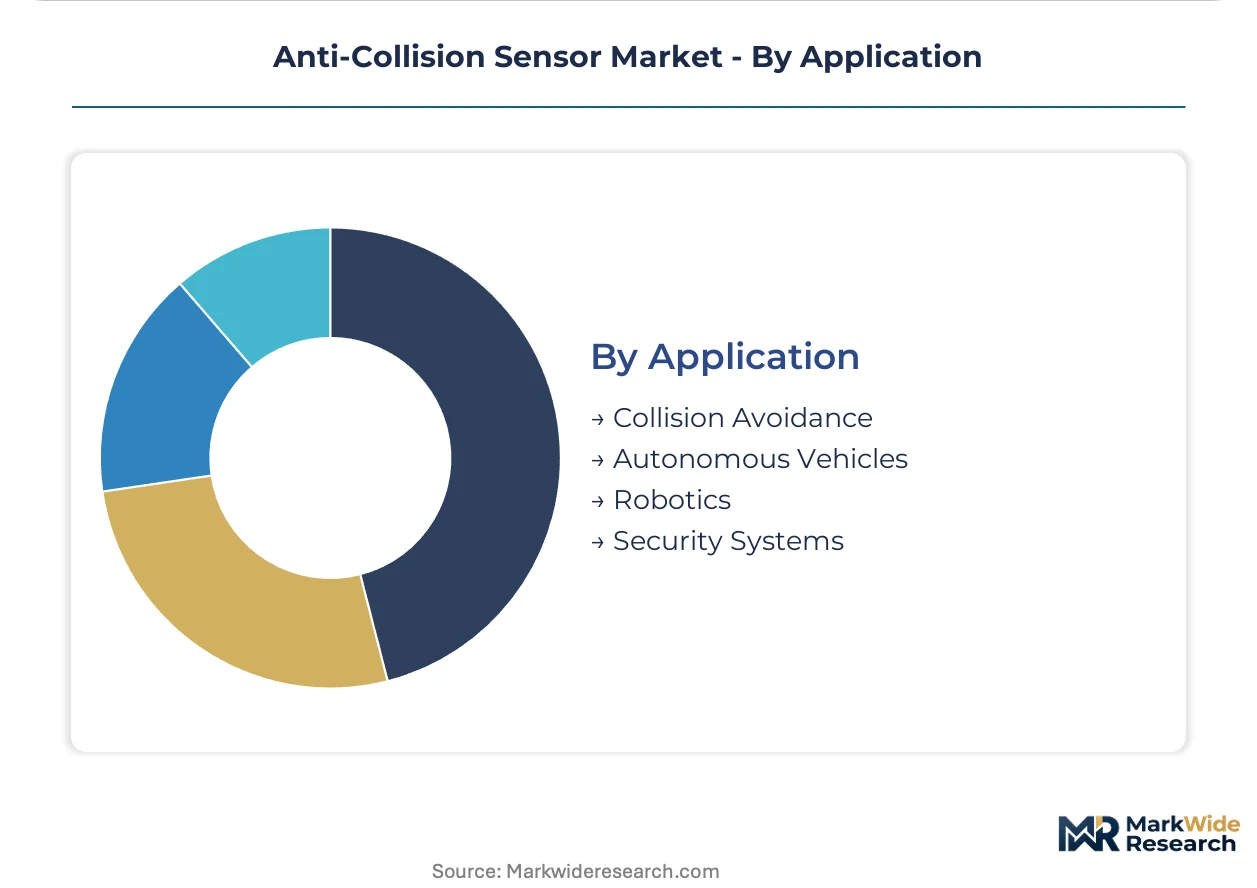
Application:
Functional safety requirements escalate with automation level, reshaping sensor redundancy specifications.
- Autonomous Vehicles:Level 4 robotaxi platforms demand 360-degree environmental coverage with sensor hardware redundancy. Waymo and Cruise specifications drive solid-state LiDAR volume commitments.
- Collision Avoidance:Automatic emergency braking systems represent the largest installed base, with NHTSA mandates extending to light trucks and SUVs.
- Robotics:Mobile manipulation platforms combine 2D LiDAR with depth cameras for simultaneous localization and mapping in unstructured environments.
- Security Systems:Perimeter monitoring applications adopt low-cost radar modules for intrusion detection, with false-positive filtering as the primary performance discriminator.
Collision Avoidance retains the largest deployment base, while Autonomous Vehicles is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys anti-collision sensors primarily for Level 3 highway automation, whereas the United States emphasizes NHTSA-mandated automatic emergency braking across all passenger vehicle classes. Japan concentrates engineering talent on 4D imaging radar for premium OEM platforms. India attracts module assembly investment through production-linked incentives.
United States
NHTSA mandates automatic emergency braking on all new passenger vehicles and light trucks, forcing OEM procurement of radar-LiDAR fusion suites across vehicle segments. The regulation compresses hardware margins while elevating software-layer valuations. Detroit engineering clusters concentrate algorithm development for pedestrian and cyclist detection thresholds.
Germany
Stuttgart and Munich engineering clusters supply radar algorithm IP that distinguishes modules on object classification accuracy. UNECE R79 steering regulations impose redundant sensor validation protocols extending type-approval timelines. Baden-Württemberg hosts dedicated radar and LiDAR engineering centers serving European OEM platforms.
Japan
Premium OEM platforms adopt 4D imaging radar for elevation mapping and object classification. METI industrial policy supports semiconductor integration in automotive sensor front ends. Nagoya engineering corridors concentrate photonics packaging expertise for solid-state LiDAR volume manufacturing.
China
Domestic OEMs expand procurement of multi-sensor fusion suites for Level 2+ ADAS platforms. MIIT standards govern vehicle networking architectures binding sensor arrays to central compute domains. Yangtze River Delta manufacturing bases concentrate radar module assembly capacity.
India
PLI scheme incentives for automotive electronics manufacturing attract radar module assembly investments. Domestic OEM export programs drive demand for homologated sensor suites meeting European and North American standards. Tamil Nadu and Maharashtra host emerging tier-1 supplier engineering operations.
Anti-Collision Sensor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the anti-collision sensor value chain. Tier-1 integrators now capture perception-stack revenue that hardware vendors previously monopolized. Two strategic archetypes dominate: diversified automotive suppliers with broad manufacturing scale, and semiconductor specialists with captive chipsets for radar front ends. Competitive moves center on multi-sensor fusion partnerships and silicon photonics capacity expansion.
Within the integrated tier, Robert Bosch GmbH exemplifies diversified manufacturing scale across European and Asian module facilities. Infineon Technologies AG occupies a specialist position in silicon germanium and gallium nitride chipsets for 77 GHz automotive radar front ends. NXP Semiconductors N.V. anchors secure vehicle networking architectures that bind sensor arrays to central compute domains.
| Leading Market Players |
|---|
| Valeo S.A. |
| Aptiv plc |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| Autoliv, Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| NXP Semiconductors N.V. |
| Denso Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between Tier-1 integrators and GaN-on-SiC foundries lock in wafer supply visibility while fixing radar front-end unit costs for 24-36 month procurement cycles, insulating automotive OEMs from spot market volatility in compound semiconductor substrates.
Pricing Analysis
Project-based pricing for LiDAR modules dominates premium ADAS platforms, with cost differentiation driven by ISO 26262 ASIL-D certification tier and software inference latency performance. Pricing pressure stems from silicon photonics cost compression in solid-state designs, forcing mechanical scanning LiDAR suppliers toward sub-$500 unit economics. Economy vehicle segments exhibit acute price sensitivity, while robotaxi OEMs prioritize detection reliability over per-unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor GaN-on-SiC wafer fabrication for 77 GHz radar chipsets, while Germany and Japan concentrate precision optical alignment for solid-state LiDAR assembly. Raw material dependencies span gallium nitride substrates, silicon photonics foundry capacity, and rare-earth dopants for laser diodes. Single-source vulnerability in GaN-on-SiC substrate supply poses structural risk. Distribution runs through Tier-1 automotive supplier networks with direct OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from software-defined perception stacks that displace fixed-threshold hardware detection, requiring defensive repositioning around machine learning inference layers.
For Market Incumbents: Consolidate algorithm IP assets in Stuttgart and Munich engineering clusters to defend against emerging solid-state LiDAR entrants. Secure captive GaN-on-SiC wafer supply through backward integration into Asian foundry partnerships. Prioritize EU AI Act conformity certification for machine learning perception stacks to maintain European platform access.
For New Entrants and Emerging Players: Lead with agricultural autonomy applications in the US Midwest, where 4D imaging radar demand for GPS-guided combine harvesters remains underpenetrated by established automotive suppliers. Target warehouse AGV safety systems under ISO 3691-4 standards as a white-space entry point. Deploy remote diagnostic capabilities as the primary go-to-market differentiator against incumbent hardware vendors.
For Investors and Strategic Acquirers: Semiconductor specialists with captive 77 GHz radar front-end chipsets represent the most defensible acquisition archetype amid fusion architecture margin compression. Monitor NHTSA AEB mandate enforcement intensity as the signal indicating hardware volume inflection. Long-term viability hinges on software-layer revenue capture exceeding 40% of total platform value across the projection horizon.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Sensor Fusion Partnership | Robert Bosch GmbH and Infineon Technologies AG collaborations accelerate Level 3 highway pilot homologation cycles. |
| Silicon Photonics Capacity Expansion | Nagoya engineering corridors solidify Japan's position in solid-state LiDAR volume manufacturing. |
| EU AI Act Conformity Investment | Machine learning perception stacks certified under safety-critical frameworks command premium European positioning. |
| PLI Scheme Manufacturing Localization | Tamil Nadu radar module assembly investments serve domestic OEM export programs to European markets. |
| 4D Imaging Radar Platform Standardization | Premium OEM specifications in Germany and Japan displace legacy 24 GHz time-of-flight architectures. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, and aftermarket distribution heads; and secondary validation against vehicle production databases, IHS Markit registration data, SEC 10-K filings, and UNECE type-approval registries. Bottom-up sensor unit estimates triangulated with top-down automotive electronics spending forecasts.
Across the analysis window, the forecasting framework modeled vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from regression analysis of historical ADAS penetration curves and regulatory mandate implementation schedules. Inputs included NHTSA AEB compliance timelines and EU AI Act enforcement trajectories.
Forecasts assume regulatory continuity in US FMVSS and European UNECE frameworks; material policy shifts would require re-modeling. Supply disruption in GaN-on-SiC substrates or photonics packaging capacity constraints represent specific revision triggers. Recalibration cycles align with material shifts in homologation requirements and semiconductor foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Electric Vehicle (EV) Sensor Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Sensor Development Kit Market