
 Lighting Control Sensors Market | 2026-2036
Lighting Control Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Lighting Control Sensors Market Analytics
REACH is hardening material compliance costs for European entrants, forcing component suppliers to requalify photodiode substrates and housings. ams-OSRAM AG leverages its vertically integrated GaN-on-silicon capacity to absorb these certification burdens internally. STMicroelectronics N.V. sustains R&D intensity across time-of-flight proximity modules that integrate ambient light and motion detection. Acuity Brands, Inc. anchors its specification-grade portfolio through deep relationships with North American electrical contractors.
Lighting control sensors are optoelectronic devices that detect occupancy, ambient illuminance, or motion to autonomously modulate artificial lighting output, typically operating across spectral ranges from 400 nm to 1100 nm with response times under 100 milliseconds for real-time dimming control. Their primary commercial purpose is to minimize wasted luminaire runtime in intermittently occupied spaces. Occupancy sensors currently dominate specification activity in commercial retrofits where payback periods compress utility incentives against labor costs. Wireless technology is displacing wired architectures in historic building adaptations where conduit installation proves prohibitive. Photocells retain mature positions in outdoor street and area lighting where simple dusk-to-dawn switching satisfies most control requirements.
The EU Green Deal and its attendant Energy Performance of Buildings Directive recast sensor deployment from optional efficiency measure to mandatory compliance pathway across member states. EPA Energy Star specifications and ASHRAE Standard 90.1 in the United States similarly embed automatic daylight-responsive controls into baseline code for new construction above threshold floor areas. Stakeholders must monitor whether emerging cyber-resilience standards for connected lighting networks fragment certification requirements across jurisdictions and delay product rollouts.
Market Dynamics
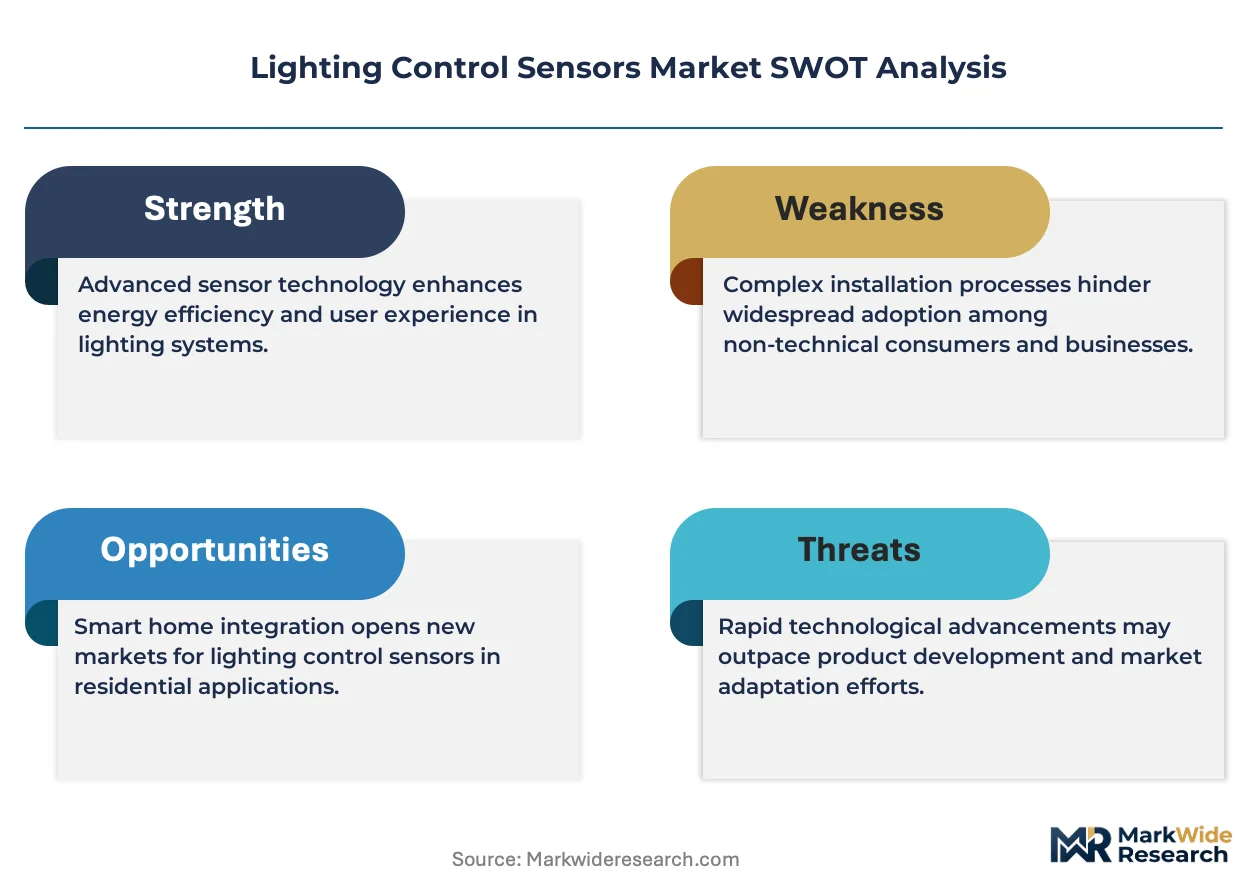
Retrofit mandates across aging commercial building stock are compressing payback thresholds for sensor deployments, converting energy code compliance from optional efficiency play into procurement necessity for facility managers.
Growth Catalysts
- EU Green Deal building renovation mandates:Mandatory performance thresholds for installed sensor systems are accelerating wholesale upgrades across member states' aging office portfolios.
- Wireless sensor architectures:Historic building adaptations where conduit installation proves prohibitive are displacing wired infrastructure and expanding addressable retrofit volume.
- Photocell dusk-to-dawn switching:Street and area lighting maintenance contracts specify these mature control solutions for predictable outdoor runtime management.
Market Restraints
- Photodiode substrate qualification costs:REACH compliance burdens are hardening material certification expenses for European market entrants without captive testing infrastructure.
- GaN-on-silicon supply concentration:Vertically integrated capacity holders absorb certification costs internally, squeezing non-integrated component suppliers.
- Response time floor for real-time dimming:Spectral detection across 400-1100 nm ranges imposes fundamental physical limits on sensor latency reduction.
Strategic Opportunities
- Time-of-flight proximity module convergence:Ambient light and motion detection integration into single optoelectronic packages reduces luminaire BOM complexity.
- Cyber-resilience certification pre-emption:Early alignment with emerging connected lighting network standards creates first-mover positioning before jurisdictional fragmentation.
- Electrical contractor specification relationships:Deep channel partnerships in North American commercial construction anchor premium-grade portfolio placement.
Industry Challenges
- Multi-jurisdiction certification timelines:EPA Energy Star, ASHRAE 90.1, and emerging cyber standards create overlapping compliance windows that delay product rollouts.
- Legacy building automation integration:BACnet and proprietary protocol fragmentation forces custom gateway development for unified sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lighting Control Sensors Market |
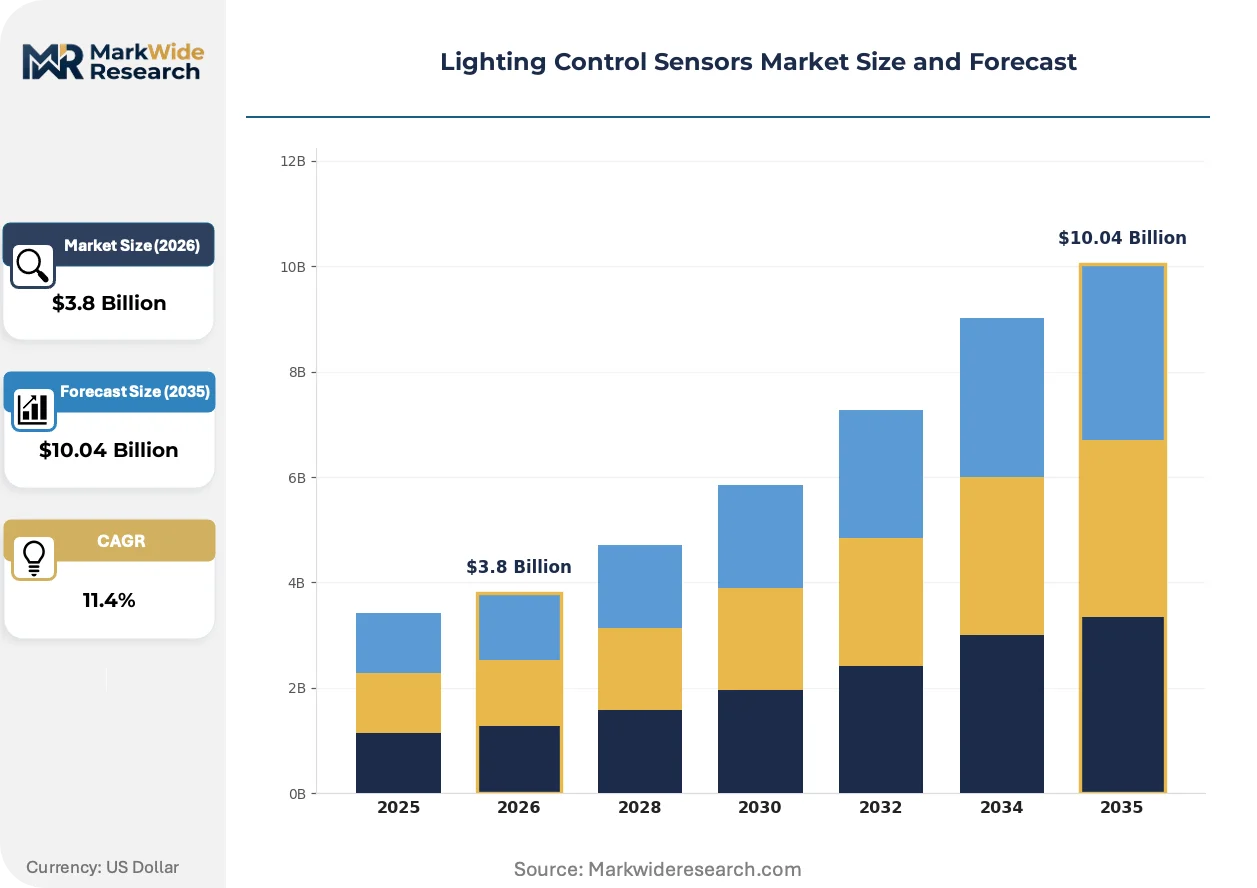
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Occupancy Sensors, Ambient Light Sensors, Motion Sensors, Photocells Technology: Wired, Wireless, Hybrid, Zigbee Application: Commercial Buildings, Residential Spaces, Industrial Settings, Outdoor Lighting End User: Contractors, Building Owners, Facility Managers, Homeowners |
| Companies Covered | ams-OSRAM AG, STMicroelectronics N.V., Broadcom Inc., Vishay Intertechnology Inc., Analog Devices, Inc., Sharp Corporation, Signify Holding, Acuity Brands, Inc., Legrand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lighting Control Sensors Market Evolving Landscape
Sensor architecture is fragmenting into interoperable subsystems that decouple detection, processing, and communication functions, enabling mix-and-match procurement for retrofit contractors facing heterogeneous building conditions.
Time-of-flight proximity modules are modularizing across specification-grade luminaire portfolios. Tier-one lighting manufacturers are adopting these integrated ambient-plus-motion packages for new commercial construction above ASHRAE 90.1 threshold floor areas. This modularization is compressing development cycles for multi-sensor arrays while reducing field calibration labor.
REACH substance restrictions are recasting photodiode supply chains across European sensor assembly operations. ECHA candidate list updates are forcing substrate requalification for housings and optical components. German municipal efficiency ordinances are tightening fastest, driving specification activity for pre-certified component bundles.
Utility incentive program structures are reshaping buyer procurement mathematics for commercial retrofits. Facility managers in intermittently occupied spaces now model sensor payback against labor cost avoidance rather than energy savings alone. This behavioral pivot concentrates demand in Germany and select US states with performance-based rebate frameworks.
Lighting Control Sensors Market Segmentation
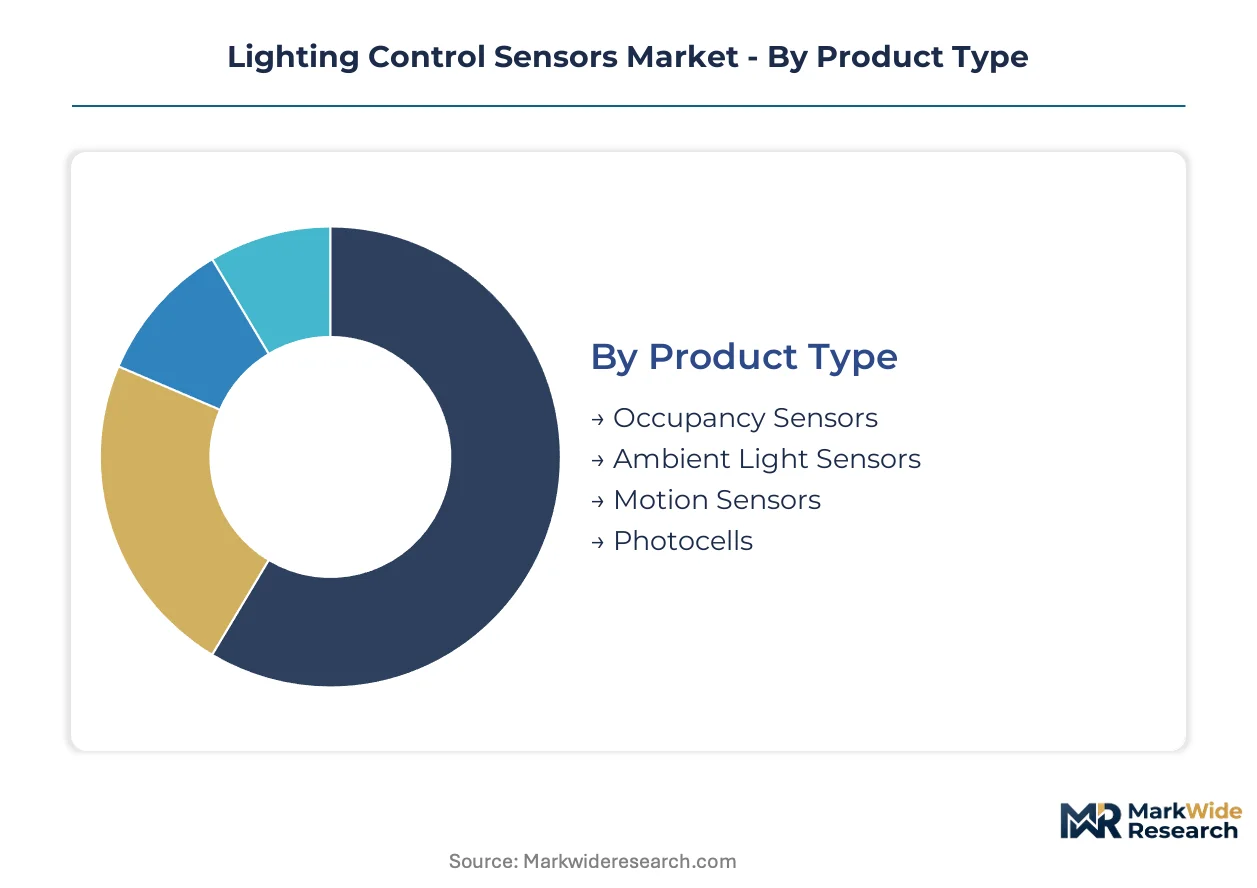
Sensor deployment economics vary sharply across building vintages and control architectures. Procurement patterns split between specification-grade new construction and retrofit-driven replacement cycles, each demanding distinct technical configurations.
Product Type:
Capital intensity concentrates in multi-sensor arrays requiring precision calibration, while single-function units minimize upfront fixture integration costs.
- Occupancy Sensors:Passive infrared and ultrasonic detection elements trigger luminaire activation upon spatial disturbance detection. Demand clusters in German office retrofits where municipal efficiency ordinances mandate automatic shutoff compliance.
- Ambient Light Sensors:Photodiode arrays measuring illuminance across 400-1100 nm spectral ranges enable continuous dimming response to daylight ingress. These dominate ASHRAE 90.1-compliant new construction above threshold floor areas in US commercial buildings.
- Motion Sensors:Microwave and PIR hybrid architectures detect kinetic displacement for corridor and parking structure applications.
- Photocells:Cadmium sulfide or silicon photodiode elements provide simple dusk-to-dawn switching for street lighting maintenance contracts.
Occupancy sensors absorb the bulk of installed capacity; ambient light sensors are expanding most quickly.
Technology:
Installation labor cost differentials between conduit-dependent and conduit-free architectures reshape project economics across building ages.
- Wired:Line-voltage and low-voltage hardwired connections deliver deterministic latency under 50 milliseconds for specification-grade dimming control. These retain dominance in new US commercial construction where electrical contractors embed infrastructure during rough-in phases.
- Wireless:Battery-powered or energy-harvesting radio nodes eliminate conduit installation in historic European building adaptations where fabric preservation restricts invasive work.
- Hybrid:Dual-path architectures combine wired backbone reliability with wireless endpoint flexibility for phased retrofit rollouts.
- Zigbee:Mesh networking protocol stacks enable interoperable commissioning across multi-vendor lighting management platforms.
Wired infrastructure retains the largest installed base; wireless deployments are gaining share fastest.
Application:
Building automation integration complexity scales with square footage and occupancy variability, concentrating sensor density in intermittently used zones.
- Commercial Buildings:Open-plan offices, conference rooms, and circulation paths require granular zone control for energy code compliance. German facility managers drive specification volume through performance-based contracting frameworks.
- Residential Spaces:Single-family and multifamily units deploy simpler vacancy sensors for utility rebate qualification. These installations concentrate in US states with structured incentive programs.
- Industrial Settings:High-bay manufacturing floors and warehousing operations demand ruggedized housings with extended temperature ranges.
- Outdoor Lighting:Street, area, and facade luminaires specify photocell controls for predictable runtime management under municipal maintenance contracts.
Commercial buildings absorb the bulk of specification activity; outdoor lighting is climbing the fastest.
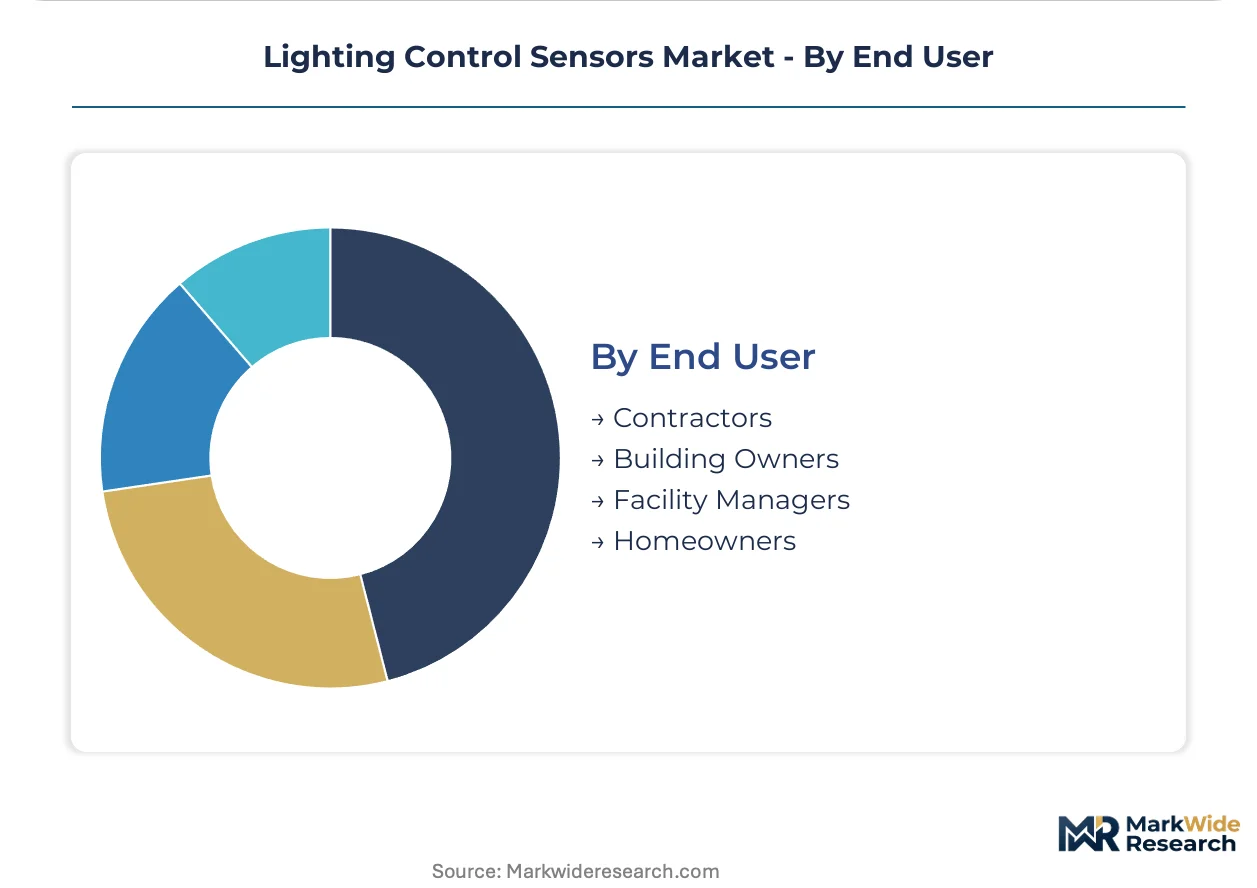
End User:
Decision authority fragments between capital budget holders and operating expense managers, complicating procurement alignment across organizational boundaries.
- Contractors:Electrical and lighting installation firms specify sensor bundles based on labor efficiency and code compliance reliability. These stakeholders anchor Acuity Brands' channel strategy in North American construction markets.
- Building Owners:Asset holders prioritize capital cost minimization and long-term energy savings documentation for green building certification.
- Facility Managers:Operating budget controllers drive retrofit demand through payback-focused business cases combining utility incentives with maintenance labor avoidance.
- Homeowners:Retail and direct-install channels serve residential replacement and renovation demand with plug-and-play sensor modules.
Facility managers absorb the bulk of retrofit procurement volume; contractors are expanding their specification influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Germany drive the densest specification activity for occupancy and ambient light sensors, with municipal efficiency ordinances converting energy code compliance into mandatory procurement rather than optional efficiency investment.
Germany
German office retrofits absorb the bulk of European sensor deployment volume as facility managers pursue payback periods below 36 months. The EU Green Deal's Energy Performance of Buildings Directive mandates automatic daylight-responsive controls in commercial renovations above threshold floor areas. Bavaria's municipal efficiency ordinances are tightening fastest, driving wholesale upgrades across aging Munich and Nuremberg office stock.
United States
US commercial construction specifies wired sensor architectures during rough-in phases where electrical contractors embed deterministic low-voltage infrastructure. EPA Energy Star specifications and ASHRAE Standard 90.1 embed automatic controls into baseline code for new buildings. Specification-grade procurement concentrates in Texas and California where utility incentive programs compress payback thresholds through performance-based rebate frameworks.
China
Chinese manufacturing clusters supply photodiode substrates and optoelectronic components for downstream sensor assembly operations. MIIT industrial standards and GB certification requirements govern electromagnetic compatibility for connected lighting networks. The Yangtze River Delta region anchors domestic production capacity, with Shanghai and Suzhou facilities serving both export markets and local smart city deployments.
Japan
Japanese industrial facilities demand ruggedized sensor housings with extended temperature ranges for high-bay manufacturing floors. METI energy efficiency guidelines incentivize occupancy-based controls in commercial and industrial sectors. The Kansai region around Osaka hosts precision optoelectronics manufacturing, with local producers supplying time-of-flight modules for integrated ambient-plus-motion detection.
United Kingdom
UK historic building adaptations favor wireless sensor architectures where fabric preservation restricts invasive conduit installation. The country's building regulations mandate automatic lighting controls in new commercial construction above specified floor areas. London's commercial retrofit market leads specification volume, with facility managers in aging City and West End office stock pursuing energy code compliance through battery-powered radio nodes.
Lighting Control Sensors Market Competitive Landscape
European producers anchor the premium-tier sensor segment; Asian component specialists hold cost-optimized positions in photodiode substrate supply. The vendor base splits between vertically integrated optoelectronics conglomerates and modular subsystem suppliers. Two strategic archetypes dominate: captive GaN-on-silicon capacity holders who absorb REACH compliance internally, and fabless design houses who outsource substrate qualification. Competitive moves concentrate on backward integration into photodiode manufacturing and pre-emptive alignment with emerging cyber-resilience certification standards.
Within the integrated optoelectronics tier, ams-OSRAM AG and STMicroelectronics N.V. exemplify capacity holders who internalize material certification burdens. Acuity Brands, Inc. anchors the specification-grade luminaire channel through deep relationships with North American electrical contractors. These three occupy positions that span component supply through finished sensor system deployment.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| STMicroelectronics N.V. |
| Broadcom Inc. |
| Vishay Intertechnology Inc. |
| Analog Devices, Inc. |
| Sharp Corporation |
| Signify Holding |
| Acuity Brands, Inc. |
| Legrand |
| Others |
Value Network & Pricing Analysis
GaN-on-silicon wafer transitions are simultaneously compressing photodiode substrate costs and concentrating supply among vertically integrated optoelectronics producers who internalize REACH certification burdens. This technology shift rewards scale players while squeezing fabless design houses into narrower component niches.
Pricing Analysis
Volume-versus-margin splits separate specification-grade luminaire channels from commodity retrofit bundles. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and after-sales calibration support. Cost compression in economy-tier photocells is intensifying because Chinese substrate suppliers are expanding silicon photodiode capacity. Facility managers in German municipal retrofits exhibit the highest price sensitivity, while North American electrical contractors anchoring Acuity Brands relationships prioritize specification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for REACH-compliant photodiode housings are forcing European sensor assemblers to qualify secondary substrate suppliers beyond their primary German or Austrian vendors. Manufacturing concentrates in China for silicon wafer production, Germany for precision optical component finishing, and Japan for time-of-flight module assembly. Raw material dependencies include high-purity silicon ingots, gallium nitride epitaxy materials, and RoHS-compliant housing polymers. Single-source vulnerability runs through GaN-on-silicon capacity held by ams-OSRAM and STMicroelectronics. Distribution runs through electrical contractor channels in North America and facility management procurement frameworks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant component suppliers as regulatory qualification costs force smaller photodiode vendors into exit or acquisition. The certification burden acts as a structural filter eliminating undercapitalized competitors.
For Market Incumbents: To counter fabless design house encroachment into wireless sensor modules, incumbents should deepen backward integration into photodiode substrate manufacturing and pre-emptively align with emerging cyber-resilience certification standards. Captive GaN-on-silicon capacity in European facilities absorbs REACH compliance costs that would otherwise erode margin. Channel control through electrical contractor specification relationships in Texas and California anchors premium-grade placement against price-driven competition.
For New Entrants and Emerging Players: Historic building facility managers in the United Kingdom represent an underserved buyer archetype demanding battery-powered wireless architectures where fabric preservation restricts conduit installation. White-space targets include Zigbee-enabled multi-sensor arrays for phased retrofit rollouts and pre-certified component bundles for German municipal efficiency ordinances. A go-to-market angle through lighting maintenance contractors rather than electrical contractors bypasses entrenched specification relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to vertically integrated optoelectronics conglomerates seeking REACH-compliant European production capacity. Long-term viability favors component suppliers with captive substrate qualification infrastructure over fabless design houses exposed to supply concentration risk. The signal to watch is ECHA candidate list expansion pace, which would accelerate requalification costs and trigger acquisition premiums for pre-certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodiode Manufacturing | Captive GaN-on-silicon capacity absorbs REACH certification burdens internally, insulating margin from regulatory cost spikes. |
| Cyber-Resilience Certification Pre-emption | Early alignment with emerging connected lighting network standards creates first-mover positioning before jurisdictional fragmentation delays competitors. |
| Wireless Sensor Architecture Development | Battery-powered radio nodes unlock historic building retrofits where conduit installation proves prohibitive, expanding addressable volume. |
| Time-of-Flight Module Convergence | Integrated ambient-plus-motion detection packages reduce luminaire BOM complexity and compress field calibration labor for contractors. |
| Electrical Contractor Channel Deepening | Specification-grade portfolio placement through North American contractor relationships anchors premium pricing against commodity competition. |
Research Methodology
Independent corroboration across facility manager interviews, electrical contractor procurement records, and optoelectronics component supplier disclosures underwrites the qualitative findings in this study. Primary fieldwork engaged lighting control system specifiers, municipal efficiency program administrators, and luminaire manufacturer product managers across Germany, the United States, and the United Kingdom. Secondary validation drew from ECHA substance restriction updates, EPA Energy Star specification documents, ASHRAE Standard 90.1 compliance databases, and utility incentive program filings. Bottom-up sensor deployment estimates triangulated against top-down building stock renovation projections.
Comparable-period anchoring linked projection assumptions to verified installation volumes from completed commercial retrofit cycles and new construction permitting data. The analytical framework modeled demand across product type, technology architecture, application setting, and end-user decision authority throughout the forecast period. CAGRs derived from segment-level growth trajectories weighted by regulatory mandate implementation schedules and utility incentive program structures. Industry-specific forecast inputs included EU Green Deal building renovation mandate compliance timelines and German municipal efficiency ordinance tightening trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA candidate list expansion, cyber-resilience standard fragmentation, and wireless protocol interoperability developments. Deviation in REACH substance restriction scope or implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Tip Location Devices Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Latin America Lidar Market