
 Global Space Sensors and Actuators Market | 2026-2036
Global Space Sensors and Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Space Sensors and Actuators Market Intelligence
The European Cooperation for Space Standardization (ECSS) qualification process is redrawing the competitive landscape for space-rated components. Moog Inc. specializes in precision motion control systems, particularly for satellite steering and deployment mechanisms. Honeywell International Inc. leverages its extensive aerospace electronics portfolio to offer integrated sensor and navigation solutions. Meanwhile, Safran differentiates through its expertise in high-reliability actuators for propulsion and flight control systems in launch vehicles.
Space sensors and actuators are devices critical for a spacecraft's operation, converting electrical signals into physical measurements or mechanical motion. These components must function under extreme conditions, requiring high radiation tolerance and wide thermal operating ranges. The adoption of MEMS technology is enabling smaller, lighter components, particularly for accelerometers and gyroscopes used in small satellites. Demand from satellite navigation and Earth observation applications continues to drive the need for highly accurate and reliable sensor packages.
Component market access is governed by stringent quality and reliability standards, such as the AS9100 framework for aerospace. Regulatory bodies including the US Federal Aviation Administration and the European Space Agency mandate rigorous testing and validation for all flight-critical hardware. The key strategic decision for satellite manufacturers is whether to develop these critical components in-house or to rely on a specialized, qualified supply chain.
Market Dynamics
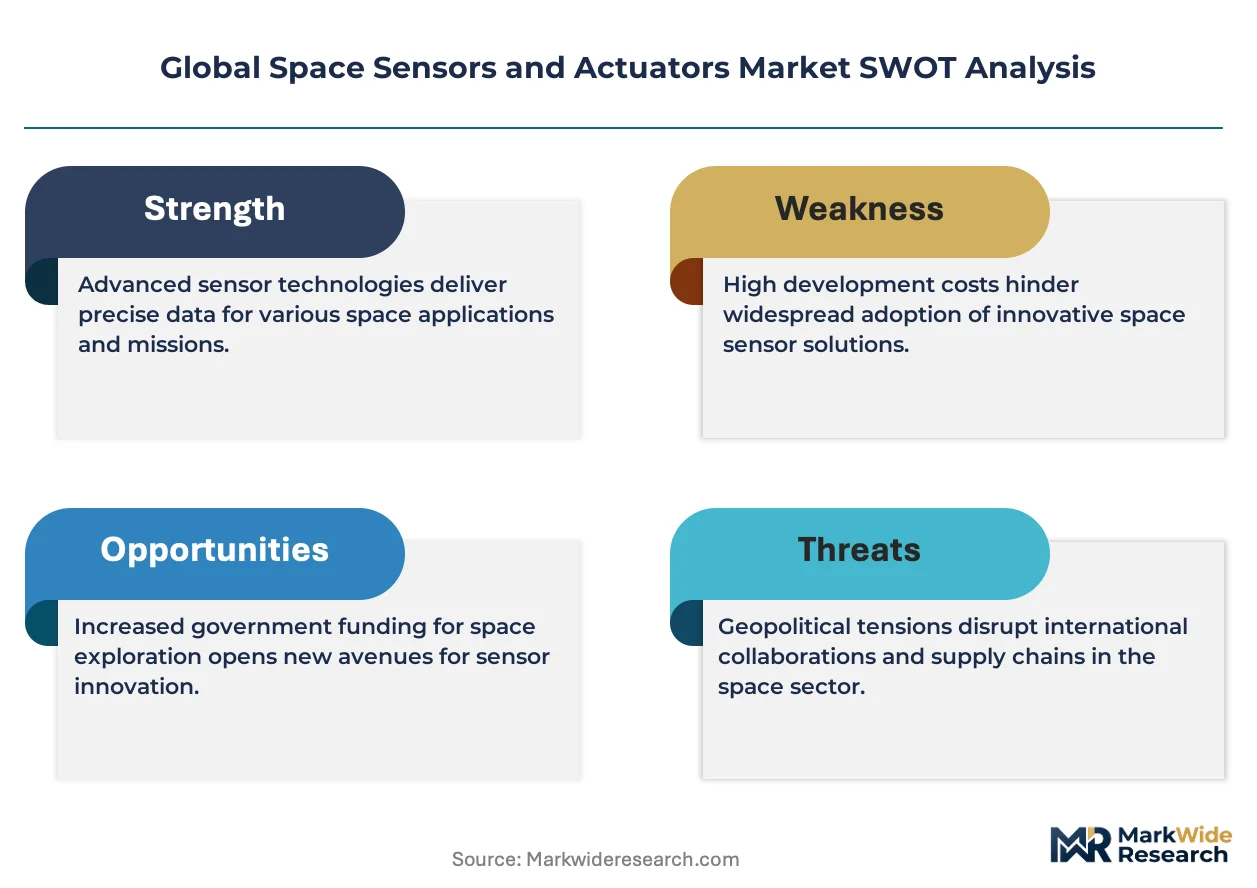
The fundamental market dynamic is the tension between the stringent reliability requirements for space-qualified hardware and the cost-reduction pressures from the commercial satellite constellation sector. This creates a bifurcated market for both high-end, bespoke components and volume-produced, "good enough" systems.
Growth Catalysts
- Large-Scale Constellations:The deployment of massive satellite constellations for global telecommunications and Earth observation is creating unprecedented volume demand for standardized sensors and actuators, moving beyond single-unit government projects.
- MEMS Technology Advancement:Micro-Electro-Mechanical Systems (MEMS) are enabling the miniaturization of components like gyroscopes and accelerometers, which is critical for the burgeoning small satellite and CubeSat markets.
- National Space Programs:Government-led initiatives in emerging space economies, such as India's PLI scheme for manufacturing and space policy directives in the United Arab Emirates, are fostering domestic supply chain development and component demand.
Market Restraints
- Qualification Costs and Timelines:The extensive testing and documentation required to achieve space-grade qualifications, such as those defined by the European Cooperation for Space Standardization (ECSS), create high barriers to entry and long lead times.
- Radiation Hardening Expense:Designing and manufacturing electronics that can withstand the harsh radiation environment of space adds significant cost and complexity, limiting the use of cheaper commercial off-the-shelf (COTS) components.
- Limited Supplier Base:The specialized nature of space-rated component manufacturing results in a concentrated supply chain, creating potential bottlenecks and limited negotiation power for satellite builders on critical parts.
Strategic Opportunities
- In-Orbit Servicing:The emerging field of in-orbit servicing, assembly, and manufacturing (ISAM) will require novel, highly reliable robotic actuators, grappling systems, and advanced proximity sensors, opening a new application segment.
- Sensor Fusion Software:Developing advanced software and AI algorithms that fuse data from multiple low-cost sensors to achieve high-fidelity navigation and attitude control presents a significant value-add opportunity.
- Standardized Component Modules:Offering pre-integrated and pre-qualified sensor and actuator modules can reduce design complexity and time-to-market for new satellite manufacturers, particularly in the university and startup ecosystem.
Industry Challenges
- Specialized Skills Gap:A persistent shortage of engineers with the cross-disciplinary expertise in radiation physics, materials science, and electronics required for space component design is a significant operational hurdle.
- Supply Chain Traceability:Ensuring full traceability and counterfeit prevention for electronic sub-components throughout a global supply chain is a complex and costly compliance challenge, mandated by frameworks like AS9100.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Space Sensors and Actuators Market |
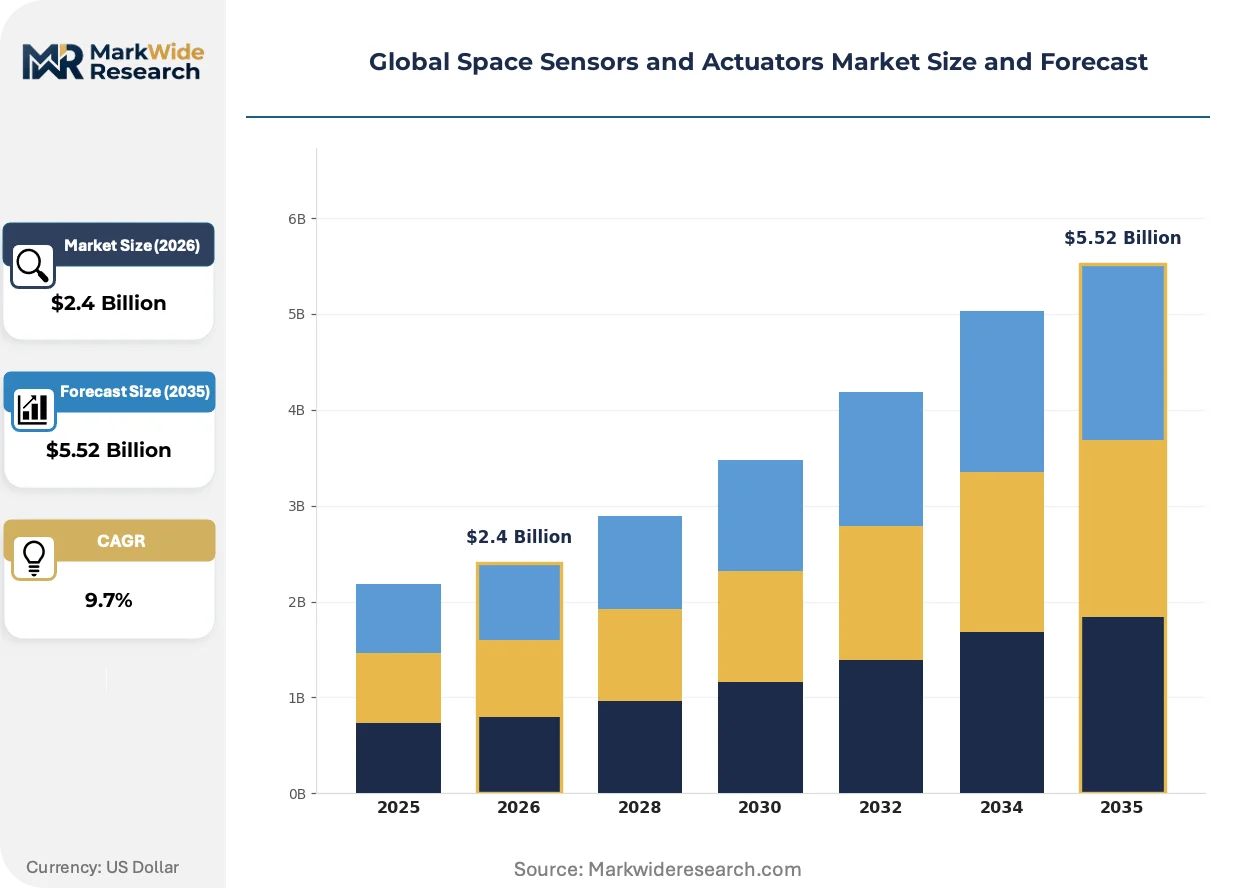
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gyroscopes, Accelerometers, Magnetometers, Pressure Sensors, Temperature Sensors Technology: MEMS, Fiber Optic, Piezoelectric, Capacitive, Inductive Application: Satellite Navigation, Space Probes, Earth Observation, Space Telescopes, Space Stations End User: Space Agencies, Satellite Manufacturers, Research Laboratories, Defense Organizations |
| Companies Covered | Moog Inc., RTX Corporation, Honeywell International Inc., Texas Instruments Incorporated, Ametek Inc., Teledyne Technologies Incorporated, Safran, RUAG Group, Airbus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Space Sensors and Actuators Market Strategic Shifts & Innovations
Innovation is being driven by the dual needs of the space industry: reducing the cost and lead time for commercial constellations while simultaneously pushing the performance envelope for scientific and defense missions. This is leading to new component architectures and business models.
Integrated Inertial Measurement Units (IMUs), which combine accelerometers, gyroscopes, and sometimes magnetometers, are a key product evolution. Manufacturers of small satellites and CubeSats are rapidly adopting these modules to conserve critical volume and mass. This trend is decomposing the traditional component sourcing model, where separate sensors were procured from multiple specialist vendors and integrated by the satellite prime contractor.
Regulatory discussions around space traffic management and debris mitigation are influencing hardware requirements. International proposals for mandatory de-orbiting capabilities at a satellite's end-of-life directly impact design. This affects operators of large Low Earth Orbit (LEO) constellations most acutely, as they must now incorporate reliable actuators and systems for controlled reentry into their platform architecture and cost models.
A notable behavioral shift involves satellite developers moving away from traditional procurement based on datasheets toward demanding in-orbit heritage or flight-proven hardware. This disrupts the established process where components were selected based on specifications alone, giving an advantage to suppliers who can offer "fly-before-you-buy" programs or have components already operating in space. This change is most pronounced in the competitive commercial remote sensing sector in the United States and Europe.
Global Space Sensors and Actuators Market Segmentation
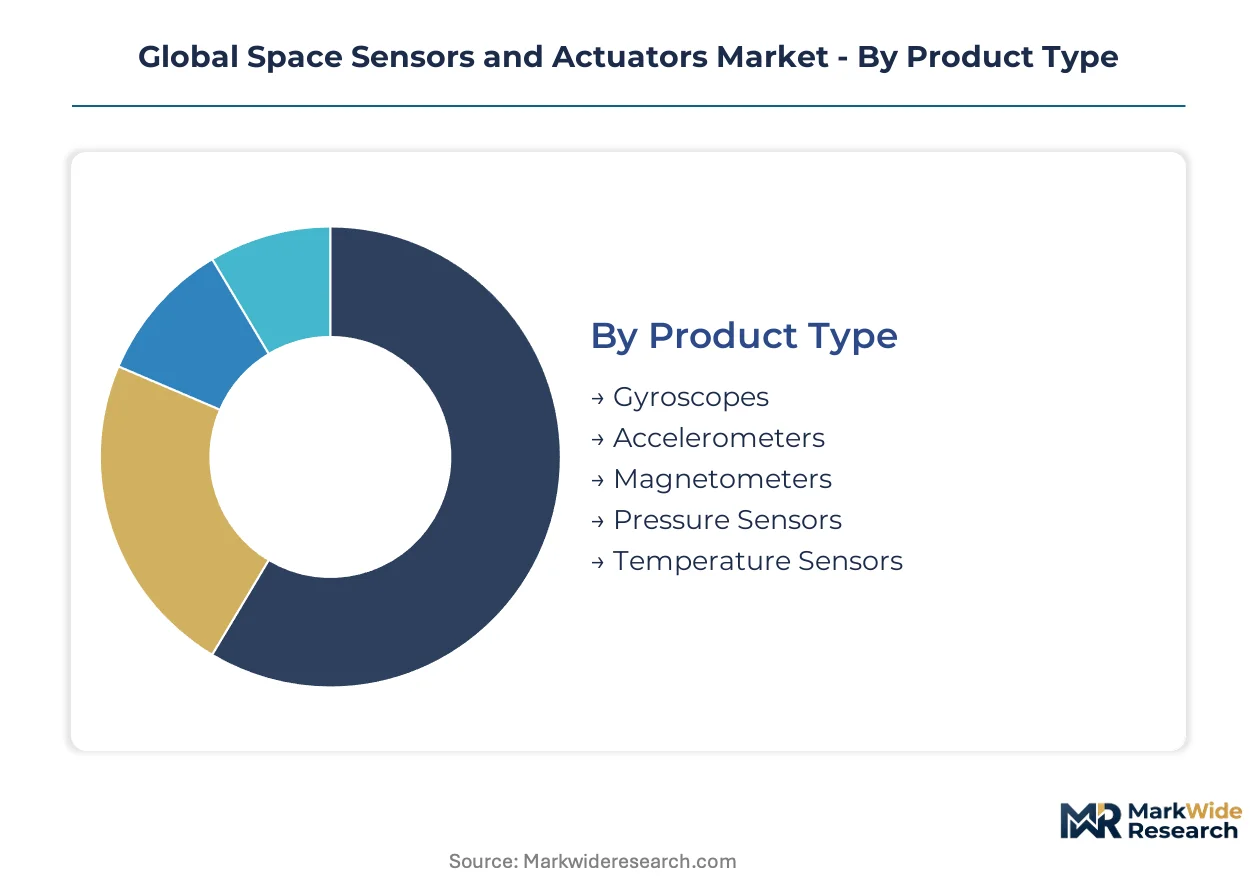
The space sensors and actuators market segments across critical component types, underlying technologies, diverse applications, and distinct end-user categories. Understanding these divisions illuminates where value accrues and how technological shifts impact procurement strategies for satellite manufacturers and space agencies globally.
Product Type:
Margin pools within the product type category concentrate on precision and radiation-hardened components that meet stringent space-grade qualifications.
- Gyroscopes:These devices measure angular velocity, critical for spacecraft attitude control and navigation, especially in complex orbital maneuvers. Demand from small satellite constellations in Earth orbit and deep space probes continues to drive innovation in miniaturization.
- Accelerometers:Accelerometers detect linear acceleration, providing essential data for trajectory correction, vibration monitoring, and inertial navigation systems. Miniaturized MEMS-based accelerometers are increasingly vital for CubeSats and other compact spacecraft platforms.
- Magnetometers:Magnetometers measure magnetic field strength and direction, used for attitude determination and magnetic field mapping in various orbital missions.
- Pressure Sensors:These sensors monitor pressure levels within propulsion systems, fuel tanks, and environmental control systems, ensuring operational safety and efficiency.
- Temperature Sensors:Temperature sensors provide crucial thermal data for component health monitoring, thermal management, and payload operation across extreme space environments.
The dominant share belongs to Gyroscopes, while Accelerometers are closing the gap fastest.
Technology:
Supply concentration for space sensors and actuators is shifting towards advanced manufacturing techniques that enable miniaturization and enhanced performance.
- MEMS:Micro-Electro-Mechanical Systems (MEMS) technology enables the fabrication of miniature, lightweight sensors like accelerometers and gyroscopes on silicon wafers. This technology is critical for reducing mass and volume in small satellite platforms, particularly for LEO constellations.
- Fiber Optic:Fiber optic sensors leverage optical fibers to measure physical parameters such as temperature, strain, and pressure with high immunity to electromagnetic interference. These sensors offer precision and reliability in radiation-rich environments, supporting scientific and defense missions.
- Piezoelectric:Piezoelectric sensors convert mechanical stress into electrical charge, commonly used in accelerometers and vibration sensors due to their robust and self-generating nature.
- Capacitive:Capacitive sensors detect changes in capacitance, often employed for displacement, pressure, and proximity sensing in various spacecraft subsystems.
- Inductive:Inductive sensors operate on electromagnetic principles, providing robust and non-contact position sensing solutions for actuators and deployment mechanisms.
MEMS technology represents the fastest-growing trajectory, driven by its inherent advantages for small satellite platforms.
Application:
Customer type preferences within applications vary from high-volume standardized components for constellations to bespoke, mission-specific designs for scientific endeavors.
- Satellite Navigation:This application relies on highly precise sensors and actuators for accurate positioning, velocity determination, and timing services for global users. The deployment of new GNSS constellations, including Europe's Galileo and China's BeiDou, drives demand for advanced sensor packages.
- Earth Observation:Sensors and actuators are crucial for high-resolution imaging, atmospheric monitoring, and environmental data collection from orbit. Commercial remote sensing companies in the United States and Europe require robust and reliable pointing mechanisms and sensor platforms.
- Space Probes:Deep space missions and planetary exploration require specialized, radiation-hardened sensors and actuators for extreme environments and long operational lifetimes.
- Space Telescopes:These applications demand ultra-precision actuators for mirror alignment and highly sensitive sensors for scientific data collection in astrophysics.
- Space Stations:Sensors and actuators are integral to environmental control, life support systems, robotic operations, and structural health monitoring on orbital platforms.
Earth Observation is expanding most quickly, driven by commercial and governmental data requirements.
End User:
The maturity of end-user programs dictates procurement cycles, with established space agencies having longer qualification processes compared to agile commercial entities.
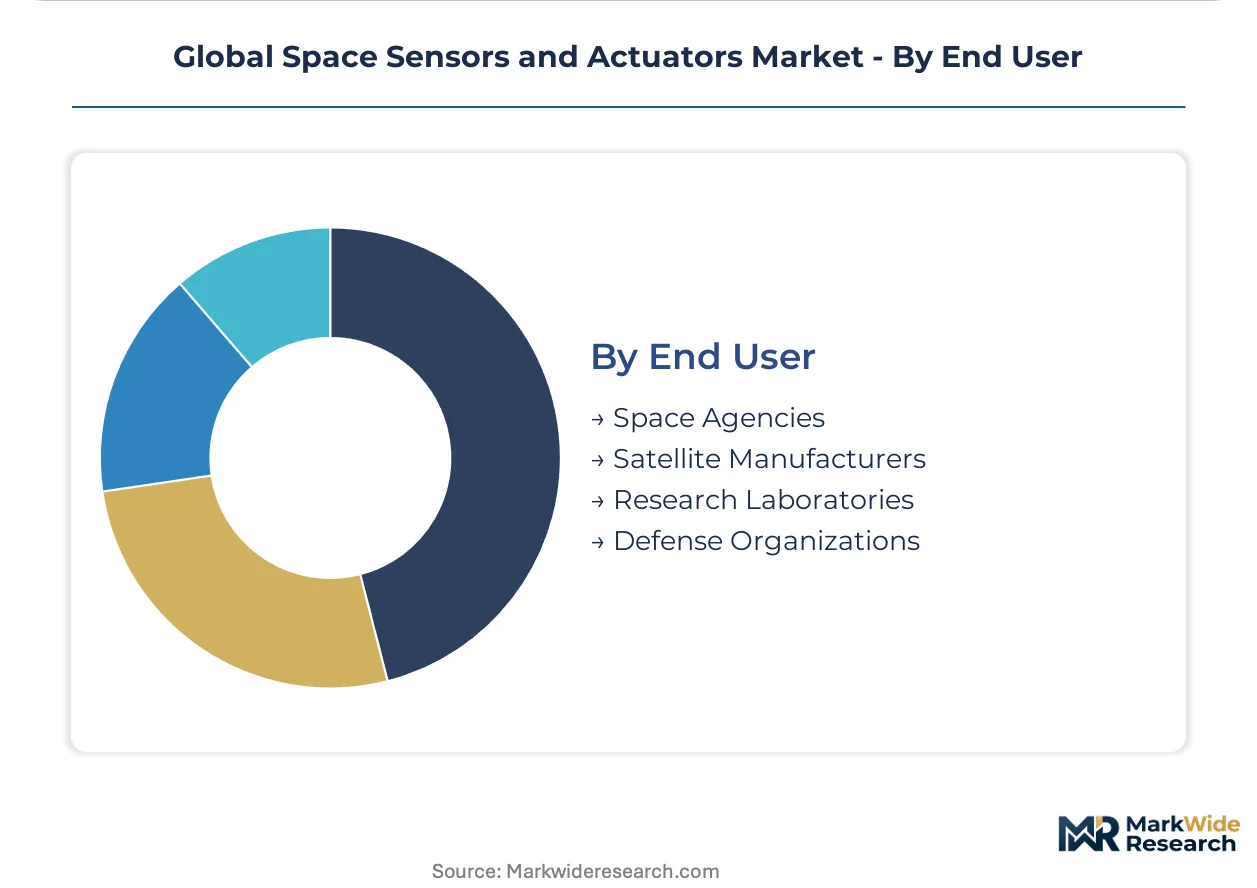
- Space Agencies:Government-funded space agencies, such as NASA and the European Space Agency, procure highly specialized and extensively qualified sensors and actuators for scientific, exploration, and national security missions. These entities prioritize reliability and performance over cost.
- Satellite Manufacturers:These companies design and build satellites for various purposes, sourcing sensors and actuators for communication, Earth observation, and navigation payloads. The growth of large commercial constellations is shifting demand towards more standardized, volume-produced components.
- Research Laboratories:Academic and institutional research laboratories utilize space-rated components for experimental payloads, technology demonstration missions, and scientific investigations.
- Defense Organizations:National defense organizations integrate space sensors and actuators into military satellites for reconnaissance, surveillance, and secure communication applications, demanding high security and resilience.
Space Agencies continue to lead in demand, with Satellite Manufacturers gaining share fastest due to commercial constellation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Established national space program infrastructure underwrites the global demand for space sensors and actuators. This infrastructure provides the foundation for both governmental and commercial space endeavors, requiring advanced components for mission success. Countries with mature space industries and emerging commercial ecosystems drive significant procurement activity for these critical devices. The need for precise navigation and reliable operational data fuels continuous investment in component development.
United States
Demand for space sensors and actuators in the United States is driven by large-scale commercial satellite constellations and defense programs. The US Federal Aviation Administration (FAA) mandates rigorous testing for flight-critical hardware, influencing component design. California's aerospace hubs, including Silicon Valley, concentrate on developing miniaturized and high-performance sensor packages for various missions.
India
India's national space programs and a rapidly expanding commercial space ecosystem are accelerating demand for advanced sensors and actuators. The PLI scheme for manufacturing incentivizes domestic production of space-grade components. Bengaluru's vibrant aerospace sector is fostering innovation in satellite manufacturing and component integration.
France
France significantly contributes to European Space Agency (ESA) missions and maintains a strong satellite manufacturing industry. The European Cooperation for Space Standardization (ECSS) qualification process sets high reliability benchmarks for components. Toulouse, a major aerospace cluster, is a center for satellite design and the integration of advanced sensor and actuator systems.
Germany
Germany's space sector focuses on Earth observation satellites and scientific research missions, requiring highly accurate sensor and actuator solutions. Contributions to the European Space Agency and national research funding support component development. The space industry clusters in Bremen and Munich are known for their expertise in precision engineering and satellite technology.
Japan
Japanese space efforts prioritize satellite navigation systems and scientific exploration, necessitating reliable sensors and actuators. The Ministry of Economy, Trade and Industry (METI) supports advanced manufacturing and space technology development. The Tsukuba Space Center region is a key hub for research and development in space component technologies.
Global Space Sensors and Actuators Market Key Industry Players
Listed leaders compete with private specialists across various tiers of space-grade component manufacturing. The market exhibits a tiered structure, with established aerospace primes and specialized component manufacturers occupying different niches. Strategic partnerships between hardware providers and software developers are common. Technology licensing also plays a role in disseminating advanced component designs across the industry.
Specialists in precision motion control and integrated sensor solutions include Moog Inc., known for its satellite steering mechanisms. Honeywell International Inc. leverages its extensive aerospace electronics portfolio to offer comprehensive navigation solutions for spacecraft. Safran differentiates through its expertise in high-reliability actuators for propulsion and flight control systems within launch vehicles, serving both governmental and commercial clients.
| Leading Market Players |
|---|
| Moog Inc. |
| RTX Corporation |
| Honeywell International Inc. |
| Texas Instruments Incorporated |
| Ametek Inc. |
| Teledyne Technologies Incorporated |
| Safran |
| RUAG Group |
| Airbus |
| Others |
Cost & Logistics Intelligence
Project-based procurement for space-rated components locks in both supply access and price visibility for satellite manufacturers. This structure reflects the specialized nature of space hardware development and qualification.
Pricing Analysis
Volume-discount tiering structures characterize pricing for space sensors and actuators, particularly for high-volume constellation components. Price differentiation stems from ECSS qualification levels, radiation hardening, and customization requirements for specific missions. Pricing softness stems from the cost-reduction pressures exerted by commercial satellite constellation operators seeking standardized components. Space agencies, prioritizing reliability and performance, exhibit lower price sensitivity than commercial satellite manufacturers.
Supply Chain Analysis
Extended lead times for space-qualified components reflect the stringent testing and validation processes mandated by bodies like the US Federal Aviation Administration. Supply concentrates in the United States, France, and Japan, with specialized manufacturers producing precision motion control systems and integrated sensor solutions. The supply chain relies on specialized radiation-hardened semiconductors and high-reliability mechanical parts, creating single-source vulnerability for mission-critical components. Distribution runs through direct sales channels to prime contractors and space agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense as incumbents navigate the increasing viability of advanced sensor fusion software. These algorithms combine data from multiple lower-cost sensors, threatening traditional high-fidelity component sales.
For Market Incumbents: Compound existing expertise in radiation hardening and precision engineering by investing in advanced MEMS technology development. Pursue strategic partnerships with software developers to integrate sensor fusion capabilities, mitigating the threat from lower-cost COTS alternatives. Consolidate market share through rigorous ECSS qualification processes, reinforcing the barrier to entry for new component suppliers.
For New Entrants and Emerging Players: Pre-integrated and pre-qualified sensor and actuator modules represent a service-layer gap where incumbents under-serve the burgeoning small satellite market. Target the university and startup ecosystem with standardized modules that reduce design complexity and time-to-market. Offer "fly-before-you-buy" programs, providing in-orbit heritage to address the demand for flight-proven hardware, particularly in Europe.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated specialists providing critical components for long-duration missions. The space sensors and actuators market offers long-term viability driven by sustained demand for global space infrastructure. Target acquisition candidates specializing in integrated IMUs or high-reliability actuators for in-orbit servicing applications. The signal to watch is the accelerated commercialization of in-orbit servicing, assembly, and manufacturing (ISAM) technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in MEMS R&D | Miniaturization of components reduces mass and volume for small satellite platforms. |
| Secure ECSS Qualification | Achieving European Space Agency standards opens access to high-value governmental and commercial contracts. |
| Develop Sensor Fusion Software | Advanced algorithms enhance navigation and attitude control by combining data from multiple sensors. |
| Offer Standardized Component Modules | Reduces design complexity and accelerates time-to-market for new satellite manufacturers. |
| Form In-Orbit Servicing Partnerships | Positions the company for emerging demand in robotic actuators and advanced proximity sensors. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings for this study. Interviews included satellite manufacturers' engineers, space agency procurement leads, component R&D directors, and commercial constellation operators. Secondary validation leveraged US Federal Aviation Administration reports, European Space Agency publications, and industry technical journals. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Sensitivity analysis underpins the quantitative model, assessing various market scenarios across the analysis window. The analytical framework incorporates segmentation by product type, technology, application, end-user, and regional space program maturity. Compound annual growth rates were derived from historical trends and projected market dynamics. Key inputs included satellite launch cadence and commercial constellation deployment schedules.
Underlying assumptions cover a stable regulatory environment and sustained space investment, with deviation risk concentrated in geopolitical tensions and unexpected technological breakthroughs. Forecasts reflect these assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Micropump Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Nano Positioning System Market