
 France Air Purifier Market | 2026-2036
France Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
France Air Purifier Market Insights
HEPA certification tiers above EN 1822:2009 standards are reorganizing how French buyers evaluate performance against price. Daikin Europe NV leverages its HVAC integration capabilities to anchor commercial contracts across hospital networks. TEQOYA SAS specializes in filterless ionic technology, competing for premium residential spaces where maintenance costs drive switching. Koninklijke Philips N.V. controls broad retail shelf presence through pharmacy and electronics channels, extending brand recognition into smart-connected models.
France air purifiers are electromechanical devices designed to remove particulate matter, volatile organic compounds, and biological contaminants from enclosed air volumes, typically employing fibrous media filtration, adsorbent beds, or ultraviolet germicidal irradiation with rated clean air delivery volumes measured in cubic meters per hour. Their primary purpose spans infection control in clinical settings, allergen reduction in domestic environments, and process protection in light industrial facilities. HEPA Filters and Activated Carbon Filters together occupy the dominant product tier, with UV-C Purifiers representing the fastest-expanding technology segment as healthcare procurement specifications harden. Smart Air Purifiers within the technology dimension are capturing margin pools through subscription filter replenishment and indoor air quality monitoring apps, while Portable units sustain volume leadership across residential and small commercial end users.
ANSES, the EU Ecodesign Directive, and France's RE2020 environmental regulation collectively shape product testing protocols, energy consumption ceilings, and building-integrated ventilation requirements that determine market access. CE marking under the EU AI Act's emerging scope for connected devices will add compliance layers to smart purifier portfolios. Stakeholders must monitor how RE2020's tightening thresholds for new construction will mandate embedded filtration versus standalone unit sales.
Market Dynamics
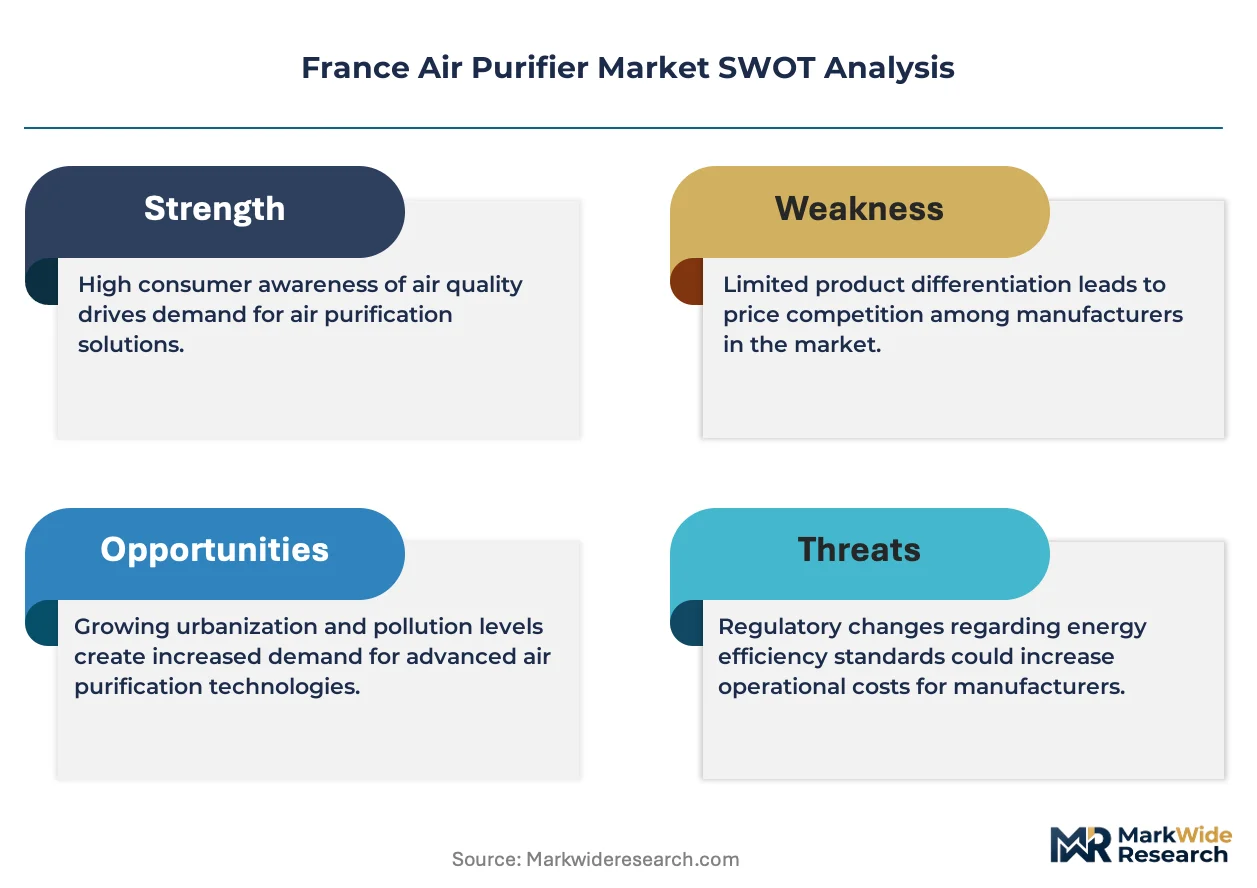
France's air purifier sector faces structural pressure from RE2020 building codes, which mandate embedded filtration in new construction and threaten standalone unit demand across residential and commercial channels.
Growth Catalysts
- ANSES indoor air quality guidelines:Healthcare facilities in Paris and Lyon face mandatory filtration upgrades, accelerating HEPA procurement cycles in hospital networks.
- Île-de-France commercial real estate concentration:Office stock modernization in La Défense and central Paris drives bulk orders for activated carbon systems addressing VOC remediation.
- Filterless ionic technology maturation:Premium residential buyers in Bordeaux and Nice switch from fibrous media to maintenance-reducing alternatives, expanding addressable margin pools.
Market Restraints
- Activated carbon supply concentration:Coconut shell precursor sourcing clusters in Southeast Asian processing hubs, exposing French manufacturers to freight cost volatility and extended lead times.
- EU Ecodesign Directive energy ceilings:Compliance testing for standby power consumption adds six-to-nine month certification delays, compressing product launch windows against Asian competitors.
- Building-integrated HVAC substitution:RE2020-compliant mechanical ventilation with filtration modules captures demand that standalone purifiers previously served in new construction.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur underpenetration:Secondary city residential markets outside Paris show filtration adoption gaps of forty-plus percent against capital region baselines.
- EU AI Act connected device framework:CE marking expansion into algorithmic air quality monitoring creates first-mover advantage for smart purifier portfolios with embedded sensor arrays.
- Pharmacy channel consolidation:Allergen-focused portable units penetrate rural distribution networks previously served only by electronics retailers, capturing seasonal pollen-driven purchase cycles.
Industry Challenges
- EN 1822:2009 testing capacity bottleneck:Accredited French laboratories face twelve-month backlogs for HEPA certification, forcing manufacturers to queue at German or Swiss facilities.
- Legacy building stock integration friction:Nineteenth-century Parisian apartment wiring constraints limit high-CADR unit deployment without electrical infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Air Purifier Market |
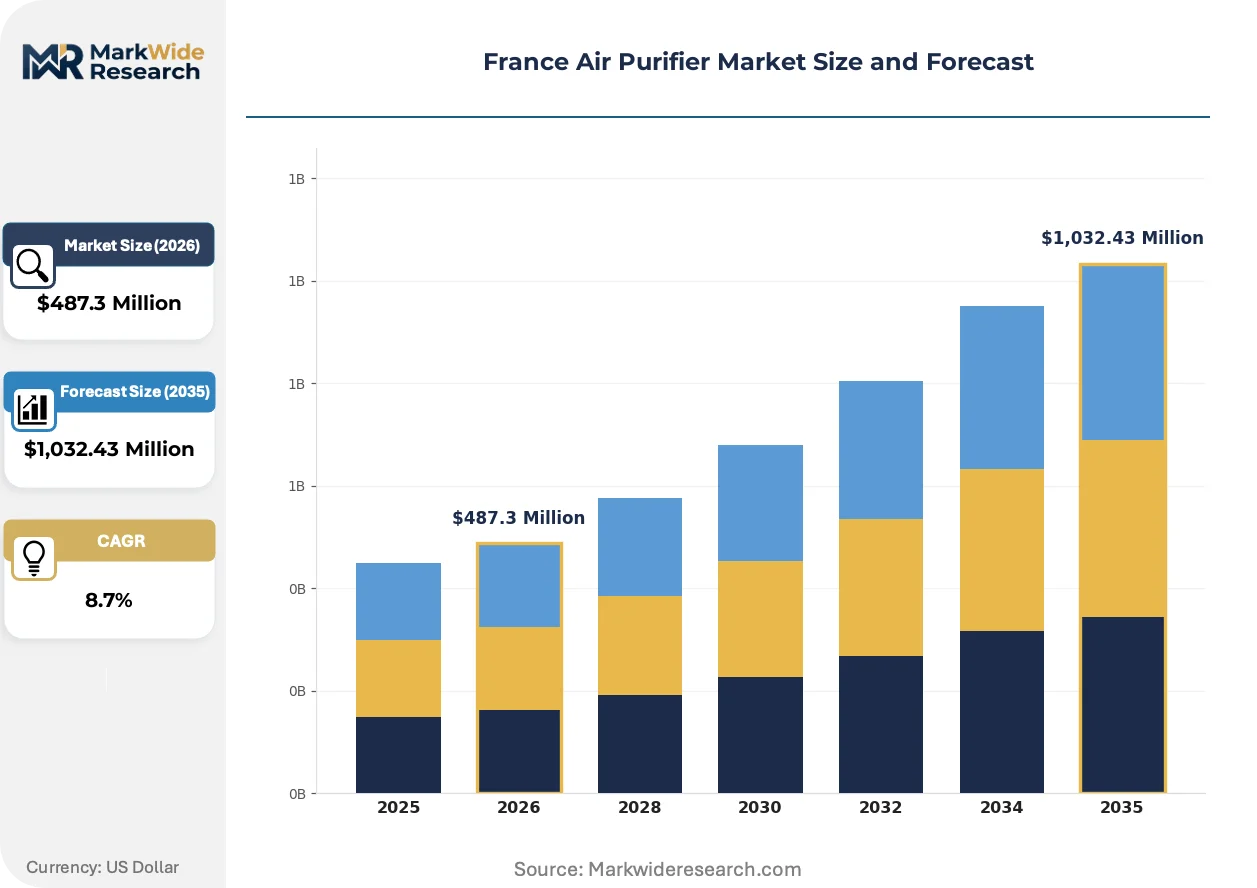
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, UV-C Purifiers, Ozone Generators End User: Residential, Commercial, Industrial, Healthcare Technology: Portable, Fixed, Smart Air Purifiers, Ionic Purifiers Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | JVD SAS, TEQOYA SAS, Koninklijke Philips N.V., Daikin Europe NV, WINIX Europe B.V., NatéoSanté SAS, Sharp Electronics France SA, Panasonic France SAS, Xiaomi Technology France S.A.S., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Air Purifier Market Trends and Innovations
UV-C germicidal irradiation is displacing conventional filtration in clinical procurement specifications, while smart connectivity and filter subscription models restructure residential buyer relationships toward recurring revenue architectures.
Photocatalytic oxidation systems paired with UV-C arrays are displacing standalone HEPA units in French hospital infection control departments. The technology neutralizes biological contaminants without fibrous media replacement burdens. Procurement committees in Assistance Publique-Hôpitaux de Paris networks now specify combined UV-photocatalytic systems for isolation wards, compressing addressable demand for traditional filtration hardware.
France's transposition of the EU Ecodesign Directive imposes standby power limits below two watts for networked air purifiers. Manufacturers must redesign power management circuits or forfeit CE marking eligibility. Smart-connected product lines face disproportionate compliance costs, advantaging incumbents with existing low-power firmware architectures against new market entrants.
Subscription filter replenishment bundled with indoor air quality monitoring apps is capturing residential buyers who previously purchased replacement media through retail channels. This shift concentrates customer lifetime value with original equipment manufacturers. Pharmacy and direct-to-consumer digital platforms in the Île-de-France region show the fastest uptake of bundled service contracts, displacing electronics retailer attachment sales.
France Air Purifier Market Segmentation
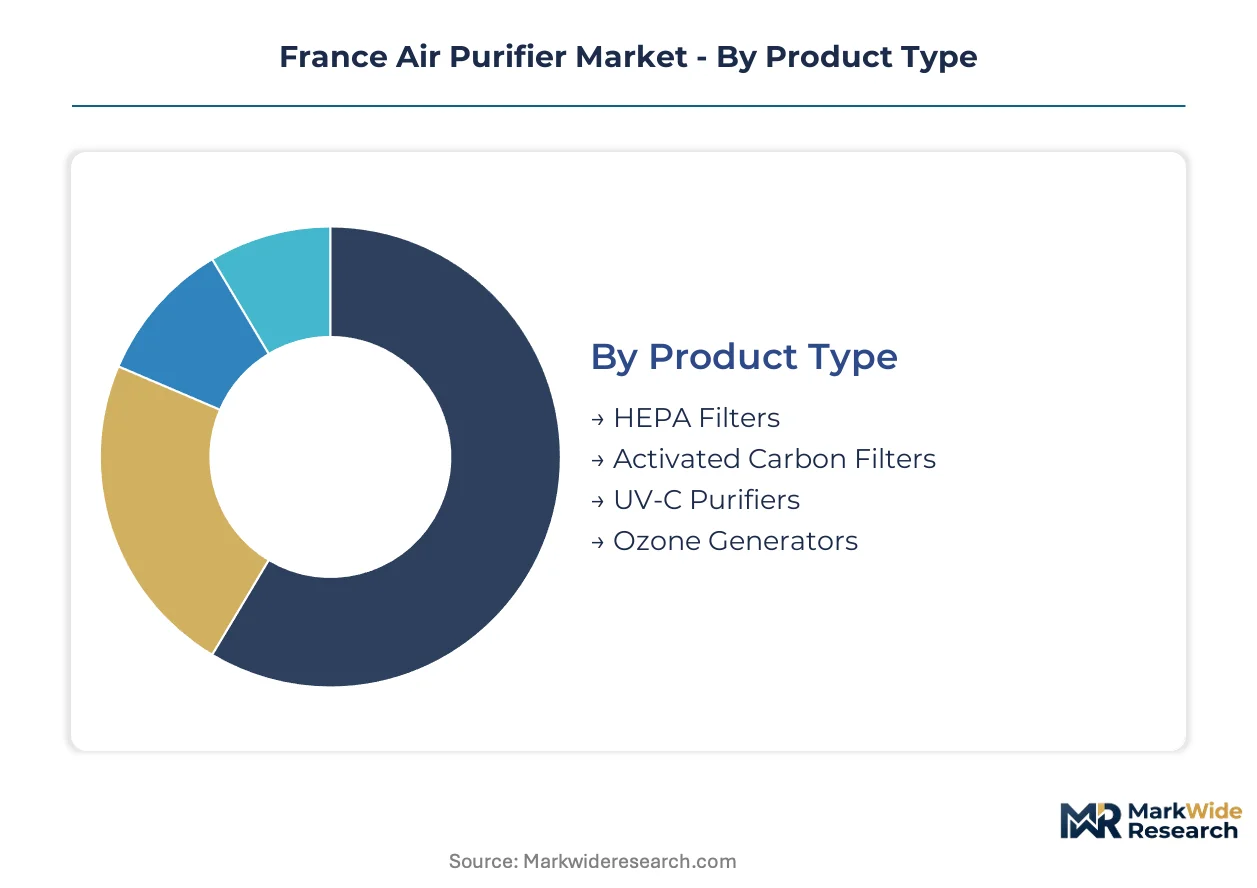
Segmentation in the France air purifier market reveals where RE2020 building codes and ANSES mandates concentrate procurement power. Understanding which configurations face HVAC substitution versus standalone demand expansion shapes portfolio allocation and channel strategy.
Product Type:
HEPA and activated carbon systems confront the steepest substitution pressure from building-integrated ventilation modules, while UV-C technologies escape this threat through clinical specification lock-in.
- HEPA Filters:Fibrous media meeting EN 1822:2009 standards capture particulate matter down to 0.3 microns. Paris hospital networks and Île-de-France commercial real estate drive bulk procurement despite twelve-month laboratory certification backlogs.
- Activated Carbon Filters:Adsorbent beds derived from coconut shell precursors target volatile organic compound remediation. La Défense office modernization projects sustain demand even as Southeast Asian supply concentration exposes manufacturers to freight volatility.
- UV-C Purifiers:Germicidal irradiation neutralizes biological contaminants without media replacement. Assistance Publique-Hôpitaux de Paris specifies combined UV-photocatalytic arrays for isolation wards.
- Ozone Generators:Electrochemical oxidation systems face ANSES safety scrutiny limiting residential deployment.
HEPA Filters anchor the volume base while UV-C Purifiers gain share at the steepest rate.
End User:
Cost tier stratification separates premium healthcare specification from price-sensitive residential procurement.
- Residential:Paris and Lyon households upgrade filtration amid tightening indoor air quality mandates. Pharmacy channel consolidation captures seasonal pollen-driven purchase cycles in rural distribution networks.
- Commercial:La Défense and central Paris office stock modernization drives activated carbon bulk orders for VOC remediation.
- Industrial:Light manufacturing facilities in Bordeaux and Nice deploy process protection systems.
- Healthcare:ANSES guidelines mandate filtration upgrades across Paris and Lyon hospital networks, accelerating HEPA procurement cycles.
Residential commands absolute unit volume while Healthcare delivers the highest margin per installation.
Technology:
Application context determines whether portability, fixed installation, or connectivity features capture buyer preference.
- Portable:Electromechanical units sustain volume leadership across residential and small commercial end users. Seasonal allergen reduction in domestic environments drives replacement cycles.
- Fixed:Permanent installation systems integrate with mechanical ventilation infrastructure. RE2020-compliant new construction captures demand previously served by standalone units.
- Smart Air Purifiers:Networked devices with indoor air quality monitoring apps restructure buyer relationships toward subscription filter replenishment. EU Ecodesign Directive standby power limits below two watts impose redesign costs.
- Ionic Purifiers:Filterless technology from TEQOYA SAS and competitors reduces maintenance burdens for premium residential buyers in Bordeaux and Nice.
Portable units dominate absolute shipments while Smart Air Purifiers expand most quickly through pharmacy and direct-to-consumer digital platforms.
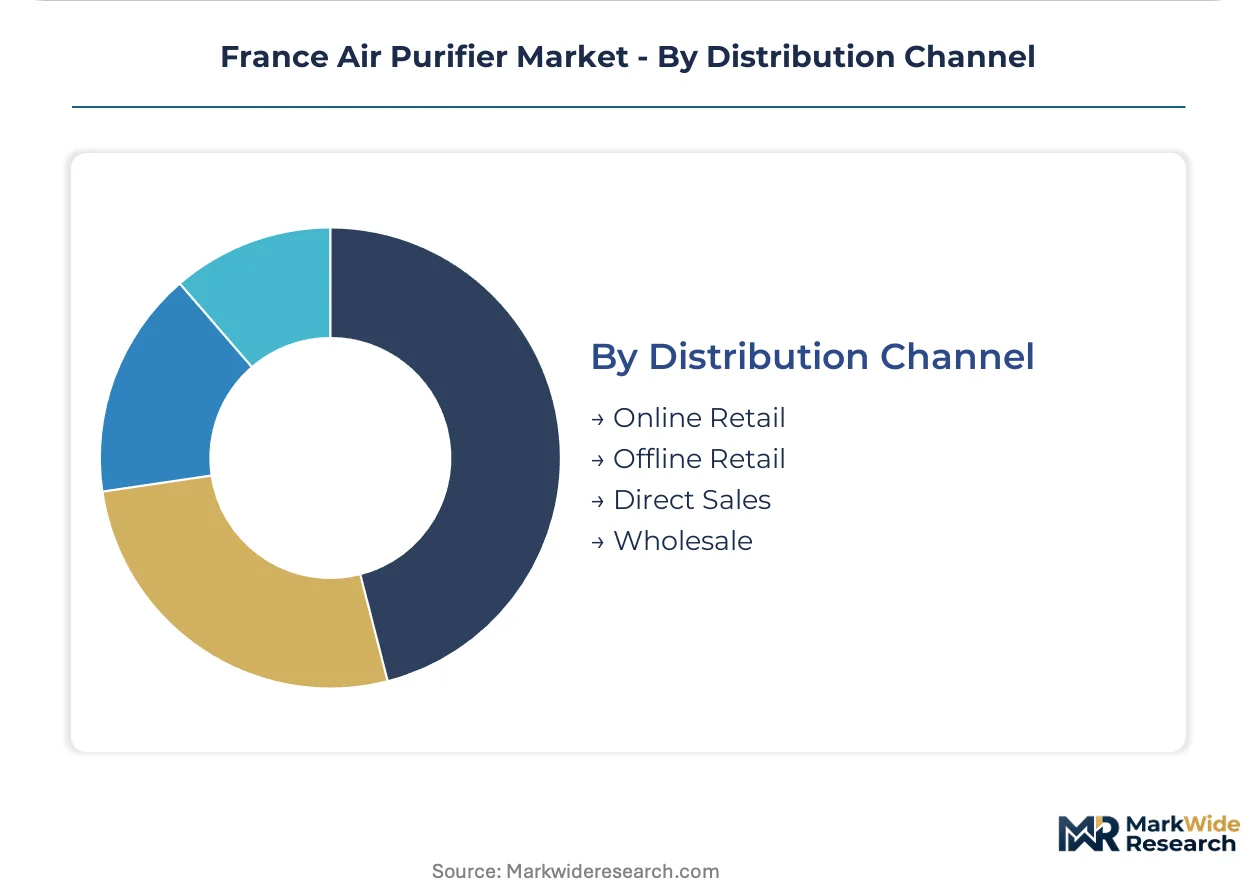
Distribution Channel:
Customer type and geography concentration shape where margin pools accumulate versus where volume flows.
- Online Retail:Direct-to-consumer digital platforms in Île-de-France show fastest uptake of bundled service contracts.
- Offline Retail:Electronics retailers face displacement as pharmacy channels capture allergen-focused portable sales.
- Direct Sales:Hospital network procurement and commercial real estate bulk orders bypass intermediaries.
- Wholesale:Aggregated volume serves secondary city markets across Provence-Alpes-Côte d'Azur with forty-plus percent adoption gaps against capital region baselines.
Offline Retail still moves the most units annually while Online Retail climbs the fastest on subscription attachment rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut shell precursor processing for activated carbon media clusters in Southeast Asian hubs, exposing French manufacturers to freight volatility and extended lead times that reshape procurement timelines.
Île-de-France
Paris hospital networks and La Défense commercial real estate drive bulk HEPA and activated carbon procurement. ANSES indoor air quality guidelines mandate filtration upgrades across healthcare facilities. Pharmacy channel consolidation in the capital region captures seasonal pollen-driven purchase cycles through direct-to-consumer digital platforms.
Auvergne-Rhône-Alpes
Lyon healthcare clusters accelerate HEPA procurement cycles amid tightening building ventilation standards. The EU Ecodesign Directive imposes standby power limits below two watts on networked units. Grenoble's precision electronics manufacturing base sustains demand for process protection systems in light industrial cleanrooms.
Provence-Alpes-Côte d'Azur
Secondary city residential markets show filtration adoption gaps exceeding forty percent against capital region baselines. RE2020 environmental regulation drives new construction toward embedded mechanical ventilation with filtration modules. Nice premium households switch toward maintenance-reducing filterless ionic alternatives.
Nouvelle-Aquitaine
Bordeaux residential buyers exhibit strong preference for premium portable units with smart connectivity features. France's transposition of EU Ecodesign rules compresses product launch windows for standby power compliance. The region's wine production facilities deploy specialized VOC remediation systems for barrel storage environments.
Hauts-de-France
Lille metropolitan area commercial stock modernization sustains activated carbon demand for VOC remediation in aging office buildings. Legacy nineteenth-century wiring constraints limit high-CADR unit deployment without electrical infrastructure upgrades. Wholesale distribution networks serve underpenetrated rural markets across the northern corridor.
France Air Purifier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the French market. The vendor base organizes around three strategic groupings: integrated HVAC multinationals anchoring commercial and healthcare contracts, consumer electronics specialists dominating retail pharmacy channels, and domestic filterless technology innovators capturing premium residential segments. Competitive moves concentrate on smart connectivity integration and subscription-based filter replenishment models that restructure buyer relationships toward recurring revenue architectures.
Within the domestic specialist tier, TEQOYA SAS exemplifies filterless ionic technology positioning for maintenance-averse premium buyers. Among integrated HVAC and electronics conglomerates, Daikin Europe NV and Koninklijke Philips N.V. occupy positions spanning commercial project contracting and broad retail distribution respectively. These three anchors represent divergent strategic bets on whether embedded building systems, standalone smart devices, or maintenance-free alternatives will capture margin pools as RE2020 codes reshape demand.
| Leading Market Players |
|---|
| JVD SAS |
| TEQOYA SAS |
| Koninklijke Philips N.V. |
| Daikin Europe NV |
| WINIX Europe B.V. |
| NatéoSanté SAS |
| Sharp Electronics France SA |
| Panasonic France SAS |
| Xiaomi Technology France S.A.S. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts for coconut shell activated carbon lock in both supply access and price visibility for French manufacturers, insulating procurement teams from Southeast Asian freight volatility while compressing margin flexibility when spot markets soften.
Pricing Analysis
EU Ecodesign Directive dictates the pricing tier structure across the France air purifier market. Three-tier pricing structure across premium, standard, and economy levels separates EN 1822:2009 HEPA-certified hospital-grade systems from pharmacy-channel portable units and unbranded online imports. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Asian competitors bypass six-to-nine month CE compliance delays. Residential buyers in Provence-Alpes-Côte d'Azur exhibit highest price sensitivity, while Assistance Publique-Hôpitaux de Paris procurement committees prioritize performance over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes expose French manufacturers to extended lead times for electronic components and sensor arrays. Coconut shell precursor processing clusters in Indonesia, Philippines, and Sri Lanka. Supply chains draw from Chinese PCB fabrication, German motor assemblies, and Southeast Asian activated carbon. Single-source vulnerability concentrates in coconut shell carbon refining, where three processing groups control eighty percent of export volume. Distribution runs through pharmacy networks for residential portable units and direct sales for hospital network procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France air purifier market sits at a platform-economics inflection where subscription filter replenishment and indoor air quality monitoring apps restructure buyer relationships toward recurring revenue architectures, rewarding ecosystem interoperability over standalone hardware margins.
For Market Incumbents: Fortify channel control in pharmacy networks against electronics retailer displacement by embedding smart connectivity as standard across mid-tier portfolios. Deepen backward integration into low-power firmware architectures to deflect EU Ecodesign Directive compliance costs that disproportionately burden new entrants. Acquire accredited HEPA testing capacity or secure priority queue positions at German and Swiss laboratories to circumvent twelve-month French certification backlogs. For New Entrants and Emerging Players: Differentiate on maintenance-free filterless ionic technology to capture premium residential segments in Bordeaux and Nice where TEQOYA SAS has validated willingness-to-pay for reduced lifecycle costs. Target underpenetrated secondary cities across Provence-Alpes-Côte d'Azur with forty-plus percent adoption gaps against Île-de-France baselines. Pursue direct-to-consumer digital platforms with bundled service contracts rather than competing for electronics retailer shelf space. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among smart-connected purifier portfolios with embedded sensor arrays and subscription filter replenishment, positioning these archetypes for superior cash flow quality over pure hardware manufacturers. Acquisition targets should demonstrate pharmacy channel penetration in Île-de-France and compliance-ready low-power architectures. The signal to watch is RE2020 building code enforcement velocity, which determines whether embedded HVAC filtration captures demand previously served by standalone units.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Connectivity Integration | Subscription filter replenishment concentrates customer lifetime value with original equipment manufacturers against retail attachment sales. |
| Pharmacy Channel Expansion | Direct-to-consumer digital platforms in Île-de-France capture seasonal pollen-driven purchase cycles previously served by electronics retailers. |
| Filterless Technology Development | Ionic purification reduces maintenance burdens for premium residential buyers in Bordeaux and Nice, expanding addressable margin pools. |
| Compliance Architecture Investment | Low-power firmware designs deflect EU Ecodesign Directive standby power limits below two watts that compress product launch windows. |
| Regional Geographic Expansion | Secondary city markets across Provence-Alpes-Côte d'Azur show filtration adoption gaps exceeding forty percent against capital region baselines. |
Research Methodology
The analysis maps HEPA filtration, activated carbon adsorption, UV-C germicidal irradiation, and smart-connected systems, each validated through hospital procurement managers, pharmacy category buyers, commercial real estate facility directors, and residential consumer panels. Primary interviews with industry stakeholders combined with secondary validation from ANSES technical bulletins, EU Ecodesign Directive transposition texts, RE2020 regulatory filings, and customs trade records. Bottom-up shipment data triangulated against top-down market sizing from building stock modernization projections and healthcare capital expenditure tracking.
Consistency checks validated volume and value outputs against external benchmarks including hospital network procurement databases, commercial real estate tenant improvement spending patterns, and pharmacy retail audit data across the analysis window. Segmentation dimensions modeled encompass product type, end user category, technology configuration, and distribution channel, with regional adoption patterns as an industry-specific overlay. CAGRs derived from regression analysis of historical shipment trajectories and elasticity-adjusted demand projections. Forecast inputs include RE2020 building code compliance timelines and ANSES guideline enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of indoor air quality mandates and RE2020 embedded filtration requirements would require recalibration. Forecasts reflect documented assumptions regarding certification backlog durations, coconut shell precursor supply stability, and smart connectivity adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Europe Machine Condition Monitoring Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Global Pressure Calibrators Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Digital Flow Meter Market
Sensors and Controls
UV Sensors Market