
 Liquid Blister Pack Market | 2026-2036
Liquid Blister Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Blister Pack Market Analytics
Consolidation among pharmaceutical contract manufacturers is repositioning procurement leverage toward fewer, larger buyers with dedicated packaging specifications. Amcor plc leverages its integrated film-to-formed-pack supply chain to secure multi-year supply agreements with consolidated drug makers. Constantia Flexibles anchors its position through specialized cold-form aluminum foil laminates that meet stringent barrier requirements for liquid oral doses. UFlex Limited competes on cost-optimized PVC and PET thermoforming capacity serving emerging-market generic pharmaceutical producers.
A liquid blister pack is a pre-formed cavity package, typically constructed from thermoformed PVC or cold-form aluminum foil laminates, designed to contain unit-dosed liquid, gel, or suspension products in sealed, individual compartments for controlled dispensing and shelf-life extension. The package relies on multi-layer barrier structures with specified moisture vapor transmission rates below 0.5 g/m²/day to protect hygroscopic liquid formulations. Cold form blister configurations lead the product type landscape due to their superior barrier performance for pharmaceutical applications, while stick packs represent the fastest-growing format as nutraceutical brands seek portable, single-serve delivery options. Thermoformed PET variants command narrower margins but occupy high-volume positions in cosmetics and sample-sized liquid food segments where barrier demands remain moderate.
FDA stability-testing protocols and EMA Annex 1 manufacturing guidelines shape material selection and validation requirements for liquid blister packs entering regulated pharmaceutical channels. REACH compliance and EU Green Deal packaging waste directives are accelerating migration from PVC toward recyclable PET and paperboard-backed structures in European supply chains. ISO 15378 certification for medicinal product packaging now functions as a de facto market-access threshold for suppliers serving multinational drug manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based barrier material certifications as these will determine which substrate investments retain competitive validity.
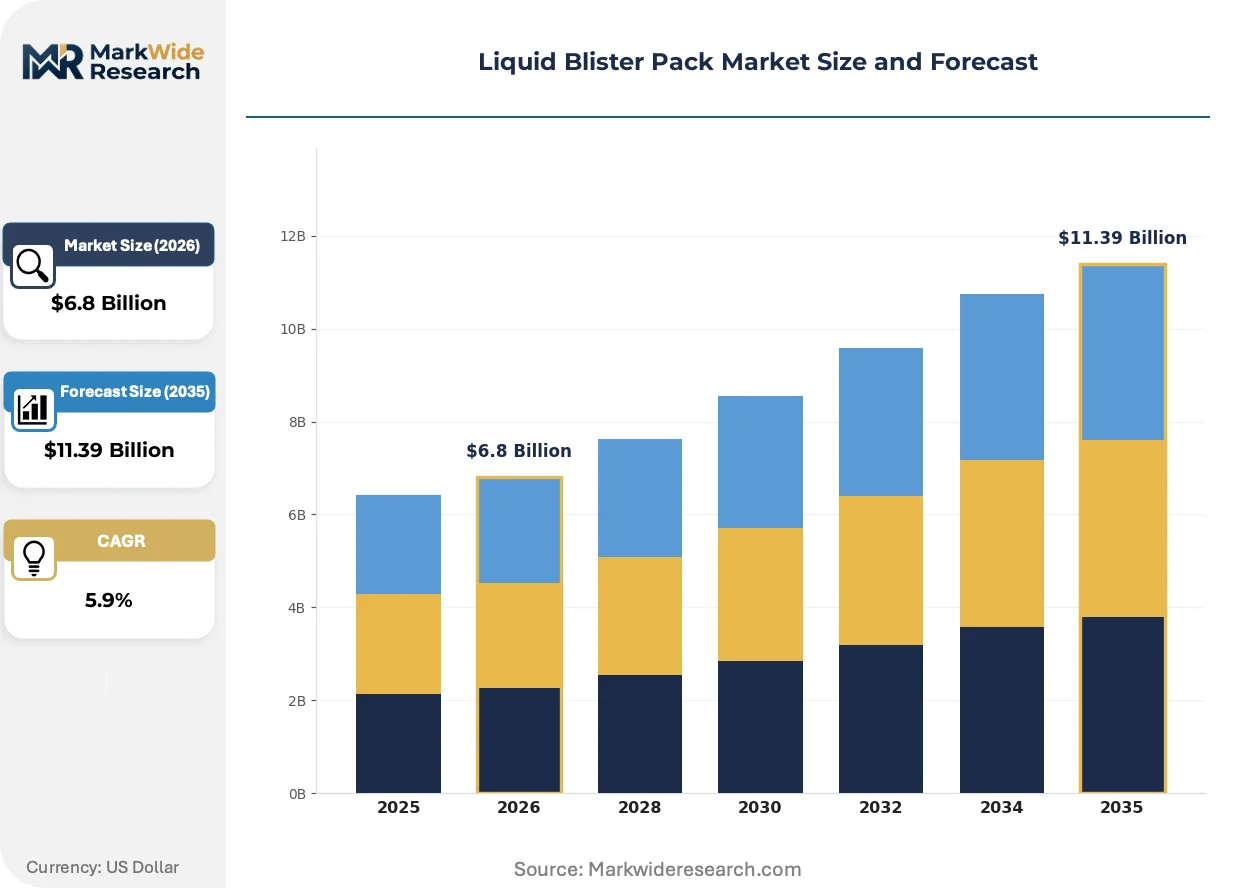
Market Dynamics
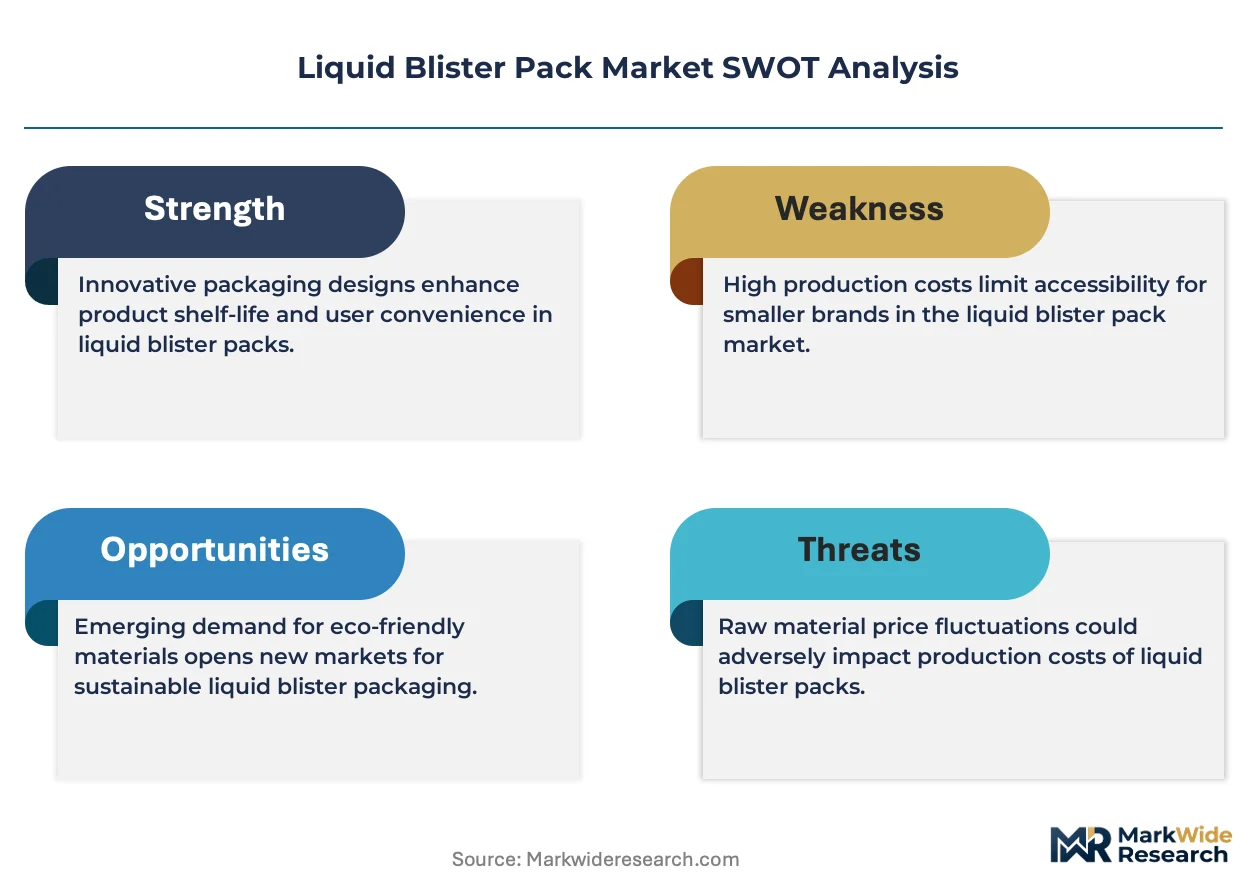
Pharmaceutical contract manufacturer consolidation is concentrating procurement leverage among fewer buyers with dedicated barrier specifications, forcing substrate suppliers to validate multi-layer structures against tightening FDA and EMA stability protocols.
Growth Catalysts
- EMA Annex 1 manufacturing guidelines:Updated sterile manufacturing requirements are mandating higher barrier integrity for liquid oral dose packaging, driving specification upgrades across European supply chains.
- Single-serve nutraceutical formats:Portable stick pack configurations for vitamins and supplements are expanding addressable volume beyond traditional pharmaceutical channels.
- Germany cold-form cluster:High-throughput aluminum foil laminate production serving pan-European pharma clients anchors regional capacity expansion and technical know-how concentration.
Market Restraints
- Aluminum foil supply concentration:Cold-form laminate producers depend on a narrow supplier base for high-purity foil, exposing margins to energy-cost volatility in primary metal production.
- PVC regulatory friction:REACH restrictions and EU Green Deal packaging waste directives are forcing premature asset retirement for producers with legacy thermoforming lines.
- Moisture barrier technical ceiling:Current multi-layer structures face fundamental limits pushing below 0.3 g/m²/day transmission rates without disproportionate cost escalation.
Strategic Opportunities
- Indian generic pharmaceutical export growth:Cost-optimized PVC and PET capacity serving emerging-market producers can capture volume from patent-expired biologic liquid formulations.
- Paperboard-backed barrier structures:Recyclable fiber-based substrates meeting pharmacy dispensing requirements open access to EU extended producer responsibility incentives.
- ISO 15378 certification arbitrage:Medicinal product packaging quality standards are becoming a de facto market-access threshold that certified suppliers can leverage for premium positioning.
Industry Challenges
- Multi-layer coextrusion technician scarcity:Specialized extrusion die engineering expertise for barrier film production is concentrated among retiring workforce cohorts in mature packaging regions.
- Validation timeline compression:FDA stability-testing protocols for new barrier structures demand 24-36 month qualification cycles that mismatch abbreviated drug approval pathways.
- Legacy thermoformer retrofit complexity:Existing PVC forming equipment requires substantial reconfiguration to process PET or PP alternatives without yield degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Blister Pack Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Form Blister, Thermoformed Blister, Stick Packs, Others End User: Pharmaceuticals, Cosmetics, Food & Beverages, Healthcare Packaging Material: Aluminum Foil, PVC, PET, Paperboard Application: Oral Medications, Topical Products, Nutraceuticals, Liquid Foods |
| Companies Covered | Amcor plc, Constantia Flexibles, UFlex Limited, Sonoco Products Company, WINPAK LTD., WestRock Company, SteriPackGroup, Klockner Pentaplast, SÜDPACK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Blister Pack Market Evolving Landscape
Barrier material science and regulatory compliance frameworks are converging to reshape substrate selection criteria, with sustainability mandates now carrying equal weight to functional performance in buyer evaluations.
High-barrier cyclic olefin copolymer (COC) films are absorbing moisture-sensitive liquid formulation volume previously served by aluminum cold-form structures. Specialty pharma packaging divisions at consolidated drug makers are specifying COC for biologic oral suspensions requiring visible dose verification. The material's clarity and processability is absorbing share in applications where barrier demands sit below pharmaceutical extremes but above standard thermoformed PET capabilities.
REACH substance restrictions and EU Green Deal packaging waste directives are accelerating PVC phase-out timelines across European supply chains. ECHA evaluations of plasticizer migration risks are compelling reformulation of flexible film additives or complete substrate substitution. German and Swiss packaging converters are responding with certified recyclable PET and PP mono-material structures validated for pharmacy automation.
Direct-to-patient subscription models for chronic condition management are compressing order cycle times and fragmenting batch sizes. Nutraceutical brands serving wellness-focused demographics are bypassing traditional wholesale distribution for e-commerce fulfillment with custom-branded unit-dose formats. This channel rotation is most visible in North American and Western European markets where last-mile cold chain requirements for liquid formulations remain manageable.
Liquid Blister Pack Market Segmentation
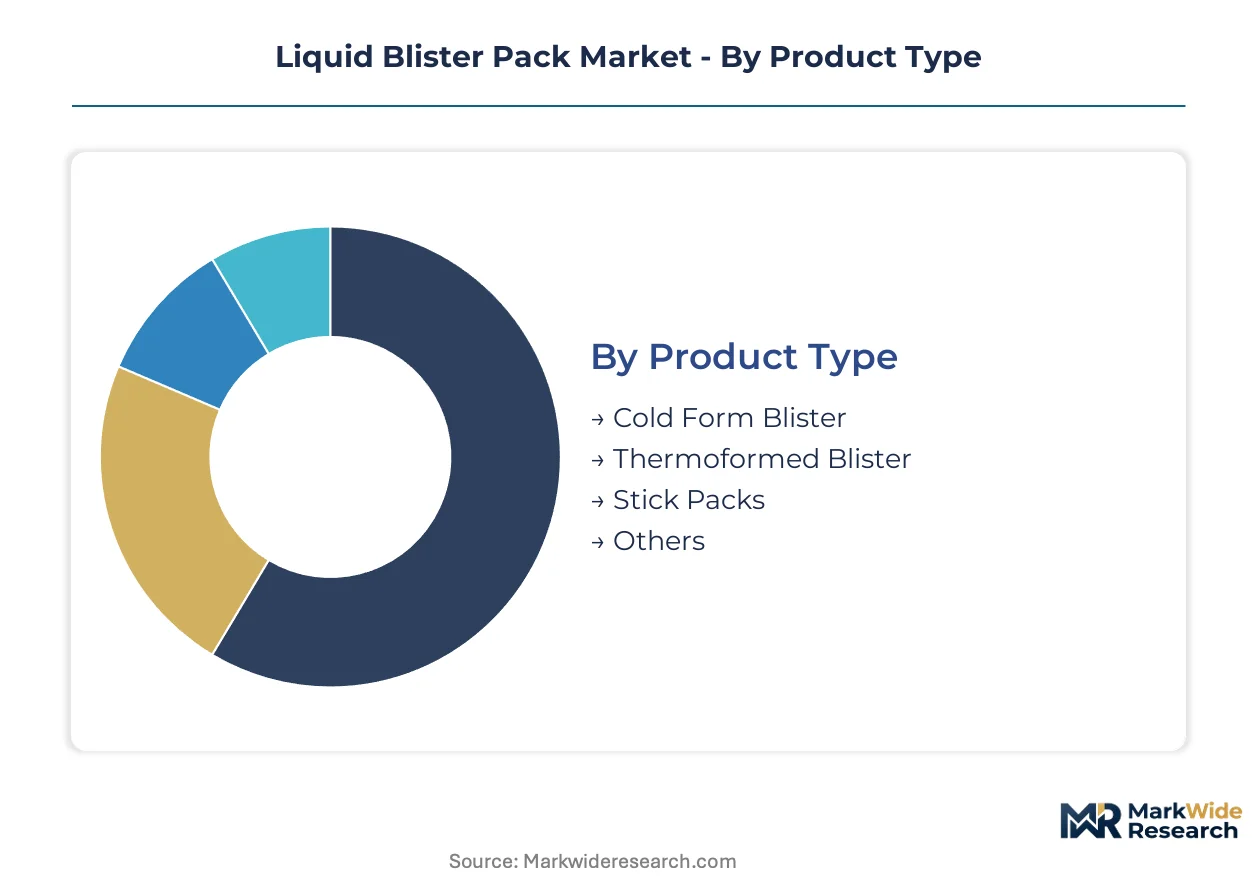
Liquid blister pack configurations diverge sharply between premium barrier applications and cost-optimized volume production. Substrate selection and forming technology determine which suppliers capture pharmaceutical validation contracts versus commodity nutraceutical orders.
Product Type:
Cold-form aluminum structures command premium positioning while thermoformed variants absorb high-volume generic demand.
- Cold Form Blister:Multi-layer aluminum foil laminates deliver moisture vapor transmission rates below 0.5 g/m²/day for hygroscopic liquid formulations. German and Swiss converters anchor European pharmaceutical supply with validated cold-form lines meeting EMA Annex 1 sterile manufacturing requirements.
- Thermoformed Blister:PVC and PET cavity structures serve cosmetics sampling and moderate-barrier nutraceutical applications where cost sensitivity outweighs extreme moisture protection. Indian and Southeast Asian producers compete aggressively on thermoforming capacity for emerging-market generic exporters.
- Stick Packs:Single-serve film pouches represent the steepest expansion trajectory as wellness brands bypass wholesale distribution for direct-to-patient subscription channels.
- Others:Specialty formats including blow-fill-seal ampoules and sachet configurations occupy narrow niches in veterinary and diagnostic liquid packaging.
Today's leader: Cold Form Blister. Tomorrow's challenger: Stick Packs.
End User:
Pharmaceutical procurement concentrates among consolidated contract manufacturers while cosmetics and food brands fragment across smaller converters.
- Pharmaceuticals:Oral medication contract packagers drive specification-setting for barrier laminates with FDA stability-testing validation. Multi-year supply agreements with consolidated drug makers favor suppliers with integrated film-to-formed-pack capabilities.
- Cosmetics:Sample-sized serum and essence formats utilize thermoformed PET structures with moderate barrier demands. Premium beauty brands specify transparent cavity designs for visible product presentation.
- Food & Beverages:Single-serve condiment and sauce portions utilize lower-cost thermoforming with shorter shelf-life requirements.
- Healthcare:Diagnostic reagents and medical device liquids require validated sterile barrier packaging with ISO 15378 certification.
Pharmaceuticals capture margin concentration. Cosmetics and food expand addressable volume fastest.
Packaging Material:
REACH compliance and EU Green Deal directives are accelerating substrate substitution timelines across European supply chains.
- Aluminum Foil:High-purity cold-form laminates remain indispensable for pharmaceutical extremes despite energy-cost volatility in primary metal production. Supply concentrates among narrow supplier bases in Germany and Austria.
- PVC:Legacy thermoforming substrate faces premature asset retirement as ECHA plasticizer migration evaluations tighten. Converters with stranded PVC capacity seek PET and PP retrofit pathways.
- PET:Recyclable mono-material structures gain pharmacy automation validation in German and Swiss markets. Clarity and processability absorb share from PVC in cosmetics and visible-dose applications.
- Paperboard:Fiber-backed barrier structures open EU extended producer responsibility incentives for sustainable packaging claims.
Aluminum dominates barrier performance. PET and paperboard capture regulatory tailwinds.
Application:
Oral medication stability requirements set the technical ceiling that other applications reference at reduced specification tiers.
- Oral Medications:Liquid suspensions and gels demand the most stringent moisture protection, driving cold-form specification and 24-36 month FDA validation cycles. Biologic oral formulations absorb emerging COC film alternatives.
- Topical Products:Cream and gel blister packs prioritize user-controlled dispensing over extreme barrier performance. Cosmetics and dermatological brands specify transparent or printed cavity designs.
- Nutraceuticals:Vitamin and supplement stick packs expand fastest through e-commerce subscription models with compressed order cycles and fragmented batch sizes.
- Liquid Foods:Sauce and condiment portions tolerate shorter shelf-life specifications with cost-optimized thermoformed structures.
Oral medications anchor technical standards. Nutraceuticals reshape volume patterns through channel rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands cold-form aluminum laminate production for European pharmaceutical clients, while India scales cost-optimized thermoforming capacity for generic drug exporters. This divergence shapes regional competitive positioning across barrier specification tiers.
Germany
EMA Annex 1 sterile manufacturing requirements drive specification upgrades for liquid oral dose packaging. REACH substance restrictions and EU Green Deal packaging waste directives accelerate PVC phase-out toward recyclable PET and PP mono-materials. The SÜDPACK and Klockner Pentaplast operations in the Rhineland and Bavaria anchor high-throughput cold-form capacity serving pan-European pharma demand.
United States
FDA stability-testing protocols mandate 24-36 month validation cycles for new barrier structures serving oral medication contract packagers. Direct-to-patient subscription models for chronic condition management compress order cycle times and fragment batch sizes. Nutraceutical brands in the Northeast and California bypass wholesale distribution for e-commerce fulfillment with custom-branded unit-dose formats.
India
Patent-expired biologic liquid formulations from generic pharmaceutical exporters drive demand for cost-optimized PVC and PET thermoforming. CDSCO manufacturing guidelines and export registration requirements shape packaging validation for regulated markets. UFlex Limited and concentrated converter capacity in Gujarat and Maharashtra capture volume from emerging-market producers.
Switzerland
Swissmedic pharmaceutical packaging regulations and ISO 15378 certification requirements establish quality thresholds for medicinal product barrier materials. High-purity aluminum foil laminate specifications from Austrian and German suppliers concentrate procurement leverage. Basel and Zurich packaging converters specialize in validated cold-form structures for biologic oral suspensions requiring visible dose verification.
China
NMPA drug packaging material registration rules and GB standards for pharmaceutical plastics govern substrate selection for domestic and export markets. Dual carbon goals and MEE environmental compliance timelines pressure PVC-dependent thermoforming operations. Yangtze River Delta and Pearl River Delta converters scale PET and COC film alternatives for moisture-sensitive liquid formulations.
Liquid Blister Pack Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate technology tiers. Consolidated drug makers concentrate procurement leverage through multi-year supply agreements with validated film-to-formed-pack suppliers. Three archetypes dominate: integrated film-to-pack conglomerates with captive resin and forming operations; specialized cold-form laminate producers with aluminum foil supply chain control; and regional thermoforming specialists competing on cost-optimized PVC and PET capacity. M&A activity targets ISO 15378-certified converters, while capacity expansion concentrates in German and Indian clusters serving pharmaceutical export growth.
Within the integrated conglomerate tier, Amcor plc exemplifies film-to-formed-pack supply chain control through its multinational packaging operations. Among European cold-form specialists, Constantia Flexibles and SÜDPACK occupy positions anchored by aluminum foil laminate expertise and EMA validation capabilities. UFlex Limited represents the emerging-market cost-optimization archetype, with Indian-based thermoforming capacity serving generic pharmaceutical export demand.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| UFlex Limited |
| Sonoco Products Company |
| WINPAK LTD. |
| WestRock Company |
| SteriPackGroup |
| Klockner Pentaplast |
| SÜDPACK |
| Others |
Value Network & Pricing Analysis
Specialized multi-layer coextrusion technicians concentrated in Germany's Rhineland corridor command wage premiums that propagate through cold-form laminate pricing tiers, widening spreads between validated pharmaceutical-grade supply and commodity thermoforming alternatives sourced from lower-cost Indian converter clusters.
Pricing Analysis
Capacity additions in India's Gujarat and Maharashtra thermoforming corridors are reshaping price floors for PVC and PET blister configurations serving generic pharmaceutical exporters. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated cold-form aluminum laminates from pharmacy-grade PET mono-materials and cost-optimized PVC alternatives. Price differentiation hinges on ISO 15378 certification status and moisture vapor transmission performance tiers. Cost compression in standard-grade PET is intensifying because REACH compliance investments are eroding legacy PVC margins. Emerging-market generic producers exhibit highest price sensitivity; consolidated European contract manufacturers prioritize barrier validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany's Bavaria cluster and Switzerland's Basel pharmaceutical corridor operate hub-and-spoke patterns for validated cold-form laminate deployment. Primary supply concentrates in Germany, India, and China. High-purity aluminum foil, COC barrier films, and pharmaceutical-grade PET resin constitute critical input dependencies. Single-source vulnerability in Austrian and German aluminum foil supply exposes downstream converters to energy-cost volatility in primary metal production. Distribution runs through pharmaceutical contract manufacturer consolidation nodes with multi-year supply agreement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid blister pack market functions as a geographic-arbitrage play where REACH-driven substrate substitution costs in Europe diverge sharply from CDSCO export-registration economics in India, creating margin capture opportunities for dual-hemisphere suppliers.
For Market Incumbents: Extend EMA Annex 1 validation coverage to COC film alternatives before biologic oral suspension specifications harden around visible-dose verification requirements. Secure backward integration into high-purity aluminum foil supply through captive arrangements with German or Austrian smelter networks. Cold-form laminate producers without foil supply chain control face margin compression from energy-cost volatility.
For New Entrants and Emerging Players: Capture paperboard-backed barrier structure volume as EU extended producer responsibility incentives reshape pharmacy automation compatibility requirements. The most penetrable white space sits in recyclable fiber-based substrates meeting Swissmedic and EMA dispensing standards. Pursue ISO 15378 certification arbitrage through acquisition of stranded European PVC converter assets seeking PET retrofit pathways.
For Investors and Strategic Acquirers: Pharmaceutical contract manufacturers are the most active acquirer in this space, consolidating film-to-formed-pack capabilities to secure supply continuity for abbreviated drug approval pathways. Long-term viability favors suppliers with validated multi-substrate flexibility across aluminum, COC, and recyclable PET platforms. Watch FDA stability-testing protocol amendments for moisture barrier thresholds as the inflection signal for substrate substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Annex 1 Validation Expansion | Secures sterile manufacturing compliance for European pharmaceutical contract packaging demand. |
| ISO 15378 Certification Acquisition | Establishes medicinal product packaging quality threshold for multinational drug manufacturer access. |
| COC Film Capacity Addition | Captures biologic oral suspension volume requiring visible dose verification and moderate barrier performance. |
| Aluminum Foil Supply Integration | Mitigates energy-cost volatility exposure in high-purity cold-form laminate production. |
| PET Mono-material Retrofit Program | Converts stranded PVC thermoforming lines for REACH-compliant recyclable pharmacy automation formats. |
Research Methodology
Bottom-up pharmaceutical contract packaging modeling reconciled against top-down barrier substrate production tracking forms the analytical core of this study. Primary interviews with pharmaceutical packaging procurement managers, multi-layer film extrusion engineers, regulatory affairs specialists at EMA-notified bodies, and cold-form line operators at German and Swiss converters were synthesized with secondary validation from FDA drug packaging material filings, ECHA REACH substance restriction evaluations, EU Green Deal packaging waste directive implementations, and SEC 10-K disclosures from listed packaging conglomerates. Triangulation between end-use demand signals and supply-side capacity announcements ensures convergence at volume and value estimates.
Input-output matrices map substrate consumption rates per oral medication unit dose across cold-form, thermoformed, and stick pack configurations. Segmentation dimensions include product type, end-user industry, packaging material substrate, and application requirement tier, with regional regulatory cluster effects modeled as overlay modifiers. CAGRs were derived from regression analysis of historical pharmaceutical packaging expenditure patterns against patent expiry schedules and biologic oral formulation pipeline densities. Forecast inputs incorporate EMA Annex 1 sterile manufacturing adoption curves and REACH PVC phase-out compliance timelines.
Regulatory protocol amendments, raw material energy-cost shocks, and pharmaceutical contract manufacturer consolidation velocity are the dominant revision risks to projection assumptions. Forecasts reflect documented scenario parameters and elasticity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Blister Packaging Equipment Market
Blister Packaging
Blister Cards Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Blister Pack Pharmaceutical Products Market