
 Asia Pacific Pharmaceutical Blister Packaging Market | 2026-2036
Asia Pacific Pharmaceutical Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pharmaceutical Blister Packaging Market Insights
China's NMPA serialization mandates is shifting the cost-of-entry calculus for blister packaging suppliers across the Asia Pacific region. Amcor Limited leverages its integrated film extrusion and forming capabilities to sustain compliance-led contract wins in Australia and New Zealand. Klockner Pentaplast Group anchors high-barrier PVC and Aclar film production for tropical stability requirements in Southeast Asian markets. Constantia Flexibles competes through specialized cold-form foil laminates serving Japanese ethical pharmaceutical exporters.
Asia Pacific pharmaceutical blister packaging denotes pre-formed plastic, aluminum, or composite cavities sealed with lidding foil to protect unit-dose oral solid dosage forms from moisture, oxygen, and light ingress, typically achieving water vapor transmission rates below 0.1 g/m²/day for high-barrier configurations. The primary commercial purpose centers on ensuring shelf-life stability, tamper evidence, and child-resistant or senior-friendly accessibility compliance for regulated drug distribution. Cold formed blister formats occupy the premium margin pool due to their complete aluminum barrier properties demanded by hygroscopic formulations in Japan and South Korea, while thermoformed PVC and PET variants dominate volume throughput across India's generic tablet export sector. Push-through blister designs lead in hospital and retail pharmacy dispensing workflows, whereas clamshell formats remain nascent outside medical device and nutraceutical applications.
India's CDSCO mandates aluminum-based cold-form compliance for certain Schedule H drug categories, while China's NMPA enforces traceable packaging serialization that reshapes lidding foil printing and verification specifications. Japan's PMDA maintains JIS-standard dimensional tolerances that filter out non-specialized import suppliers. Stakeholders must monitor diverging national serialization timelines and barrier-grade material qualification protocols to align capital deployment across multi-country manufacturing footprints.
Market Dynamics
China's NMPA serialization mandates are compressing supplier qualification timelines across the Asia Pacific region, forcing contract packaging organizations to requalify lidding foil specifications and printing verification systems ahead of enforcement deadlines.
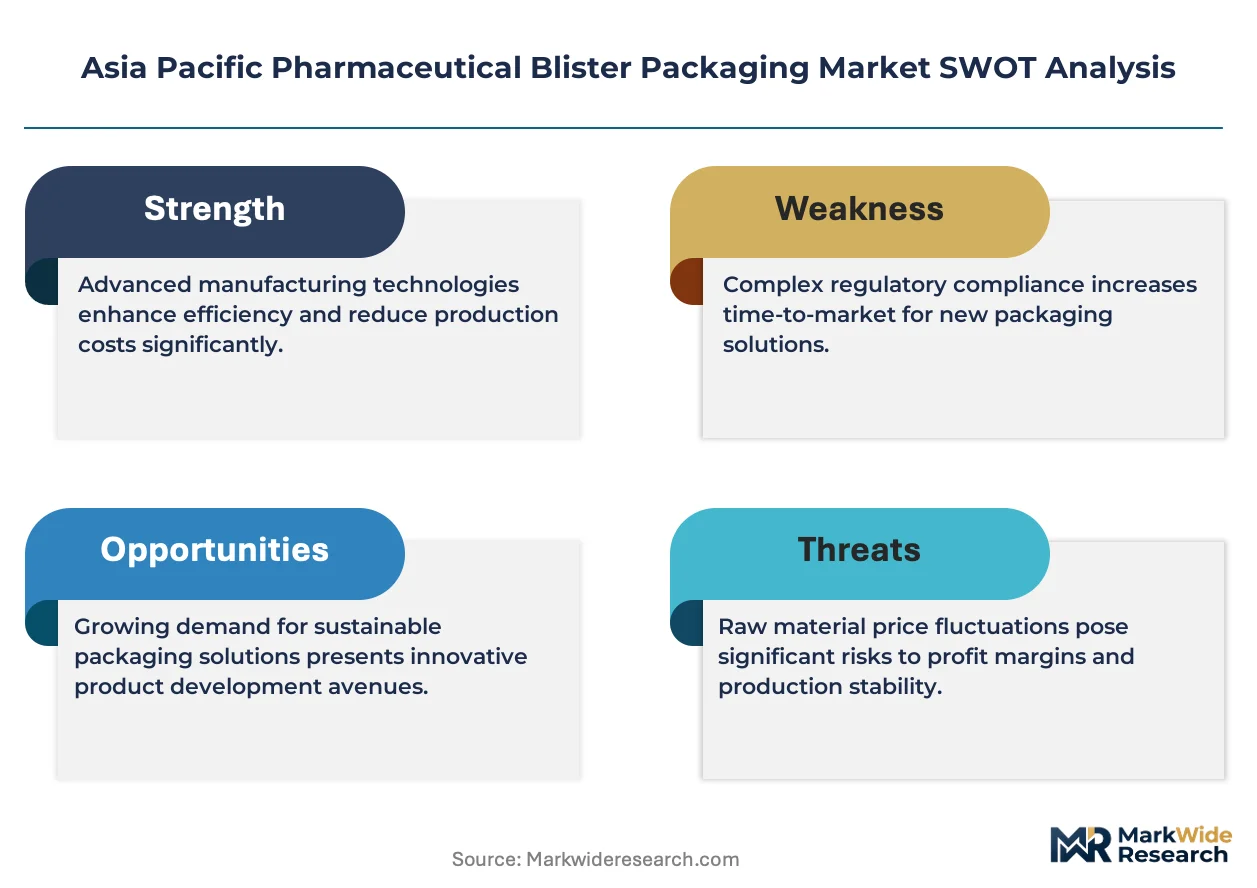
Growth Catalysts
- CDSCO aluminum cold-form mandates:India's drug regulator requires barrier-grade packaging for Schedule H categories, pulling domestic converters toward high-specification equipment.
- Unit-dose adherence programs:Generic manufacturers in Gujarat and Maharashtra are scaling compliance packaging for patient retention contracts with hospital networks.
- Tropical stability demand:Southeast Asian distributors specify Aclar and high-barrier PVC films to protect moisture-sensitive formulations through monsoon logistics.
Market Restraints
- Aluminum foil supply concentration:Regional rolling capacity clusters in China create input cost volatility for lidding material converters elsewhere.
- Specialized thermoforming equipment scarcity:Cold-form blister lines require precision tooling that few regional machinery suppliers can fabricate.
- PMDA dimensional tolerance enforcement:Japan's standards filter out non-specialized import suppliers, limiting sourcing flexibility for ethical pharmaceutical exporters.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing ascent:Emerging contract packaging demand from multinational drug sponsors seeking China-plus-one sourcing.
- Track-ready barrier film convergence:Integration of serialization-ready substrates with embedded verification codes for NMPA compliance.
- Direct-to-pharmacy distribution channels:Bypassing traditional wholesale layers through e-procurement platforms serving hospital networks in South Korea.
Industry Challenges
- Multi-regulator serialization alignment:Simultaneous CDSCO, NMPA, and PMDA timeline mismatches complicate capital deployment across multi-country footprints.
- High-barrier film qualification delays:Extended stability testing protocols for new material submissions stretch customer onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pharmaceutical Blister Packaging Market |
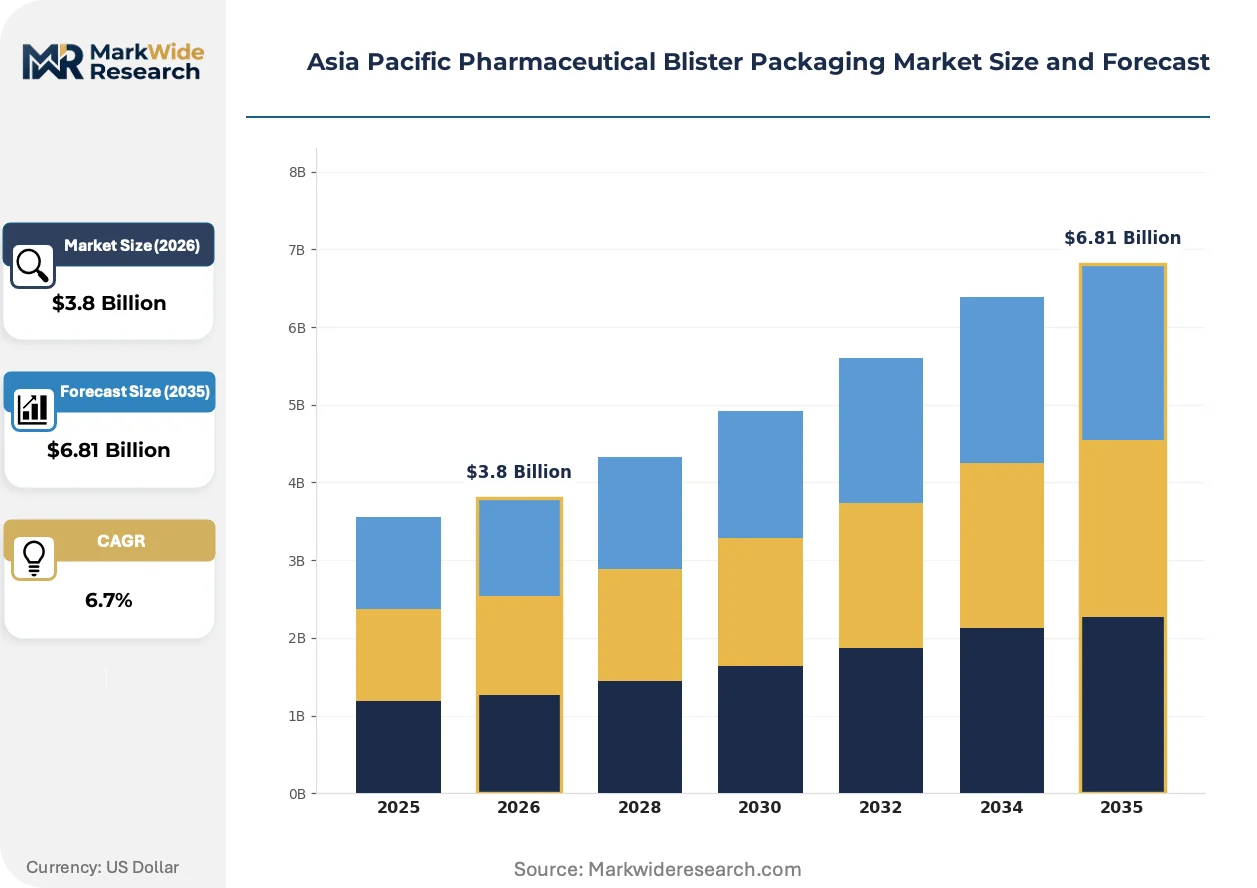
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoformed Blister, Cold Formed Blister, Clamshell Blister, Push Through Blister Material: Aluminum, PVC, PET, Polypropylene End User: Pharmaceutical Companies, Contract Packaging Organizations, Hospitals, Retail Pharmacies Application: Tablets, Capsules, Nutraceuticals, Medical Devices |
| Companies Covered | Klockner Pentaplast Group, Competent Packaging Industries Inc, Amcor Limited, Tekni-Plex Inc, Uflex Limited, Constantia Flexibles, Sonoco Products Company, Perlen Packaging (Suzhou) Co Ltd, WestRock Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pharmaceutical Blister Packaging Market Trends and Innovations
Packaging material science and regulatory traceability requirements are converging to reshape competitive capabilities across the Asia Pacific pharmaceutical blister packaging sector.
Cold-form aluminum laminates are expanding into hygroscopic formulation protection for Japanese and South Korean ethical pharmaceutical exporters. These formats deliver complete moisture and oxygen barriers that thermoformed alternatives cannot match. Domestic converters in Osaka and Seoul are retrofitting forming lines to capture premium margin pools previously served by European suppliers.
China's NMPA serialization mandates are forcing lidding foil printers to integrate track-and-trace verification codes at the point of manufacture. The industrial consequence is a wholesale requalification of substrate and ink specifications to meet machine-readability standards. Australian and New Zealand contract packaging organizations serving Chinese export markets are accelerating supplier audits to maintain eligibility.
Hospital procurement departments across India are consolidating vendor panels around integrated design-to-delivery packaging partners. The segment being disrupted is fragmented local converters without in-house design or regulatory filing support. This concentration is most visible in Maharashtra's Mumbai-Pune pharmaceutical corridor where tertiary care networks are reducing approved supplier lists from dozens to single-digit counts.
Asia Pacific Pharmaceutical Blister Packaging Market Segmentation
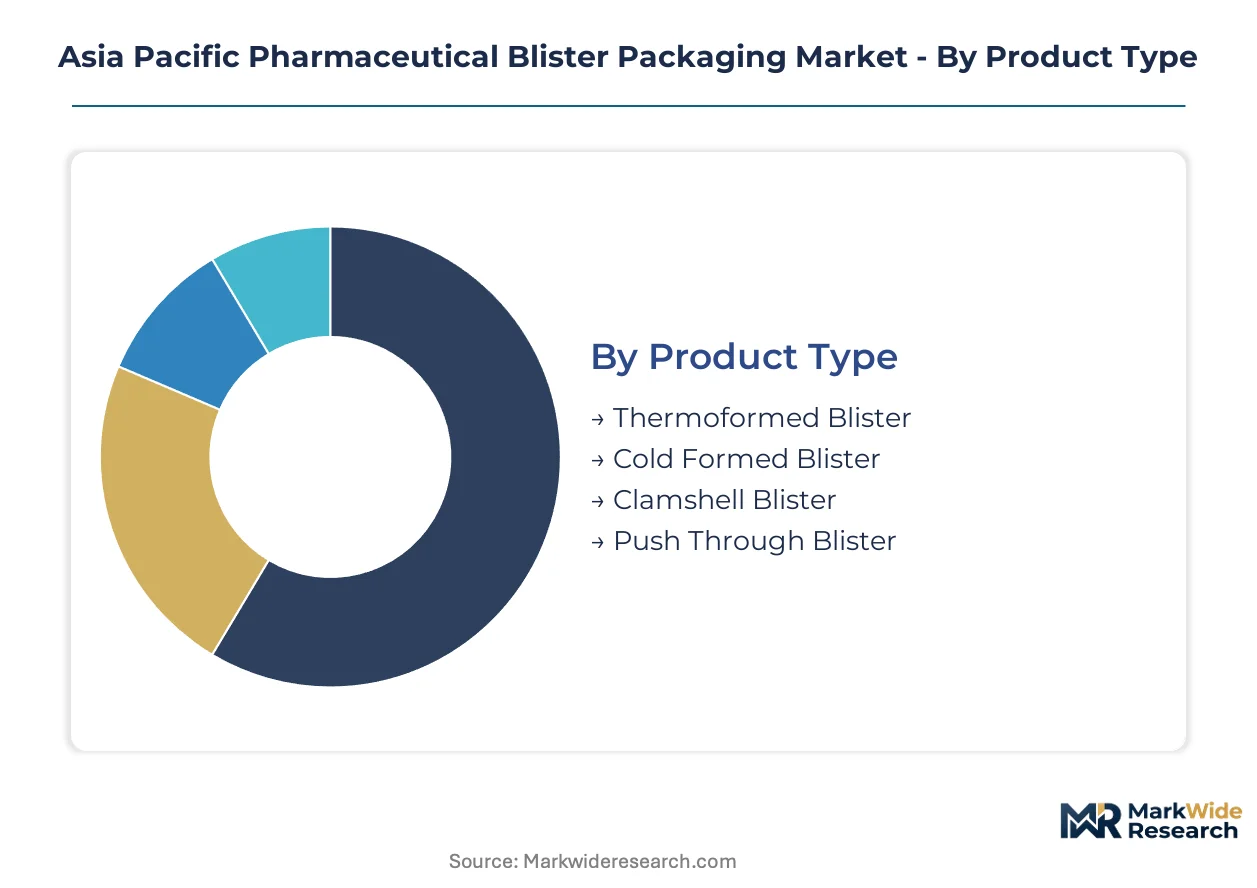
Segmentation in Asia Pacific pharmaceutical blister packaging reveals how material specifications and forming technologies map to divergent regulatory requirements across India, China, and Japan. Suppliers must qualify discrete product lines for each national regulator's barrier-grade mandates and serialization protocols.
Product Type:
Supply concentration for specialized forming equipment shapes competitive access across product categories, with cold-form lines requiring precision tooling that few regional fabricators can deliver.
- Thermoformed Blister:PVC and PET substrates dominate volume throughput across India's Gujarat and Maharashtra generic export corridors. Thermoforming equipment is more widely available domestically, pulling contract packaging organizations toward this accessible technology tier despite inferior barrier properties versus aluminum alternatives.
- Cold Formed Blister:Complete aluminum barrier laminates protect hygroscopic formulations for Japanese and South Korean ethical pharmaceutical exporters. PMDA dimensional tolerance enforcement filters out non-specialized import suppliers, concentrating premium margin capture among Osaka and Seoul-based converters with retrofit forming capabilities.
- Clamshell Blister:Nascent adoption outside medical device and nutraceutical applications, with limited penetration into regulated pharmaceutical distribution.
- Push Through Blister:Standard hospital and retail pharmacy dispensing format across Southeast Asian markets, specified for unit-dose adherence programs in Indian tertiary care networks.
Today's leader: Thermoformed Blister. Tomorrow's challenger: Cold Formed Blister.
Material:
Cost tier differentiation separates premium barrier films from commodity substrates, with tropical stability requirements in Southeast Asia pulling specifications upward.
- Aluminum:Cold-form laminates and lidding foils command premium positioning for CDSCO Schedule H compliance and NMPA serialization-ready track-and-trace integration. China's regional rolling capacity concentration creates input cost volatility for converters elsewhere in the Asia Pacific.
- PVC:Volume workhorse material for Indian generic tablet exports, with high-barrier grades specified for monsoon logistics protection across Southeast Asian distribution networks.
- PET:Growing specification for clarity and dimensional stability in South Korean direct-to-pharmacy channels.
- Polypropylene:Emerging substrate for moisture-resistant applications in Australian and New Zealand contract packaging serving temperature-variable supply chains.
Material selection is inseparable from regulator-specific barrier-grade mandates.
End User:
Customer type determines design-to-delivery integration depth, with hospital procurement consolidation favoring partners with in-house regulatory filing support.
- Pharmaceutical Companies:Direct specification of barrier-grade formats for ethical drug portfolios, particularly Japanese and South Korean exporters requiring PMDA-compliant dimensional tolerances.
- Contract Packaging Organizations:Scaling unit-dose compliance packaging for patient retention contracts with Indian hospital networks in Mumbai-Pune corridor. These intermediaries face compressed supplier qualification timelines from NMPA serialization mandates.
- Hospitals:Consolidating vendor panels around integrated packaging partners, reducing approved supplier lists from dozens to single-digit counts in Maharashtra's tertiary care networks.
- Retail Pharmacies:Dispensing workflow specifications favoring push-through blister designs for consumer accessibility compliance.
Contract Packaging Organizations are climbing the fastest as procurement centralization accelerates.
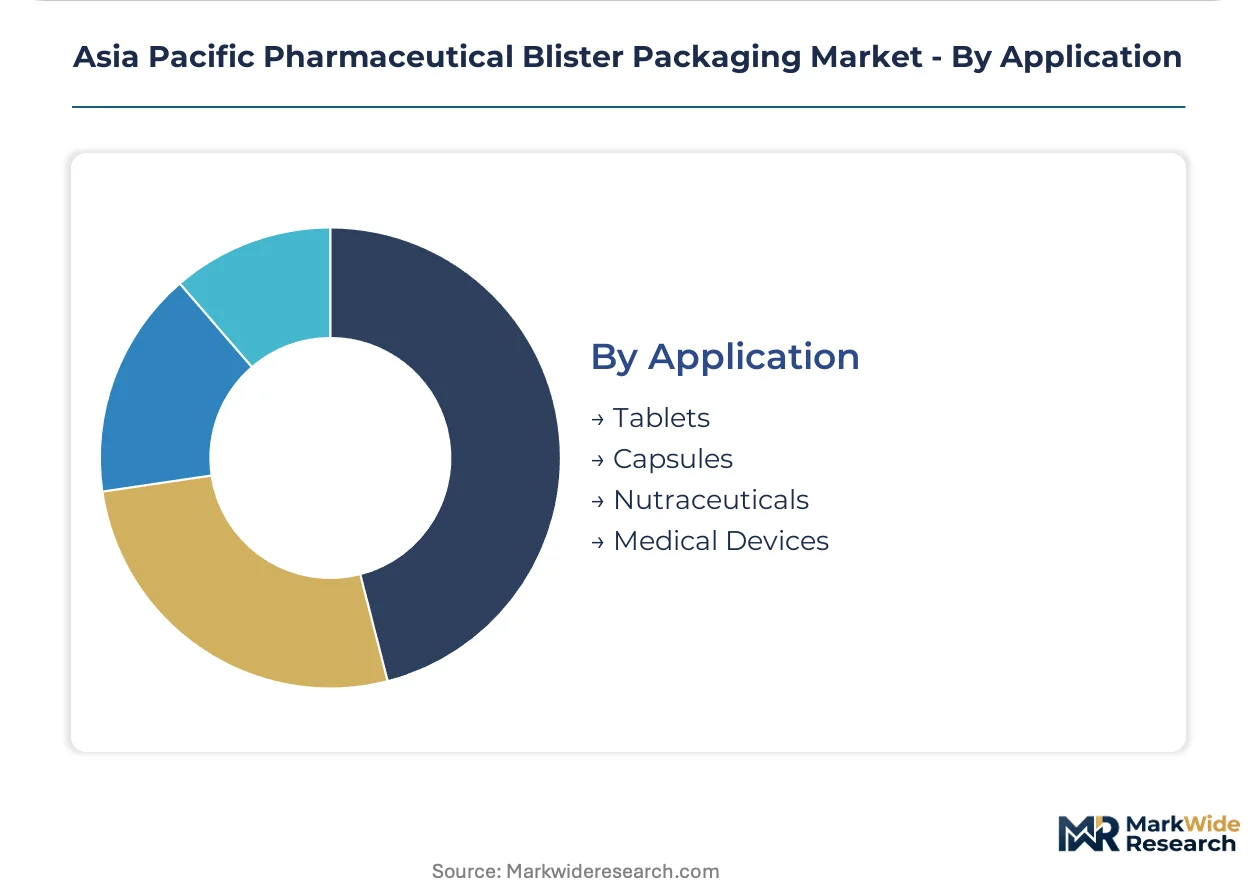
Application:
Application focus dictates barrier specification intensity, with hygroscopic oral solids demanding complete moisture and oxygen protection.
- Tablets:Core volume driver across Indian generic export sector, with thermoformed PVC and PET formats dominating throughput. CDSCO aluminum cold-form mandates for Schedule H categories pull specifications upward for certain therapeutic segments.
- Capsules:Gelatin shell moisture sensitivity drives high-barrier PVC and Aclar film specification for tropical stability through Southeast Asian monsoon logistics.
- Nutraceuticals:Less stringent regulatory barriers permit clamshell and lower-tier thermoformed formats, though Japanese PMDA oversight for certain functional claims creates premium tier access.
- Medical Devices:Sterility and tamper-evidence requirements overlap with pharmaceutical standards, with clamshell formats finding niche adoption outside oral solid dosage forms.
Tablets anchor current volume. Capsules are gaining share fastest on tropical stability premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in pharmaceutical packaging equipment and polymer chemistry anchor the Asia Pacific region's competitive position. Regulatory divergence across national drug authorities creates distinct qualification corridors for suppliers serving multiple markets. Manufacturing clusters concentrate in proximity to active pharmaceutical ingredient synthesis and formulation sites.
India
Generic drug exports from Gujarat and Maharashtra drive thermoformed blister volume demand. CDSCO aluminum cold-form mandates for Schedule H categories pull domestic converters toward high-specification barrier equipment. Mumbai-Pune corridor contract packaging organizations scale unit-dose adherence programs for hospital network contracts.
China
NMPA serialization mandates compress supplier qualification timelines for lidding foil and track-ready substrates. Yangtze River Delta rolling mills supply regional aluminum foil inputs, creating cost volatility for converters elsewhere. Suzhou-based Perlen Packaging exemplifies foreign-invested production capacity serving domestic ethical pharmaceutical demand.
Japan
PMDA dimensional tolerance enforcement filters out non-specialized import suppliers for ethical pharmaceutical exporters. Osaka-based converters retrofit cold-form lines to capture premium margin pools for hygroscopic formulations. Kanto region pharmaceutical sponsors specify complete aluminum barrier laminates for tropical stability requirements.
South Korea
Direct-to-pharmacy distribution channels reshape procurement patterns for Seoul Capital Area hospital networks. MFDS oversight maintains stringent barrier-grade standards for oral solid dosage exports. Busan-Ulsan corridor converters serve both domestic ethical portfolios and contract manufacturing for multinational sponsors.
Australia and New Zealand
TGA compliance requirements and temperature-variable supply chains drive specification for moisture-resistant substrate formats. Amcor Limited leverages integrated film extrusion capabilities to sustain contract wins across Oceania markets. ANZ contract packaging organizations accelerate supplier audits to maintain NMPA export eligibility.
Asia Pacific Pharmaceutical Blister Packaging Market Competitive Landscape
The competitive structure tilts toward integrated material suppliers with captive film extrusion and forming capabilities. Tiered specialization separates premium cold-form aluminum laminates from commodity thermoformed PVC throughput. Three archetypes dominate: multinational converters with regional hub strategies, domestic specialists serving single-country regulatory corridors, and film manufacturers backward-integrating into forming equipment. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers position for NMPA and CDSCO qualification windows.
Among integrated packaging conglomerates, Amcor Limited and Constantia Flexibles occupy positions exemplifying multinational hub-and-spoke configurations. Klockner Pentaplast Group anchors the high-barrier film specialist archetype. Uflex Limited represents domestic Indian scale players competing on thermoformed volume throughput for generic export corridors. These three patterns—multinational integration, barrier-grade specialization, and domestic volume scale—capture the competitive topography across Asia Pacific pharmaceutical blister packaging.
| Leading Market Players |
|---|
| Klockner Pentaplast Group |
| Competent Packaging Industries Inc |
| Amcor Limited |
| Tekni-Plex Inc |
| Uflex Limited |
| Constantia Flexibles |
| Sonoco Products Company |
| Perlen Packaging (Suzhou) Co Ltd |
| WestRock Company |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consolidation across Maharashtra's Mumbai-Pune corridor anchors contract-based long-term offtake pricing for pharmaceutical blister packaging services. Japanese ethical pharmaceutical exporters absorb premium cold-form aluminum laminate costs through PMDA-mandated dimensional tolerance requirements that filter out lower-tier competitors.
Pricing Analysis
Service bundling separates integrated design-to-delivery partners from commodity converters across the Asia Pacific region. Three-tier pricing structure across premium cold-form laminates, standard high-barrier PVC, and economy thermoformed PET reflects certification-grade differentiation and volume scale. Cost compression in standard-tier thermoformed segments intensifies as Gujarat-based generic manufacturers consolidate vendor panels. Indian contract packaging organizations exhibit highest price sensitivity due to thin margin structures serving export markets, while Japanese ethical pharmaceutical sponsors prioritize barrier performance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from NMPA and CDSCO compliance programs force pharmaceutical sponsors to qualify multiple lidding foil converters across China, India, and Japan. Raw material flows draw from Yangtze River Delta aluminum rolling mills, Gujarat PVC resin plants, and Osaka specialty film extruders. Single-source vulnerability concentrates in precision cold-form tooling fabrication where regional machinery suppliers remain scarce. Distribution runs through contract packaging organization intermediaries serving hospital networks and direct-to-pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific pharmaceutical blister packaging functions as a stable compounder anchored by irreversible regulatory serialization mandates across China, India, and Japan that perpetually refresh equipment and material qualification cycles.
For Market Incumbents: Anticipate margin compression from NMPA serialization deadline acceleration by securing captive aluminum foil rolling capacity in Yangtze River Delta proximity. CDSCO aluminum cold-form mandate expansion for additional Schedule H categories threatens thermoformed volume positions; preemptive high-barrier equipment retrofit in Gujarat and Maharashtra corridors defends share against European import suppliers. For New Entrants and Emerging Players: Contract packaging organizations in Vietnam's emerging pharmaceutical manufacturing corridor represent the most penetrable entry point for track-ready barrier film qualification ahead of multinational sponsor China-plus-one sourcing decisions. Direct-to-pharmacy distribution channel partnerships with Seoul Capital Area hospital networks offer specialized cold-form laminate access without incumbent regulatory filing overhead. For Investors and Strategic Acquirers: Integrated film manufacturers with backward extrusion capabilities are the most active acquirer in this space, consolidating forming equipment operators to capture NMPA and CDSCO qualification windows. Target acquisition archetypes include Osaka and Seoul-based cold-form specialists with PMDA-compliant dimensional tolerance certifications. Watch MFDS barrier-grade standard tightening as the inflection signal for Korean market premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Track-Ready Barrier Film Integration | NMPA serialization mandates force substrate-ink co-qualification for machine-readability compliance. |
| Cold-Form Line Retrofit | Osaka and Seoul converters capture PMDA-compliant premium margins from hygroscopic formulation demand. |
| Dual-Country Qualification | Simultaneous CDSCO and NMPA certification expands addressable sponsor base across India-China export corridors. |
| Direct-to-Pharmacy Channel Partnership | Seoul hospital network e-procurement platforms bypass wholesale layers for margin retention. |
| Aluminum Foil Rolling Capacity Expansion | Yangtze River Delta concentration creates input cost volatility for non-integrated converters elsewhere. |
Research Methodology
Bottom-up pharmaceutical end-use modeling reconciled against top-down film extrusion and forming equipment tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at multinational drug sponsors, procurement managers at Indian hospital networks, technical directors at contract packaging organizations, and equipment specialists at regional machinery fabricators combined with secondary validation from NMPA and CDSCO filing databases, PMDA submission records, and customs trade data for aluminum foil and PVC resin flows.
Input-output matrices map cold-form and thermoformed blister volume to pharmaceutical dosage form, barrier-grade specification tier, and national regulatory cluster across the projection horizon. Segmentation dimensions include product type, material substrate, end-user archetype, and application focus. CAGRs derive from fitted growth curves calibrated to equipment installation cycles and serialization mandate enforcement timelines. Forecast inputs incorporate tropical stability demand patterns for Southeast Asian monsoon logistics and CDSCO Schedule H category expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA serialization deadline acceleration or delay, aluminum foil input cost volatility from Yangtze River Delta capacity fluctuations, and PMDA dimensional tolerance standard revisions. Deviation in multi-regulator timeline synchronization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
PVC Blister Packaging Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Blister Foil Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
North America Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Global Blister Packaging Market
Blister Packaging
Blister Paper Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Blister Packs Market