
 Pharma Blister Packaging Machines Market | 2026-2036
Pharma Blister Packaging Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Blister Packaging Machines Market Analytics
Contract packaging organizations is unwinding legacy manual workflows toward high-speed automated lines as pharmaceutical manufacturers outsource secondary packaging to reduce capital intensity. Uhlmann Packaging Group anchors its position through deep specialization in integrated cartoning-blister systems for regulated markets. ACG Worldwide competes aggressively on total cost of ownership across emerging market installations. Romaco Group leverages modular platform architectures that let buyers scale throughput without greenfield replacement.
Pharma blister packaging machines form, fill, and seal thermoplastic or cold-form laminate cavities around individual doses at speeds reaching 1,200 blisters per minute, with seal integrity validated against moisture vapor transmission thresholds. Their primary purpose is unit-dose protection, tamper evidence, and compliance with child-resistant senior-friendly regulations. High-speed machines dominate revenue contribution where large pharmaceutical manufacturers run continuous campaigns, while cold forming technology captures premium margin pools for hygroscopic and light-sensitive compounds requiring aluminum-aluminum barrier structures. Thermoforming retains volume leadership across standard PVC-PVDC tablet applications due to lower material cost and faster changeover.
FDA's 21 CFR Part 11 electronic records requirements, EU MDR traceability mandates, and EMA serialization directives under the Falsified Medicines Directive collectively force machine builders to embed vision inspection, aggregation, and data logging as standard rather than optional modules. Germany's KBA-equivalent machinery safety frameworks and REACH compliance for polymer contact materials add further specification layers for European-bound equipment. Stakeholders must weigh total validation burden against line flexibility when selecting between integrated monobloc systems and standalone blister-cell configurations.
Market Dynamics
Serialization mandates across the US, EU, and Saudi Arabia are forcing contract packaging organizations to replace legacy manual lines with integrated blister-cartoning systems that embed aggregation and vision inspection as standard modules.
Growth Catalysts
- EMA Falsified Medicines Directive:European serialization deadlines are accelerating replacement cycles for standalone blister cells with track-and-trace capable monobloc systems across Eastern European contract packagers.
- Thermoforming speed advantages:High-speed thermoforming lines are capturing volume from cold-form alternatives in standard oral solid dose applications where moisture sensitivity is moderate.
- German machinery exports:Equipment originating from Baden-Württemberg and Bavaria is serving dual demand from domestic pharmaceutical manufacturers and Polish contract packaging facilities.
Market Restraints
- Aluminum cold-form laminate cost volatility:Fluctuations in aluminum ingot pricing are compressing margins for barrier-intensive applications requiring aluminum-aluminum structures.
- Validation burden concentration:FDA 21 CFR Part 11 and EU MDR compliance documentation requirements are extending commissioning timelines by four to eight months for integrated lines.
- Skilled technician scarcity:Shortages of qualified validation engineers and servo-drive specialists are constraining installation throughput in North American and Western European markets.
Strategic Opportunities
- Indian CDMO expansion:Domestic contract development and manufacturing organizations are scaling secondary packaging capacity to capture outsourced work from Western pharmaceutical innovators.
- Biologic-compatible barrier films:Coextruded high-barrier thermoformable polymers are opening blister applications for humidity-sensitive biologic tablets previously restricted to cold-form aluminum.
- Saudi serialization readiness:SFDA track-and-trace implementation timelines are creating first-mover advantages for machinery suppliers pre-integrating aggregation software.
Industry Challenges
- Legacy MES integration friction:Brownfield pharmaceutical facilities are struggling to interface new blister line PLCs with existing manufacturing execution systems without custom middleware development.
- Multi-site qualification complexity:Pharmaceutical manufacturers operating distributed packaging networks face redundant IQ/OQ/PQ documentation burdens when standardizing equipment across FDA, EMA, and Health Canada jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Blister Packaging Machines Market |
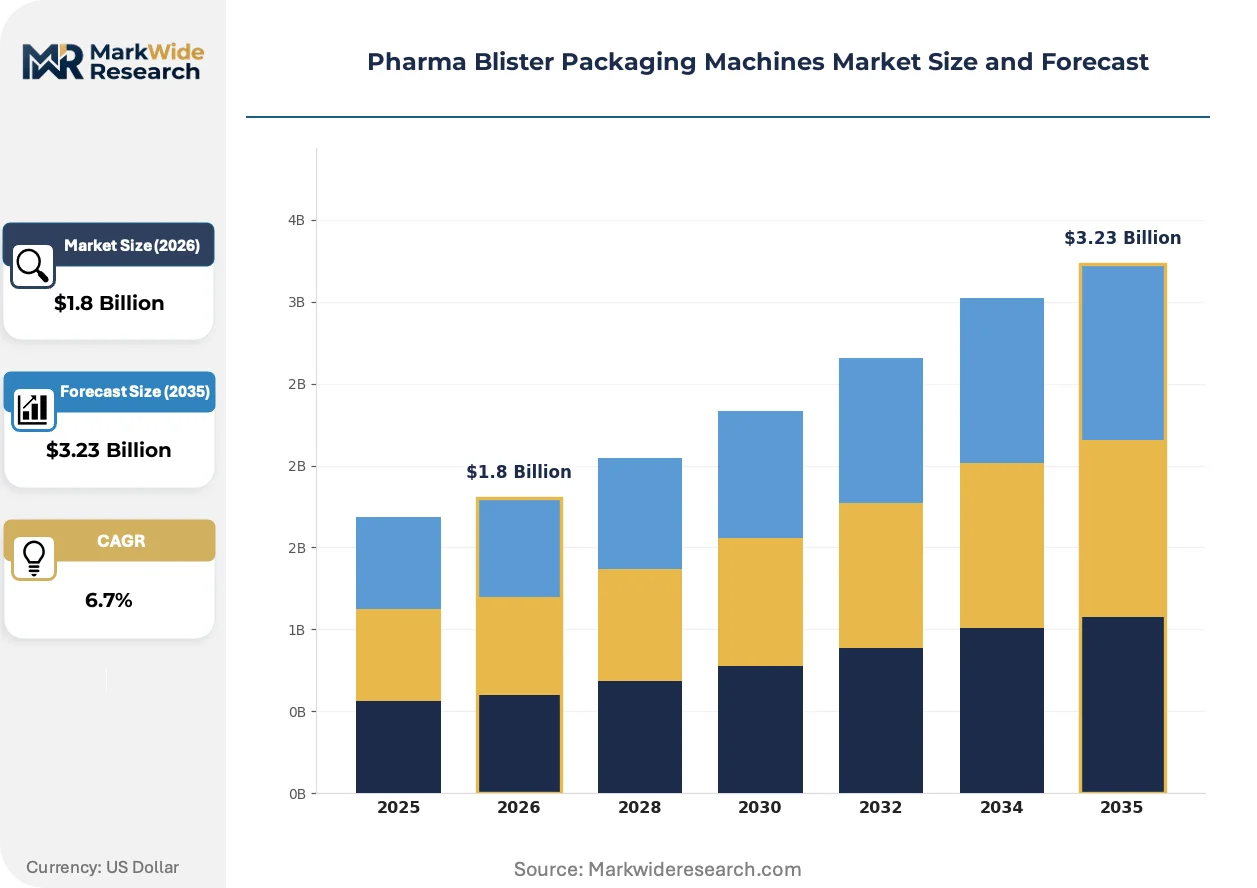
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed Machines, Semi-Automatic Machines, Manual Machines, Cold Forming Machines Technology: Thermoforming, Cold Forming, Vacuum Forming, Heat Sealing End User: Pharmaceutical Manufacturers, Contract Packaging Organizations, Biotechnology Firms, Nutraceutical Companies Application: Tablets, Capsules, Powders, Lozenges |
| Companies Covered | Romaco Group, Marchesini Group, Uhlmann Packaging Group, SED Pharma, CAM Packaging, IMA Group, ACG Worldwide, SaintyCo, Syntegon Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Blister Packaging Machines Market Evolving Landscape
Digital twin commissioning and predictive maintenance algorithms are compressing validation timelines while servo-driven format changeover systems are reducing campaign transition downtime from hours to minutes.
Continuous motion rotary sealing technology is displacing intermittent platen-based systems in high-volume oral solid dose facilities. Large pharmaceutical manufacturers running 24-hour campaigns are adopting these lines to eliminate the mechanical dwell time that constrains throughput. The shift is compressing total cost of ownership calculations for buyers comparing European and Asian equipment suppliers.
EU MDR traceability mandates and FDA's evolving guidance on data integrity are forcing machine builders to embed audit trail functionality at the PLC level rather than as bolt-on software modules. Equipment shipped into European markets must now demonstrate compliance with both CE machinery safety frameworks and REACH substance restrictions for polymer contact materials. German and Italian manufacturers are responding by pre-certifying control architectures through notified body partnerships.
Pharmaceutical procurement functions are unbundling after-sales service contracts from equipment purchase agreements, creating standalone service markets for validation support and spare parts logistics. Contract packaging organizations are driving this shift to reduce capital intensity and convert fixed maintenance costs to variable structures. The pattern is most pronounced among mid-sized CDMOs in Poland and the Czech Republic seeking operational flexibility.
Pharma Blister Packaging Machines Market Segmentation
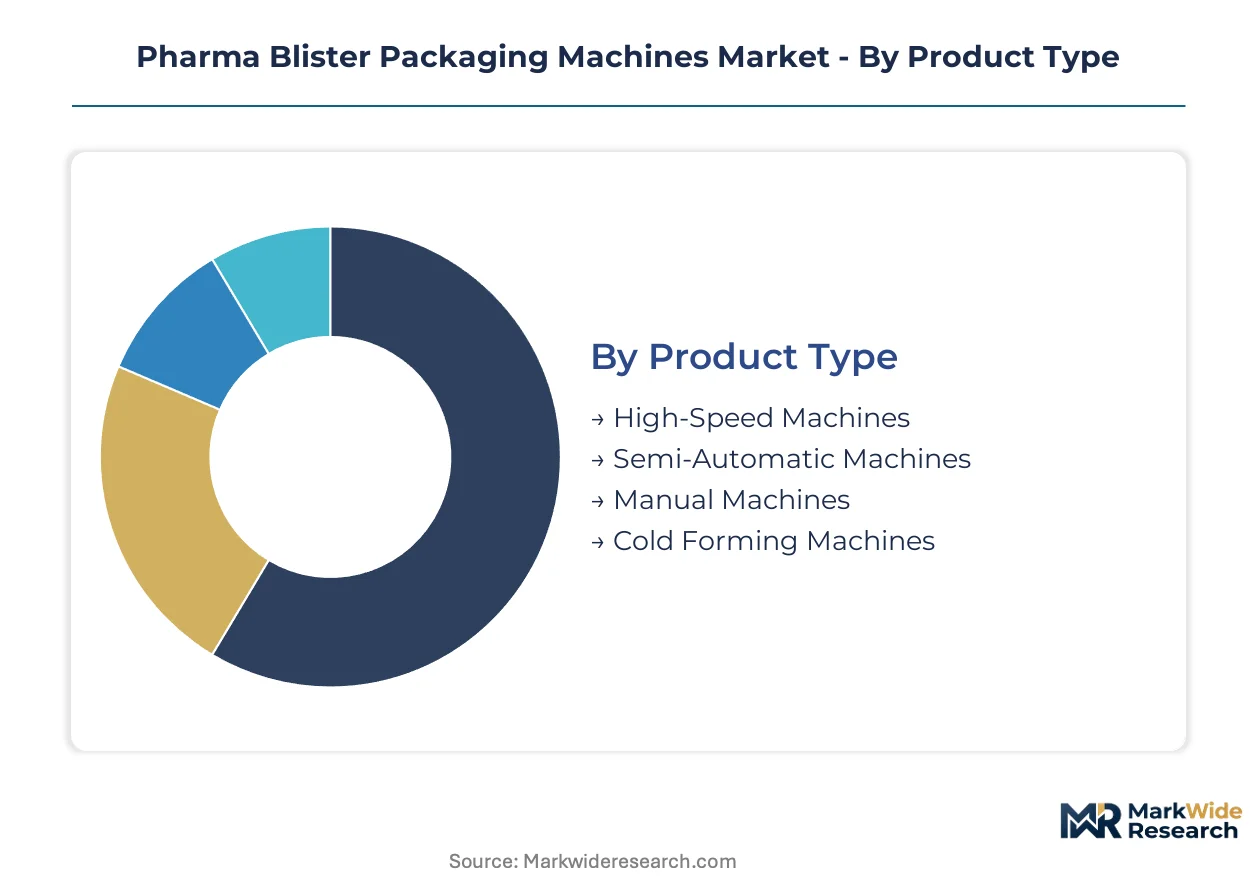
Segmentation in pharma blister packaging machines reveals distinct margin pools tied to regulatory complexity, throughput requirements, and barrier specifications. Technology and end-user splits matter most for procurement strategy, while product type dictates total cost of ownership calculations.
Product Type:
Premium margins concentrate in high-speed and cold forming configurations where validation documentation and barrier performance justify pricing power.
- High-Speed Machines:Continuous motion rotary systems achieve throughput exceeding 1,200 blisters per minute with servo-driven format changeover. Large pharmaceutical manufacturers in Germany and the United States deploy these for 24-hour oral solid dose campaigns where downtime costs dominate economics.
- Cold Forming Machines:Aluminum-aluminum laminate structures deliver moisture vapor transmission rates below 0.01 g/m²/day for hygroscopic compounds. Demand from Swiss and Austrian innovators running humidity-sensitive portfolios sustains margin premiums despite aluminum ingot price volatility.
- Semi-Automatic Machines:Intermediate throughput solutions serve mid-sized CDMOs in Poland and the Czech Republic balancing flexibility against capital constraints.
- Manual Machines:Legacy equipment persists in small-batch clinical trial packaging and emerging market installations where serialization mandates have not yet enforced automation.
The dominant share belongs to High-Speed Machines, while Cold Forming Machines is closing the gap fastest.
Technology:
Technology selection hinges on barrier requirements versus speed economics, with thermoforming commanding volume leadership and cold forming capturing specialty value.
- Thermoforming:PVC-PVDC and Aclar laminates form cavities through radiant or contact heating with cycle times under 2 seconds. Standard tablet applications across Indian and Chinese pharmaceutical manufacturers favor this route for material cost efficiency and rapid tooling changeover.
- Cold Forming:Deep-drawn aluminum structures eliminate moisture ingress without desiccant dependence. German and Italian machinery builders specialize in these systems for European markets where EMA stability requirements drive barrier investment.
- Vacuum Forming:Slower cycle alternative for shallow-draw applications with moderate barrier needs, common in nutraceutical packaging.
- Heat Sealing:Critical sub-process technology integrated across all forming types, with lidding seal strength validated against USP <1207> container closure integrity standards.
Thermoforming retains volume leadership, though Cold Forming is expanding most quickly in biologic tablet applications.
End User:
Procurement authority and validation burden distribution vary sharply between captive pharmaceutical operations and outsourced packaging services.
- Contract Packaging Organizations:CDMOs and dedicated packagers drive demand for integrated blister-cartoning-serialization monoblocs. Polish and Czech facilities are replacing standalone cells to meet EU Falsified Medicines Directive deadlines while serving Western European pharmaceutical innovators.
- Pharmaceutical Manufacturers:Captive packaging lines at large innovators prioritize OEE metrics and continuous motion technology. German domestic manufacturers anchor regional machinery demand alongside export-oriented equipment purchases.
- Biotechnology Firms:Emerging demand segment requiring specialized barrier configurations for humidity-sensitive biologic tablets, often sourcing from Swiss and German precision equipment suppliers.
- Nutraceutical Companies:Price-sensitive purchasers favoring semi-automatic thermoforming configurations with reduced validation documentation requirements.
Contract Packaging Organizations command the largest equipment procurement volume, while Biotechnology Firms is gaining share fastest.
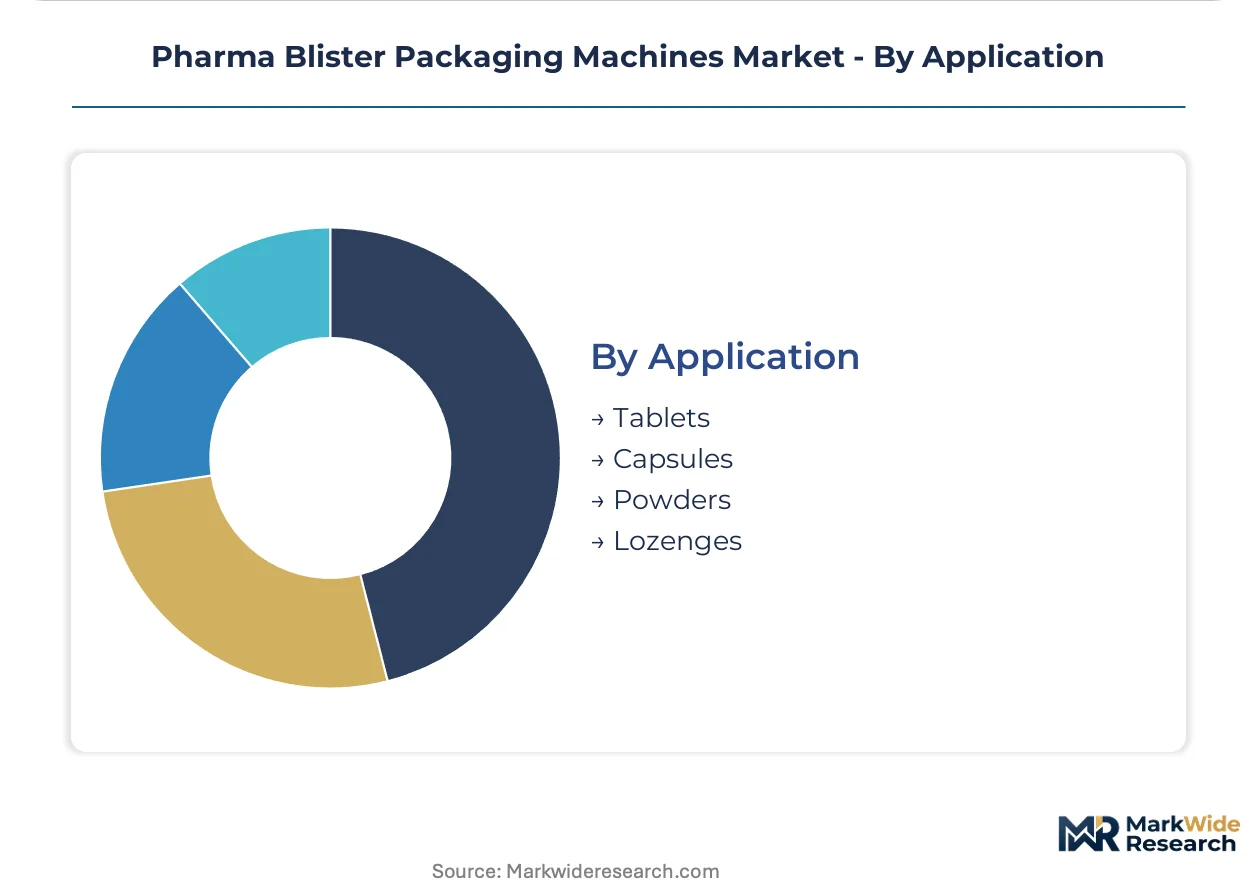
Application:
Product form factor determines cavity geometry, forming depth, and lidding material selection across machine configurations.
- Tablets:Flat-faced or biconvex geometries dominate blister cavity design, with deep-draw requirements for large-dose formulations driving cold forming adoption. US and German solid dose manufacturers standardize on high-speed thermoforming for immediate-release portfolios.
- Capsules:Cylindrical cavity profiles require precise forming depth control to prevent cap-body separation. Gelatin and HPMC capsule formats sustain consistent machinery demand across European and North American markets.
- Powders:Sachet-compatible blister configurations with enhanced seal integrity for hygroscopic formulations, niche application concentrated in respiratory and pediatric delivery systems.
- Lozenges:Specialized tooling for larger cavity volumes, primarily serving over-the-counter and throat care segments with lower throughput requirements.
Tablets holds the dominant application share, while Capsules is climbing the fastest on biologic delivery expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's machinery export dominance, connecting Bavarian and Baden-Württemberg manufacturing clusters to North Sea ports and Eastern European markets.
Germany
Domestic pharmaceutical manufacturers and Polish contract packagers drive dual demand for high-speed thermoforming lines. KBA machinery safety frameworks and REACH polymer compliance specifications shape equipment design requirements. Stuttgart and Karlsruhe machinery builders pre-certify control architectures through notified body partnerships to accelerate EU market entry.
United States
FDA 21 CFR Part 11 electronic records mandates force replacement of legacy standalone blister cells with integrated serialization-ready systems. Large pharmaceutical manufacturers in New Jersey and North Carolina prioritize continuous motion rotary technology for 24-hour oral solid dose campaigns. Skilled validation engineer shortages constrain installation throughput across Midwest packaging corridors.
India
Domestic CDMOs scale secondary packaging capacity to capture outsourced work from Western innovators. CDSCO track-and-trace readiness requirements accelerate automation adoption across Maharashtra and Gujarat pharmaceutical zones. Mumbai-Pune machinery distributors report surging procurement of semi-automatic configurations balancing flexibility against capital constraints.
Switzerland
Swissmedic stability requirements sustain premium demand for cold-form aluminum-aluminum barrier systems protecting hygroscopic compounds. Precision equipment sourcing concentrates around Basel and Zurich innovation clusters serving humidity-sensitive biologic tablet portfolios. Domestic innovators accept margin premiums to secure validated moisture vapor transmission performance below 0.01 g/m²/day.
Saudi Arabia
SFDA serialization implementation timelines create first-mover advantages for machinery suppliers pre-integrating aggregation software. Riyadh and Jeddah pharmaceutical packaging facilities replace manual workflows ahead of enforcement deadlines. Gulf distribution networks position the kingdom as a re-export hub serving UAE and Kuwait contract packaging demand.
Pharma Blister Packaging Machines Market Competitive Landscape
Concentration sits with integrated systems specialists serving regulated pharmaceutical markets. The vendor base stratifies across three tiers: German and Italian precision builders commanding premium pricing for validated monobloc configurations, Indian and Chinese fabricators competing on total cost of ownership for emerging market installations, and modular platform specialists enabling throughput scaling without greenfield replacement. Dominant competitive moves include backward integration into control software development and geographic expansion through Eastern European service hub establishment.
Among German precision builders, Uhlmann Packaging Group and Romaco Group exemplify the integrated systems archetype through deep specialization in cartoning-blister combinations for FDA and EMA jurisdictions. ACG Worldwide occupies a position within the emerging market cost-optimization tier, while Marchesini Group represents Italian engineering precision serving Swiss and Austrian barrier-intensive applications.
| Leading Market Players |
|---|
| Romaco Group |
| Marchesini Group |
| Uhlmann Packaging Group |
| SED Pharma |
| CAM Packaging |
| IMA Group |
| ACG Worldwide |
| SaintyCo |
| Syntegon Technology |
| Others |
Value Network & Pricing Analysis
Aluminum cold-form laminate substitution by coextruded high-barrier thermoformable polymers is redrawing procurement geography toward Indian polymer compounders while compressing barrier-premium pricing tiers for European machinery builders. This material pivot simultaneously erodes Swiss and Austrian margins on aluminum-intensive systems and opens volume opportunities for thermoforming specialists serving humidity-sensitive biologic tablet portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers capturing validation documentation and CE-notified body pre-certification, standard tiers competing on total cost of ownership, and economy tiers serving emerging market CDMOs with reduced after-sales bundling. Price differentiation rests on servo-drive precision and serialization module integration, with German and Italian builders commanding premiums against Indian and Chinese fabricators. Cost compression in standard-tier thermoforming lines is intensifying because of aluminum ingot price volatility feeding through to cold-form alternatives. Contract packaging organizations in Poland and the Czech Republic exhibit highest price sensitivity, while Swiss biotechnology firms accept steepest premiums for moisture vapor transmission guarantees below 0.01 g/m²/day.
Supply Chain Analysis
Inventory lead times for servo-drive components and vision inspection modules extend equipment delivery windows, forcing German and Italian builders to pre-position control hardware in Eastern European service hubs. Manufacturing concentration centers on Germany, Italy, and India, with Baden-Württemberg and Bavaria anchoring precision engineering, Emilia-Romagna specializing in barrier-intensive configurations, and Maharashtra scaling semi-automatic production. Component sourcing draws from Japanese servo-motor suppliers, German PLC manufacturers, and Chinese aluminum laminate processors. Single-source vulnerability in high-resolution camera modules for serialization validation threatens commissioning schedules. Distribution runs through machinery distributors in Mumbai-Pune and direct OEM relationships for large pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as serialization mandates splinter demand across integrated monobloc systems, modular platform upgrades, and standalone validation services, creating distinct competitive arenas for capital-intensive incumbents, agile regional fabricators, and software-native entrants.
For Market Incumbents: Shield installed base revenue by embedding predictive maintenance algorithms and digital twin commissioning as subscription layers, converting one-time equipment sales to recurring service income. Counter modular platform specialists by pre-certifying control architectures through notified body partnerships to compress EU market entry timelines. Vertical integration into PLC-level audit trail software development defends against software-native entrants unbundling after-sales contracts. For New Entrants and Emerging Players: After-sales service unbundling by mid-sized CDMOs creates white-space for standalone validation support and spare parts logistics specialists. Target Saudi Arabian contract packagers pre-integrating SFDA aggregation software ahead of enforcement deadlines. Penetrate through validation-engineer-as-a-service models addressing skilled technician scarcity constraining North American installation throughput. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed German precision builders seeking exit liquidity after multi-year hold periods. Long-term viability favors platforms with biologic-compatible barrier film capabilities as humidity-sensitive tablet portfolios expand. Watch Indian CDMO capital expenditure announcements as inflection indicator for semi-automatic and mid-speed equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Machine builders embedding PLC-level audit trails capture recurring revenue from FDA 21 CFR Part 11 compliance mandates. |
| Eastern European Service Hub Establishment | Polish and Czech facilities reduce lead times for serialization module commissioning across EU Falsified Medicines Directive deadlines. |
| Biologic-Compatible Barrier Film Development | Coextruded polymer R&D opens thermoforming applications for humidity-sensitive compounds previously restricted to cold-form aluminum. |
| Digital Twin Commissioning Deployment | Predictive maintenance algorithms compress validation timelines and convert equipment sales to subscription-based service contracts. |
| Saudi Serialization Software Pre-Integration | Aggregation module bundling creates first-mover advantage ahead of SFDA track-and-trace enforcement timelines. |
Research Methodology
Operator-level perspectives from packaging line engineers, validation specialists, CDMO procurement directors, and pharmaceutical manufacturing heads anchored the qualitative base. Primary interviews triangulated against secondary sources including FDA 21 CFR Part 11 guidance documents, EMA Falsified Medicines Directive implementation reports, CDSCO track-and-trace circulars, and machinery safety frameworks from Germany's KBA-equivalent bodies. Bottom-up equipment shipment data from Bavarian and Baden-Württemberg manufacturing clusters converged with top-down pharmaceutical packaging capacity expansion announcements across the analysis window.
Sensitivity analysis tested forecast robustness against aluminum ingot price volatility, skilled technician availability constraints, and regulatory deadline shifts. Segmentation modeling spanned technology type, product configuration, end-user archetype, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, serialization mandate phase-in schedules, and biologic tablet portfolio expansion trajectories. Forecast inputs incorporated continuous motion rotary sealing adoption curves and cold-form barrier premium erosion rates.
Forecasts assume regulatory continuity in FDA, EMA, and SFDA serialization regimes; material policy shifts would require re-modeling compliance timeline impacts on replacement demand. Aluminum laminate cost volatility and validation engineer scarcity present specific revision triggers. Revision becomes warranted when CDMO capital expenditure announcements in India and Saudi Arabia cross threshold densities indicating demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
North America Pharmaceutical Blister Packaging Market
Blister Packaging
Asia Pacific Blister Packaging Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Liquid Blister Pack Market
Blister Packaging
Ampoules and Blister Packaging Market
Blister Packaging
Blister Cards Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Sliding Blister Packaging Market
Blister Packaging
North America Blister Packaging Market