
 United States Blister Packaging Market | 2026-2036
United States Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United States Blister Packaging Market Analytics
Tool-and-die engineering talent is bifurcating between legacy thermoforming shops and digital-ready converters, constraining capacity expansion across the Midwest. Amcor PLC leverages captive resin partnerships to sustain film supply security for pharmaceutical clients. Berry Global Group, Inc. anchors its position through high-speed form-fill-seal infrastructure across Tennessee and Ohio. Tekni-Plex, Inc. specializes in multi-layer barrier films that compete on moisture and oxygen protection for sensitive drug products.
Blister packaging in the United States denotes a pre-formed plastic cavity sealed to a lidding substrate—typically aluminum foil or paper-backed film—via heat or pressure, with cavity depths ranging from 0.5 mm to 12 mm depending on product geometry. The format serves primary functions of unit-dose protection, child-resistance compliance, and shelf visibility across retail and clinical channels. Clamshell configurations dominate theft-deterrent applications in consumer electronics, while cold-form aluminum blisters capture premium margin pools in pharmaceutical moisture-barrier segments. Thermoformed plastic formats lead volume across food and personal care, though rigid PVC alternatives face substitution pressure from PET-G and recycled-content films.
FDA serialization mandates under the Drug Supply Chain Security Act reshape lidding substrate specifications, driving track-and-trace compatibility investments. EPA guidelines on recycled-content thresholds and state-level extended producer responsibility frameworks in California and Maine alter material sourcing calculus for national converters. Stakeholders must monitor state-by-state packaging fee structures and resin certification standards to avoid stranded capacity commitments.
Market Dynamics
Pharmaceutical serialization mandates under the FDA's Drug Supply Chain Security Act are compressing converter timelines while reshaping lidding substrate specifications across the Northeast contract packaging corridor.
Growth Catalysts
- Unit-dose compliance:FDA DSCSA track-and-trace requirements accelerate tamper-evident format adoption across branded drug distribution networks.
- Barrier film innovation:Multi-layer coextrusion advances enable moisture and oxygen protection for biologic stability in cold-chain applications.
- Recycled-content thresholds:EPA guidelines and state-level extended producer responsibility frameworks in California and Maine drive material certification investments.
Market Restraints
- Resin price volatility:PVC and PET-G feedstock costs fluctuate with petrochemical capacity constraints, squeezing converter margins.
- Tool-and-die scarcity:Bifurcation of thermoforming engineering talent between legacy shops and digital-ready converters limits Midwest capacity expansion.
- Substitution pressure:Rigid PVC formats face displacement from PET-G and post-consumer recycled films in food and personal care segments.
Strategic Opportunities
- Biologics packaging:Cold-form aluminum blisters capture premium positioning for moisture-sensitive injectable and oral solid dose products.
- Clamshell diversification:Theft-deterrent configurations extend into high-value consumer electronics retail channels beyond traditional pharma.
- State-level EPR alignment:California and Maine packaging fee structures create first-mover advantages for certified recycled-content film suppliers.
Industry Challenges
- Serialization integration:Legacy form-fill-seal lines require capital-intensive retrofitting for track-and-trace compatibility with new lidding specifications.
- Cross-state compliance:Divergent extended producer responsibility fee structures and resin certification standards complicate national capacity planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Blister Packaging Market |
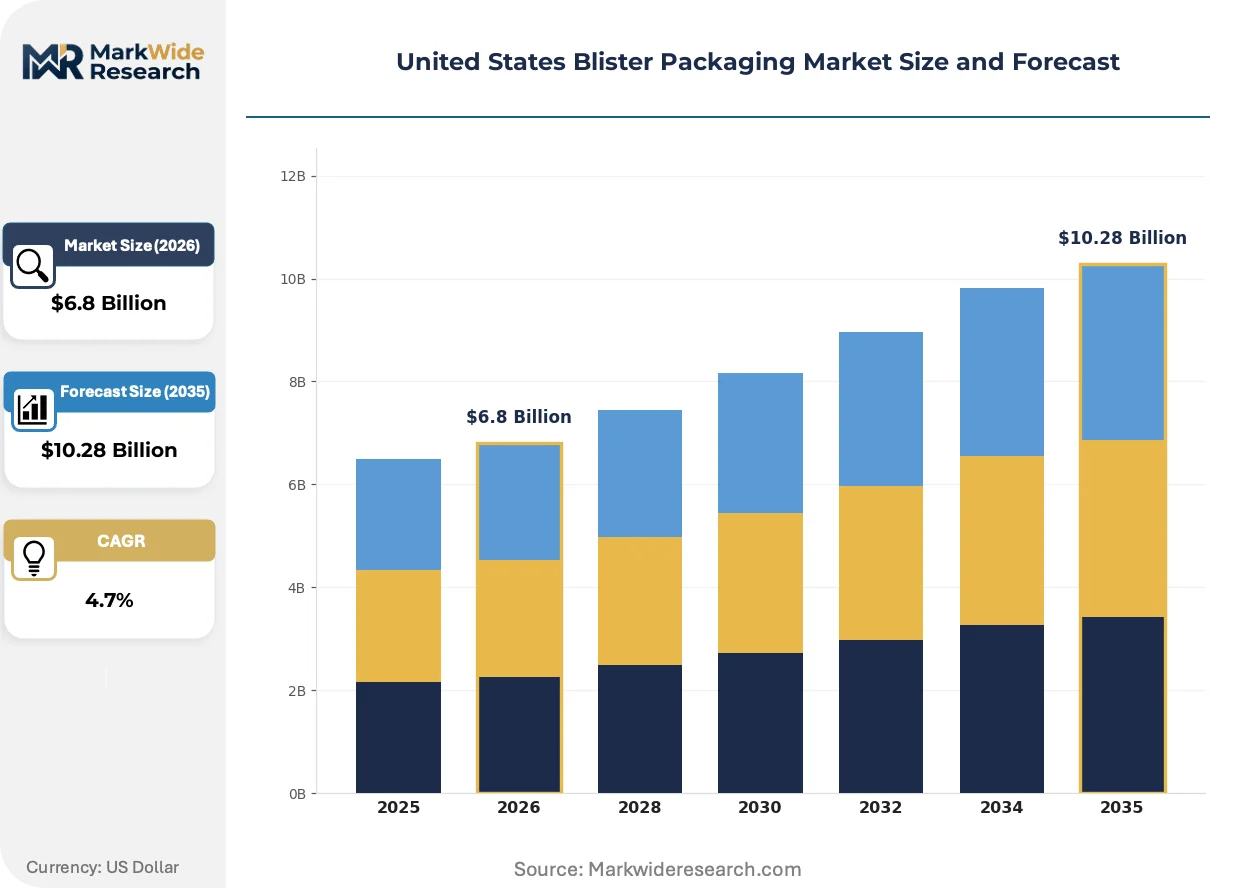
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshell, Skin Pack, Standard Blister, Carded Blister Material: Plastic, Aluminum, Paper, PVC End User: Pharmaceutical, Food & Beverage, Consumer Electronics, Personal Care Packaging Type: Thermoformed, Cold Form, Rigid, Flexible |
| Companies Covered | Constantia Flexibles, Honeywell International Inc., Amcor PLC, Berry Global Group, Inc., Tekni-Plex, Inc., WestRock Company, Klöckner Pentaplast, Winpak Ltd., Sonoco Products Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Blister Packaging Market Evolving Landscape
Digital printing and smart packaging integration are reconfiguring how converters deliver traceability and brand differentiation without sacrificing line speed or barrier performance.
Digital printing on lidding substrates is fragmenting the traditional pre-printed foil supply chain by enabling lot-specific variable data and anti-counterfeiting features at production speed. Mid-size pharmaceutical contract packers in New Jersey and Pennsylvania are adopting this capability to compress lead times for short-run branded products. The technology is fragmenting converter-customer relationships from volume-based contracts toward flexible, serialization-ready partnerships.
FDA Drug Supply Chain Security Act Phase II implementation tightens aggregation requirements for unit-level traceability, forcing investments in vision systems and data infrastructure. Converters must now validate lidding substrate compatibility with 2D barcode readability and tamper-evidence verification. The regulation most directly impacts high-volume oral solid dose producers in the Northeast corridor, where packagers are consolidating supplier bases to reduce validation burden.
Buyer concentration among top-tier pharmaceutical distributors is compressing switching cycles and unbundling after-sales technical support from material supply agreements. Large contract packaging organizations now demand dedicated engineering resources and rapid prototype turnaround as table stakes. This pattern is most pronounced in the Tennessee and Ohio manufacturing belts, where Berry Global and regional competitors anchor high-speed infrastructure.
United States Blister Packaging Market Segmentation
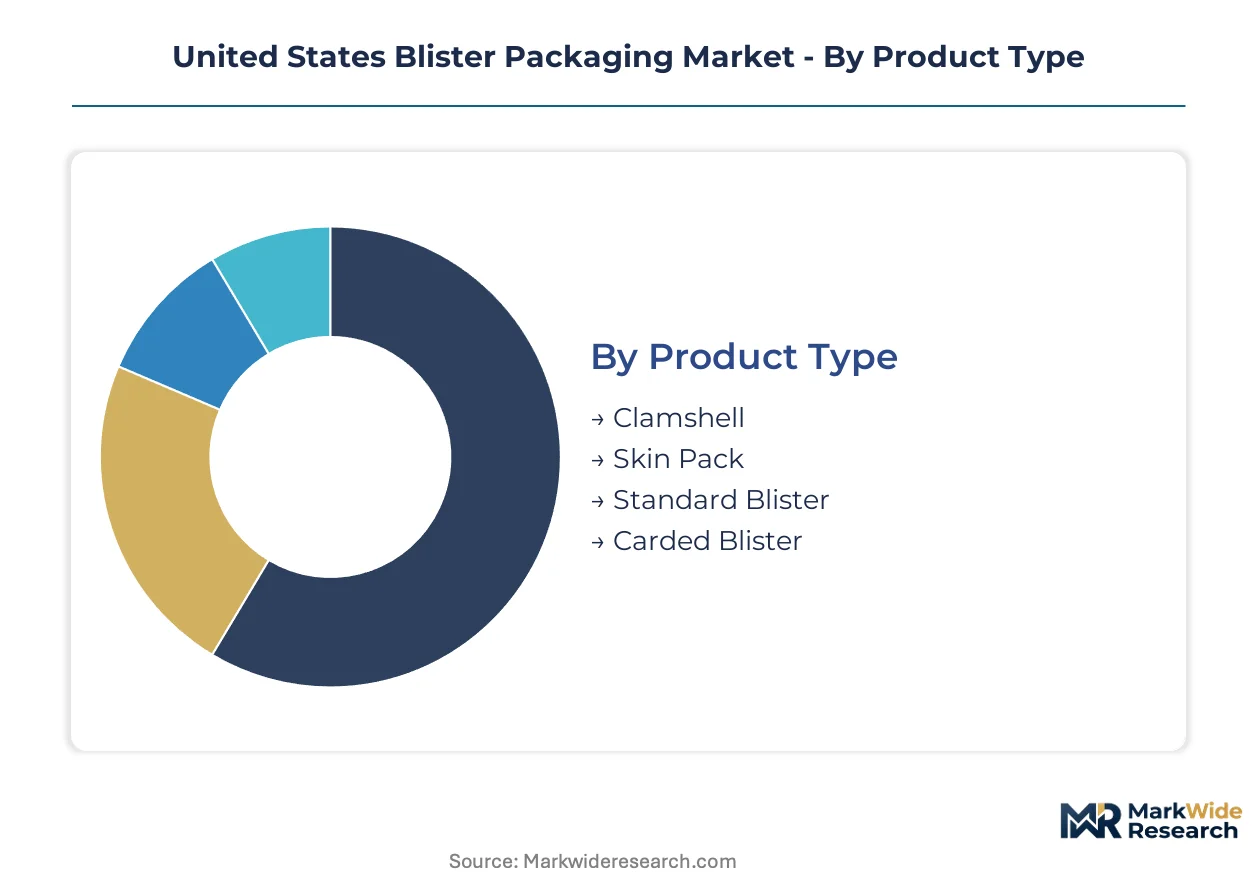
Blister packaging segmentation in the United States reflects divergent regulatory pressures across FDA pharmaceutical mandates, EPA material guidelines, and state-level extended producer responsibility frameworks. Each dimension carries distinct compliance costs and geographic concentration patterns that reshape converter investment priorities.
Product Type:
FDA Drug Supply Chain Security Act serialization requirements differentiate tamper-evident formats from standard configurations through validation burden and track-and-trace infrastructure.
- Standard Blister:Heat-sealed plastic cavity with aluminum foil lidding dominates oral solid dose pharmaceutical distribution. Northeast contract packers in New Jersey and Pennsylvania anchor demand for validated serialization-ready formats serving branded drug makers.
- Clamshell:Hinged thermoformed shells with perimeter sealing deliver theft-deterrent protection for high-value retail applications. Consumer electronics channels in California and Texas drive adoption where visible product display must coexist with loss prevention.
- Skin Pack:Vacuum-formed film bonded to printed card backing serves hardware and automotive aftermarket segments with lower barrier requirements than pharmaceutical grades.
- Carded Blister:Heat-sealed film-to-cardboard construction balances visibility with cost efficiency in personal care and over-the-counter health products.
Established volume favors Standard Blister; emerging adoption favors Clamshell.
Material:
Cost tier stratification separates commodity resin grades from certified recycled-content films required by California and Maine extended producer responsibility statutes.
- PVC:Rigid vinyl films offer clarity and thermoforming ease but face substitution pressure from PET-G and post-consumer recycled alternatives. Food and personal care converters in the Midwest are phasing out virgin PVC to preempt state-level packaging fees.
- Plastic:PET-G and APET films provide superior impact resistance and recycling compatibility versus legacy vinyl. Tennessee and Ohio form-fill-seal infrastructure has retooled toward these grades to serve pharmaceutical and electronics clients demanding sustainability credentials.
- Aluminum:Cold-form foil blisters deliver moisture and oxygen barrier protection for biologic stability in injectable and oral solid dose cold-chain applications.
- Paper:Fiber-based lidding substrates gain traction in food segments where compostability certifications offset higher unit costs against landfill diversion targets.
Cost concentration favors PVC; regulatory alignment favors Plastic.
End User:
Application-specific barrier requirements and serialization mandates create divergent margin pools across pharmaceutical compliance and consumer goods visibility.
- Pharmaceutical:Unit-dose primary packaging for oral solids, injectables, and biologics demands multi-layer barrier films and tamper-evident lidding validated for FDA track-and-trace readability. Northeast corridor contract packers concentrate validation resources on high-volume branded drug distribution networks.
- Consumer Electronics:Theft-deterrent clamshell and blister formats protect high-value retail inventory while enabling shelf visibility. Demand clusters in California and Texas retail corridors where loss prevention intersects with unboxing experience requirements.
- Food & Beverage:Modified atmosphere and vacuum skin formats extend shelf life for fresh proteins and prepared meals with lower regulatory burden than pharmaceutical grades.
- Personal Care:Single-use sachets and sample formats prioritize cost efficiency and retail presence over extended barrier protection.
Margin concentration favors Pharmaceutical; volume expansion favors Consumer Electronics.
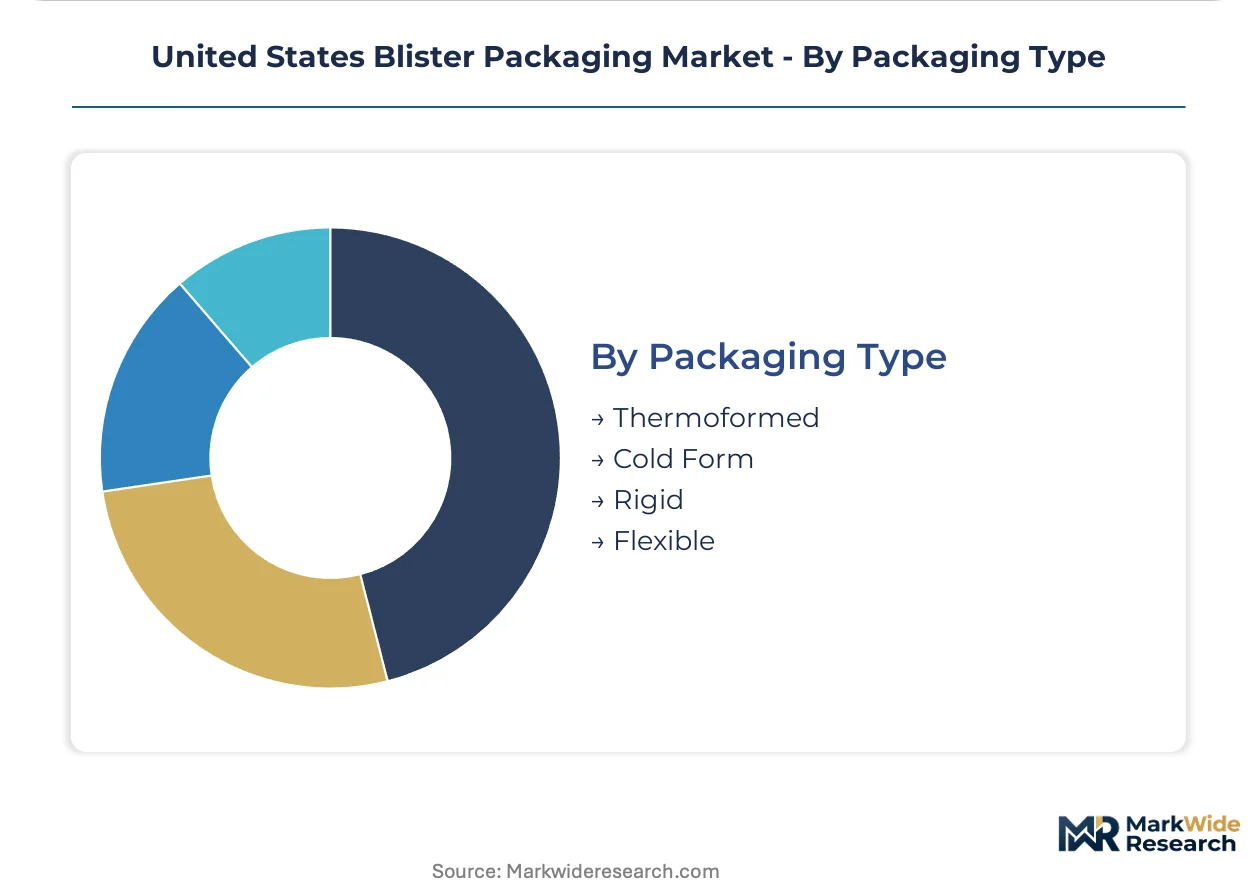
Packaging Type:
Manufacturing process selection determines capital intensity, barrier performance, and compatibility with recycled-content film specifications.
- Thermoformed:Heat-and-vacuum shaping of plastic sheet dominates volume across food, personal care, and standard pharmaceutical applications. Midwest converter capacity concentrates on high-speed lines serving retail and clinical channels with 0.5 mm to 12 mm cavity depths.
- Cold Form:Aluminum-based deep-drawn cavities without heat exposure capture premium positioning for moisture-sensitive pharmaceutical products. FDA serialization mandates require specialized lidding compatibility for 2D barcode readability in these formats.
- Rigid:Pre-formed containers with snap-fit or heat-seal closures serve durable goods and electronics where structural protection exceeds barrier requirements.
- Flexible:Form-fill-seal rollstock configurations optimize material efficiency for high-volume food and personal care segments with shorter shelf-life requirements.
Capacity deployment favors Thermoformed; premium positioning favors Cold Form.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast corridor consumes blister packaging through pharmaceutical serialization mandates, while the Midwest and Southeast deploy the format across food, electronics, and industrial channels with lighter regulatory burden.
Northeast Corridor
New Jersey and Pennsylvania contract packers anchor pharmaceutical demand for FDA DSCSA-compliant unit-dose formats. State-level packaging fees in Maine drive certified recycled-content film sourcing decisions. Boston's biotech cluster accelerates cold-form aluminum blister adoption for moisture-sensitive injectables.
Southeast
Tennessee and Georgia high-speed form-fill-seal infrastructure serves branded consumer goods and over-the-counter health products. EPA recycled-content guidelines influence resin certification investments across regional converters. Atlanta's logistics hub distributes thermoformed formats to retail channels throughout the Sun Belt.
Midwest
Ohio and Illinois converters face tool-and-die engineering scarcity that constrains capacity expansion across legacy thermoforming operations. State environmental agencies in Michigan enforce resin certification standards that complicate material sourcing. Chicago's contract packaging belt balances pharmaceutical validation with food-grade volume production.
California
Los Angeles and Bay Area electronics manufacturers drive clamshell adoption for theft-deterrent retail packaging of high-value consumer devices. The state's extended producer responsibility framework imposes packaging fee structures that favor post-consumer recycled film suppliers. San Diego's medical device cluster sources barrier-grade formats for sterile instrument kits.
Texas
Dallas-Fort Worth and Houston distribution networks channel blister packaging into oilfield equipment and automotive aftermarket segments with lower barrier requirements. State-level environmental regulations lag California and Maine, reducing compliance-driven material switching. Austin's consumer electronics retail corridor demands visible product display formats with loss-prevention features.
United States Blister Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the United States blister packaging market. Consolidated film suppliers and diversified packaging conglomerates control upstream resin partnerships and high-speed converting infrastructure. Specialist archetypes include multi-layer barrier film developers, regional contract packers with validation expertise, and digital-printing-enabled converters serving short-run pharmaceutical clients. Competitive moves center on captive resin supply security and serialization-ready line retrofitting.
Among integrated packaging conglomerates, Amcor PLC and Berry Global Group, Inc. exemplify scale-driven positions anchored in captive supply chains and multi-state manufacturing footprints. Tekni-Plex, Inc. occupies a specialist tier focused on barrier film technology. These three entities represent distinct competitive archetypes: resin-integrated volume leadership, high-speed infrastructure dominance, and technical specialization in moisture-sensitive applications.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Honeywell International Inc. |
| Amcor PLC |
| Berry Global Group, Inc. |
| Tekni-Plex, Inc. |
| WestRock Company |
| Klöckner Pentaplast |
| Winpak Ltd. |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
FDA Drug Supply Chain Security Act serialization requirements gate both supplier qualification and price differentiation simultaneously, as converters must validate lidding substrate compatibility for track-and-trace readability before securing pharmaceutical contracts. This regulatory threshold stratifies the market between validated premium tiers and commodity formats, with certification investments becoming the primary price discrimination mechanism across the Northeast contract packaging corridor.
Pricing Analysis
Long-term offtake agreements dominate pharmaceutical supply relationships, with branded drug makers locking in multi-year contracts for serialization-ready formats to amortize validation costs. Price differentiation separates FDA-validated cold-form aluminum blisters from standard thermoformed configurations, with barrier-grade films commanding premiums based on moisture protection performance and 2D barcode readability certification. Cost compression in commodity PVC and PET-G segments is intensifying because resin price volatility squeezes converter margins without corresponding pass-through mechanisms. Generic oral solid dose producers exhibit the highest price sensitivity, while biologic drug developers prioritize barrier performance over unit cost.
Supply Chain Analysis
Port congestion across the Houston-Galveston and Los Angeles-Long Beach trade lanes elevates inbound logistics costs for imported resin grades, particularly specialty barrier films sourced from European and Asian suppliers. Domestic supply concentrates in Texas, Louisiana, and Pennsylvania petrochemical corridors for base resins, with specialty multi-layer films drawing from South Korean and German converter networks. Raw material dependencies center on PVC and PET-G feedstocks, aluminum foil for cold-form applications, and adhesive coatings for lidding substrates. Single-source vulnerability in pharmaceutical-grade film supply creates exposure to regional production disruptions. Distribution runs through contract packaging clusters in New Jersey, Pennsylvania, and Tennessee before final sterilization and assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States blister packaging market rewards converters who control scarce tool-and-die engineering capacity and FDA validation expertise, as legacy thermoforming shops face displacement by digital-ready competitors. This capability gap creates asymmetric returns for stakeholders who secure specialized talent pools before regional expansion accelerates.
For Market Incumbents: Secure captive resin partnerships to insulate pharmaceutical clients from petrochemical price volatility, particularly for PVC and PET-G grades facing substitution pressure. Consolidate validation resources around high-volume branded drug networks in the Northeast corridor to reduce customer switching. Defend against digital-printing-enabled mid-size competitors by embedding rapid prototype turnaround into standard service agreements. For New Entrants and Emerging Players: Differentiate on certified recycled-content film supply to capture California and Maine extended producer responsibility compliance premiums before national fee structures expand. Target the consumer electronics clamshell segment in Texas and California retail corridors, where theft-deterrent requirements outpace pharmaceutical regulatory burden. Pursue white-label digital printing partnerships with New Jersey and Pennsylvania contract packers seeking serialization-ready short-run flexibility. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cold-form aluminum blister manufacturing as FDA aggregation requirements demand vision system retrofits and data infrastructure investments. Long-term viability favors converters with backward integration into multi-layer barrier film production or captive resin supply chains. Acquisition targets should display validated pharmaceutical customer relationships and tool-and-die engineering depth. Monitor state-level extended producer responsibility adoption as the signal to watch for recycled-content film demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Film Production | Captive supply of multi-layer films insulates pharmaceutical margins from resin volatility. |
| Serialization-Ready Line Retrofitting | FDA DSCSA Phase II compliance enables continued access to high-margin branded drug contracts. |
| Recycled-Content Film Certification | California and Maine EPR alignment creates first-mover pricing power in sustainability-driven segments. |
| Digital Printing Capability Expansion | Lot-specific variable data compresses lead times for short-run pharmaceutical contract packers. |
| Cold-Form Aluminum Capacity Addition | Moisture-sensitive biologic packaging captures premium positioning in Boston's injectables cluster. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA guidance documents, EPA recycled-content guidelines, and state-level extended producer responsibility statutes. Primary interviews engaged contract packaging executives, tool-and-die engineering directors, pharmaceutical quality assurance leads, and resin procurement specialists across the Northeast, Midwest, and Southeast manufacturing belts. Secondary validation drew from SEC 10-K filings of listed packaging conglomerates, customs trade data for resin imports, and Drug Supply Chain Security Act implementation timelines. Bottom-up demand modeling from end-use segments triangulated against top-down capacity assessments of regional converter infrastructure.
Segmentation dimensions modeled span product type, material grade, end-use application, and packaging process technology across the projection horizon. Treatment line differentiation separates pharmaceutical unit-dose from consumer electronics theft-deterrent formats. Regional regulatory clusters capture FDA, EPA, and state-level EPR variation. CAGRs were derived from volume trajectory analysis anchored in pharmaceutical serialization mandate deadlines and biologics pipeline expansion. Industry-specific forecast inputs include resin price elasticity coefficients and validation burden amortization curves for serialization-ready equipment.
Material uncertainties — resin supply disruptions, state EPR adoption acceleration, FDA aggregation requirement delays — sit outside the modeled envelope. Forecasts reflect assumptions about petrochemical capacity expansion and tool-and-die engineering labor market recovery. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Holographic Blister Foil Market
Blister Packaging
Blister Cards Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Paper Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Latin America Pharmaceutical Blister Packaging Market
Blister Packaging
Pharma Blister Packaging Machines Market
Blister Packaging
Middle East and Africa Pharmaceutical Blister Packaging Market
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
Europe Blister Packaging Market
Blister Packaging
Blister Packs Market
Blister Packaging
Blister Foil Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Ampoules and Blister Packaging Market