

Holographic Blister Foil Market Size, Share, and Industry Trends Forecast 2026-2036
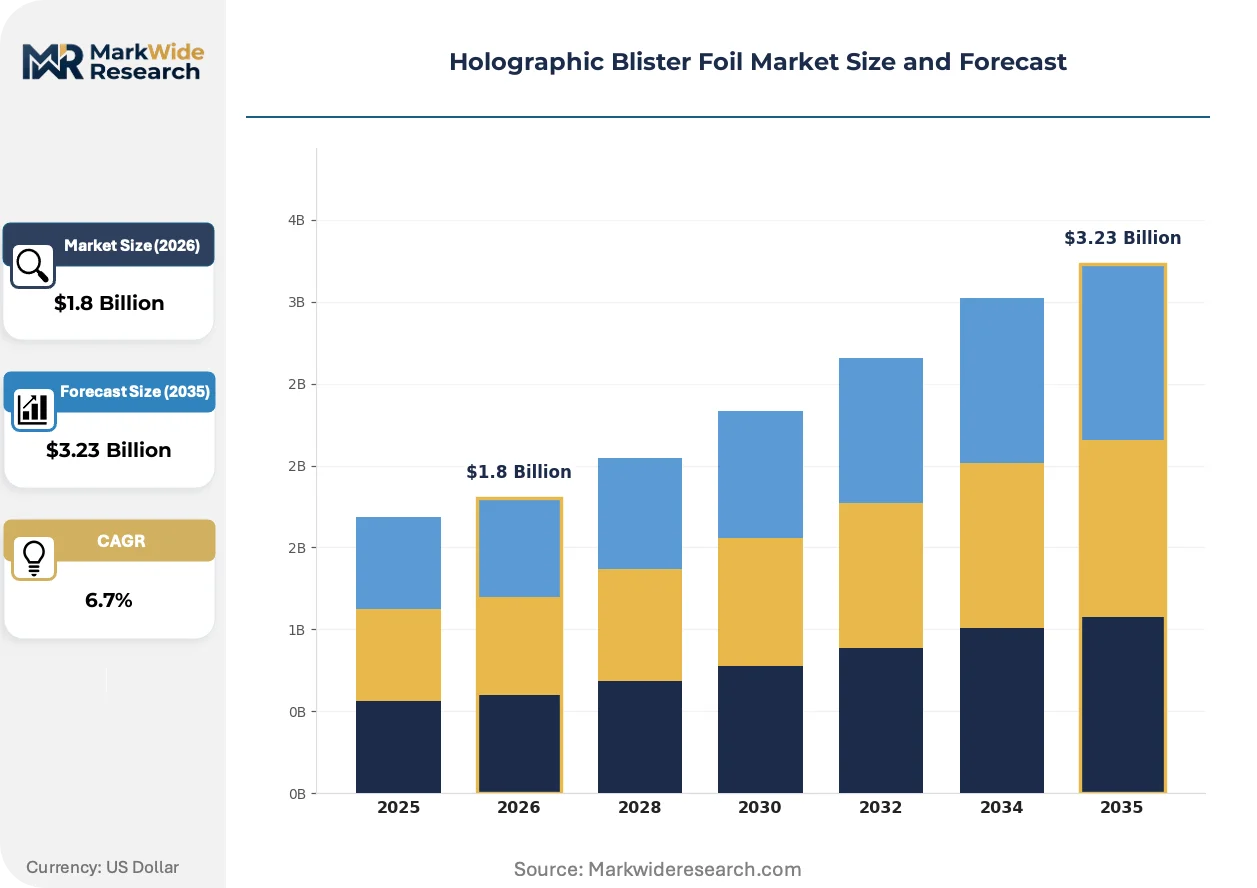
Holographic Blister Foil Market Insights
India is reconfiguring its position as a strategic production hub for holographic blister foil, with domestic converters expanding metallization and embossing capacity to serve contract pharmaceutical packaging. Amcor leverages its integrated film-to-foil operations across multiple continents to sustain supply security for multinational drug manufacturers. Constantia Flexibles anchors European demand through specialized cold-seal formulations that meet stringent barrier requirements for moisture-sensitive therapeutics. Uflex competes aggressively on cost-engineered duplex structures for emerging-market generic drug portfolios.
Holographic blister foil consists of aluminum substrate laminated with holographic polyester or oriented polypropylene films, typically measuring 20-45 micrometers in total thickness, manufactured through vacuum metallization and micro-embossing to produce optically variable security patterns. Its primary commercial purpose is to provide tamper-evident, anticounterfeiting protection for unit-dose pharmaceuticals while maintaining moisture and oxygen barrier integrity. Heat-seal foil dominates current volume owing to established compatibility with polyvinyl chloride and polychlorotrifluoroethylene forming films, though triplex foil configurations are gaining traction where extended shelf life demands justify premium material stacks. Pharmaceutical packaging applications command the deepest margin pools due to regulatory validation requirements and brand-protection premiums, while cosmetic wrapping represents a faster-growing adjacent segment as luxury goods adopt authentication features.
FDA guidance on anticounterfeiting packaging mandates and EU MDR traceability requirements are elevating holographic features from optional brand elements to compliance-relevant safeguards, directly shaping material specifications and vendor qualification protocols. REACH restrictions on certain adhesive chemistries and BIS certification requirements for imported packaging substrates into India are further segmenting supplier capabilities by regulatory jurisdiction. Stakeholders must monitor evolving serialization integration standards that could either embed holographic verification within digital track-and-trace systems or render standalone optical features redundant.
Market Dynamics
Pharmaceutical serialization mandates are compressing supplier qualification timelines while simultaneously elevating holographic authentication from brand embellishment to compliance infrastructure, forcing converters to reengineer production workflows around track-and-trace integration.
Growth Catalysts
- FDA Anticounterfeiting Guidance:Unit-dose packaging mandates for high-risk therapeutics are embedding holographic verification layers directly into primary blister specifications, expanding addressable substrate volumes for qualified converters.
- India BIS Certification:Import restrictions on unregistered packaging materials are redirecting procurement toward domestic metallization facilities with validated holographic embossing capabilities.
- Moisture-Sensitive Biologics:Extended shelf-life requirements for mRNA and peptide formulations are accelerating triplex foil adoption where holographic polyester serves dual barrier and security functions.
Market Restraints
- Aluminum Price Volatility:Raw material swings in commodity-grade foil substrates compress converter margins and destabilize long-term contract pricing for pharmaceutical packaging agreements.
- Vacuum Metallization Concentration:Specialized deposition equipment manufacturing clusters in Germany and Japan create equipment procurement bottlenecks for emerging-market converters seeking capacity expansion.
- Digital Watermark Substitution:Covert smartphone-verifiable codes on standard foil threaten to displace overt holographic features in cost-sensitive generic drug portfolios.
Strategic Opportunities
- Cosmetic Authentication Adjacencies:Luxury skincare and fragrance brands are adopting pharmaceutical-grade holographic blister formats to combat gray-market diversion, opening premium margin pools outside regulated drug packaging.
- EU MDR Traceability Convergence:Unique Device Identification requirements for combination products create specification overlap where holographic foil suppliers can embed machine-readable features alongside optical security.
- Cold-Chain Biologics Expansion:Temperature-sensitive therapeutics requiring specialized barrier properties are driving demand for holographic laminates with enhanced thermal stability across distribution networks.
Industry Challenges
- Micro-Embossing Talent Scarcity:Specialized technicians capable of maintaining sub-micron pattern fidelity in continuous roll-to-roll operations command premium wages and limited geographic availability.
- Serialization Integration Complexity:Legacy holographic verification systems require costly retrofitting to communicate with emerging cloud-based authentication platforms demanded by pharmaceutical track-and-trace mandates.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Blister Foil Market Trends and Innovations
Convergence between optical security features and digital verification infrastructure is redefining how pharmaceutical packaging converters architect substrate specifications and production investments.
Nanostructured surface relief holography is collapsing the functional distinction between decorative brand elements and machine-readable authentication tracks. Specialty converters serving European pharmaceutical manufacturers are embedding diffractive patterns with simultaneous visual inspection and automated line-scan verification capabilities. This compression eliminates redundant substrate layers previously required for separate optical and digital security functions.
REACH restrictions on specific adhesive chemistries used in holographic lamination are forcing reformulation investments across European converter operations. ECHA substance evaluations targeting phthalate-based bonding agents are accelerating migration toward acrylic and polyurethane alternatives with equivalent barrier performance. Cold-seal pharmaceutical applications in Germany and France face the steepest compliance timelines given existing validated drug packaging specifications.
Direct converter relationships with pharmaceutical quality assurance departments are displacing traditional distributor-mediated procurement for holographic blister foil. Large generic drug manufacturers in India now specify substrate performance parameters directly with metallization houses, bypassing regional trading intermediaries. This channel compression concentrates volume commitments among qualified suppliers while marginalizing speculative inventory holders lacking regulatory documentation capabilities.
Holographic Blister Foil Market Segmentation
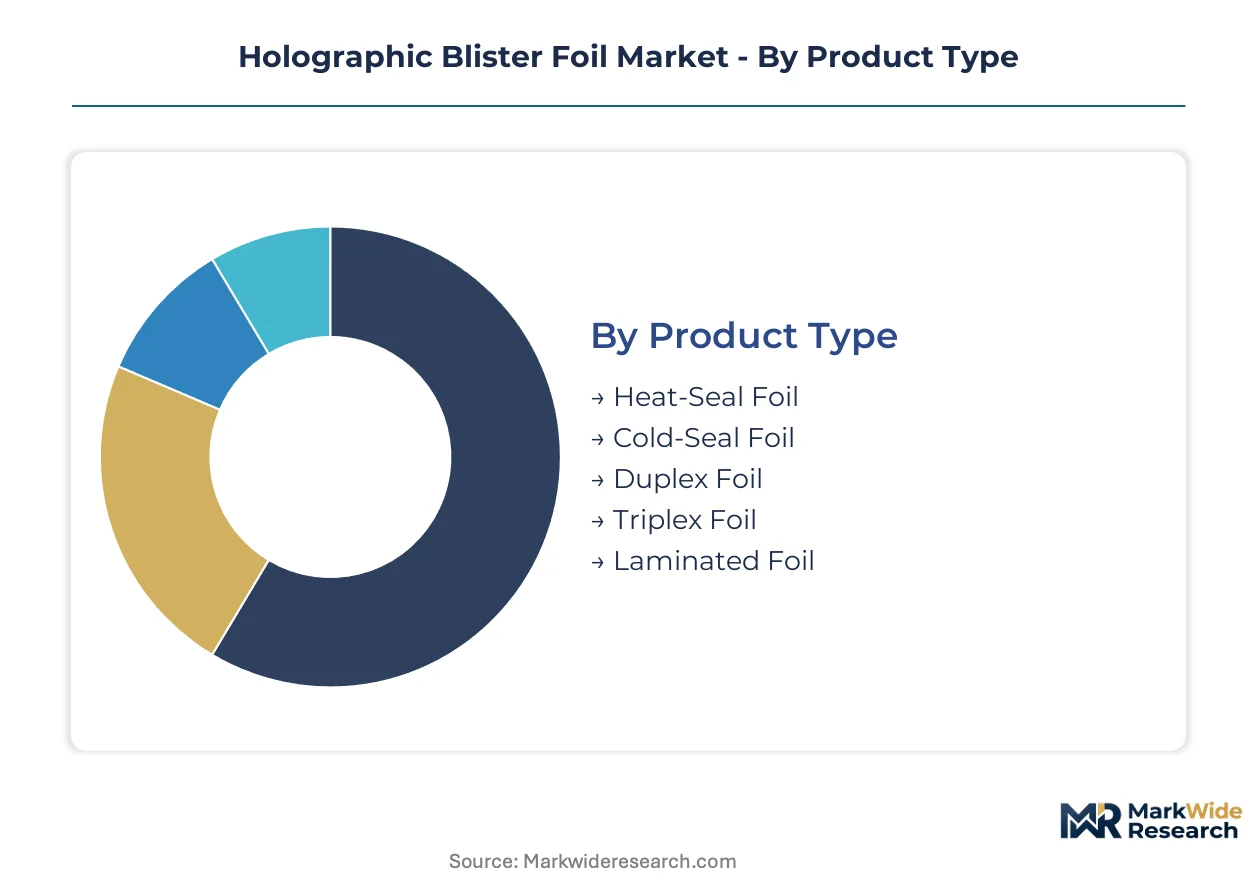
Segmentation in holographic blister foil markets reveals how substrate specifications diverge across regulatory regimes and end-use performance requirements. Technical distinctions between seal technologies and barrier configurations directly determine vendor qualification pathways and margin structures for converters serving pharmaceutical versus consumer goods applications.
Product Type:
After-sales service intensity varies sharply across foil categories, with heat-seal and triplex configurations demanding specialized technical support for validation documentation and line integration troubleshooting that cold-seal alternatives rarely require.
- Heat-Seal Foil:Aluminum-polyester laminates with thermoplastic coating layers compatible with PVC and polychlorotrifluoroethylene forming films dominate current pharmaceutical volumes. Demand concentrates in India where domestic converters supply both local drug manufacturers and export contracts to regulated markets, though REACH adhesive compliance costs are compressing European converter margins.
- Cold-Seal Foil:Pressure-sensitive adhesive formulations eliminate heat-sealing equipment requirements, enabling high-speed packaging lines for moisture-sensitive biologics. Constantia Flexibles anchors European demand through specialized barrier coatings that meet EMA stability requirements for peptide formulations in Germany and France.
- Duplex Foil:Two-layer aluminum-polymer structures balance cost and barrier performance for generic drug portfolios in emerging markets.
- Triplex Foil:Three-layer configurations incorporating holographic polyester between aluminum and sealant layers serve extended shelf-life requirements.
- Laminated Foil:Custom adhesive-bonded stacks accommodate non-standard forming films for specialty pharmaceutical applications.
Heat-seal foil holds the largest share; momentum sits with triplex configurations as biologics expand.
Application:
Cost tier stratification separates pharmaceutical-grade validated substrates from cosmetic and food applications where authentication features command premium pricing without regulatory compliance overhead.
- Pharmaceutical Packaging:Unit-dose blister formats for tablets and capsules require tamper-evident holographic verification combined with moisture and oxygen barrier integrity. FDA anticounterfeiting guidance and EU MDR traceability mandates are embedding optical security as compliance infrastructure rather than optional brand enhancement.
- Cosmetic Wrapping:Luxury skincare and fragrance brands adopt pharmaceutical-grade holographic formats to combat gray-market diversion, opening premium margin pools outside regulated drug packaging with faster qualification timelines and lower documentation burdens.
- Food Preservation:Extended shelf-life requirements for sensitive ingredients drive holographic laminate adoption where brand protection intersects with barrier performance.
- Electronic Component Encasing:Static-dissipative holographic foils protect moisture-sensitive semiconductors during distribution.
- Personal Care Products:Authentication features for premium hygiene goods follow cosmetic packaging specifications with reduced barrier requirements.
Pharmaceutical packaging commands the deepest margins; cosmetic wrapping is climbing the fastest as luxury authentication demand accelerates.
End User:
Customer type determines procurement channel structure, with multinational drug manufacturers consolidating volume through direct converter relationships while cosmetic and food processors retain distributor-mediated purchasing.
- Drug Manufacturers:Branded and generic pharmaceutical producers specify substrate performance parameters directly with metallization houses, bypassing regional trading intermediaries. Large Indian generic manufacturers now demand validated holographic embossing capabilities with complete regulatory documentation packages for FDA and EMA submissions.
- Cosmetic Brands:Luxury goods houses prioritize overt authentication features with shorter qualification cycles than pharmaceutical validation.
- Food Processors:Barrier performance requirements dominate procurement criteria with authentication as secondary consideration.
- Electronics Producers:Cleanroom-compatible holographic packaging specifications serve semiconductor and component distribution.
- Hygiene Goods Providers:Cost-engineered duplex structures balance authentication visibility with high-volume production economics.
Drug manufacturers represent the largest addressable base; cosmetic brands are gaining share fastest as authentication premiums expand beyond regulated sectors.
Packaging Type:
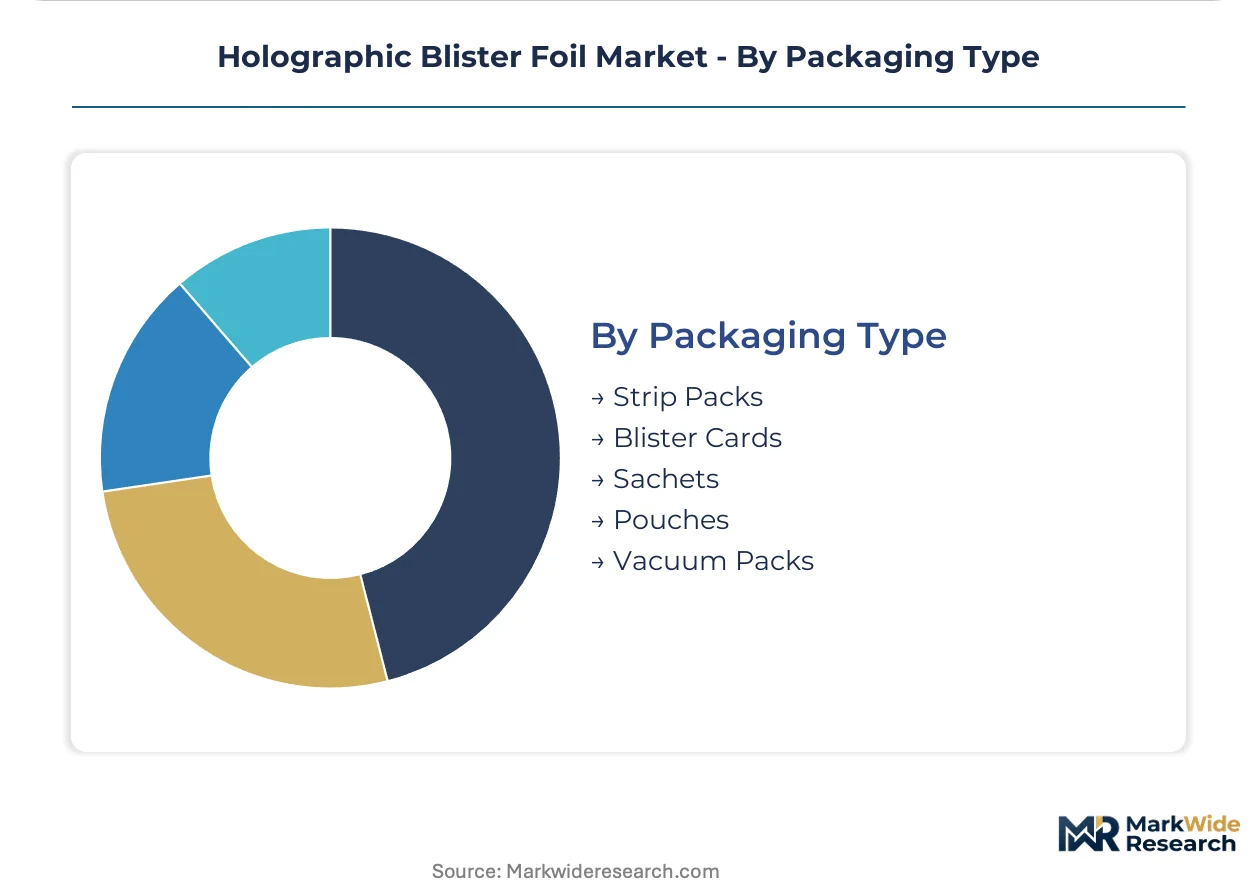
Volume concentration in blister cards and strip packs reflects pharmaceutical unit-dose dominance, while pouch and sachet formats serve emerging cosmetic and food authentication applications with different equipment compatibility requirements.
- Strip Packs:Continuous sealed pouches for individual tablets or capsules maximize barrier surface area with holographic verification along the full seal perimeter.
- Blister Cards:Thermoformed cavities with lidding foil dominate prescription pharmaceutical volumes across North American and European retail pharmacy distribution.
- Sachets:Single-dose flexible packages for cosmetics and personal care samples adopt holographic laminates for brand authentication at point of trial.
- Pouches:Stand-up and flat formats for food and cosmetic bulk products integrate holographic strips as authentication markers.
- Vacuum Packs:Extended shelf-life formats for sensitive electronics and specialty foods combine holographic barriers with oxygen scavenging systems.
Blister cards hold the largest share; momentum sits with sachets as cosmetic sample authentication demand expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on anticounterfeiting packaging anchors North American demand, while BIS certification redirects procurement toward domestic Indian metallization facilities and REACH adhesive restrictions reshape European converter operations.
United States
Unit-dose packaging mandates for high-risk therapeutics drive holographic blister foil specifications through FDA anticounterfeiting guidance. Serialization integration requirements compress supplier qualification timelines for domestic drug manufacturers. New Jersey and Pennsylvania pharmaceutical packaging clusters concentrate metallization demand for branded drug portfolios.
Germany
EMA stability requirements for peptide formulations sustain demand for specialized cold-seal barrier coatings. ECHA substance evaluations targeting phthalate-based bonding agents force acrylic adhesive reformulation investments across converter operations. Bavarian pharmaceutical packaging corridors anchor European holographic embossing capacity for moisture-sensitive biologics.
India
Domestic blister packaging output serves both local pharmaceutical consumption and export contracts to regulated markets. BIS certification requirements for imported packaging substrates redirect procurement toward domestic metallization facilities with validated holographic capabilities. Gujarat and Maharashtra converter clusters expand vacuum metallization capacity to serve contract pharmaceutical packaging.
China
NMPA traceability requirements for pharmaceutical packaging elevate holographic verification from brand embellishment to compliance infrastructure. Dual carbon goals pressure energy-intensive vacuum metallization operations toward efficiency upgrades. Yangtze River Delta pharmaceutical manufacturing zones concentrate demand for triplex foil configurations serving biologics expansion.
Japan
PMDA quality standards for primary packaging materials sustain premium specifications for holographic blister foil in domestic drug manufacturing. METI industrial policy supports advanced packaging technology development for export-oriented pharmaceutical production. Kanto region pharmaceutical corridors maintain specialized cold-seal demand for moisture-sensitive therapeutics.
Holographic Blister Foil Market Competitive Landscape
Capability concentration sits with specialized converters possessing validated holographic embossing and regulatory documentation expertise; scale advantage sits with integrated packaging conglomerates controlling film-to-foil operations across multiple continents. The market structures around three tiers: multinational integrated suppliers, regional metallization specialists, and emerging-market cost-engineered producers. Dominant competitive moves include backward integration into vacuum metallization equipment and strategic partnerships with pharmaceutical quality assurance departments.
Within the integrated multinational tier, Amcor and Constantia Flexibles exemplify archetypes of supply security and specialized barrier formulation respectively. Uflex occupies a position among cost-engineered converters serving high-volume generic drug portfolios. These three anchors illustrate how competitive positioning diverges across premium validation capabilities, regulatory compliance depth, and emerging-market scale economics.
| Leading Market Players |
|---|
| Amcor |
| Constantia Flexibles |
| Huhtamaki |
| Uflex |
| Winpak |
| AptarGroup |
| Tekni-Plex |
| Berry Global |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European vacuum metallization facilities is compressing converter margins while simultaneously elevating pricing power for qualified suppliers serving FDA-validated pharmaceutical contracts. Utilization gaps between REACH-compliant European converters and BIS-certified Indian metallization houses are driving divergent pricing postures across regulatory jurisdictions.
Pricing Analysis
Geographic price spreads between Indian domestic converters and European specialized suppliers exceed threefold for equivalent triplex foil specifications. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical-grade substrates from cost-engineered generic drug portfolios and unvalidated cosmetic applications. Price differentiation hinges on regulatory documentation completeness and volume commitment scale. Cost compression in emerging-market duplex structures is intensifying because digital watermark substitutes threaten overt holographic features in price-sensitive generic drug segments.
Supply Chain Analysis
Contract manufacturing concentration sits with Amcor's integrated film-to-foil operations across multiple continents and Constantia Flexibles' specialized cold-seal barrier coating facilities in Germany and France. Raw material dependencies draw from commodity-grade aluminum foil substrates, holographic polyester films, and pressure-sensitive adhesive chemistries. Single-source vulnerability concentrates in German and Japanese vacuum metallization equipment manufacturing clusters. Distribution runs through direct converter relationships with pharmaceutical quality assurance departments, displacing traditional distributor-mediated procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against digital watermark and smartphone-verifiable authentication technologies that threaten to displace optical holographic features in cost-sensitive segments.
For Market Incumbents: Insulate validated regulatory documentation capabilities as the primary defensive moat against digital substitute technologies. Deepen backward integration into vacuum metallization equipment manufacturing to reduce procurement bottlenecks from German and Japanese suppliers. Expand embossing capacity in BIS-certified Indian facilities to capture redirected procurement from import-restricted packaging substrates. For New Entrants and Emerging Players: Cosmetic authentication adjacencies in luxury skincare and fragrance present the most penetrable white-space opportunity outside regulated pharmaceutical validation timelines. Target cold-chain biologics packaging specifications where thermal stability requirements create performance barriers for incumbent converters. Pursue direct relationships with mid-tier generic drug manufacturers in India seeking validated holographic capabilities with complete FDA and EMA documentation packages. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because serialization integration mandates and evolving anticounterfeiting guidance continuously elevate barriers for unqualified suppliers. Acquisition target archetype: regional metallization specialists possessing validated embossing capabilities and existing pharmaceutical quality assurance relationships. Monitor NMPA traceability requirement implementation in China as inflection indicator for Asia-Pacific demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Metallization Equipment | Reduces procurement bottlenecks from German and Japanese equipment manufacturing clusters. |
| REACH-Compliant Adhesive Reformulation Investment | Enables continued European market access as ECHA phthalate restrictions tighten bonding agent specifications. |
| Direct Pharmaceutical QA Department Relationships | Bypasses distributor intermediaries and concentrates volume commitments among qualified suppliers. |
| Serialization-Integrated Holographic Verification Development | Aligns optical security features with cloud-based pharmaceutical track-and-trace mandates. |
| BIS-Certified Indian Capacity Expansion | Captures redirected procurement from import-restricted packaging substrates into domestic metallization facilities. |
Research Methodology
Desk research of FDA guidance documents, EMA stability requirement publications, and BIS certification standards preceded structured interviews with pharmaceutical packaging procurement managers, converter operations directors, regulatory affairs specialists, and metallization equipment manufacturers. Primary fieldwork combined with secondary validation against customs trade data, SEC 10-K filings from integrated packaging conglomerates, and pharmaceutical packaging industry association reports. Bottom-up volume estimates from converter capacity utilization and top-down demand segmentation triangulated across multiple independent sources.
Assumptions regarding aluminum price stability, REACH adhesive compliance timelines, and serialization integration adoption curves were held fixed across baseline scenarios while regulatory enforcement intensity and digital watermark substitution rates were varied in sensitivity analysis. Segmentation dimensions modeled include seal technology type, barrier configuration tier, end-use application, and regional regulatory cluster. CAGRs were derived from regression analysis of historical pharmaceutical packaging output against anticounterfeiting mandate implementation phases. Forecast inputs incorporated biologics pipeline expansion data and generic drug portfolio authentication requirement evolution.
Practitioners should monitor aluminum commodity price volatility, digital watermark technology cost curves, and serialization standard convergence for early signals of forecast revision necessity. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and pharmaceutical packaging output growth. Quarterly review of converter capacity utilization rates and pharmaceutical track-and-trace mandate implementation timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.