
 Plastic Fillers Market | 2026-2036
Plastic Fillers Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Fillers Market Analysis
Automotive OEMs is unwinding legacy reliance on virgin resin loading, redirecting compound specifications toward high-aspect-ratio talc and precipitated calcium carbonate for interior and under-hood applications. Imerys leverages vertical integration from quarry operations to surface-treated grades, sustaining cost discipline across European and Asian supply corridors. Omya AG anchors its position through controlled calcium carbonate reserves and on-site slurry operations at major polymer compounding hubs. Evonik Industries differentiates via specialty precipitated silicas and functionalized oxides targeting optical and barrier performance in thin-wall packaging.
Plastic fillers are inorganic or organic particulate additives, typically 0.1 to 100 microns in median diameter, dispersed within thermoplastic or thermoset matrices to modify modulus, shrinkage, thermal conductivity, or unit cost. Calcium carbonate dominates volume consumption due to its low oil absorption, ready surface treatment with stearic acid or coupling agents, and compatibility with polypropylene and PVC systems. Talc commands premium positioning in automotive and appliance segments where dimensional stability and heat deflection temperature requirements are stringent. Barium sulfate occupies specialized niches in radiation-shielding compounds and high-density masterbatches for acoustic damping applications.
REACH registration obligations and RoHS substance restrictions in Europe compel filler suppliers to document impurity profiles and substitution pathways for heavy metal traces. The US EPA and OSHA frameworks govern respirable crystalline silica exposure in mining and milling operations, shaping plant location and automation investment decisions. China's GB standards and MEE environmental enforcement are tightening particulate emissions controls at calcium carbonate processing facilities. Stakeholders must monitor evolving extended producer responsibility mandates and carbon border adjustment mechanisms that will recalibrate sourcing economics between domestic production and import dependency.
Market Dynamics
Automotive lightweighting mandates are compressing compound specifications toward high-performance mineral reinforcements, forcing filler suppliers to reconcile cost discipline with surface chemistry investments that satisfy OEM tier-down requirements.
Growth Catalysts
- REACH RoHS Compliance Trajectory:European chemical registration obligations are redirecting formulation strategies toward halogen-free filler systems, creating specification pull through appliance and electronics molding supply chains.
- China Appliance Cluster Density:Concentrated molding operations in Guangdong and Zhejiang provinces are driving calcium carbonate offtake through just-in-time slurry delivery models.
- Mineral-Reinforced Polymer Adoption:Under-hood thermal management requirements are accelerating consumption of high-aspect-ratio talc in powertrain component applications.
Market Restraints
- Respirable Crystalline Silica Exposure Limits:US EPA and OSHA frameworks govern milling operations, elevating automation capital requirements and constraining greenfield plant economics.
- Heavy Metal Impurity Documentation:REACH substance restrictions compel suppliers to maintain batch-level traceability systems, adding fixed cost layers to commodity-grade production.
- Polymer Matrix Substitution Pressure:Bio-based resin platforms in packaging applications are displacing conventional polypropylene compounds, compressing addressable volume for standard calcium carbonate grades.
Strategic Opportunities
- India Compounding Hub Expansion:BIS standardization and PLI scheme incentives for domestic manufacturing are creating first-mover positioning for precipitated calcium carbonate slurry operations.
- Optical Performance Barrier Films:Convergence of precipitated silica surface treatment chemistry with thin-wall packaging specifications is opening premium positioning in food-contact applications.
- Extended Producer Responsibility Mandates:EU packaging waste directives are incentivizing filler grades compatible with mechanically recycled polymer streams, rewarding surface-modified products with proven reprocessing stability.
Industry Challenges
- Surface Chemistry Talent Scarcity:Formulation expertise spanning silane coupling agent selection and dispersion rheology commands premium compensation, constraining R&D throughput at mid-scale suppliers.
- On-Site Slurry Infrastructure Requirements:Proximate compounding operations demand capital-intensive pipeline and storage installations, complicating market entry for quarry-dependent producers.
- Batch Certification Timeline Compression:Automotive PPAP documentation and REACH dossier maintenance are extending qualification cycles, straining working capital for specification-grade product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Fillers Market |
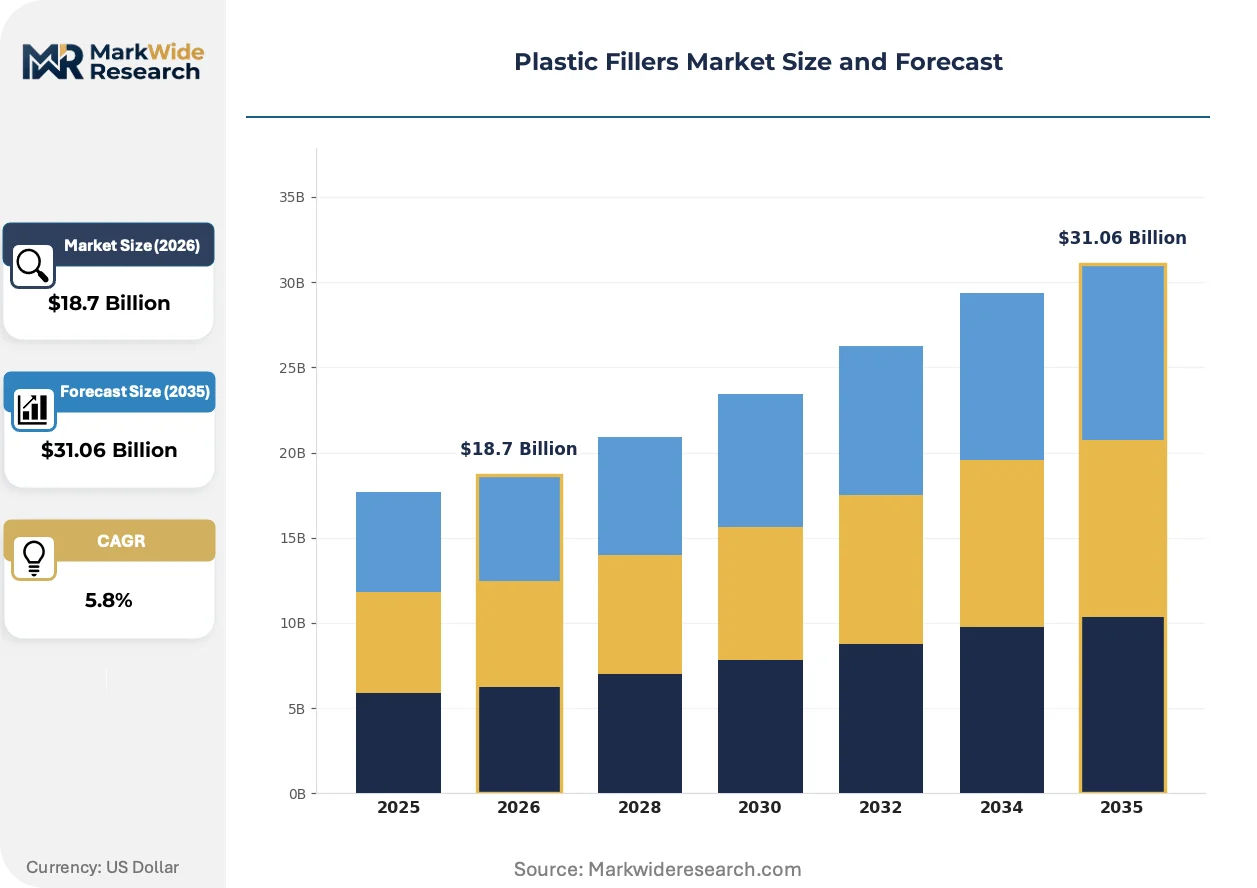
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Carbonate, Talc, Barium Sulfate, Clay Form: Powder, Granule, Pellet, Bead Application: Plastics, Coatings, Rubber, Adhesives End User: Construction, Automotive, Electronics, Packaging |
| Companies Covered | Imerys, Mineral Technologies Inc., BASF SE, Huber Engineered Materials, Omya AG, LKAB Group, The Dow Chemical Company, Evonik Industries, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Fillers Market Emerging Trajectories
Surface treatment chemistry and dispersion engineering are separating commodity filler supply from value-added compound solutions, with automation and regulatory compliance investments determining competitive survival.
Precipitated calcium carbonate with controlled particle size distribution and stearic acid surface coating is bifurcating the market between quarry-ground commodity grades and specification-tuned automotive compounds. Tier-one suppliers are capturing interior panel programs through tailored oil absorption profiles, while commodity producers face margin compression from polymer compounders consolidating purchase specifications.
China's MEE environmental enforcement and GB standards for particulate emissions are tightening processing facility compliance, forcing calcium carbonate producers toward closed-loop water systems and baghouse upgrades. Shandong and Guangxi province operations are absorbing the heaviest retrofit costs, while integrated quarry-to-slurry operators leverage captive mineral reserves to sustain cost positions.
Automotive OEMs are consolidating approved supplier lists around compounders with demonstrated lot-to-lot consistency, compressing switching flexibility for filler specification changes. Tier-two molders in the US Midwest and Germany's Ruhr region are absorbing the qualification burden, with sourcing decisions increasingly tied to slurry tank farm proximity rather than delivered price per kilogram.
Plastic Fillers Market Segmentation
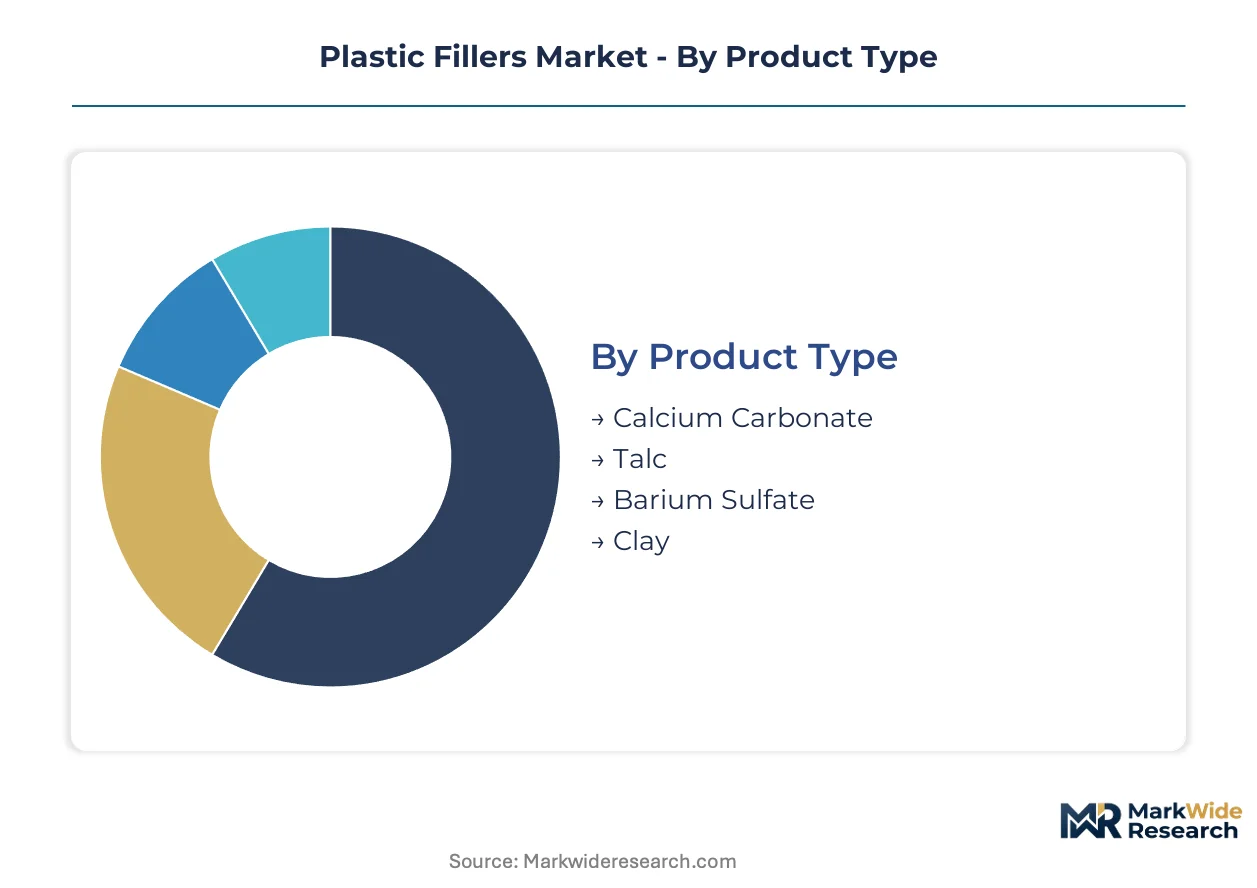
Plastic fillers segment along mineral chemistry, physical form, and downstream application, with substitution pressure varying sharply across each axis. Suppliers must align surface treatment investments and logistics infrastructure against the specific performance thresholds and regulatory exposure of each segment cluster.
Product Type:
Substitution pressure from bio-based reinforcements and recycled polymer streams is most acute in commodity mineral grades, while specialty precipitated products defend position through OEM qualification barriers.
- Calcium Carbonate:Quarry-ground and precipitated grades span oil absorption values from 15 to 45 g/100g, with surface-treated variants dominating polypropylene automotive interior specifications. Guangdong and Zhejiang appliance molding clusters in China absorb the highest slurry volumes through just-in-time pipeline delivery.
- Talc:High-aspect-ratio lamellar structures provide dimensional stability and heat deflection temperature elevation critical for under-hood automotive components. Powertrain thermal management requirements in Germany's Ruhr region and the US Midwest are concentrating demand for platy grades with top-cut control below 10 microns.
- Barium Sulfate:High specific gravity (4.5 g/cm³) enables radiation shielding compounds and acoustic damping masterbatches for medical and industrial applications.
- Clay:Kaolin and bentonite grades serve cost-sensitive PVC cable and flooring compounds where electrical insulation and rheology modification are required.
Calcium carbonate retains volume leadership; talc holds the steepest expansion curve.
Form:
Physical form selection directly determines logistics economics and compounding line integration, with slurry and pellet formats commanding premium positioning over commodity powder.
- Powder:Dry-ground mineral powders remain the default for small-batch compounders and remote processing locations lacking slurry infrastructure. Dust exposure controls under OSHA and REACH occupational limits are elevating handling costs and accelerating automation investment at US and European facilities.
- Granule:Agglomerated forms reduce dust generation and improve flowability for automated feeding systems in high-volume extrusion operations.
- Pellet:Pre-dispersed mineral concentrates in polymer carrier resins eliminate compounding stage dispersion requirements, serving specialty film and thin-wall packaging producers.
- Bead:Spherical agglomerates optimize bulk density and handling characteristics for pneumatic conveying systems in large-scale automotive compounding plants.
Powder retains volume leadership; pellet formats are gaining share fastest in premium packaging applications.
Application:
Application segmentation reveals diverging regulatory exposure, with food-contact and medical specifications imposing qualification burdens that commodity construction grades escape.
- Plastics:Thermoplastic and thermoset matrix loading represents the core demand pool, spanning polypropylene, PVC, polyethylene, and engineering polymer systems. Automotive lightweighting mandates in Germany, the United States, and China are redirecting compound specifications toward high-aspect-ratio mineral reinforcements.
- Coatings:Functional fillers modify opacity, rheology, and barrier performance in architectural and industrial paint systems.
- Rubber:Mineral loading in tire and industrial rubber compounds improves tear strength and reduces compound cost.
- Adhesives:Controlled particle size distribution enables viscosity modification and sag resistance in construction and assembly sealants.
Plastics retains volume leadership; coatings applications are climbing the fastest on construction activity recovery.
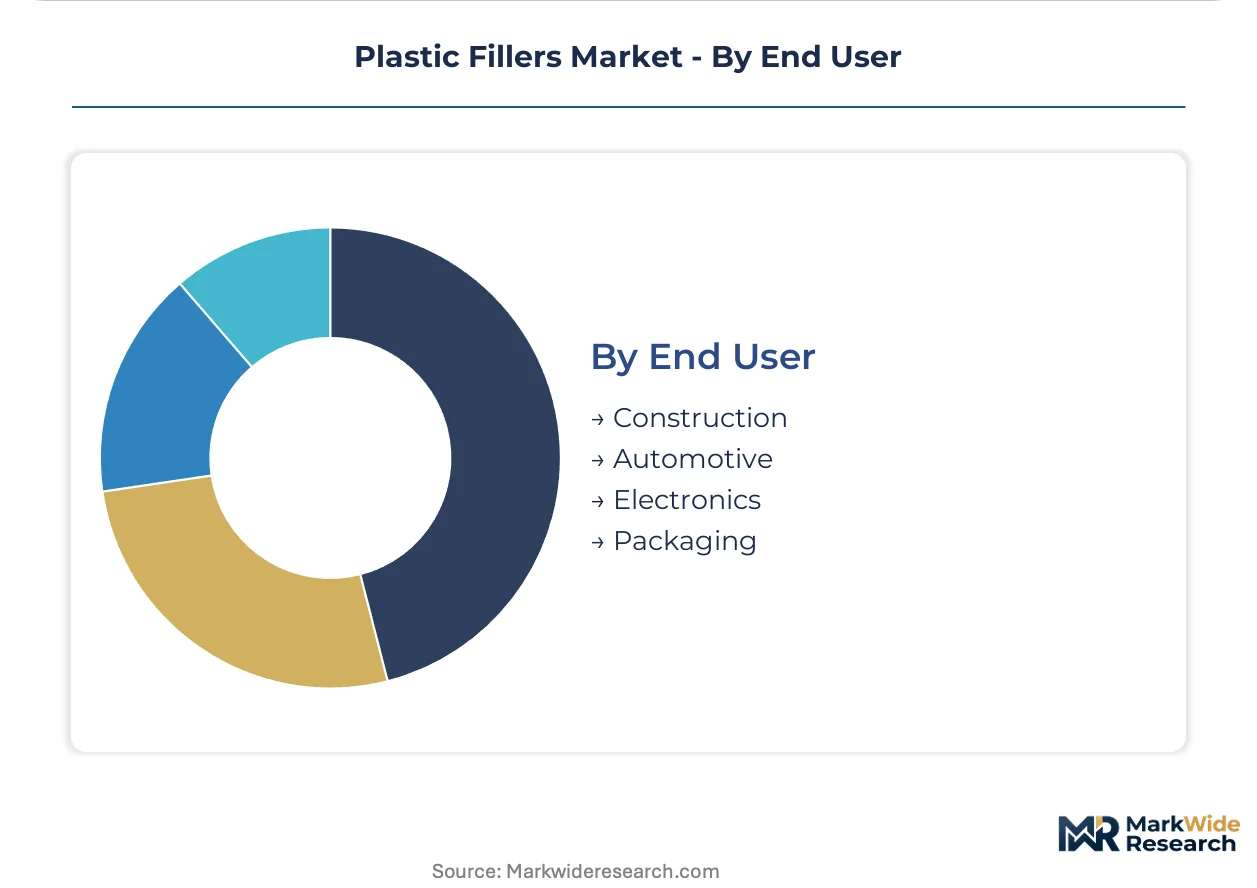
End User:
End-user concentration patterns determine regional supply corridor economics, with automotive and electronics clusters dictating slurry infrastructure placement decisions.
- Construction:PVC pipe, siding, and flooring compounds absorb commodity calcium carbonate grades with limited surface treatment requirements.
- Automotive:Interior panel, bumper, and under-hood applications demand lot-to-lot consistency and PPAP documentation, consolidating supply around tier-one compounders with captive slurry tank farms.
- Electronics:Halogen-free flame retardant formulations in appliance housings and connectors require heavy metal impurity documentation under REACH and RoHS frameworks.
- Packaging:Food-contact thin-wall containers and barrier films drive precipitated silica and surface-modified calcium carbonate specifications.
Construction retains volume leadership; automotive holds the steepest expansion trajectory on lightweighting mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports precipitated calcium carbonate slurry to polymer compounding hubs across Germany, the United States, and Southeast Asia, while integrated quarry-to-slurry operators in Shandong and Guangxi provinces capture domestic appliance cluster demand.
China
Guangdong and Zhejiang appliance molding clusters absorb the highest calcium carbonate slurry volumes through just-in-time pipeline delivery. MEE environmental enforcement and GB standards for particulate emissions are forcing processing facility retrofits toward closed-loop water systems. Shandong province operations face the heaviest compliance costs, while integrated operators leverage captive mineral reserves to sustain cost positions.
Germany
The Ruhr region concentrates demand for high-aspect-ratio talc in powertrain thermal management applications. REACH registration obligations and RoHS substance restrictions compel suppliers to document heavy metal impurity profiles and maintain batch-level traceability systems. Automotive OEMs in Bavaria and Baden-Württemberg are consolidating approved supplier lists around compounders with demonstrated lot-to-lot consistency.
United States
Tier-two molders in the Midwest absorb qualification burdens as OEMs compress switching flexibility for filler specification changes. EPA and OSHA frameworks govern respirable crystalline silica exposure in milling operations, elevating automation capital requirements. Sourcing decisions increasingly tie to slurry tank farm proximity in Ohio and Michigan rather than delivered price per kilogram.
India
BIS standardization and PLI scheme incentives for domestic manufacturing are creating first-mover positioning for precipitated calcium carbonate slurry operations. Maharashtra and Gujarat compounding hubs are expanding capacity to serve appliance and automotive export programs. DGFT trade policies are redirecting formulation strategies toward local mineral sourcing to reduce import dependency.
Japan
METI industrial policy supports high-performance mineral reinforcement development for automotive lightweighting programs. Kansai and Chubu regions host precision compounding operations serving thin-wall packaging and electronics housing specifications. JIS standards for polymer compound quality are tightening qualification requirements for imported filler grades.
Plastic Fillers Market Vendor Landscape
Player mix skews toward vertically integrated mineral processors with captive quarry reserves and surface-treatment capabilities, creating tiered competition between commodity ground-carbonate suppliers and specification-grade precipitated product specialists. Strategic archetypes include integrated quarry-to-slurry operators, specialty precipitated mineral producers, and regional grinding mills serving construction-grade compounds. Dominant competitive moves encompass backward integration into mining assets and geographic expansion of on-site slurry infrastructure at major polymer compounding hubs.
Among European integrated processors, Imerys and Omya AG exemplify the quarry-to-slurry archetype through vertical control from mineral extraction to surface-treated grades. Evonik Industries occupies a position within the specialty precipitated chemicals tier, representing functionalized oxide capabilities targeting optical and barrier performance segments. These three anchors illustrate how surface chemistry investments and logistics infrastructure placement determine competitive survival across automotive, packaging, and electronics supply chains.
| Leading Market Players |
|---|
| Imerys |
| Mineral Technologies Inc. |
| BASF SE |
| Huber Engineered Materials |
| Omya AG |
| LKAB Group |
| The Dow Chemical Company |
| Evonik Industries |
| Avient Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between quarry-integrated suppliers and automotive compounders lock in five-year supply visibility while capping price volatility exposure. These arrangements tether calcium carbonate slurry pricing to captive mineral reserves in Shandong province and pipeline delivery infrastructure, compressing spot market liquidity for specification-grade talc and precipitated grades.
Pricing Analysis
Surface-treatment-generation pricing gaps separate stearic-acid-coated precipitated calcium carbonate from uncoated quarry-ground powder, with silane-coupled talc commanding additional premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by lot-to-lot consistency certification and REACH dossier completeness. Cost compression in commodity ground-carbonate runs through polymer compounders consolidating purchase specifications toward fewer approved suppliers. Construction-grade compounders exhibit highest price sensitivity; automotive tier-one compounders prioritize slurry tank farm proximity over per-kilogram delivered cost.
Supply Chain Analysis
Just-in-time slurry delivery preferences dominate automotive compounding corridors in Germany, the United States, and China, displacing strategic stockpiling of dry powder. Supply concentrates in China, Finland, and the United States for high-aspect-ratio talc and precipitated calcium carbonate feedstock. Processing draws from limestone deposits, platy talc ore, and precipitated silica precursor chemicals. Single-source vulnerability concentrates around Shandong province pipeline networks serving Guangdong appliance clusters. Distribution runs through integrated quarry-to-slurry operators with captive tank farm installations at major polymer compounding hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plastic fillers are approaching a platform-economics inflection where surface chemistry interoperability determines supplier switching costs and compounder lock-in. REACH batch-level traceability systems and automotive PPAP documentation create ecosystem stickiness that rewards first-mover qualification investments.
For Market Incumbents: Secure captive mineral reserves in Shandong and Guangxi provinces through lease extensions or backward integration into quarry assets. Expand on-site slurry tank farm footprints at Ohio and Michigan automotive compounding clusters to tighten logistics moats against emerging Indian suppliers. Bio-based resin substitution in packaging applications threatens commodity calcium carbonate volumes; defend position through precipitated silica surface treatment R&D for barrier film specifications.
For New Entrants and Emerging Players: BIS certification fast-track for precipitated calcium carbonate slurry operations unlocks first-mover positioning in Maharashtra and Gujarat compounding hubs. White-space targets include thin-wall packaging precipitated silica specifications and mechanically recycled polymer-compatible filler grades under EU extended producer responsibility mandates. Penetrate through on-site slurry infrastructure partnerships with domestic appliance molders seeking import substitution from Chinese supply.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated quarry-to-slurry operators with demonstrated REACH dossier maintenance and automotive PPAP qualification track records. Long-term viability hinges on surface chemistry talent retention and captive mineral reserve positions rather than grinding capacity alone. Watch for inflection when carbon border adjustment mechanisms recalibrate sourcing economics between domestic European production and Chinese import dependency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Assets | Captive limestone and talc reserves in Shandong province insulate against MEE environmental enforcement cost spikes. |
| On-Site Slurry Infrastructure Expansion | Pipeline-connected tank farms at Ruhr region compounding hubs compress switching flexibility for automotive OEMs. |
| REACH Dossier Investment | Batch-level heavy metal traceability systems unlock specification-grade positioning in electronics housing supply chains. |
| Surface Treatment Chemistry R&D | Silane coupling agent expertise separates commodity ground-carbonate supply from value-added automotive compounds. |
| India Compounding Hub Partnership | PLI scheme-aligned slurry operations in Gujarat capture appliance and automotive export program demand. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining procurement directors at Tier 1 automotive compounders, plant managers at calcium carbonate processing facilities, and technical R&D leads at specialty precipitated mineral producers. Secondary validation drew from customs and trade data, SEC filings of integrated mineral processors, and MEE environmental enforcement disclosures. Bottom-up volume modeling triangulated against top-down value estimates from polymer compounding capacity expansions.
Across the analysis window, forecasts employed a segmented analytical framework spanning mineral chemistry, physical form, and downstream application, with additional modeling of surface treatment intensity tiers. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization trajectories at major quarry-to-slurry operations. Key inputs included automotive lightweighting content-per-vehicle assumptions and appliance cluster density metrics for Guangdong and Zhejiang provinces.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and automotive PPAP documentation requirements; material deviation would warrant model refresh. Specific risk factors include abrupt bio-based resin substitution acceleration, carbon border adjustment mechanism implementation timelines, and MEE environmental enforcement intensity variation. Revision becomes warranted when polymer compounding consolidation crosses thresholds that fundamentally alter buyer concentration dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tris Nonylphenyl Phosphite Market
Additives
Global Feed Acidulants Market
Additives
Tocopheryl Acetate Market
Additives
Plasticizer Alcohols Market
Additives
Monocalcium Phosphate Market
Additives
India Feed Additives Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Competitive Inhibitors Market
Additives
Tricalcium Citrate Market
Additives
Extruded Inclusions Market
Additives
Liquid Thickeners Market
Additives
Tamarind Gum Derivatives Market
Additives
Carboxymethyl Cellulose Market
Additives
Viscosity Index Improvers Market
Additives
Extrusion Aids Market