
 Organic Friction Modifier Additives Market | 2026-2036
Organic Friction Modifier Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Friction Modifier Additives Market Outlook
A capital-intensity divergence between integrated petrochemical majors and specialty additive houses is reorganizing competitive tiers in organic friction modifier additives. BASF leverages backward integration into fatty acid feedstocks to control raw material costs across European supply chains. Croda International PLC specializes in high-purity ester chemistry for electric vehicle transmission fluids, occupying a premium niche that commands technical validation cycles.
Organic friction modifier additives are surface-active compounds—typically long-chain fatty acids, esters, or amines—that adsorb onto metal interfaces to reduce boundary friction coefficients in lubricated systems, with typical treat rates ranging from 0.1% to 3.0% by weight in finished lubricant formulations. These additives serve primarily to improve fuel economy, reduce wear, and extend drain intervals in automotive and industrial applications. Ester-based friction modifiers lead product type value contribution due to their superior thermal stability and compatibility with Group III and Group IV base oils, while fatty acid derivatives sustain volume dominance in cost-sensitive industrial lubricant segments. Automotive transmissions anchor application demand as dual-clutch and continuously variable transmission designs multiply contact points requiring precise friction control.
EPA fuel economy standards and REACH chemical registration requirements in the United States and Europe are forcing reformulation of legacy friction modifier packages toward lower sulfur, lower ash chemistries. China's SAMR and GB standards for lubricant performance are tightening import specifications for metalworking fluids and greases. Stakeholders must monitor regulatory divergence between California's CARB protocols and federal EPA benchmarks, as this fragmentation will determine which additive architectures achieve multi-jurisdictional approval without redundant testing investment.
Market Dynamics
Automotive OEMs are tightening fuel economy specifications faster than additive suppliers can reformulate legacy friction modifier packages, compressing validation timelines and forcing simultaneous compliance with divergent regional chemical registration frameworks.
Growth Catalysts
- EPA Fuel Economy Standards:US automotive manufacturers face escalating CAFE penalties, driving procurement of ester-based friction modifiers that reduce boundary friction coefficients in dual-clutch transmissions.
- China's Heavy Machinery Production:Domestic scaling of excavator and wind turbine manufacturing concentrates demand for high-temperature-stable industrial lubricant additives in Jiangsu and Shandong provinces.
- Electric Vehicle Transmission Fluids:EV gearboxes require specialized friction control chemistry that legacy mineral oil additives cannot satisfy, opening specification windows for synthetic ester formulations.
Market Restraints
- Palm Oil and Coconut Fatty Acid Volatility:Feedstock costs for natural ester production swing with Malaysian and Indonesian agricultural commodity markets, compressing margin predictability for non-integrated formulators.
- German REACH Registration Concentration:ECHA data requirements for novel chemical substances concentrate compliance expertise in a handful of European specialty houses, raising barriers for new market entrants.
- Group III Base Oil Substitution:High-quality hydrocracked mineral oils from Middle Eastern mega-refineries displace synthetic base stocks in cost-sensitive commercial vehicle segments, reducing premium additive treat rates.
Strategic Opportunities
- India's Industrial Lubricant Sector:BIS certification requirements for metalworking fluids remain underenforced in secondary manufacturing cities, creating first-mover advantages for additive suppliers establishing local technical service presence.
- Marine Stern Tube Lubricants:Vessel Environmental Protection Act compliance in North American waters mandates biodegradable friction modifiers, opening a specification channel distinct from automotive procurement patterns.
- Digital Oil Condition Monitoring:Integration of IoT sensors with lubricant management platforms enables performance-based additive replenishment contracts, shifting revenue from product sales to service subscriptions.
Industry Challenges
- Tribology-Chemistry Hybrid Talent Scarcity:Formulation teams require simultaneous expertise in surface science and synthetic organic chemistry, a combination rarely cultivated in standard chemical engineering curricula.
- Multi-Jurisdictional Test Matrix Expansion:Simultaneous pursuit of API, ACEA, and JASO certification for transmission fluid additives stretches R&D timelines and capital allocation across redundant bench test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Friction Modifier Additives Market |
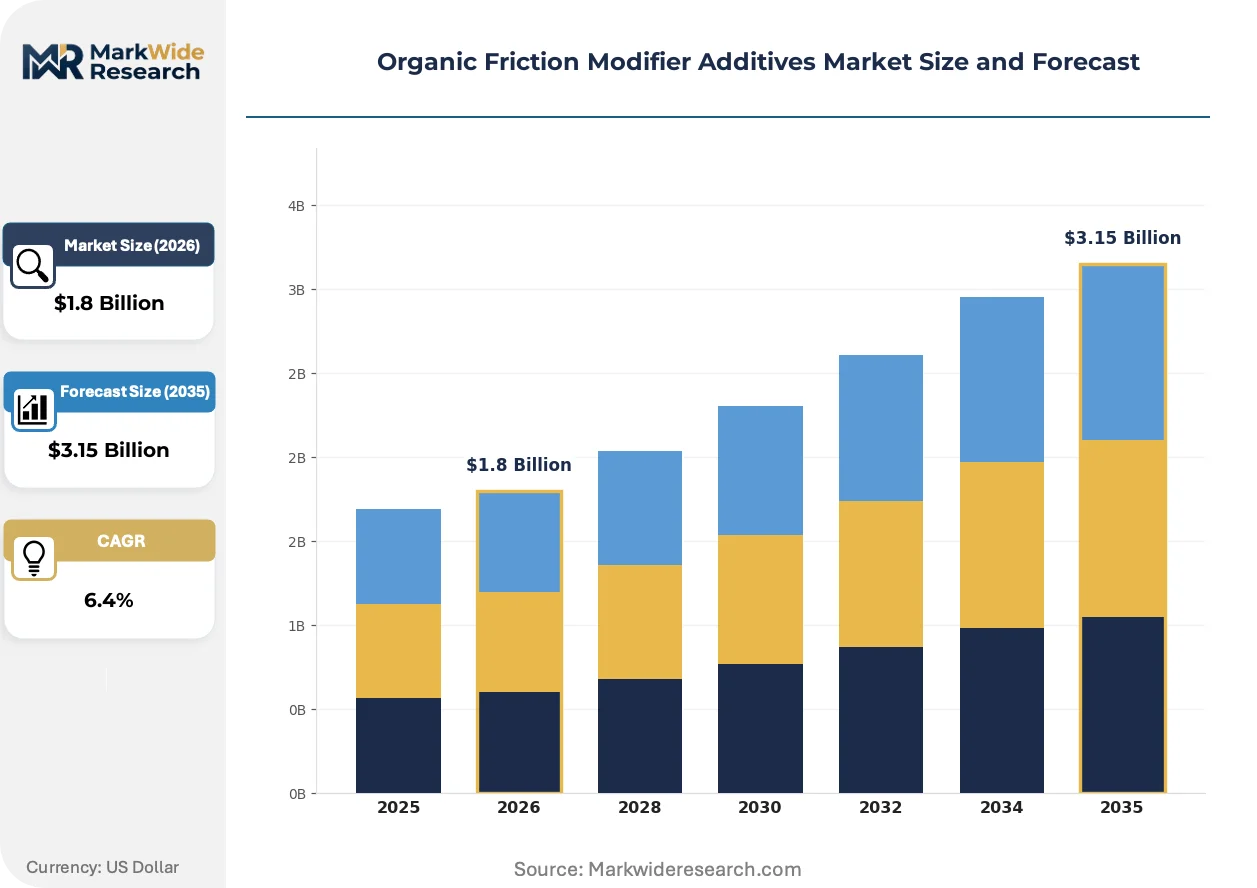
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fatty Acids, Esters, Alcohols, Amines Application: Automotive Transmissions, Industrial Lubricants, Greases, Metalworking Fluids End User: Automotive OEMs, Aerospace Manufacturers, Heavy Machinery, Marine Industry Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | BASF, Infineum International Limited, R.T. Vanderbilt Holding Company, LANXESS, Croda International PLC, Chevron Oronite Company LLC, Lubrizol Corporation, Afton Chemical Corporation, King Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Friction Modifier Additives Market Strategic Shifts
Friction modifier formulation is converging with sensor-enabled lubricant lifecycle management, compressing the traditional separation between additive chemistry and equipment maintenance economics.
Boron-nitride nanoparticle dispersions are miniaturizing friction reduction mechanisms at the asperity contact scale, enabling sub-micron film thickness control previously unattainable with molecular organic additives. Aerospace hydraulic system manufacturers in France and Germany have adopted these formulations for flight control actuators. The technology is miniaturizing the addressable wear surface, allowing additive treat rate reduction while maintaining friction coefficient targets.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating certain fluorinated friction modifiers from European lubricant formulations. Industrial grease manufacturers face reformulation deadlines that compress product development cycles. Metalworking fluid compounders in the Czech Republic and Poland are accelerating bio-based ester alternatives to maintain machinery export eligibility into German automotive supply chains.
Consolidated fleet operators now specify total cost of ownership metrics rather than unit price in lubricant procurement decisions. Long-haul trucking companies in the US Midwest negotiate drain interval guarantees tied to oil analysis data, displacing traditional volume-based distributor relationships. This behavioral shift concentrates purchasing power with national fleet management entities and marginalizes regional lubricant blenders lacking analytical service infrastructure.
Organic Friction Modifier Additives Market Segmentation
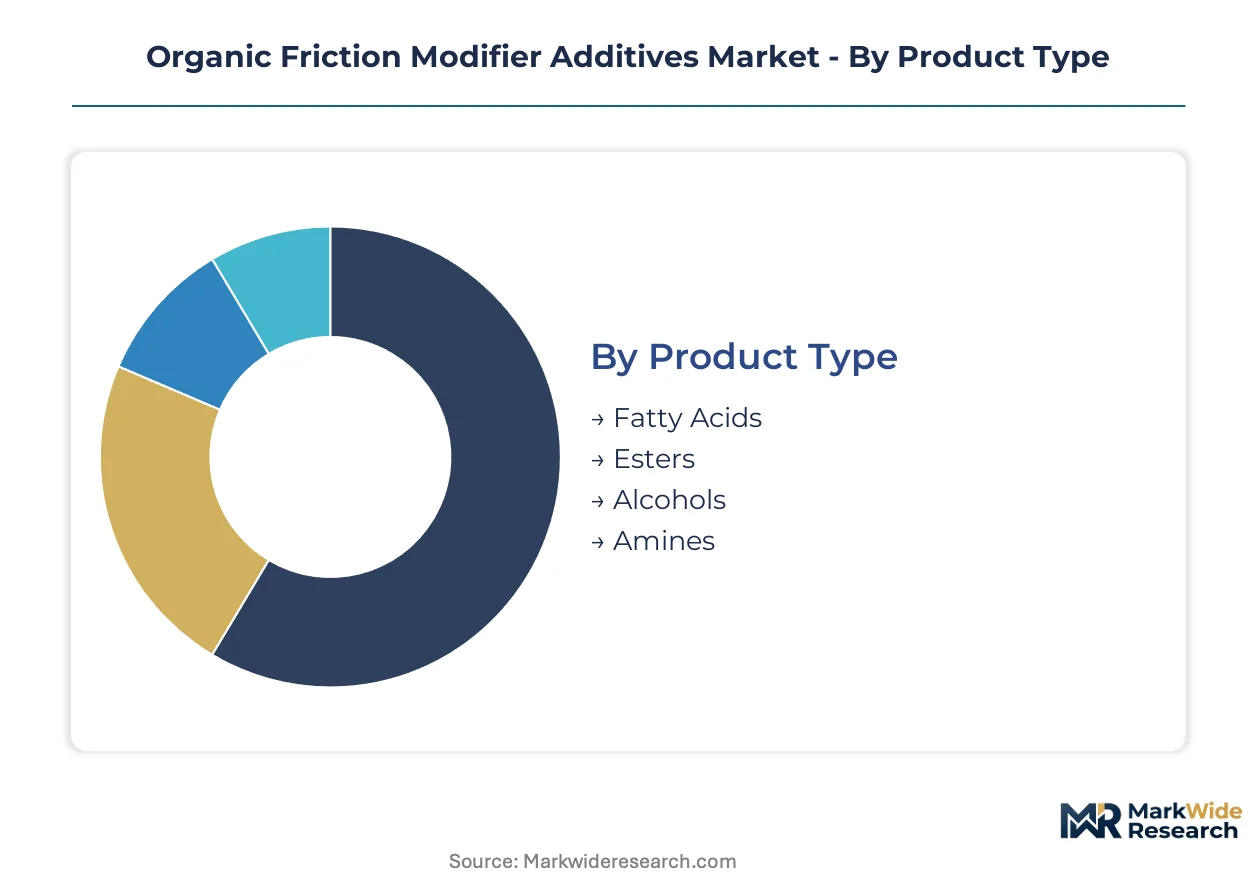
Segmentation in organic friction modifier additives reveals how formulation chemistry, application engineering, and procurement channels create distinct margin architectures. Suppliers must align R&D investment with the specific tribological demands and regulatory constraints governing each segment cluster.
Product Type:
Esters command premium pricing due to thermal stability requirements in next-generation transmission fluids, while fatty acid derivatives anchor volume throughput in cost-sensitive industrial segments.
- Fatty Acids:Long-chain carboxylic acids derived from vegetable oils adsorb onto metal surfaces through polar headgroup interactions, forming ordered monolayers that reduce boundary friction. Demand concentrates in metalworking fluids for China's Jiangsu and Shandong machinery clusters, where cost-per-liter constraints dominate procurement. Palm oil and coconut feedstock volatility compresses margin predictability for non-integrated formulators.
- Esters:Synthetic esters deliver superior oxidative stability and compatibility with Group III and Group IV base stocks, enabling extended drain intervals in dual-clutch and continuously variable transmissions. Automotive OEMs in Germany and the United States specify ester-based friction modifiers to meet tightening EPA fuel economy standards and avoid CAFE penalties.
- Alcohols:Fatty alcohols function as secondary friction modifiers in industrial gear oils, offering lower cost positioning than ester alternatives.
- Amines:Amine-based friction modifiers provide corrosion inhibition alongside tribological performance in marine stern tube lubricants.
Fatty acids hold installed capacity. Esters are rotating up the share rankings.
Application:
Automotive transmission fluids concentrate value capture, while industrial lubricants distribute volume across fragmented machinery maintenance budgets.
- Automotive Transmissions:Dual-clutch and CVT designs multiply contact points requiring precise friction coefficient control across temperature and shear regimes. OEM validation cycles in Germany's KBA certification framework and Japan's JASO protocols stretch 18-36 months, locking in supplier relationships.
- Industrial Lubricants:Hydraulic fluids and compressor oils for heavy machinery in China's domestic manufacturing sector absorb volume production of fatty acid derivatives.
- Greases:REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation of fluorinated friction modifiers in European industrial grease applications.
- Metalworking Fluids:Cutting and forming lubricants for automotive supply chains in the Czech Republic and Poland require bio-based ester alternatives to maintain machinery export eligibility into German OEM networks.
Automotive transmissions concentrate specification power. Industrial lubricants are expanding most quickly in absolute volume terms.
End User:
Automotive OEMs wield procurement concentration, while marine and aerospace segments open specialized specification channels with distinct regulatory compliance requirements.
- Automotive OEMs:Consolidated fleet operators and original equipment manufacturers negotiate total cost of ownership metrics tied to oil analysis data, displacing traditional volume-based distributor relationships. Long-haul trucking companies in the US Midwest specify drain interval guarantees that concentrate purchasing power with national fleet management entities.
- Heavy Machinery:Domestic scaling of excavator and wind turbine manufacturing in China drives demand for high-temperature-stable industrial lubricant additives.
- Aerospace Manufacturers:Hydraulic system manufacturers in France and Germany have adopted boron-nitride nanoparticle dispersions for flight control actuators, enabling sub-micron film thickness control.
- Marine Industry:Vessel Environmental Protection Act compliance in North American waters mandates biodegradable friction modifiers for stern tube lubricants, opening a specification channel distinct from automotive procurement patterns.
Automotive OEMs anchor contract value. Aerospace manufacturers are climbing the fastest in technical specification complexity.
Distribution Channel:
Direct sales relationships capture formulation co-development revenue, while distributor networks handle commoditized industrial volume.
- Direct Sales:Additive suppliers embed technical service teams at major lubricant blenders and automotive OEM formulation centers, enabling collaborative development of certified transmission fluid packages. These relationships span API, ACEA, and JASO certification timelines.
- Distributors:Regional lubricant distributors serve secondary manufacturing cities in India where BIS certification enforcement remains inconsistent.
- E-commerce:Digital platforms enable small-batch procurement for specialty metalworking fluid compounders seeking rapid formulation iteration.
- Retail:Consumer automotive lubricants reach do-it-yourself maintenance segments through retail channels with minimal friction modifier technical differentiation.
Direct sales holds relationship depth. E-commerce is gaining share fastest in specialty chemical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in organic friction modifier additives tilt toward net-import dependence in lubricant-consuming economies while integrated chemical clusters in Germany and the United States sustain additive export positions. China's domestic ester production capacity is narrowing its import gap for industrial-grade friction modifiers. India's formulation sector remains heavily reliant on imported active components from European specialty houses.
United States
Automotive OEM procurement of ester-based friction modifiers is accelerating as manufacturers face escalating CAFE penalties for fuel economy shortfalls. EPA emission standards and NHTSA safety protocols are tightening formulation requirements for transmission fluid additives. Detroit-area lubricant blenders are expanding technical service teams to support OEM validation cycles for next-generation dual-clutch transmission packages.
Germany
KBA certification frameworks and REACH registration requirements are concentrating compliance expertise among established specialty additive suppliers serving the domestic automotive sector. ECHA data requirements for novel chemical substances are extending validation timelines for reformulated friction modifier packages. Industrial lubricant demand in Baden-Württemberg's machinery manufacturing belt is absorbing high-purity ester production from integrated chemical sites along the Rhine corridor.
China
Domestic scaling of excavator and wind turbine manufacturing in Jiangsu and Shandong provinces is concentrating demand for high-temperature-stable industrial lubricant additives. SAMR and GB standards for lubricant performance are tightening import specifications for metalworking fluids and greases. Local ester production capacity in the Yangtze River Delta is expanding to serve both domestic industrial lubricant blenders and export markets across Southeast Asia.
India
BIS certification requirements for metalworking fluids remain underenforced in secondary manufacturing cities, creating first-mover advantages for additive suppliers establishing local technical service presence. DGFT import regulations are gradually tightening specification enforcement for lubricant raw materials. Maharashtra and Gujarat industrial corridors are absorbing growing volumes of fatty acid derivatives for cost-sensitive hydraulic fluid formulations serving domestic machinery maintenance budgets.
Japan
METI energy efficiency mandates are driving specification upgrades in automotive transmission fluids for the domestic vehicle manufacturing sector. JASO certification protocols are extending validation timelines for friction modifier packages targeting continuously variable transmission applications. Kansai-region lubricant compounders are specializing in synthetic ester formulations for precision friction control in hybrid vehicle powertrains.
Organic Friction Modifier Additives Market Competitive Environment
Concentration sits with integrated petrochemical majors and specialty additive houses that command backward integration into fatty acid feedstocks or high-purity ester chemistry capabilities. The vendor base separates into three strategic archetypes: multinational chemical conglomerates with captive raw material supply, mid-cap specialty houses focused on technical validation-intensive niches, and regional formulators serving cost-sensitive industrial segments. Dominant competitive moves include capacity expansion in high-purity ester production and strategic partnerships with automotive OEMs for co-development of certified transmission fluid packages.
Within the integrated petrochemical tier, BASF leverages European supply chain control over fatty acid feedstocks. Among specialty additive houses, Croda International PLC exemplifies the premium-niche archetype through technical validation cycles for electric vehicle transmission fluids. Lubrizol Corporation anchors the mid-cap specialist position with formulation expertise spanning automotive and industrial lubricant applications. These three companies represent distinct competitive positioning vectors rather than direct substitutability.
| Leading Market Players |
|---|
| BASF |
| Infineum International Limited |
| R.T. Vanderbilt Holding Company |
| LANXESS |
| Croda International PLC |
| Chevron Oronite Company LLC |
| Lubrizol Corporation |
| Afton Chemical Corporation |
| King Industries |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Malaysian palm oil processors and European ester manufacturers lock in both feedstock access and eighteen-month price visibility against agricultural commodity swings. These arrangements concentrate procurement power with integrated petrochemical majors while compressing margin buffers for non-captive formulators exposed to spot fatty acid markets.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in organic friction modifier additives. Price differentiation separates ester-based formulations validated under ACEA and JASO protocols from unbranded fatty acid derivatives serving cost-sensitive hydraulic fluid blenders. Cost compression in the economy tier is intensifying because Middle Eastern Group III base oil substitution reduces premium additive treat rates in commercial vehicle segments. Fleet operators negotiating total cost of ownership metrics demonstrate the lowest price sensitivity, while secondary manufacturing cities in India exhibit acute cost-per-liter constraints.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for Indonesian and Malaysian fatty acid shipments to Rotterdam and Hamburg. Geographic supply concentration centers on Germany, Malaysia, and China, with the Yangtze River Delta expanding domestic ester production capacity. Raw material dependencies draw from palm oil plantations, coconut fatty acid distillates, and synthetic alcohol feedstocks. Single-source vulnerability persists in high-purity ester chemistry where ECHA registration expertise concentrates among Rhine corridor specialty houses. Distribution runs through direct technical service relationships for automotive OEM validation cycles and regional distributor networks for industrial volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital oil condition monitoring platforms represent a service-attach opportunity expanding faster than hardware sales, with IoT-enabled replenishment contracts shifting revenue from product transactions to recurring performance-based subscriptions.
For Market Incumbents: Secure backward integration into Southeast Asian fatty acid feedstocks to insulate margin structures from palm oil price volatility. Expand technical service teams in China's Jiangsu and Shandong machinery clusters to defend against domestic ester producers capturing specification influence. Certification investment in EPA fuel economy validation cycles locks in automotive OEM relationships against emerging bio-based additive competitors. For New Entrants and Emerging Players: Technical service gaps in India's secondary manufacturing cities present white-space targets where BIS certification enforcement remains inconsistent. Marine stern tube lubricant specifications under the Vessel Environmental Protection Act offer a penetrable segment distinct from consolidated automotive procurement channels. Establish local analytical service partnerships to capture fleet operator drain interval guarantee contracts displacing traditional volume-based distributors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialty houses commanding ECHA registration expertise and electric vehicle transmission fluid validation cycles. Long-term viability over a multi-year horizon favors additive suppliers with captive ester production and automotive OEM co-development relationships. Watch for inflection signals in China's SAMR enforcement tightening import specifications for metalworking fluids and greases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Feedstocks | BASF's captive palm oil supply secures margin stability against Malaysian commodity volatility. |
| Electric Vehicle Transmission Fluid Co-Development | Croda's JASO validation cycles for synthetic esters capture premium specification windows. |
| Digital Oil Condition Monitoring Platform Launch | IoT sensor integration enables performance-based additive replenishment subscription revenue. |
| Marine Biodegradable Lubricant Certification | Vessel Environmental Protection Act compliance opens North American stern tube specification channels. |
| China Technical Service Expansion | Localized R&D presence in Yangtze River Delta defends against domestic ester capacity growth. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, and European Chemical Agency registration databases. Primary interviews engaged lubricant blender procurement directors, automotive OEM tribology engineers, additive supplier R&D heads, and marine classification society technical managers. Secondary validation drew from ACEA oil sequences, API service category documentation, and SAMR lubricant standard publications. Bottom-up demand modeling across end-use applications triangulates against top-down supply capacity assessments.
Segmentation dimensions modeled span product chemistry type, application engineering requirements, end-user procurement concentration, and regional regulatory framework clusters across the analysis window. CAGRs derive from unit consumption trajectories in transmission fluid formulations and industrial lubricant treat rate evolution. Forecast inputs incorporate EPA CAFE penalty escalation schedules and China's domestic heavy machinery production scaling.
Forecasts assume regulatory continuity in EPA emission standards and REACH Annex XVII substance restrictions; material policy shifts would require re-modeling. Palm oil feedstock volatility and German ECHA data requirement changes represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
North America Fuel Additives Market
Additives
Global Slip Additives Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Global Sizing Agents Market
Additives
Sorbitan Tristearate Market
Additives
Global Feed Acidifiers Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Allura Red AC Market
Additives
Automotive Additives Market
Additives
Anti-Creasing Agent Market
Additives
Sodium Stearyl Fumarate Market
Additives
Global Pour Point Depressant Market
Additives
Monocalcium Phosphate Market
Additives
Disodium Inosinate Market
Additives
Dry-Mix Mortar Additives and Chemicals Market