
 Sodium Diacetate Market | 2026-2036
Sodium Diacetate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Diacetate Market Analytics
Asset-light leasing arrangements for fermentation capacity are fragmenting competitive dynamics in sodium diacetate supply. Corbion leverages its integrated biotechnology platform to control raw material flows from corn-derived acetic acid through finished powder. Niacet sustains cost advantages through captive sodium acetate production and long-standing pharmaceutical-grade certifications. Kerry Group competes by embedding sodium diacetate within broader clean-label preservative systems sold to multinational food manufacturers.
Sodium diacetate is a molecular compound of sodium acetate and acetic acid, typically standardized at a 1:1 molar ratio with free acetic acid content ranging from 39% to 41%, functioning as an antimicrobial acidulant and pH regulator across food, feed, and industrial applications. Food Preservation dominates volume offtake as processors reformulate cured meats and baked goods to meet retailer clean-label mandates, while Animal Feed represents the fastest-expanding application segment driven by antibiotic-free livestock production protocols. Powder form anchors the majority of shipments due to handling efficiency in high-throughput seasoning operations, though liquid formulations are gaining traction in automated brine injection systems for processed proteins.
FDA food additive regulations under 21 CFR govern sodium diacetate's GRAS status and labeling requirements in the United States, while REACH compliance in Europe mandates full toxicological dossiers for importers exceeding volume thresholds. China's SAMR enforces GB standards for food-grade acidulants that foreign suppliers must meet through certified local testing laboratories. Stakeholders should monitor evolving EFSA opinions on acetic acid derivatives and position supply chains to absorb incremental certification burdens without margin erosion.
Market Dynamics
Clean-label reformulation mandates from major retailers are compressing synthetic preservative demand while elevating sodium diacetate's role in antimicrobial systems. This structural pull is redrawing supplier relationships and certification requirements across food manufacturing value chains.
Growth Catalysts
- FDA GRAS modernization:Updated food additive review protocols under 21 CFR are accelerating approval timelines for label-friendly acidulants in cured meat applications.
- Antibiotic-free livestock protocols:Poultry integrators in the United States are substituting ionophores with sodium diacetate-enhanced feed formulations to meet retailer procurement standards.
- Ready-to-eat snack expansion:Seasoning manufacturers in India are scaling powder-based sodium diacetate throughput to supply quick-service restaurant chains.
Market Restraints
- Acetic acid feedstock volatility:Corn-derived ethanol price swings directly transmit to sodium diacetate production economics, squeezing margin stability for non-integrated processors.
- REACH dossier burdens:ECHA toxicological data requirements for acetic acid derivatives impose six-figure compliance costs on European importers below 100-ton annual thresholds.
- Potassium sorbate substitution:Some baked goods manufacturers are reverting to established antimicrobials where sodium diacetate's acetic acid release complicates flavor profiles.
Strategic Opportunities
- Automated brine injection systems:Liquid sodium diacetate formulations are penetrating processed pork operations seeking precision pH control without powder handling infrastructure.
- India FSSAI alignment:Harmonized food-grade acidulant standards are reducing import friction for suppliers achieving dual FDA-FSSAI certification.
- Biotechnology platform convergence:Fermentation-derived acetic acid supply chains are merging with downstream sodium acetate crystallization to capture carbon accounting advantages.
Industry Challenges
- Pharmaceutical-grade certification timelines:USP and EP compliance for sodium diacetate excipient applications requires 18-24 month validation cycles that delay market entry.
- Legacy ERP integration:Food manufacturers running SAP or Oracle instances face customization costs when embedding sodium diacetate lot-tracking into existing antimicrobial inventory modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Diacetate Market |
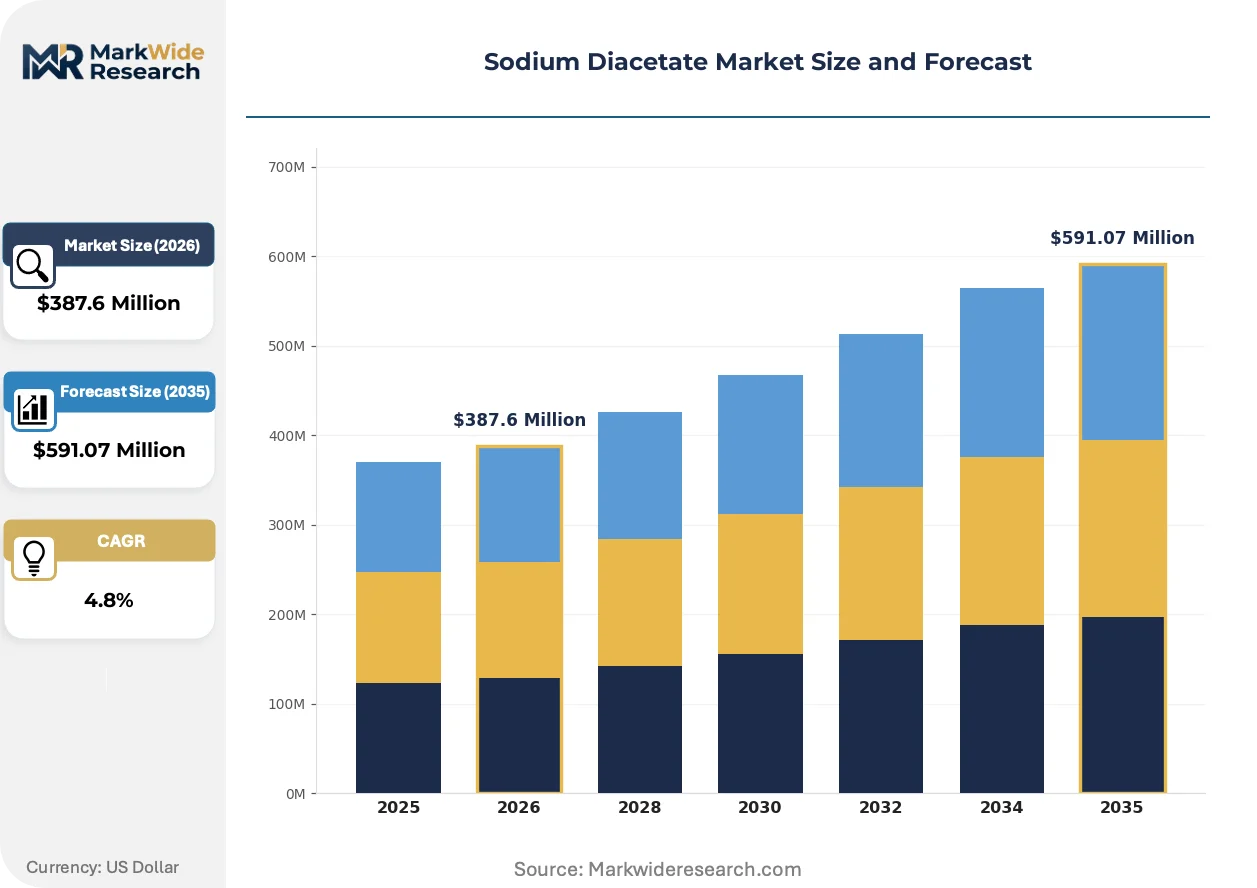
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Preservation, Animal Feed, Pharmaceuticals, Cosmetics Form: Powder, Granules, Liquid, Tablets End User: Food Manufacturers, Dietary Supplement Makers, Pharmaceutical Companies, Cosmetic Brands Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Corbion, ULRICH GmbH, Henan Honghui Biotechnology Co., Ltd., Vinipul Inorganics Pvt Ltd., Macco Organiques Inc., Niacet, Celanese, Fooding Group Limited, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Diacetate Market Evolving Landscape
Processing technology advances and regulatory recalibration are compressing traditional supply chain hierarchies. Sodium diacetate's functional versatility is enabling new application architectures while compliance frameworks evolve.
Encapsulated sodium diacetate with controlled-release acetic acid profiles is collapsing the performance gap between synthetic acidulants and natural alternatives in extended-shelf-life bakery applications. European manufacturers are piloting these systems to meet retailer clean-label mandates without sacrificing mold inhibition windows. The technology is collapsing reformulation timelines from 12 months to under 6 months for multinational baked goods portfolios.
REACH authorization amendments for acetic acid derivatives are tightening data requirements for importers above 10-ton annual volumes into the European Union. ECHA's updated guidance demands chronic toxicity studies that smaller suppliers cannot fund independently. Specialty chemical distributors are consolidating import licenses to spread compliance costs across pooled volumes.
Direct procurement relationships between sodium diacetate manufacturers and protein processors are displacing traditional ingredient distributor networks in North America. Cured meat operations are negotiating multi-year supply agreements with fixed-price mechanisms to hedge acetic acid volatility. This channel compression is most pronounced in the Midwest United States, where regional pork processors command sufficient volume to justify dedicated logistics arrangements.
Sodium Diacetate Market Segmentation
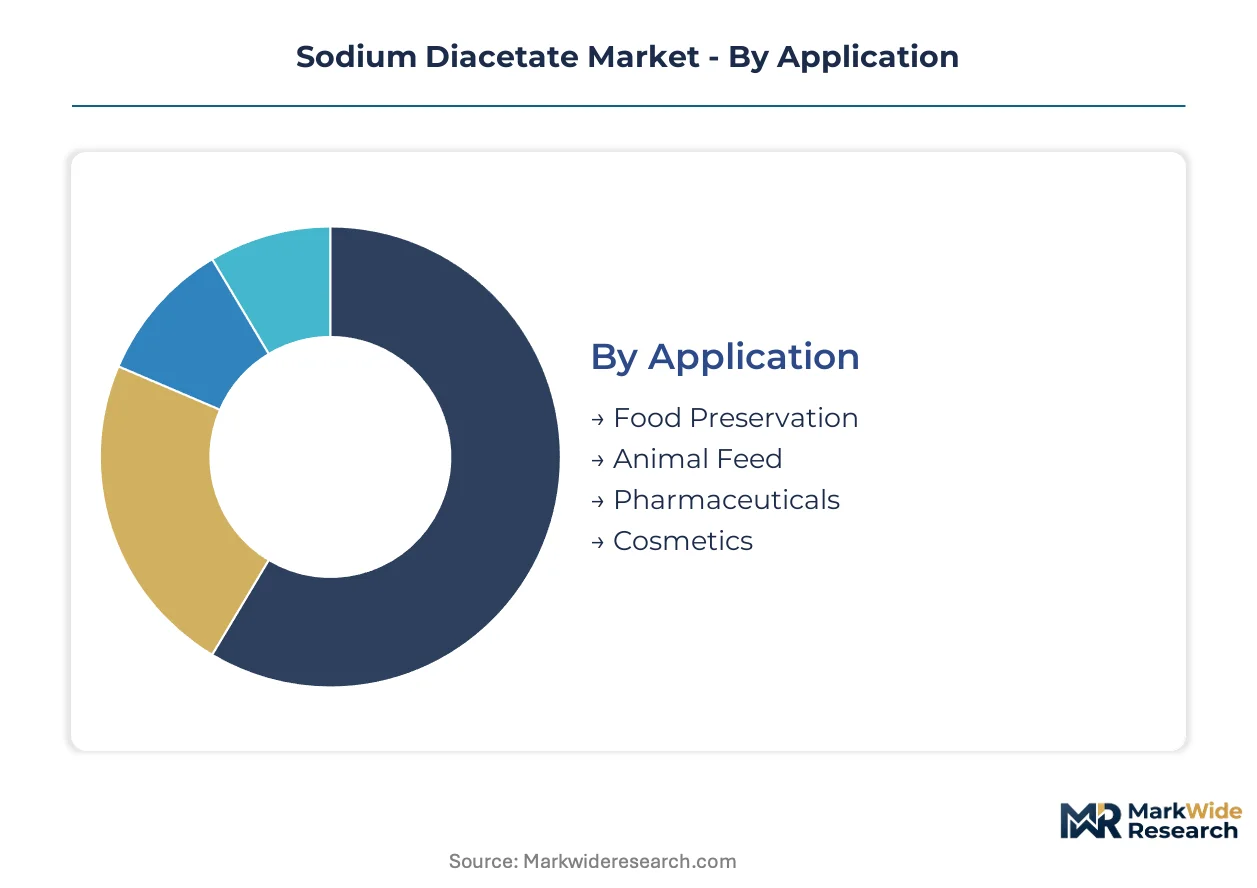
Sodium diacetate's functional versatility across antimicrobial, acidulant, and pH-regulating roles creates distinct demand profiles by application and formulation. Segmentation reveals where formulation complexity and regulatory certification concentrate margin capture.
Application:
After-sales technical support intensity varies sharply across applications, with pharmaceutical and food-grade certifications demanding ongoing compliance consulting that commodity feed sales rarely require.
- Food Preservation:Sodium diacetate functions as a GRAS-designated antimicrobial acidulant in cured meats, baked goods, and snack seasonings, releasing acetic acid to suppress bacterial growth. Demand concentrates in Midwest United States pork processing and Maharashtra, India snack manufacturing, driven by retailer clean-label mandates that displace synthetic preservatives like benzoates. By volume, Food Preservation leads. By growth pace, Animal Feed is ahead.
- Animal Feed:Poultry and swine integrators deploy sodium diacetate as an antibiotic-free growth promoter and mold inhibitor in complete feeds. Expansion is fastest in Iowa and North Carolina poultry operations responding to Costco and Walmart procurement standards prohibiting ionophores.
- Pharmaceuticals:USP and EP-grade sodium diacetate serves as an excipient pH modifier in tablet formulations and buffer systems. Indian API manufacturers in Hyderabad and Ahmedabad are scaling purchases to supply generic drug exporters.
- Cosmetics:Acidulant applications in personal care formulations remain niche, limited by odor profile constraints and preference for gentler organic acids in premium skincare.
Food Preservation dominates shipment volumes. Animal Feed climbs the fastest as livestock integrators reformulate.
Form:
Cost tier stratification separates commodity powder from premium liquid and tablet grades, with handling automation and dissolution speed driving price differentiation.
- Powder:Standardized free-flowing sodium diacetate with 39-41% acetic acid content anchors high-throughput seasoning operations and dry-blend feed formulations. Seasoning manufacturers in Gujarat, India and snack processors in Pennsylvania rely on pneumatic conveying compatibility.
- Liquid:Pre-dissolved aqueous solutions enable precision dosing in automated brine injection systems for processed proteins. Pork processors in Denmark and the Netherlands are adopting liquid formats to eliminate powder handling infrastructure.
- Granules:Agglomerated particles reduce dust generation during manual handling in smaller feed mills and artisanal bakeries lacking enclosed conveying systems.
- Tablets:Compressed sodium diacetate serves pharmaceutical manufacturing with controlled dissolution kinetics, requiring dedicated tablet press feed systems that limit adoption outside drug production.
Powder commands the largest volume share. Liquid formats gain share fastest in automated protein processing.
End User:
Customer type determines procurement patterns, with multinational food manufacturers negotiating multi-year supply agreements while dietary supplement makers purchase spot quantities through distributors.
- Food Manufacturers:Cured meat, bakery, and snack producers purchase sodium diacetate as a clean-label preservative system component. Tyson Foods and JBS operations in the United States specify dual-certified FDA-FSSAI grades for export flexibility.
- Dietary Supplement Makers:Capsule and tablet producers use sodium diacetate as a pH modifier in mineral formulations, with demand concentrated in Utah and California contract manufacturing clusters.
- Pharmaceutical Companies:Generic drug manufacturers in India and China source excipient-grade material with full ICH Q3D elemental impurity documentation.
- Cosmetic Brands:Formulators in France and South Korea incorporate sodium diacetate in rinse-off products where acetic acid odor dissipates, avoiding leave-on applications.
Food Manufacturers absorb the majority of volume. Pharmaceutical Companies are expanding most quickly as excipient qualification accelerates.
Distribution Channel:
Supply concentration in acetic acid production clusters shapes channel efficiency, with direct sales viable only where volume thresholds justify dedicated logistics.
- Distributors:Regional chemical distributors aggregate sodium diacetate with complementary acidulants and preservatives, serving mid-sized food manufacturers lacking procurement scale. Univar Solutions and Brenntag operations in the United States and Germany dominate this channel.
- Direct Sales:Large protein processors and pharmaceutical manufacturers negotiate direct supply agreements with sodium diacetate producers, locking in fixed-price mechanisms to hedge acetic acid volatility.
- Online Retail:E-commerce platforms serve small-scale cosmetic formulators and research laboratories requiring kilogram-scale quantities with rapid delivery.
- Wholesalers:Traditional agricultural supply wholesalers move sodium diacetate in blended feed additive packages to independent livestock operations in Brazil and Argentina.
Distributors handle the greatest volume. Direct Sales is climbing fastest as channel compression accelerates in North America.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean-label mandates from major retailers are redirecting procurement flows toward jurisdictions with harmonized food additive standards. Governments in key producing regions are tightening purity requirements while expanding export certification reciprocity.
United States
Poultry integrators in Iowa and North Carolina are reformulating feed to eliminate ionophores under Costco and Walmart procurement standards. FDA GRAS modernization under 21 CFR is accelerating approval timelines for acidulants in cured meat applications. Midwest pork processors in Minnesota and Illinois are negotiating direct supply agreements to hedge acetic acid volatility.
China
Processed meat and ready-to-eat snack manufacturers are scaling sodium diacetate throughput to supply domestic quick-service restaurant chains. SAMR enforces GB standards for food-grade acidulants that require certified local testing laboratory validation. Yangtze River Delta seasoning operations in Jiangsu and Zhejiang provinces are driving powder form demand through pneumatic conveying infrastructure.
India
Snack seasoning manufacturers in Maharashtra and Gujarat are expanding powder-based throughput for quick-service restaurant supply chains. FSSAI alignment with FDA standards is reducing import friction for dual-certified suppliers. Hyderabad and Ahmedabad pharmaceutical clusters are scaling USP-grade purchases to serve generic drug exporters.
Germany
Pork processors in Lower Saxony and North Rhine-Westphalia are adopting liquid sodium diacetate formats for automated brine injection systems. REACH authorization amendments for acetic acid derivatives are tightening toxicological data requirements above 10-ton annual import volumes. ECHA's updated guidance is consolidating import licenses among specialty chemical distributors.
Brazil
Poultry and swine integrators in São Paulo and Paraná are deploying sodium diacetate as an antibiotic-free growth promoter under export-oriented production protocols. ANVISA food additive regulations govern import purity requirements for acidulants entering processed meat value chains. Agricultural supply wholesalers in Rio Grande do Sul are moving sodium diacetate in blended feed additive packages to independent livestock operations.
Sodium Diacetate Market Competitive Landscape
On the supply side, the industry is consolidating around biotechnology-integrated platforms and captive raw material production. Three strategic archetypes dominate: fermentation-derived acetic acid specialists with downstream crystallization capabilities, sodium acetate producers with acid neutralization integration, and clean-label preservative system integrators. Competitive moves center on multi-year supply agreements with fixed-price mechanisms and pharmaceutical-grade certification expansion.
Among European chemical specialists, ULRICH GmbH exemplifies the premium-grade archetype through its positioning in high-purity acidulant supply. Henan Honghui Biotechnology Co., Ltd. anchors the China-based fermentation platform tier, representing integrated biotechnology approaches to acetic acid derivatives. Kerry Group occupies the preservative system integrator position, embedding sodium diacetate within broader clean-label antimicrobial portfolios sold to multinational food manufacturers.
| Leading Market Players |
|---|
| Corbion |
| ULRICH GmbH |
| Henan Honghui Biotechnology Co., Ltd. |
| Vinipul Inorganics Pvt Ltd. |
| Macco Organiques Inc. |
| Niacet |
| Celanese |
| Fooding Group Limited |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Corn-derived acetic acid production clustering in the United States and China anchors margin capture downstream, with fermentation capacity concentration in the Yangtze River Delta and Midwest ethanol corridors dictating where pricing power accrues to integrated processors versus merchant market participants.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade USP/EP material and commodity feed-grade powder, with FDA-FSSAI dual-certified food-grade occupying a mid-tier position. Three-tier pricing structure across premium excipient, standard food-grade, and economy feed-grade levels reflects validation burden differentials. Cost compression in commodity powder tiers is intensifying because corn ethanol volatility transmits directly to non-integrated processors. Feed-grade buyers exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Extended payment terms from large protein processors in the United States and pharmaceutical manufacturers in India are reshaping working capital requirements for sodium diacetate producers. Supply concentrates in China, the United States, and India, with Jiangsu province and Iowa ethanol corridors feeding downstream crystallization. Production rests on corn-derived acetic acid, sodium carbonate, and fermentation-derived sodium acetate as core inputs. Single-source vulnerability in acetic acid supply creates structural exposure to biofuel policy shifts. Distribution runs through specialty chemical distributors in Europe and direct sales relationships in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sodium diacetate market is approaching a platform-economics inflection as clean-label preservative systems integrate acidulants, antimicrobials, and pH modifiers into unified ingredient platforms, with Kerry Group's bundled offerings demonstrating interoperability advantages over standalone commodity suppliers.
For Market Incumbents: Entrench position through captive sodium acetate production and pharmaceutical-grade certification expansion that potassium sorbate substitutors cannot match. Prioritize backward integration into fermentation-derived acetic acid to neutralize corn ethanol volatility exposure. Lock in multi-year supply agreements with Midwest pork processors and Iowa poultry integrators before channel compression accelerates. For New Entrants and Emerging Players: Build out liquid formulation capabilities for automated brine injection systems in European pork processing, where powder-handling infrastructure gaps create penetrable white space. Target Maharashtra snack seasoning manufacturers with pneumatic-conveying-compatible powder grades. Pursue dual FDA-FSSAI certification as the primary go-to-market credential for export-flexible supply positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fermentation platform operators lacking downstream sodium acetate crystallization capabilities. Five-to-ten-year viability hinges on biotechnology convergence and carbon accounting advantages in acetic acid supply chains. Monitor EFSA opinion timelines on acetic acid derivatives as the signal for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetic Acid | Captive fermentation capacity insulates Corbion and Niacet from corn ethanol price swings. |
| Pharmaceutical-Grade Certification Expansion | USP and EP compliance opens excipient markets in Hyderabad and Ahmedabad API clusters. |
| Liquid Formulation Development | Pre-dissolved sodium diacetate penetrates Danish and Dutch automated brine injection systems. |
| Dual FDA-FSSAI Certification | Harmonized standards reduce import friction for suppliers targeting India snack manufacturing. |
| Long-term Supply Agreements | Fixed-price mechanisms with Tyson and JBS operations hedge acetic acid volatility exposure. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, ECHA REACH dossiers, FSSAI food additive registrations, and trade flow data from customs authorities. Interviews with sodium diacetate plant managers, procurement leads at Midwest pork processors, poultry integrator feed formulation directors, and specialty chemical distribution partners were cross-validated against SEC filings from Corbion and Kerry Group, GB standard documentation from SAMR, and industry association reports from the American Chemistry Council. Bottom-up volume estimates from application-level consumption patterns were triangulated against top-down production capacity assessments.
Forecast inputs include acetic acid feedstock cost trajectories, clean-label reformulation adoption curves across cured meat and snack categories, antibiotic-free livestock protocol penetration rates, and regulatory certification timeline assumptions across the analysis window. Segmentation modeling spans application tier, form factor, end-user category, and regional production hub. CAGRs were derived from regression analysis against historical price-volume relationships and forward-looking capacity expansion announcements. Industry-specific inputs encompass corn ethanol policy sensitivity and EFSA opinion evolution on acetic acid derivatives.
Stress conditions across corn price volatility bands, REACH authorization amendment stringency, and potassium sorbate substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory stability and feedstock supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Calcium Diglutamate Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Global Peptone Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Diamino Stilbene Disulfonic Acid (DASDA) Market
Additives
Phenolic Antioxidant Market
Additives
Refining Additives Market
Additives
Tocopheryl Acetate Market
Additives
Friction Modifier Additives Market
Additives
Europe Fuel Additives Market
Additives
Viscosity Reducing Agents Market
Additives
Enzyme Stabilizer Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Canada Anti-Caking Market
Additives
Antimicrobial Ingredients Market
Additives
Global Carboxylic Acids Based Esters Market