
 South Africa Acidulants Market | 2026-2036
South Africa Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Acidulants Market Analytics
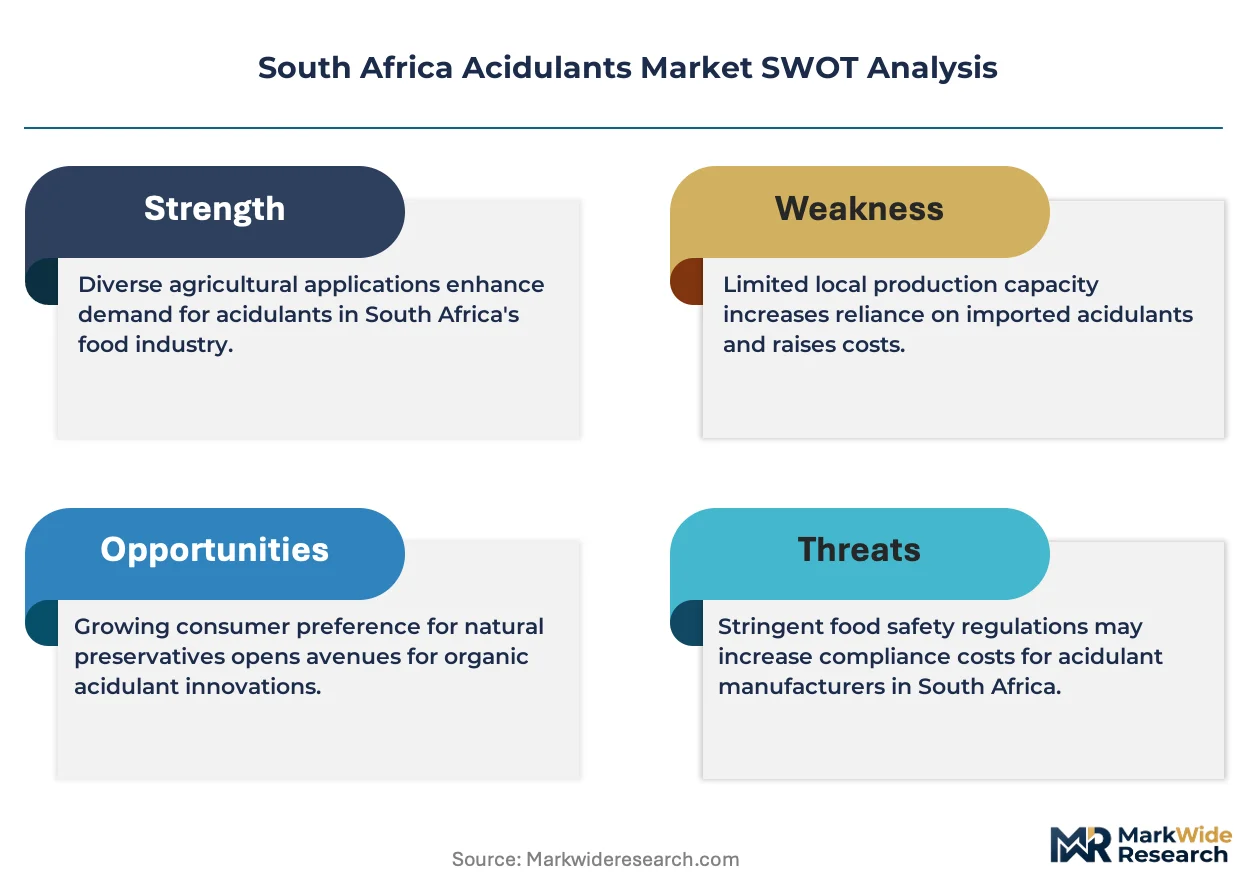
HACCP certification and FSSC 22000 qualification cycles is collapsing the supplier base to food-grade compliant manufacturers. Corbion N.V. leverages its fermentation technology leadership to dominate citric acid supply chains across Southern Africa. Cargill anchors its position through backward integration into corn-derived feedstock processing. Jungbunzlauer Suisse AG differentiates via specialized lactic acid grades for pharmaceutical applications.
Acidulants are organic or inorganic compounds that impart sourness, control pH, and function as preservatives or chelating agents, typically manufactured through fermentation, chemical synthesis, or extraction processes with purity thresholds exceeding 99.5% for food and pharmaceutical grades. Citric acid leads product type demand due to its versatility across beverage acidification and antioxidant stabilization. Phosphoric acid commands concentrated margin pools from cola manufacturers seeking specific taste profiles. Lactic acid represents the fastest-growing product type as clean-label formulations displace synthetic preservatives in dairy alternatives and personal care products.
South Africa's Department of Health enforces the Foodstuffs, Cosmetics and Disinfectants Act alongside mandatory compliance with SANS standards for food additive safety, directly shaping formulation choices and import documentation burdens. The National Regulator for Compulsory Specifications oversees quality benchmarks that determine market access for imported acidulant shipments. Stakeholders must monitor evolving SANS amendments and Department of Agriculture reformulation incentives to anticipate qualification requirements and procurement cost shifts.
Market Dynamics
Food-grade certification requirements under South Africa's Foodstuffs, Cosmetics and Disinfectants Act are consolidating supplier relationships toward HACCP and FSSC 22000 compliant manufacturers, compressing the vendor base while elevating procurement costs for non-qualified entrants.
Growth Catalysts
- Clean-label dairy alternatives:Lactic acid demand from plant-based beverage formulators in Cape Town's processing cluster is accelerating as synthetic preservative displacement becomes a formulation priority.
- SANS 1027 compliance mandates:Tighter additive labeling requirements are forcing manufacturers toward high-purity acidulant grades, creating qualification barriers that favor established fermentation-based suppliers.
- Gauteng beverage corridor expansion:Carbonated and functional drink producers in Johannesburg's industrial belt are scaling acidulant volumes for pH control and flavor stability.
Market Restraints
- Corn feedstock volatility:Cargill's backward integration into maize-derived glucose processing exposes citric acid supply chains to South African agricultural input price swings.
- Import documentation burdens:National Regulator for Compulsory Specifications quality benchmarks create shipment delays and qualification costs for non-domestic acidulant sources.
- Phosphoric acid substitution pressure:Cola manufacturers seeking specific taste profiles remain locked into phosphoric acid despite margin compression, limiting citric acid penetration in this segment.
Strategic Opportunities
- Western Cape pharmaceutical-grade lactic acid:Jungbunzlauer's specialized grades for personal care applications remain underexploited in South Africa's cosmetic formulation sector.
- Department of Agriculture reformulation incentives:Emerging subsidy frameworks for natural preservative adoption could accelerate clean-label acidulant procurement across processed food categories.
- Fermentation technology convergence:Corbion's microbial production platforms paired with enzymatic purification advances enable domestic manufacturing cost parity with imported Asian supply.
Industry Challenges
- FSSC 22000 auditor scarcity:Limited certification body capacity in South Africa extends supplier qualification timelines from 12 to 18 months, constraining new market entry.
- Legacy ERP integration:Batch traceability requirements for SANS compliance force mid-tier manufacturers into costly system overhauls for acidulant lot tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Acidulants Market |
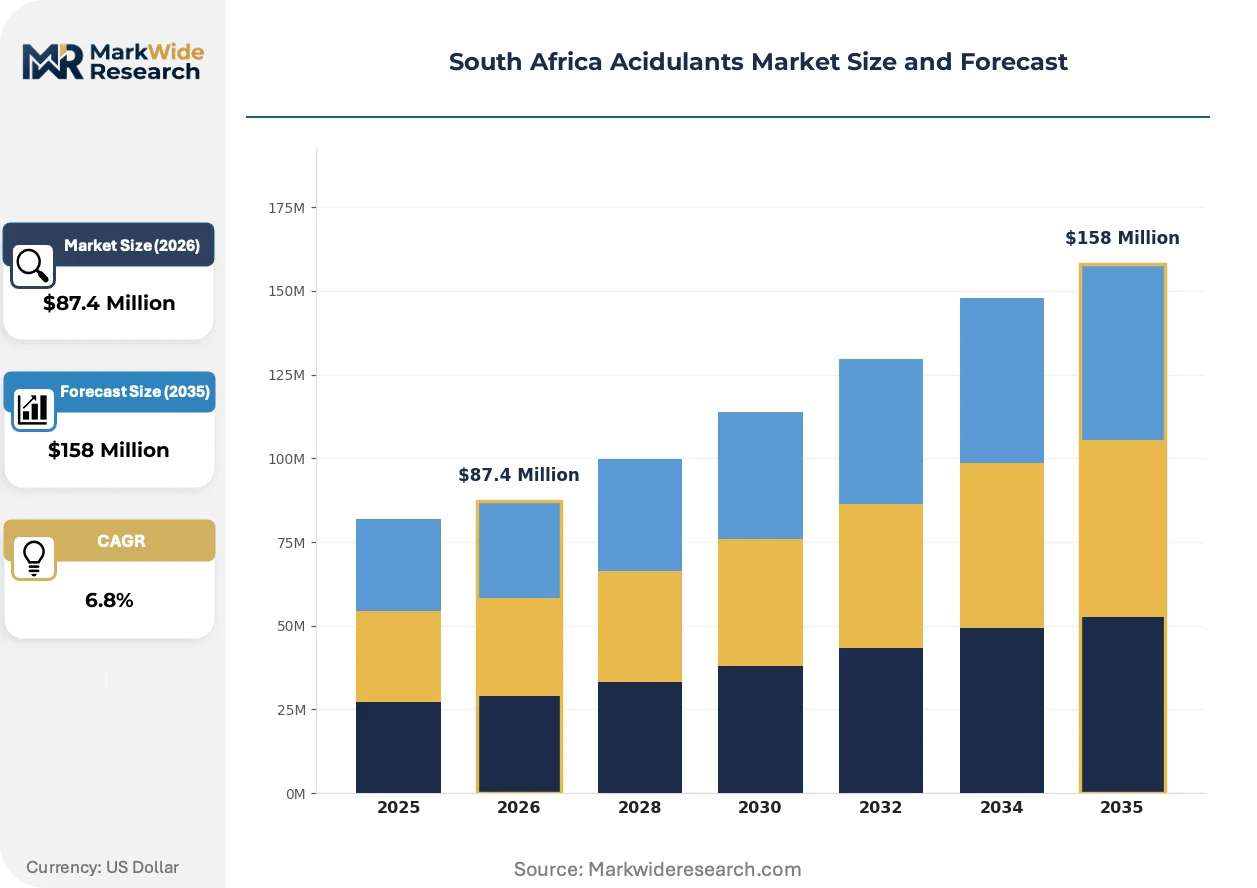
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Phosphoric Acid, Lactic Acid, Acetic Acid Application: Food & Beverages, Pharmaceuticals, Cosmetics, Cleaning Products End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Cosmetic Manufacturers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Corbion N.V., Archer Daniels Midland, Cargill, Tate & Lyle, Jungbunzlauer Suisse AG, Brenntag North America, Univar Solutions LLC, Hawkins Watts Ltd., Bartek Ingredients Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Acidulants Market Evolving Landscape
Biotechnological fermentation advances and regulatory purity mandates are restructuring how acidulants are manufactured, certified, and procured across South African food and pharmaceutical value chains.
Enzymatic citric acid purification is supplanting traditional calcium salt precipitation methods in high-volume production. Beverage manufacturers in Johannesburg's industrial corridor are adopting these grades for antioxidant stabilization. The shift is compressing qualification timelines for suppliers while elevating purity thresholds above 99.7%.
Amendments to the Foodstuffs, Cosmetics and Disinfectants Act are tightening maximum permissible limits for residual solvents in acidulant imports. South Africa's Department of Health is expanding testing protocols at Durban and Cape Town ports. Pharmaceutical-grade lactic acid shipments face the heaviest documentation burdens, with rejections rising for non-compliant certificates of analysis.
Direct procurement contracts between acidulant users and fermentation specialists are displacing traditional distributor intermediaries in the Western Cape food processing cluster. Large-scale dairy alternative manufacturers are negotiating volume commitments with Corbion's regional operations. This channel compression is most visible in Cape Town, where three major plant-based beverage producers have eliminated chemical trading houses from their supply chains since 2024.
South Africa Acidulants Market Segmentation
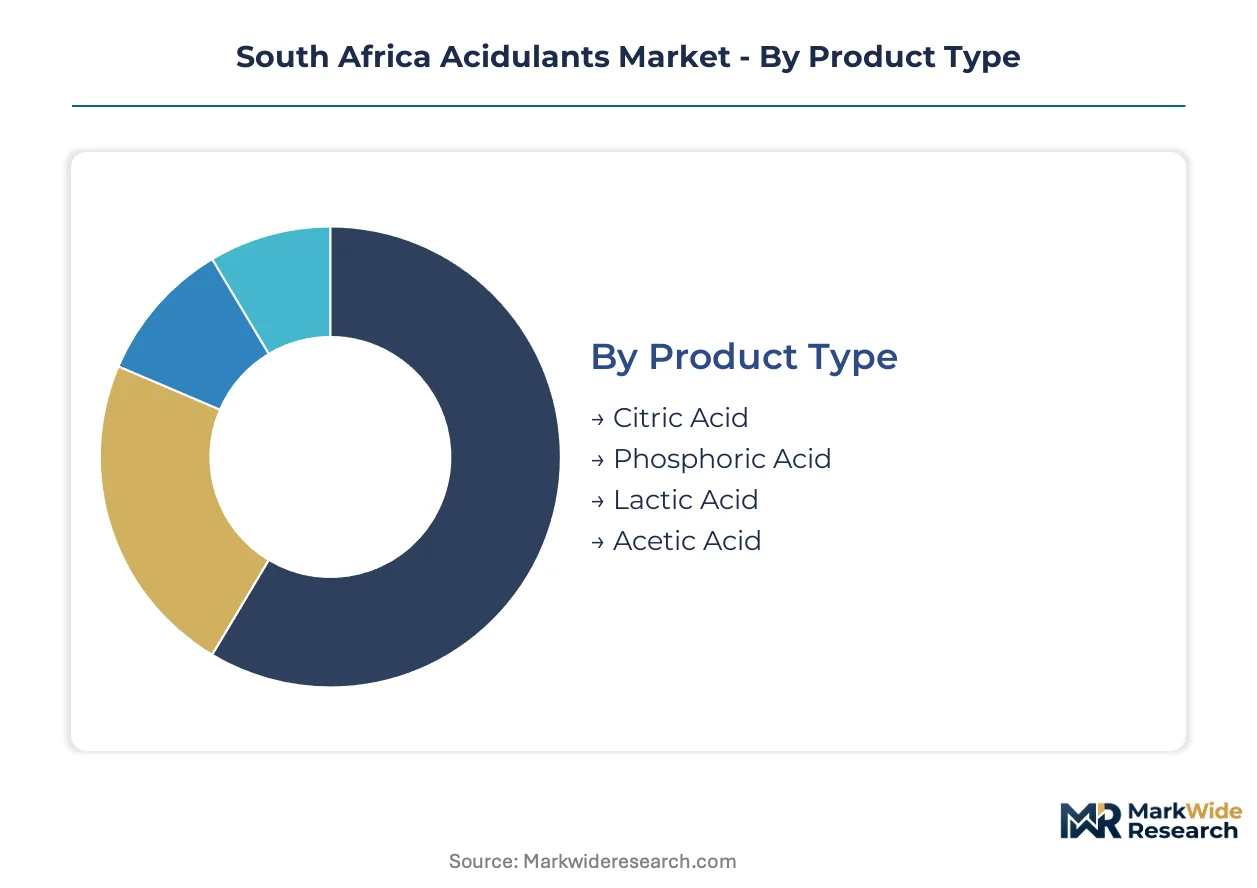
Acidulant procurement patterns in South Africa diver sharply between commodity-grade bulk shipments and specialized pharmaceutical certifications. Segmentation reveals how Gauteng's beverage corridor and Cape Town's processing cluster pull different product specifications through distinct channel configurations.
Product Type:
Citric acid and phosphoric acid dominate domestic production volumes, while lactic acid shipments increasingly serve export-oriented pharmaceutical formulators.
- Citric Acid:Fermentation-derived tricarboxylic acid with purity thresholds exceeding 99.5% for food-grade applications. Johannesburg's carbonated beverage manufacturers consume bulk volumes for pH stabilization and antioxidant preservation in cola and functional drink formulations.
- Phosphoric Acid:Inorganic acid produced through wet-process phosphate rock treatment, delivering the sharp, dry taste profile cola manufacturers specifically require. Cape Town's concentrate bottlers maintain dedicated procurement contracts despite margin compression from energy-intensive production.
- Lactic Acid:Bacterial fermentation product displacing synthetic preservatives in clean-label dairy alternatives.
- Acetic Acid:Synthetic and biomass-derived grades serving vinegar production and industrial cleaning formulations.
Citric acid commands the established base. The steepest expansion runs through lactic acid as clean-label reformulation accelerates.
Application:
Cost tier differentiation separates commodity food-grade volumes from premium pharmaceutical certifications requiring extensive documentation.
- Food & Beverages:Acidification, preservation, and flavor enhancement across processed foods and carbonated drinks. Gauteng's industrial corridor concentrates procurement for pH control in meat processing and beverage manufacturing, with SANS 1027 compliance mandating residue testing.
- Pharmaceuticals:pH adjustment and active pharmaceutical ingredient stabilization requiring certificates of analysis for every lot. Durban port inspections under Department of Health protocols create documentation burdens that favor established fermentation suppliers with dedicated regulatory affairs capacity.
- Cosmetics:pH balancing and preservative boosting in personal care formulations.
- Cleaning Products:Descaling and antimicrobial applications in industrial and household formulations.
Food and beverage applications anchor volume procurement. Pharmaceutical-grade demand climbs fastest as domestic manufacturing expands.
End User:
Customer type determines contract structure, with multinational beverage producers negotiating direct supply agreements while mid-tier food manufacturers rely on distributor intermediaries.
- Food Manufacturers:Processed meat, bakery, and convenience food producers requiring consistent acidification for shelf-life extension. Cape Town's processing cluster shows accelerating lactic acid adoption as synthetic preservative displacement becomes a formulation priority.
- Beverage Producers:Carbonated and functional drink manufacturers with volume procurement power. Johannesburg's industrial belt concentrates cola and energy drink production, locking in phosphoric acid contracts despite citric acid substitution potential.
- Pharmaceutical Companies:Domestic and multinational drug manufacturers requiring compendial-grade acidulants.
- Cosmetic Manufacturers:Personal care formulators seeking natural-origin acidulants for marketing claims.
Beverage producers dominate contract volumes. Pharmaceutical companies drive the fastest specification escalation.
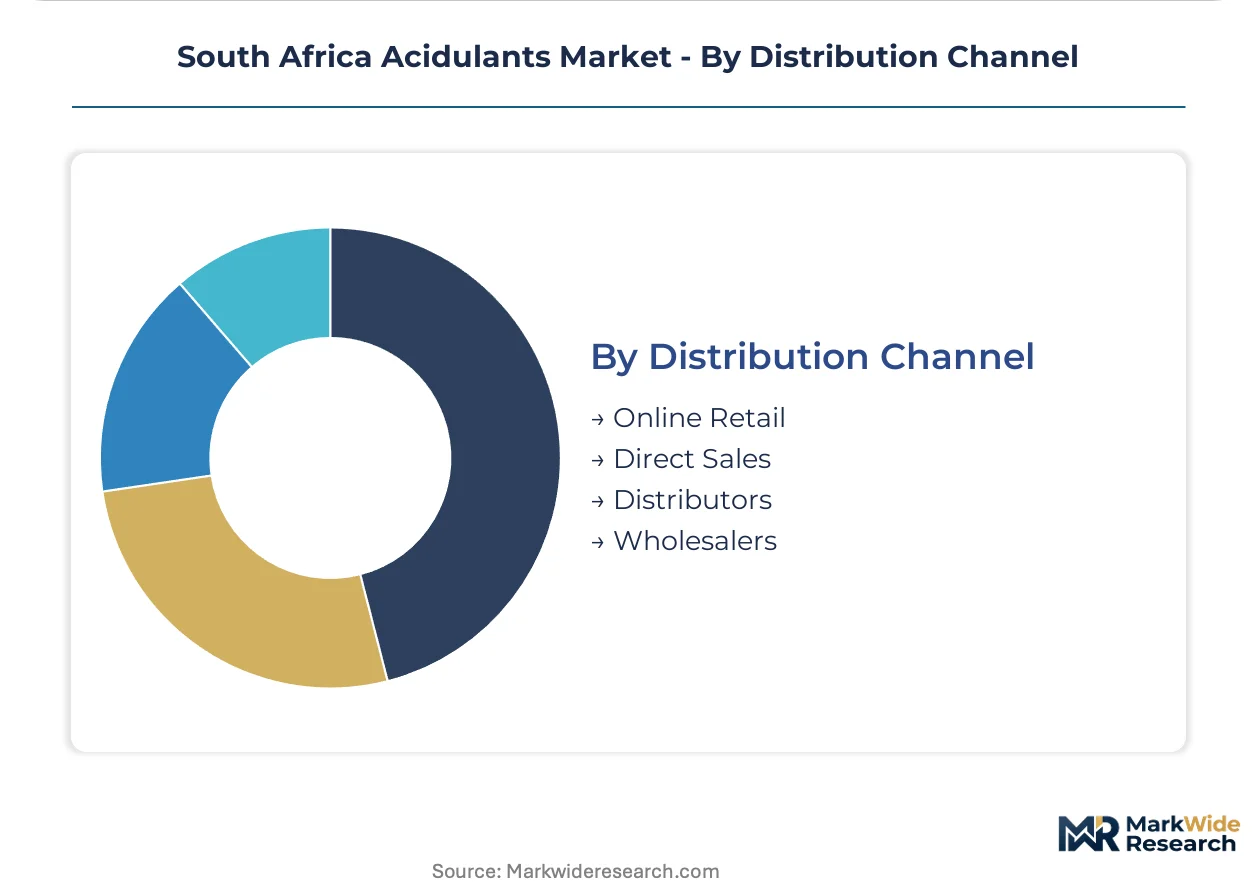
Distribution Channel:
Supply concentration in fermentation-based manufacturing is compressing traditional distributor roles as direct procurement expands.
- Direct Sales:Volume contracts between acidulant users and fermentation specialists eliminating intermediary margins. Three major plant-based beverage producers in the Western Cape have eliminated chemical trading houses from their supply chains since 2024.
- Distributors:Regional chemical traders serving mid-tier manufacturers without procurement scale. KwaZulu-Natal distributors maintain inventory positions for smaller food processors lacking direct supplier relationships.
- Online Retail:Small-volume procurement for laboratory and specialty formulation applications.
- Wholesalers:Bulk aggregation for industrial cleaning and agricultural acidulant applications.
Direct sales channels capture the largest volume flows. Online retail expands most quickly for specialty and laboratory grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers and pharmaceutical formulators concentrate acidulant procurement in South Africa's three dominant industrial corridors, with regulatory compliance requirements varying sharply across provincial boundaries.
Gauteng
Johannesburg's industrial belt hosts the densest concentration of carbonated drink producers and meat processors. The Department of Health's Foodstuffs, Cosmetics and Disinfectants Act enforcement tightens additive labeling requirements here first. Midrand and Vereeniging processing plants are scaling citric acid volumes for pH stabilization in energy drink formulations.
Western Cape
Cape Town's food processing cluster drives lactic acid demand from plant-based dairy alternative manufacturers. SANS 1027 compliance mandates force formulators toward high-purity acidulant grades. Stellenbosch and Paarl facilities are eliminating distributor intermediaries through direct procurement contracts with fermentation specialists.
KwaZulu-Natal
Durban port serves as the primary entry point for imported acidulant shipments facing National Regulator for Compulsory Specifications inspections. The Department of Agriculture's emerging reformulation incentives for natural preservatives target Pietermaritzburg's processed food manufacturers. Pinetown chemical traders maintain inventory positions for mid-tier processors lacking direct supplier scale.
Eastern Cape
Gqeberha's automotive sector spillover creates niche demand for industrial cleaning acidulants. Provincial environmental regulators scrutinize phosphoric acid handling protocols more intensively than national baseline standards. East London manufacturers blend acetic acid derivatives for agricultural and descaling applications.
South Africa Acidulants Market Competitive Landscape
Player mix skews toward fermentation-based specialists with backward integration into feedstock processing. Supplier relationships are consolidating around HACCP and FSSC 22000 compliant manufacturers, compressing the vendor base while elevating qualification barriers. Three strategic archetypes dominate: fermentation technology leaders, corn-derived feedstock integrators, and specialized pharmaceutical-grade producers. Competitive moves center on direct procurement contract expansion and enzymatic purification technology licensing.
Within the fermentation technology tier, Corbion N.V. and Jungbunzlauer Suisse AG occupy positions exemplifying divergent specialization vectors. Corbion represents the citric acid supply chain dominance anchored in microbial production platforms. Jungbunzlauer sits within the pharmaceutical-grade lactic acid niche serving personal care and drug formulation applications. Cargill anchors the feedstock integration archetype through corn-derived glucose processing exposure.
| Leading Market Players |
|---|
| Corbion N.V. |
| Archer Daniels Midland |
| Cargill |
| Tate & Lyle |
| Jungbunzlauer Suisse AG |
| Brenntag North America |
| Univar Solutions LLC |
| Hawkins Watts Ltd. |
| Bartek Ingredients Inc. |
| Others |
Value Network & Pricing Analysis
Forty-five to sixty-day inventory cycles at Durban port compress negotiating leverage for mid-tier processors while amplifying margin capture by fermentation specialists with captive glucose supply. This lead-time exposure concentrates pricing power among Corbion and Cargill, whose backward integration into maize-derived feedstock processing insulates them from South African agricultural spot volatility.
Pricing Analysis
Cost-plus contracts indexed to South African maize futures dominate procurement between beverage manufacturers and citric acid suppliers. Pricing stratifies across pharmaceutical-grade, food-grade, and industrial-grade certification tiers, with SANS 1027 compliance premiums widening spreads. Cost compression in commodity citric acid is intensifying because enzymatic purification technology from Asian suppliers is penetrating the market. Mid-tier food manufacturers show highest price sensitivity, while multinational cola producers accept premium phosphoric acid pricing for taste-profile lock-in.
Supply Chain Analysis
Sixty-day port clearance timelines at Durban expose distributors to working capital strain while favoring direct-ship arrangements with fermentation specialists. Supply concentrates in the Netherlands, China, and Thailand for citric acid fermentation capacity, while phosphoric acid draws from Moroccan and Tunisian phosphate rock processing. South African maize, imported glucose syrup, and energy-intensive purification inputs anchor cost structures. Single-source vulnerability runs through Corbion's microbial production platform dominance. Distribution runs through direct sales for volume buyers and regional chemical traders for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense as citric acid formulators face displacement pressure from lactic acid in clean-label dairy alternatives. Incumbents must navigate the threat of synthetic preservative elimination mandates while protecting phosphoric acid's cola manufacturer lock-in.
For Market Incumbents: Secure FSSC 22000 certification capacity expansion ahead of auditor scarcity constraints. Deepen backward integration into Western Cape fermentation facilities to capture lactic acid substitution momentum. Defend against Jungbunzlauer's pharmaceutical-grade penetration by accelerating enzymatic purification licensing.
For New Entrants and Emerging Players: Lead with specialized lactic acid grades targeting Cape Town's plant-based beverage cluster, the most penetrable segment given clean-label reformulation urgency. Exploit the 12-to-18-month qualification timeline gap by pre-certifying with SANS compliance ahead of volume commitment negotiations. Position through direct procurement contracts that eliminate distributor margins.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because fermentation technology convergence and regulatory compliance barriers are compressing the vendor base toward qualified manufacturers. Target acquisition archetypes include mid-tier distributors with established SANS certification relationships and captive port logistics at Durban. Watch for Department of Agriculture reformulation incentive announcements as inflection signals for natural preservative demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maize Processing | Cargill's captive glucose supply insulates margin structures from South African agricultural spot price swings. |
| Enzymatic Purification Technology Licensing | Corbion's microbial platforms paired with enzymatic advances enable domestic cost parity with Asian imports. |
| FSSC 22000 Certification Pre-Qualification | Auditor scarcity in South Africa extends qualification timelines, creating first-mover advantage for certified entrants. |
| Direct Procurement Contract Expansion | Three Western Cape plant-based beverage producers eliminated chemical trading houses from supply chains. |
| Pharmaceutical-Grade Lactic Acid Capacity Addition | Jungbunzlauer's specialized grades remain underexploited in South Africa's cosmetic formulation sector. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, Department of Health regulatory filings, and SANS standard amendments. Primary interviews engaged fermentation technology directors, beverage procurement leads at Johannesburg manufacturers, Cape Town food processing plant managers, and Durban port logistics coordinators. Secondary validation drew from National Regulator for Compulsory Specifications inspection records, corn futures pricing data, and fermentation industry technical literature. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Segmentation dimensions modeled include acidulant grade tier, end-use industry concentration, distribution channel configuration, and regional production cluster dynamics. CAGRs were derived through trend extrapolation anchored to volume commitment data and regulatory compliance timeline analysis. Forecast inputs incorporated SANS amendment trajectories, Department of Agriculture incentive program development, and enzymatic purification technology adoption curves across the projection horizon.
Forecasts assume regulatory continuity in South Africa's Foodstuffs, Cosmetics and Disinfectants Act enforcement and SANS 1027 compliance frameworks; material policy shifts would require re-modeling. Corn feedstock price volatility, phosphoric acid substitution acceleration, and FSSC 22000 auditor capacity constraints represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Fluoropolymer Additives Market
Additives
Choline Chloride Market
Additives
Global Zinc Stearate Market
Additives
Gelatin Peptones Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Anti-Settling Agents Market
Additives
Extruded Inclusions Market
Additives
Global Slip Additives Market
Additives
Flux Injection System Market
Additives
Calcium Tartrate Market
Additives
Refinery Process Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
2-Ethylhexyl Nitrate (2EHN) Market
Additives
Tamarind Gum Derivatives Market
Additives
Low Melt Inclusions Market
Additives
Crosslinking Agents Market