
 Ballast Tank Corrosion Inhibitors Market | 2026-2036
Ballast Tank Corrosion Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Ballast Tank Corrosion Inhibitors Market Analysis
The ballast tank corrosion inhibitors market is pivoting on a widening split between premium film-forming amine formulations and commodity-grade inorganic salt blends. BASF SE leverages its integrated specialty amines portfolio to sustain pricing power in high-performance marine coatings. Henkel AG & Co. KGaA anchors its position through direct technical service relationships with European shipyards. Dow Inc. competes on manufacturing scale, supplying bulk additive packages to regional blenders across Asia-Pacific.
Ballast tank corrosion inhibitors are chemical formulations designed to form protective barriers on steel surfaces exposed to alternating immersion and aeration cycles in seawater ballast environments, typically comprising film-forming amines, phosphate esters, or zinc-based compounds applied at dosage rates between 50-200 ppm to prevent pitting and general corrosion. Their primary commercial purpose is to extend structural integrity intervals for vessel ballast tanks, reducing dry-docking frequency and steel replacement costs for fleet operators. Organic inhibitor formulations now lead value generation due to superior compatibility with modern coating systems and lower environmental persistence concerns, while coating-form delivery systems represent the fastest-expanding segment as shipowners integrate corrosion control with existing maintenance schedules. Cationic inhibitors occupy the mature core of the product mix, with margin pools shifting toward gel-form applications that enable targeted placement in structurally complex tank geometries.
The International Maritime Organization's Ballast Water Management Convention shapes formulation requirements by mandating environmental compatibility assessments for chemicals discharged during ballast operations. The EPA's Vessel General Permit program in the United States imposes numeric effluent limits that filter allowable active ingredients, while REACH registration obligations in Europe restrict certain chromate and nitrite chemistries from commercial use. Classification societies including Lloyd's Register and DNV GL enforce performance verification protocols that determine product qualification for newbuild specifications. Stakeholders must monitor the trajectory of green chemistry mandates and bioaccumulation testing standards to align R&D pipelines with emerging regulatory thresholds.
Market Dynamics
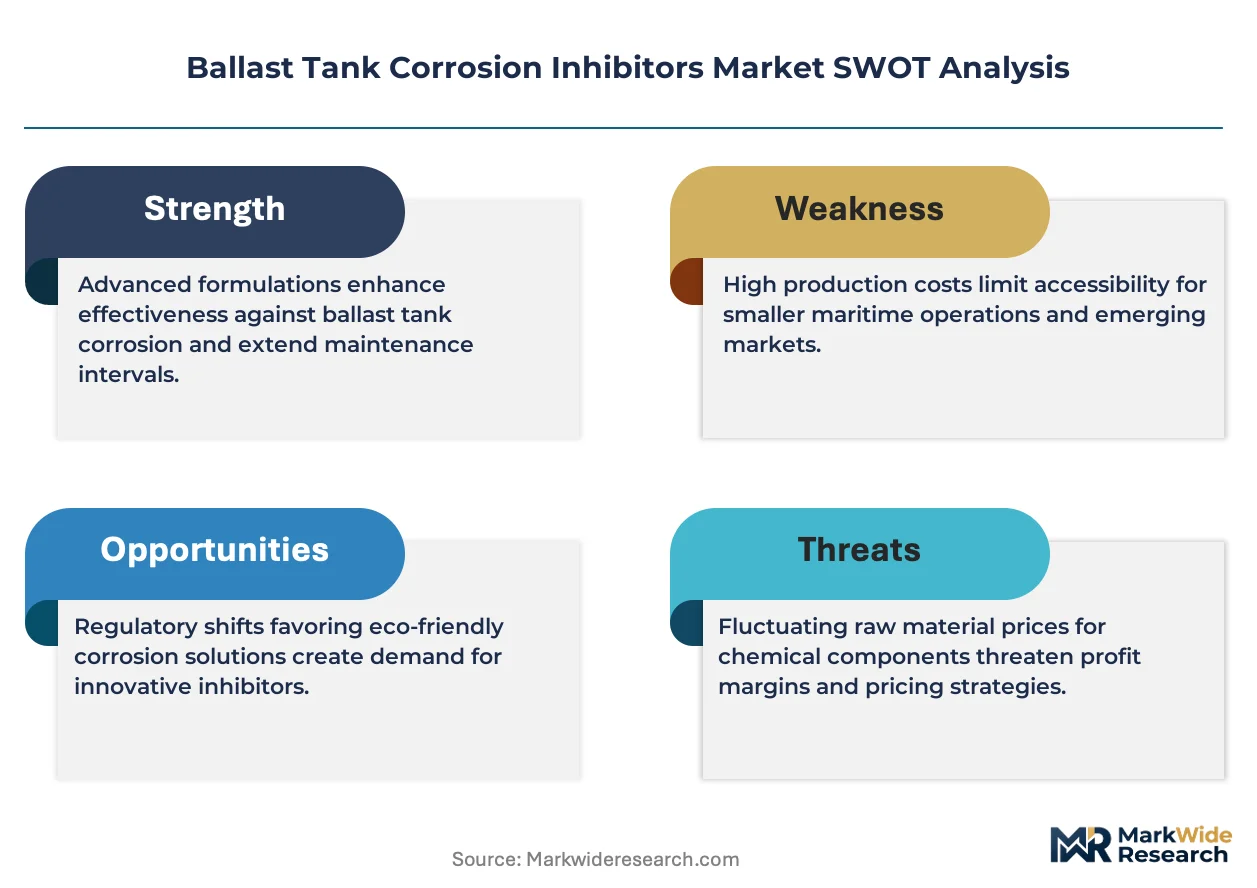
Commercial vessel operators face accelerating pressure to reconcile extended ballast tank service intervals with tightening discharge chemistry limits under IMO Convention amendments, forcing simultaneous investment in inhibitor performance and environmental compliance infrastructure.
Growth Catalysts
- IMO Ballast Water Management Convention:Updated performance verification protocols mandate enhanced protective formulations, pulling demand toward advanced film-forming amine systems that satisfy discharge criteria.
- Shipyard clustering in South Korea:Concentrated newbuild activity around Ulsan and Geoje generates localized procurement volume for specification-grade inhibitor packages.
- Extended dry-docking intervals:Fleet operators pursuing 7.5-year survey cycles require corrosion control systems capable of maintaining structural integrity across longer operational periods without recoating.
Market Restraints
- Specialty amine feedstock volatility:Film-forming inhibitor production depends on ethylene oxide and fatty acid derivatives subject to petrochemical price swings.
- European REACH registration costs:Obligations to register novel active ingredients under ECHA protocols impose six-figure entry barriers for regional blenders.
- Chromate substitution timeline:Legacy zinc-chromate pretreatments retain residual market presence in developing ship repair sectors, delaying full transition to organic inhibitor platforms.
Strategic Opportunities
- Gel-form application systems:Targeted placement technologies enable penetration into structurally complex double-bottom tank geometries inaccessible to conventional spray methods.
- Coating-form integration:Pre-blended inhibitor-coating combinations streamline shipyard application workflows and capture maintenance-schedule synergies.
- EPA Vessel General Permit alignment:Formulations meeting numeric effluent limits under US federal permits qualify for preferential specification in Jones Act fleet retrofits.
Industry Challenges
- Marine chemist certification scarcity:Qualified personnel capable of conducting ballast tank inhibitor dosage calculations and efficacy monitoring remain concentrated in established shipbuilding centers.
- Classification society approval timelines:Lloyd's Register and DNV GL performance verification protocols require 18-24 month qualification cycles for novel formulation submissions.
- Legacy tank coating incompatibility:Existing epoxy and zinc-silicate surfaces in aged vessels demand extensive surface preparation before organic inhibitor application.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballast Tank Corrosion Inhibitors Market |
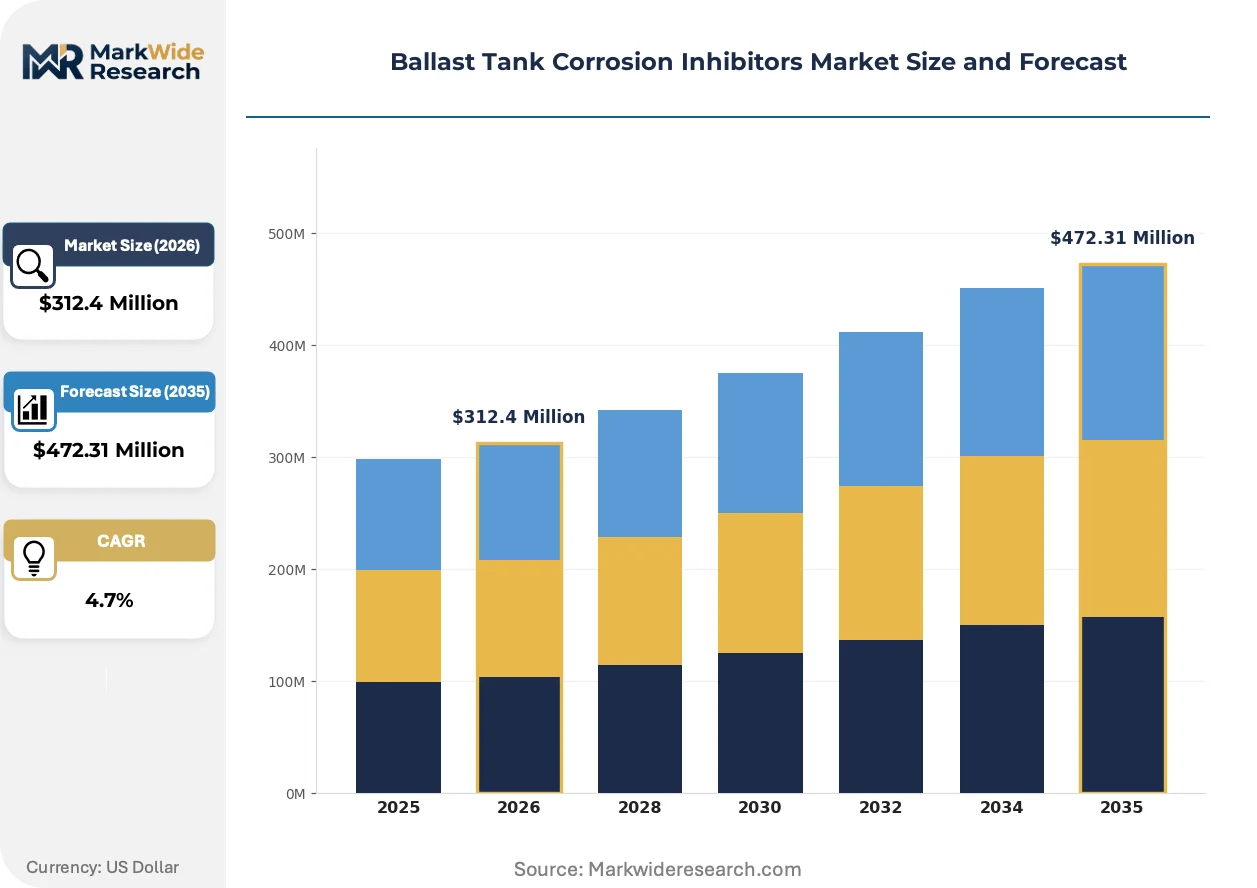
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cationic Inhibitors, Anionic Inhibitors, Organic Inhibitors, Inorganic Inhibitors Formulation: Liquid Form, Powder Form, Gel Form, Coating Form End User: Commercial Vessels, Naval Vessels, Offshore Platforms, Fishing Boats Application: Marine Industry, Chemical Processing, Oil & Gas, Water Treatment |
| Companies Covered | BASF SE, Henkel AG & Co. KGaA, Nouryon, Dow Inc., The Lubrizol Company, Cortec Corporation, Ashland, AkzoNobel, Ecolab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballast Tank Corrosion Inhibitors Market Emerging Trajectories
Formulation chemistry and application methodology are converging to address the dual mandate of structural protection and environmental discharge compliance, with delivery system innovation outpacing raw material advancement.
Smart dosing systems incorporating real-time corrosion potential monitoring are modularizing how fleet operators manage inhibitor consumption. Large container carriers and bulk operators with centralized technical management functions are piloting sensor-integrated feed systems at accelerating rates. This technology is modularizing maintenance planning by enabling condition-based rather than calendar-based inhibitor replenishment, compressing chemical waste volumes and labor allocation simultaneously.
REACH restrictions on bioaccumulative substances are forcing reformulation of phosphate ester chemistries across European supply chains. ECHA substance evaluation processes have flagged several legacy corrosion inhibitor actives for authorization review, compelling blenders to accelerate green chemistry R&D pipelines. Marine coating specifications in EU-flagged newbuilds are responding by disqualifying candidates failing OECD 301 biodegradability thresholds.
Shipowners are consolidating technical procurement decisions at fleet-management level, displacing vessel-master discretion over corrosion control purchasing. This behavioral shift concentrates annual inhibitor volume into fewer, larger contracts negotiated by technical superintendents rather than port agents. The transformation is most visible in Greek and German tanker operations, where centralized technical departments now mandate uniform inhibitor specifications across mixed-age fleets.
Ballast Tank Corrosion Inhibitors Market Segmentation
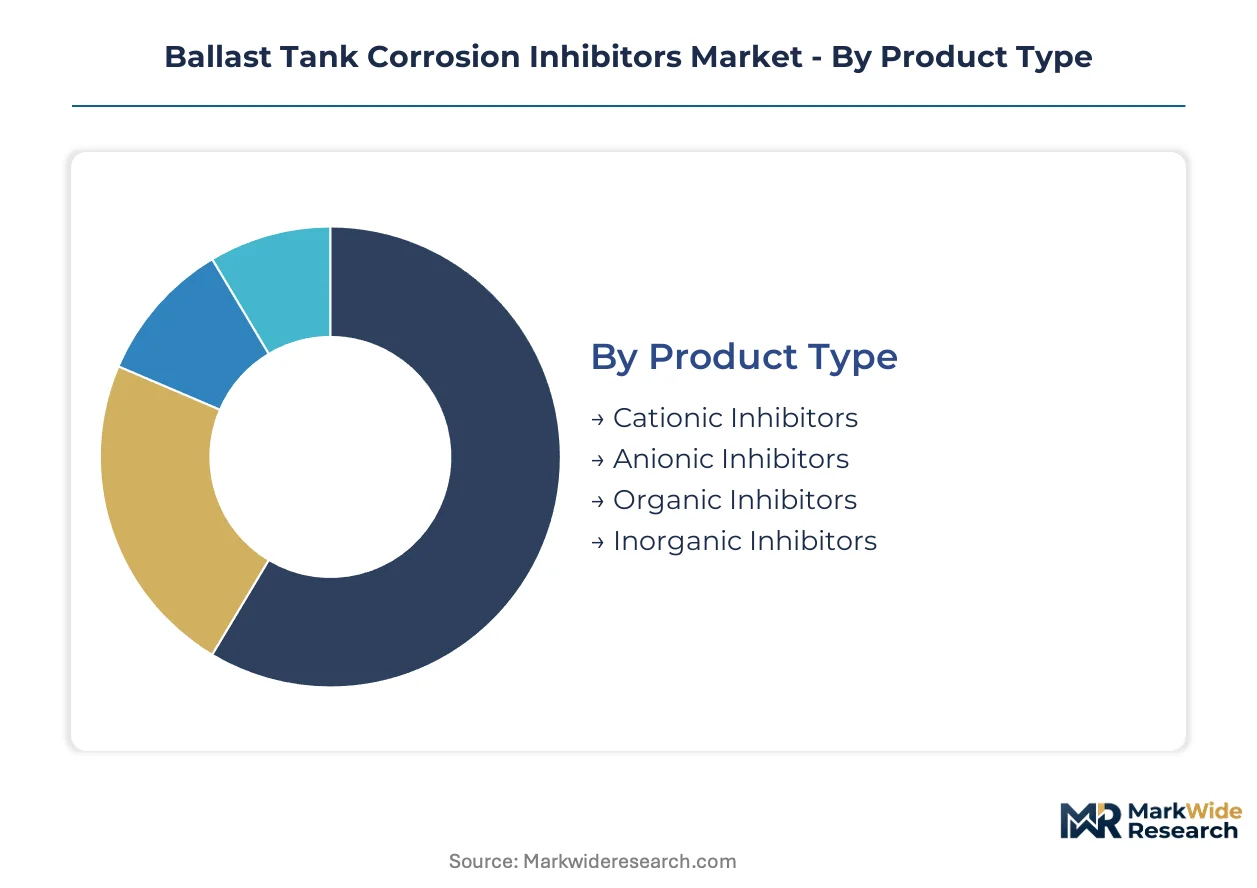
Ballast tank corrosion inhibitors serve structurally distinct vessel geometries and regulatory environments, forcing suppliers to maintain parallel formulation portfolios. Segmentation discipline determines which chemistries shipyards specify for newbuild programs versus retrofit applications.
Product Type:
Supply concentration in ethylene oxide derivatives and fatty acid feedstocks shapes competitive positioning across organic and inorganic inhibitor platforms.
- Organic Inhibitors:Film-forming amine and phosphate ester formulations dominate specification-grade marine coatings due to superior compatibility with epoxy tank linings. Demand concentrates in South Korean newbuild yards around Ulsan and Geoje, where IMO discharge compliance mandates favor biodegradable actives over legacy chemistries.
- Cationic Inhibitors:Quaternary ammonium compounds and imidazoline derivatives constitute the mature installed base for ballast water treatment integration. Fleet operators in Greek and German tanker segments specify these formulations for their established classification society approval records, though REACH bioaccumulation reviews are forcing reformulation timelines.
- Anionic Inhibitors:Sulfonate and carboxylate chemistries serve niche applications in chemical tanker operations where pH buffering requirements override film-forming priorities.
- Inorganic Inhibitors:Zinc-based and chromate-leaning salt blends retain residual presence in developing ship repair sectors, constrained by ECHA authorization restrictions and EPA Vessel General Permit numeric limits.
Organic inhibitors absorb the bulk of installed capacity; organic inhibitor platforms are expanding most quickly as ECHA substance evaluations accelerate green chemistry transitions.
Formulation:
Application methodology determines labor allocation and surface preparation requirements, with coating-form systems capturing maintenance-schedule synergies.
- Coating Form:Pre-blended inhibitor-coating combinations integrate corrosion control with existing shipyard spray workflows, reducing tank entry and ventilation downtime. Japanese and South Korean newbuild specifications increasingly mandate these systems for double-bottom tank geometries where access constraints complicate liquid dosing.
- Gel Form:Thixotropic formulations enable targeted placement in structural complexities—frame intersections, bracket toes, and longitudinal girders—unreachable by conventional application methods. Offshore platform operators in the North Sea and Gulf of Mexico are piloting these systems for extended unmanned inspection intervals.
- Liquid Form:Standard dosing systems for ballast water treatment integration remain the default for container carriers with centralized technical management functions.
- Powder Form:Concentrated additive packages serve regional blenders across Asia-Pacific manufacturing scale operations, requiring on-site dissolution infrastructure.
Liquid formulations retain the largest addressable base; gel-form applications are climbing the fastest as sensor-integrated feed systems enable condition-based replenishment.
End User:
Procurement centralization at fleet-management level is displacing vessel-master discretion, concentrating annual volume into fewer technical superintendent negotiations.
- Commercial Vessels:Container carriers, bulk operators, and tanker fleets with 7.5-year dry-docking cycles drive specification-grade demand for extended-interval corrosion control. Greek and German technical departments now mandate uniform inhibitor specifications across mixed-age fleets, consolidating supplier relationships.
- Naval Vessels:Military procurement protocols impose distinct qualification pathways through national defense material agencies, with longer approval timelines but higher contract values per vessel.
- Offshore Platforms:Fixed and floating production facilities in the North Sea and Gulf of Mexico require inhibitor systems compatible with unmanned inspection regimes and subsea structural monitoring.
- Fishing Boats:Smaller vessel operators in coastal fleets prioritize cost-minimized commodity formulations, with limited specification influence on supplier R&D priorities.
Commercial vessels command the dominant procurement volume; offshore platforms are gaining share fastest as production facility life extension programs accelerate.
Application:
Regulatory jurisdiction determines permissible active ingredients, fragmenting formulation requirements across marine and industrial end-uses.
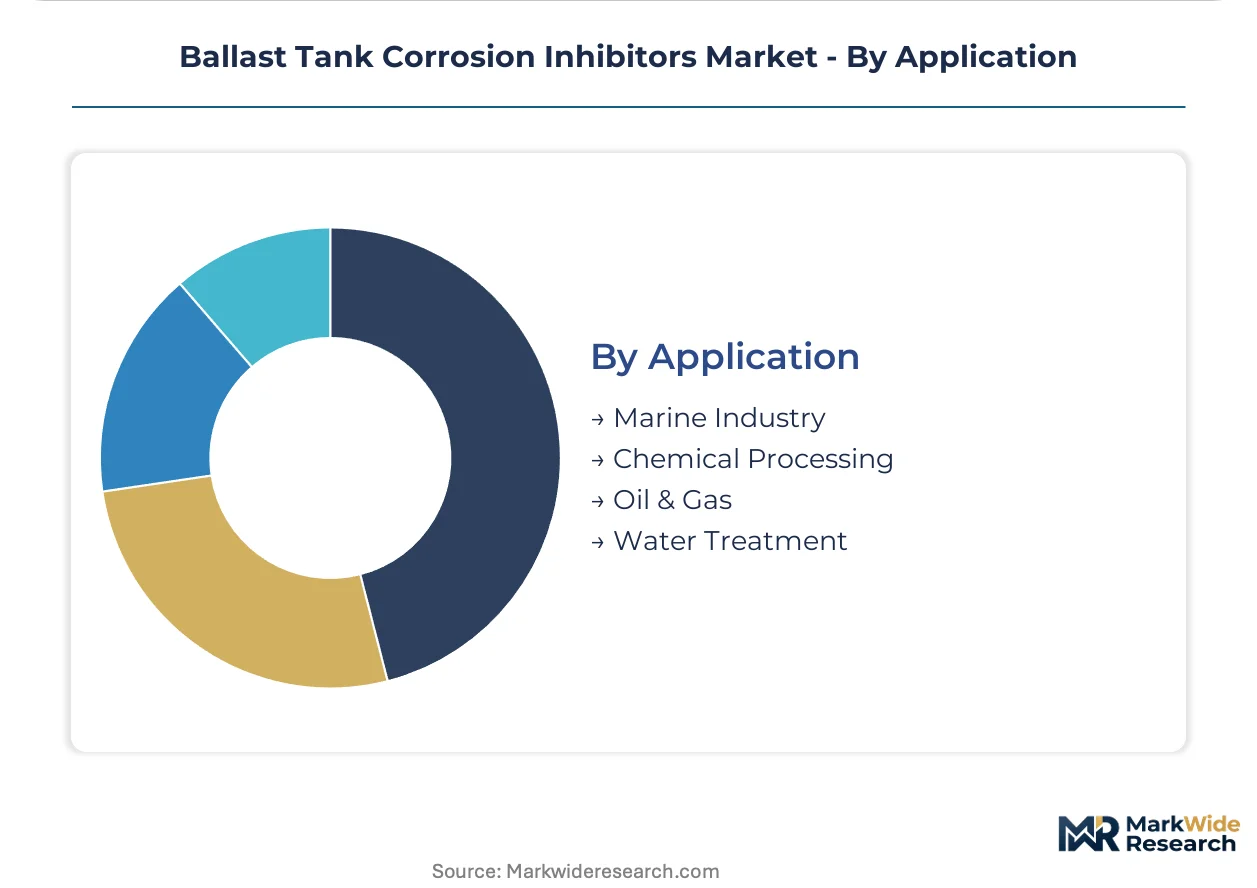
- Marine Industry:IMO Ballast Water Management Convention and EPA Vessel General Permit frameworks govern discharge chemistry, with Lloyd's Register and DNV GL performance verification protocols determining product qualification. This application absorbs the majority of film-forming amine R&D investment.
- Oil & Gas:Pipeline and storage tank corrosion control in upstream and midstream operations utilizes similar chemistries but faces distinct regulatory frameworks—OSHA process safety management in the US, COMAH in the UK—without marine discharge constraints.
- Chemical Processing:Acid pickling and process water systems in European and North American manufacturing facilities specify inhibitor grades meeting REACH and TSCA registration requirements.
- Water Treatment:Municipal and industrial cooling water systems represent a price-sensitive adjacent market with limited overlap in supplier technical service capabilities.
Marine applications absorb the bulk of specification-grade capacity; oil and gas applications are expanding most quickly as midstream infrastructure corrosion management budgets increase.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan and Geoje anchor shipbuilding demand for specification-grade inhibitor systems, concentrating procurement volume for advanced film-forming amine formulations. Fleet operators across four additional maritime economies drive regional diversification in corrosion control adoption.
South Korea
Shipyard clusters around Ulsan and Geoje generate concentrated demand for IMO-compliant inhibitor packages in newbuild specifications. Korean Register classification protocols enforce performance verification standards that filter supplier qualification. Hyundai Heavy Industries and Samsung Heavy Industries technical departments mandate uniform coating-form systems across mixed-age tanker fleets.
China
State-owned shipbuilders in Shanghai and Dalian expand adoption of gel-form applications for double-bottom tank geometries. MEE discharge standards align with IMO Convention amendments, restricting chromate-based formulations in coastal waters. Jiangnan Shipyard and Waigaoqiao Shipbuilding procurement offices consolidate annual inhibitor volume into fewer technical superintendent contracts.
Germany
Greek-owned tanker fleets under German technical management specify REACH-registered organic inhibitors for extended dry-docking intervals. ECHA substance evaluation processes accelerate green chemistry transitions across Hamburg and Bremen supply chains. Lloyd's Register German offices enforce 18-month qualification cycles for novel formulation submissions.
United States
Jones Act fleet operators in the Gulf Coast and Pacific Northwest pursue EPA Vessel General Permit alignment for preferential retrofit specifications. USCG ballast water discharge standards filter allowable active ingredients in Great Lakes and coastal operations. Crowley Maritime and Matson Navigation technical departments pilot sensor-integrated feed systems for condition-based replenishment.
Japan
Imabari Shipbuilding and Japan Marine United yards in Imabari and Yokohama integrate coating-form inhibitors with existing spray workflows. METI industrial standards govern environmental compatibility assessments for chemicals discharged during ballast operations. Classification society Nippon Kaiji Kyokai performance protocols determine product qualification for domestic newbuild programs.
Ballast Tank Corrosion Inhibitors Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and technical service depth. The vendor base stratifies between integrated petrochemical majors supplying ethylene oxide derivatives and regional blenders purchasing bulk additive packages. Three archetypes dominate: specialty amine producers with captive feedstock, coating-integrated formulators with direct shipyard relationships, and manufacturing-scale suppliers competing on volume pricing. Competitive moves center on coating-form integration partnerships and REACH registration consolidation to raise entry barriers.
Within the specialty chemical tier, BASF SE and Henkel AG & Co. KGaA exemplify divergent positioning strategies. BASF SE anchors the integrated feedstock archetype through captive ethylene oxide and fatty acid derivative production. Henkel AG & Co. KGaA occupies the technical service vector with direct specification relationships at European shipyards. Dow Inc. represents the manufacturing-scale end, supplying bulk additive packages to regional blenders across Asia-Pacific.
| Leading Market Players |
|---|
| BASF SE |
| Henkel AG & Co. KGaA |
| Nouryon |
| Dow Inc. |
| The Lubrizol Company |
| Cortec Corporation |
| Ashland |
| AkzoNobel |
| Ecolab |
| Others |
Supply Flow & Price Mechanics
A certification-grade bifurcation between IMO-verified film-forming amine systems and unregistered commodity salt blends manifests in pricing power concentrated among REACH-registered suppliers and supply chain configurations that privilege captive ethylene oxide feedstock over spot-market sourcing. Premium formulations command sustained margin premiums through Lloyd's Register qualification records, while regional blenders in Asia-Pacific absorb feedstock volatility through powder-form additive packages.
Pricing Analysis
Value-based pricing anchored to dry-docking interval extension shapes the dominant structure, with fleet operators calculating inhibitor expenditure against steel replacement and recoat avoidance. Price differentiation rests on classification society approval tier and REACH registration status, with ECHA-registered organic formulations sustaining premiums over chromate-leaning alternatives. Pricing pressure stems from ethylene oxide derivative cost volatility transmitted through specialty amine supply chains. Greek and German tanker technical departments exhibit lowest price sensitivity due to centralized specification mandates, while coastal fishing fleet operators prioritize cost-minimized commodity grades.
Supply Chain Analysis
South Korean local-content rules for naval and commercial newbuild programs are reshaping sourcing patterns, mandating domestic blending capacity for specification-grade inhibitor packages. Supply concentrates in Germany, South Korea, and the United States for film-forming amine production, with ethylene oxide and fatty acid derivatives as critical feedstock dependencies. Single-source vulnerability runs through BASF SE's integrated ethylene oxide derivatives position. Distribution feeds from integrated petrochemical majors through regional blenders to shipyard procurement offices and fleet technical departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over ethylene oxide and fatty acid derivative supply determines margin sustainability against feedstock volatility.
For Market Incumbents: Anchor qualification records through accelerated Lloyd's Register and DNV GL submission pipelines for gel-form applications, defending against sensor-integrated feed system entrants eroding liquid-form volume. Prioritize backward integration into ethylene oxide derivatives to neutralize petrochemical price swing exposure. For New Entrants and Emerging Players: Begin with coating-form integration partnerships at second-tier shipyards in China's Dalian and Shanghai clusters, where procurement consolidation creates specification entry points without incumbent technical service depth. Target Jones Act fleet retrofits where EPA Vessel General Permit alignment qualifies novel formulations for preferential specification. For Investors and Strategic Acquirers: Re-rating potential sits with REACH-registered regional blenders given ECHA authorization timelines compressing competitive entry, as green chemistry mandates accelerate organic inhibitor transitions. Watch classification society approval velocity as the inflection signal—18-month qualification cycles versus 24-month lags separate compounders from commodity suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Feedstock | BASF SE's captive derivative production insulates margin structure from petrochemical volatility. |
| Coating-Form Application Partnership | Henkel AG's direct shipyard relationships streamline specification-grade inhibitor integration. |
| REACH Registration Consolidation | ECHA authorization barriers raise competitive moats against unregistered commodity blenders. |
| Gel-Form Technology Licensing | Targeted placement systems penetrate double-bottom tank geometries inaccessible to spray methods. |
| Sensor-Integrated Feed System Pilot | Crowley Maritime's condition-based replenishment trials compress chemical waste and labor allocation. |
Methodological Framework
IMO regulatory filings, ECHA substance evaluation databases, and Lloyd's Register qualification records formed the secondary backbone, cross-referenced with primary interviews involving marine chemists, shipyard procurement managers, fleet technical superintendents, and specialty chemical R&D directors. Customs data on ethylene oxide derivative trade flows and shipyard production schedules provided demand-side triangulation against bottom-up inhibitor consumption estimates. Primary fieldwork concentrated in Ulsan, Geoje, Hamburg, and Houston maritime clusters.
Historical trendline analysis of specification-grade inhibitor adoption across commercial vessel newbuild and retrofit cycles anchored the projection framework, with segmentation across organic, cationic, and inorganic inhibitor platforms further disaggregated by coating-form, gel-form, liquid-form, and powder-form delivery systems. CAGRs were derived from regression analysis of fleet dry-docking interval extension patterns and green chemistry regulatory phase-in timelines, incorporating shipbuilding orderbook data and REACH authorization review schedules as industry-specific inputs.
Underlying measurement precision varies by segment; IMO-verified coating-form systems carry tighter precision than commodity-grade inorganic salt blends due to concentrated shipyard procurement visibility. Forecasts reflect assumptions on regulatory enforcement intensity and classification society approval velocity, with ECHA substance evaluation acceleration or delay representing primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cold Flow Improvers Market
Additives
Apocarotenal Market
Additives
Lauroyl Methyl Glucamide Market
Additives
Glacial Acetic Acid Market
Additives
Asia-Pacific Feed Acidifiers Market
Additives
Global Silica-Based Matting Agents Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
China Sodium Reduction Ingredient Market
Additives
Green Chelates/Natural Chelating Agents Market
Additives
Metal Modifiers Market
Additives
Europe Citric Acid Market
Additives
North America Phosphate Esters Market
Additives
Extruded Inclusions Market
Additives
Rosin Ester Market
Additives
Anti-Wear Additives Market
Additives
Phenolic Antioxidant Market